
 Loan Servicing Software Market | 2026-2036
Loan Servicing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Loan Servicing Software Market Analysis
India's fintech infrastructure build-out is reshaping how loan servicing platforms penetrate emerging credit markets. Finastra Loan IQ leverages its London-based development centers to sustain multi-currency syndicated loan capabilities across Asian banking networks. Fiserv LoanServ anchors North American market presence through deep core banking integration, while LoanPro specializes in subprime and specialty finance workflows with configurable API architectures.
Loan servicing software encompasses platforms that automate borrower account administration, payment collection, escrow management, and regulatory reporting across the full credit lifecycle. These systems typically process amortization schedules, handle investor remittances, and maintain audit trails compliant with consumer protection mandates. Cloud-based deployment leads functionality expansion as mortgage lenders and credit unions abandon on-premise data centers for elastic infrastructure. API integration levels now determine competitive viability, with banks prioritizing open connectivity to CRM systems and third-party origination tools over monolithic legacy replacements.
The Consumer Financial Protection Bureau enforces servicing rules under RESPA and TILA, compelling software vendors to embed complaint tracking and loss mitigation workflows. The Federal Housing Administration mandates specific reporting formats for government-insured loans, creating compliance moats around established platforms. Stakeholders must monitor how state-level privacy legislation fragments data residency requirements across multi-jurisdictional servicing operations.
Market Dynamics
Cloud-native API architectures are compressing replacement cycles for legacy mainframe installations across mortgage servicing operations, forcing vendors to restructure delivery models around elastic infrastructure rather than perpetual license sales.
Growth Catalysts
- CFPB Enforcement Intensity:Escalating examination frequency under RESPA and TILA mandates drives credit unions and non-bank servicers toward platforms with embedded complaint tracking and loss mitigation workflows.
- Syndicated Loan Digitization:Multi-currency syndication complexity across Asian banking networks accelerates demand for platforms supporting real-time position tracking and waterfall calculations.
- Escrow Automation:Property tax and insurance payment volatility pushes mortgage lenders toward systems with predictive escrow analytics and automated shortage/surplus adjustments.
Market Restraints
- Data Migration Friction:Decades of borrower payment history trapped in COBOL-based systems create technical debt that extends implementation timelines by 18-36 months for large servicers.
- Specialized Talent Scarcity:Shortage of engineers proficient in both legacy mainframe protocols and modern cloud architectures drives implementation costs upward across North American credit unions.
- Regulatory Fragmentation:State-level privacy legislation in California, Virginia, and Colorado fragments data residency requirements, forcing multi-jurisdictional operators to maintain redundant infrastructure.
Strategic Opportunities
- Subprime Workflow Expansion:Configurable API architectures enable penetration of specialty finance segments including buy-here-pay-here auto and point-of-sale lending with minimal customization.
- Investor Reporting Convergence:Ginnie Mae and Fannie Mae data format harmonization creates openings for platforms that unify government-sponsored enterprise and FHA reporting streams.
- Embedded Finance Integration:Open banking APIs enable direct servicing integration within e-commerce checkout flows and property management software ecosystems.
Industry Challenges
- Mainframe Knowledge Attrition:Retiring COBOL and Assembler specialists threaten operational continuity for servicers maintaining hybrid legacy-cloud environments during extended migration periods.
- Cybersecurity Certification Burden:SOC 2 Type II and ISO 27001 audit cycles consume 8-14 months, delaying go-live dates for vendors serving federally insured depository institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loan Servicing Software Market |
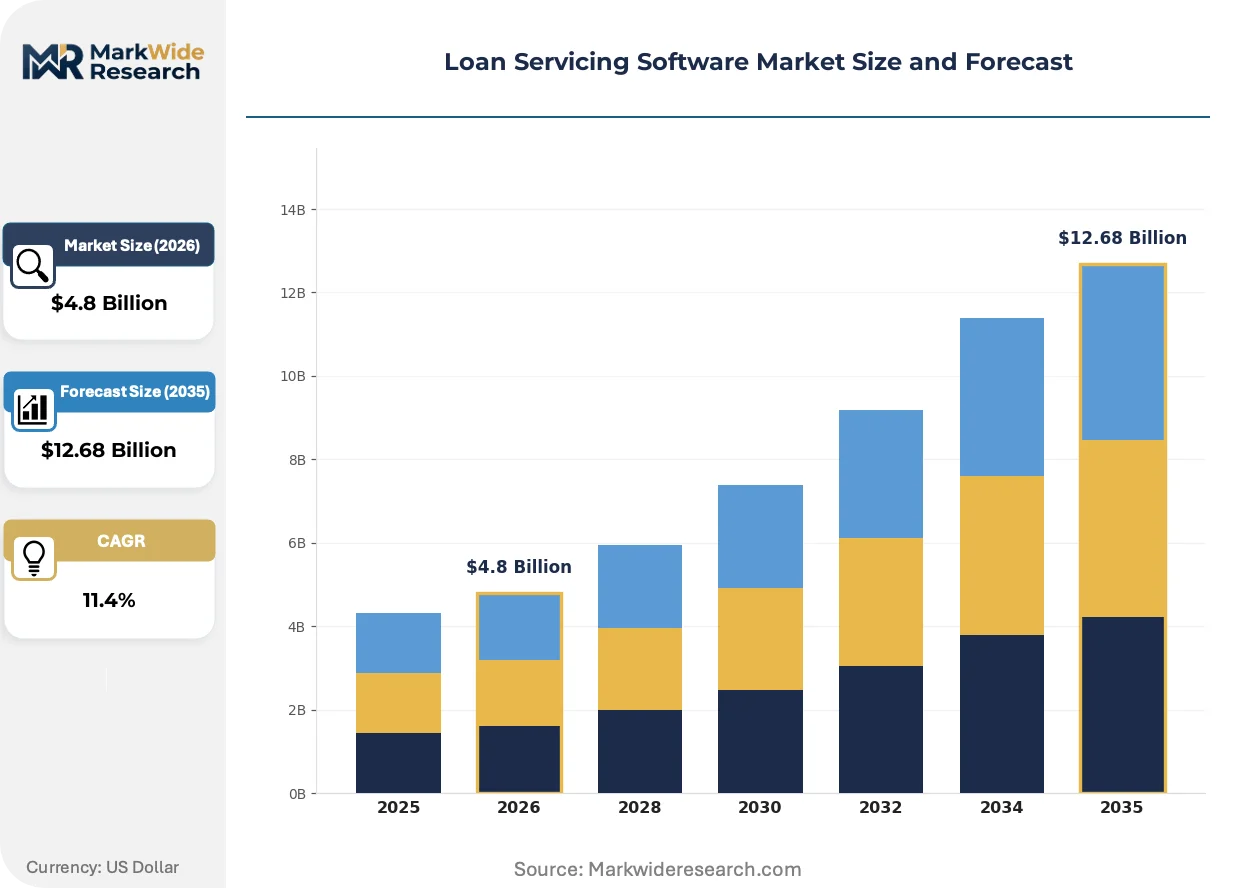
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Banks, Credit Unions, Mortgage Lenders, Investment Firms Functionality: Payment Processing, Loan Management, Customer Support, Compliance Integration Level: API, Third-Party Software, CRM Systems, Legacy Platforms |
| Companies Covered | defi SOLUTIONS, HES LoanBox, LendFoundry, Bryt Software, Finastra Loan IQ, LoanPro, Fiserv LoanServ, LendingWise, Nortridge Loan System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loan Servicing Software Market Emerging Trajectories
Artificial intelligence and machine learning capabilities are penetrating core servicing workflows, compressing decision timelines for loss mitigation and borrower communication while reshaping vendor competitive positioning around predictive analytics rather than transactional processing.
Machine learning models trained on historical payment patterns and macroeconomic indicators are hybridizing traditional rules-based escrow analysis with dynamic forecasting. Mid-tier mortgage servicers are deploying these tools to reduce manual cushion calculations by sixty percent. The technology is hybridizing operational cost structures while elevating borrower satisfaction scores through proactive shortage notifications.
The Consumer Financial Protection Bureau's 2023 servicing rule amendments mandate enhanced borrower communication timelines and dual-tracking restrictions during foreclosure proceedings. Compliance departments at non-bank servicers are reconfiguring workflow engines to trigger mandatory outreach at 36-day and 45-day delinquency thresholds. Subprime specialists face the steepest adaptation costs as their borrower populations exhibit higher volatility in contact information and preferred communication channels.
Consolidation among correspondent lenders and subservicers is compressing vendor sales cycles toward centralized procurement decisions. Regional banks that previously maintained autonomous servicing technology stacks are ceding operational control to national subservicers with scale advantages in compliance and technology investment. The shift is most visible in the Southeast United States, where mid-sized depository institutions have exited direct servicing at accelerating rates since 2022.
Loan Servicing Software Market Segmentation
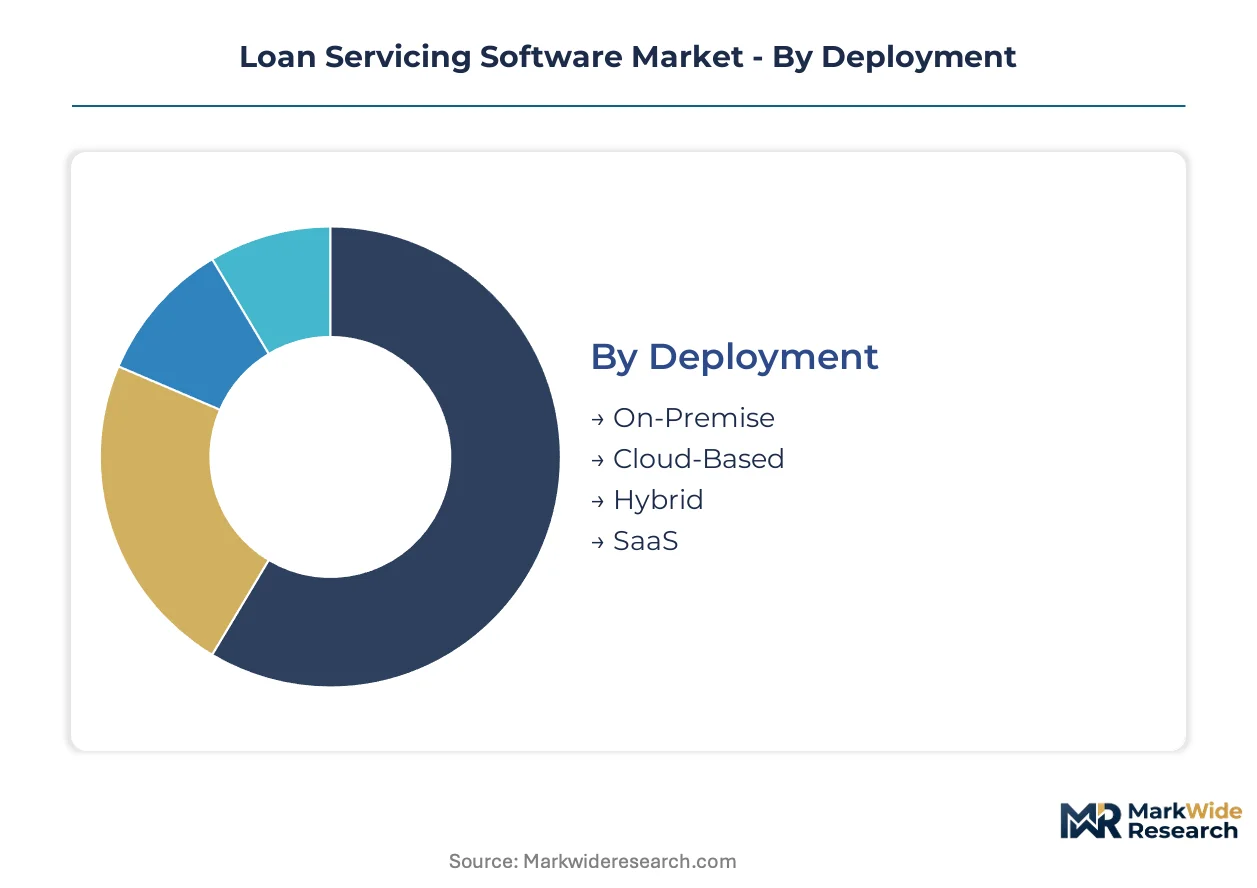
Loan servicing software segmentation reveals how deployment architectures, user sophistication, and integration requirements fragment procurement patterns across financial institutions. Understanding these divides exposes where cloud-native platforms displace legacy installations and which functional modules command premium pricing.
Deployment:
The use-case spectrum spans from fortress institutions requiring air-gapped control to agile lenders prioritizing elastic scalability over capital expenditure containment.
- Cloud-Based:Multi-tenant architectures with automatic scaling handle seasonal payment volume spikes without infrastructure overprovisioning. Regional banks in the United States are migrating here fastest, driven by CFPB audit trail requirements that favor centralized data lakes over distributed on-premise storage.
- SaaS:Subscription models eliminate perpetual license capital hits and shift vendor accountability for uptime and security patching. Credit unions with sub-$500 million servicing portfolios favor this route to access enterprise-grade functionality without dedicated IT departments.
- On-Premise:Air-gapped installations persist among investment firms handling classified government-backed securities where data sovereignty overrides cost efficiency.
- Hybrid:Split configurations keep sensitive borrower PII on local servers while pushing payment processing to public cloud nodes.
The dominant share belongs to Cloud-Based deployments, while SaaS is closing the gap fastest among mid-tier credit unions shedding technical debt.
End User:
Procurement authority concentrates differently across institution types, with regulatory complexity and portfolio scale dictating platform sophistication requirements.
- Banks:Full-service institutions demand modular platforms spanning commercial real estate, consumer installment, and mortgage verticals within unified general ledgers.
- Mortgage Lenders:Specialized servicers prioritize escrow analytics and investor remittance engines over generalized loan administration, with FHA-compliant workflows commanding non-negotiable priority.
- Credit Unions:Member-owned cooperatives seek member-facing portals with seamless core banking integration, often accepting narrower feature depth for tighter cost control.
- Investment Firms:Asset managers and private equity servicers require waterfall calculation engines for complex capital structures and real-time position reporting across syndicated facilities.
Mortgage Lenders retain the dominant deployment volume, while Investment Firms are expanding most quickly as private credit markets absorb bank-disintermediated lending.
Functionality:
Module selection reflects where institutions automate versus maintain human judgment, with compliance and payment processing commanding non-discretionary budgets.
- Payment Processing:ACH, wire, and check handling engines with automated exception routing and NSF retry logic form the operational backbone. United States servicers prioritize here due to RESPA-mandated same-day crediting requirements.
- Compliance:Embedded rule engines tracking CFPB complaint timelines, FHA reporting formats, and state-level foreclosure mediation requirements. Non-bank servicers face steepest adaptation costs as regulatory scrutiny intensifies.
- Loan Management:Amortization engines, escrow administration, and investor remittance calculations supporting multi-servicer pooling structures.
- Customer Support:Borrower portals, automated payment reminders, and loss mitigation intake workflows with omnichannel communication tracking.
Payment Processing holds the dominant functional share, while Compliance modules are climbing the fastest as regulatory enforcement tightens.
Integration Level:
Connectivity architecture determines whether platforms function as closed ecosystems or orchestration hubs, with API maturity now a primary competitive filter.
- API:REST and GraphQL interfaces enabling real-time data exchange with origination systems, credit bureaus, and property valuation services. Modern platforms architect around these as primary design principles rather than retrofitted afterthoughts.
- CRM Systems:Salesforce and Microsoft Dynamics connectors that synchronize borrower contact histories, marketing touchpoints, and servicing notes across departmental silos.
- Third-Party Software:Pre-built adapters for document management, electronic signature, and payment gateway providers reducing implementation friction.
- Legacy Platforms:COBOL screen-scraping and message queue bridges maintaining operational continuity during multi-year mainframe migration programs.
API integration commands the dominant procurement priority, while Legacy Platform bridges maintain persistent demand despite accelerating cloud displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Consumer Financial Protection Bureau anchors the United States as the dominant geography, where regulatory enforcement intensity drives platform procurement. Mortgage servicers across credit unions and non-bank operators face escalating compliance mandates that favor centralized data architectures over fragmented legacy systems.
United States
Mortgage lenders and credit unions dominate procurement volumes as portfolio complexity rises. The CFPB enforces RESPA and TILA servicing rules that embed complaint tracking and loss mitigation workflows into platform requirements. Dallas-Fort Worth and Charlotte banking clusters concentrate subservicer consolidation activity as regional banks exit direct servicing.
United Kingdom
Open banking APIs and embedded finance integration reshape how servicing platforms connect to origination ecosystems. The Financial Conduct Authority mandates consumer duty obligations that elevate borrower communication tracking requirements. London fintech development centers drive multi-currency syndicated loan capability expansion across Asian banking networks.
Germany
Commercial real estate and corporate lending automation accelerate as Sparkassen and cooperative banks modernize core systems. BaFin supervisory requirements enforce robust audit trails for loan administration and investor remittance processes. Frankfurt's banking infrastructure cluster supports waterfall calculation engines for complex capital structures.
India
Fintech infrastructure build-out penetrates emerging credit markets with cloud-native deployment models. The Reserve Bank of India regulates non-banking financial companies with escalating data localization and borrower protection mandates. Mumbai and Bangalore technology corridors anchor API-first servicing platform development for microfinance and digital lending workflows.
Japan
Regional bank consolidation creates centralized procurement decisions for servicing technology stacks. The Financial Services Agency pushes digitization timelines for legacy mainframe migration across shrinking institution counts. Tokyo's financial district maintains demand for multi-currency position tracking across syndicated facilities serving Asian corporate borrowers.
Loan Servicing Software Market Vendor Landscape
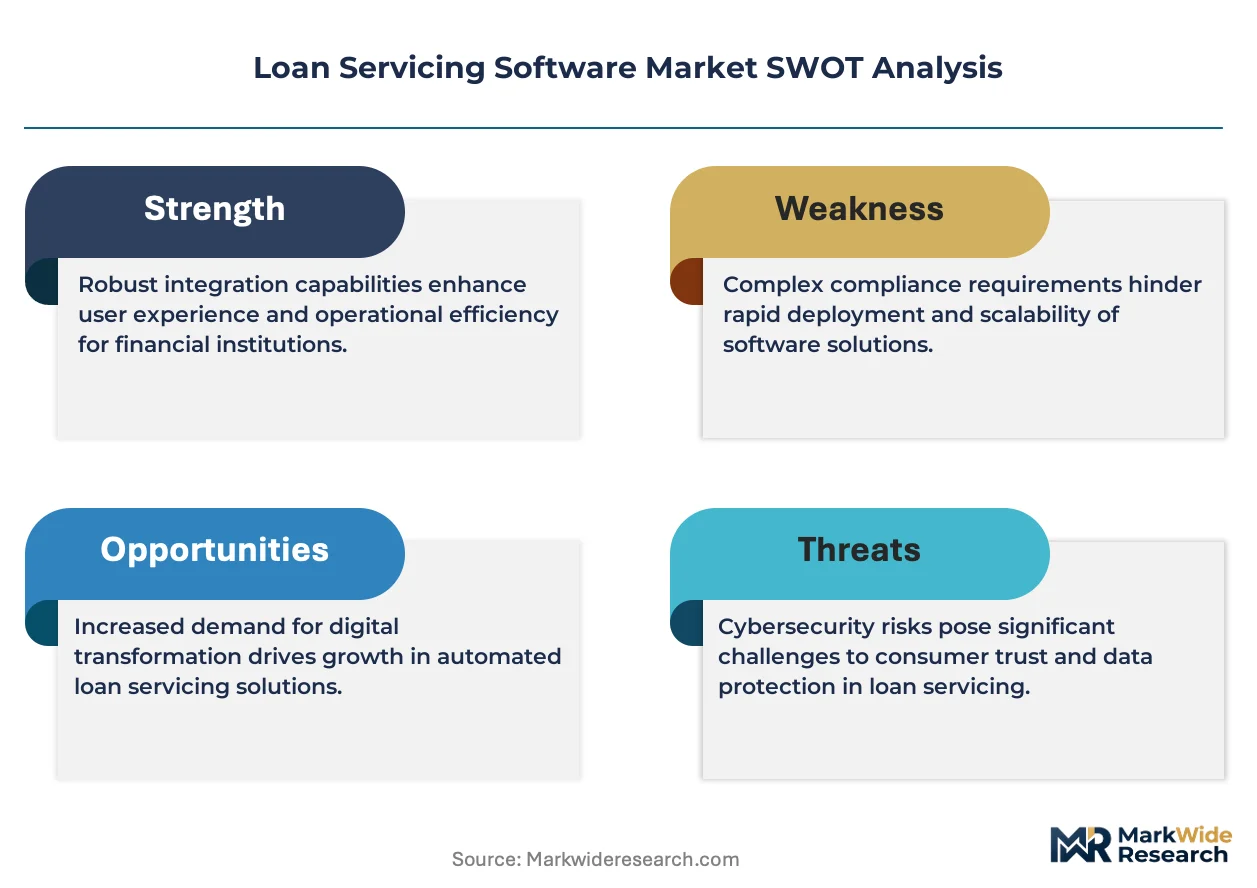
Capability concentration sits with specialized workflow architects; scale advantage sits with core-integrated platform incumbents. The vendor base stratifies across three tiers: cloud-native specialists, legacy-integrated banking technology providers, and regional workflow configurators. Dominant competitive moves include API-first architecture investments and subservicer market consolidation partnerships that compress sales cycles toward centralized procurement.
Within the specialized workflow tier, LoanPro and Bryt Software exemplify configurable API architectures targeting subprime and specialty finance segments. Finastra Loan IQ occupies a position serving multi-currency syndicated loan complexity across Asian banking networks. Fiserv LoanServ anchors the core-integrated tier with deep banking infrastructure presence in North American credit union and mortgage lender deployments.
| Leading Market Players |
|---|
| defi SOLUTIONS |
| HES LoanBox |
| LendFoundry |
| Bryt Software |
| Finastra Loan IQ |
| LoanPro |
| Fiserv LoanServ |
| LendingWise |
| Nortridge Loan System |
| Others |
Supply Flow & Price Mechanics
Regulatory fragmentation across state-level privacy mandates in California, Virginia, and Colorado functions as a tariff-like cost layer that widens pricing spreads between compliant cloud-native platforms and legacy on-premise installations while forcing multi-jurisdictional servicers toward redundant infrastructure architectures.
Pricing Analysis
North American deployments command substantial premiums over Asian and European equivalents due to embedded CFPB and FHA compliance modules. Three-tier pricing structure across enterprise, mid-market, and credit union tiers reflects certification depth and core banking integration maturity. Cost compression in the mid-market tier is intensifying because SaaS vendors are disintermediating perpetual license incumbents. Credit unions with sub-$500 million portfolios exhibit highest price sensitivity; investment firms handling classified securities show lowest.
Supply Chain Analysis
Tariff exposure between United States and India on software development services dominates cost structure volatility for vendors maintaining hybrid delivery models. Engineering talent concentrates in India, the United Kingdom, and the United States, with London and Bangalore anchoring multi-currency syndication development. Cloud infrastructure draws from hyperscaler data centers in Virginia, Frankfurt, and Mumbai. Single-source vulnerability rests on aging COBOL specialist pools retiring without replacement pipeline. Distribution runs through direct enterprise sales teams and banking technology consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first platform economics are displacing monolithic architecture value capture, with interoperability consolidation around open banking standards in the United Kingdom and embedded finance ecosystems in North America redistributing margins toward orchestration-layer vendors.
For Market Incumbents: Pre-empt cloud-native displacement by acquiring specialist workflow configurators in subprime auto and point-of-sale lending segments before API-first entrants establish anchor tenancy. Fortify core banking integration moats through deeper Fiserv and Jack Henry partnerships that raise switching costs for credit union clients. The priority lever sits in escrow analytics patent portfolios that mid-tier servicers cannot replicate internally. For New Entrants and Emerging Players: India's non-banking financial company sector offers the most penetrable white-space target, where Reserve Bank of India data localization mandates have slowed incumbent cloud migrations. Specialty finance workflows in buy-here-pay-here auto present second entry vector with lower compliance friction than mortgage servicing. A direct API marketplace go-to-market angle bypasses lengthy procurement cycles that entrench established vendors at large banks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compliance-automation specialists over transactional processing utilities. Long-term viability hinges on regulatory workflow depth rather than payment volume scale. Target acquisition archetypes include vendors with embedded CFPB loss mitigation engines and FHA reporting certification. The signal to watch is subservicer market concentration rates in the Southeast United States as regional banks accelerate servicing exits.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open banking API consolidation with Salesforce and Microsoft Dynamics ecosystems captures workflow orchestration premiums. |
| Acquisition of Specialist Firm | Subprime workflow configurators with point-of-sale lending modules fill portfolio gaps in high-yield segments. |
| Geographic Expansion | India's NBFC sector offers first-mover advantage before domestic vendors achieve cloud-native parity. |
| Strategic Partnership | Ginnie Mae and Fannie Mae data format harmonization partnerships unify government-sponsored enterprise reporting streams. |
| Product Launch | Predictive escrow analytics modules reduce manual cushion calculations and elevate borrower satisfaction scores. |
Methodological Framework
The analysis maps cloud-native deployment architectures, legacy migration pathways, and API integration maturity tiers, each validated through mortgage servicing executives, credit union technology officers, regulatory compliance leads, and core banking integration specialists. Primary fieldwork combined structured interviews with secondary triangulation against SEC 10-K filings, CFPB examination reports, FFIEC call report data, and banking technology consortium procurement disclosures. Bottom-up vendor revenue estimates and top-down market sizing converged through iterative reconciliation.
Assumptions held regulatory enforcement intensity and cloud adoption curves fixed at observed trajectories while varying subservicer consolidation rates and mainframe specialist attrition scenarios across the projection horizon. Segmentation modeling spanned deployment model, institution type, functional module priority, and integration complexity tier. CAGRs derived from logistic adoption curves fitted to historical replacement cycle data and elasticity-adjusted pricing trajectories. Escrow automation penetration and syndicated loan digitization velocity served as industry-specific demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive API-first pricing moves by cloud-native entrants or accelerated CFPB rulemaking would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Battery Leasing Service Market