
 Australia Used Car Financing Market | 2026-2036
Australia Used Car Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Used Car Financing Market Outlook
The Australian Securities and Investments Commission's responsible lending obligations is shifting how lenders assess borrower capacity, pushing providers toward more granular credit scoring and income verification tools. Pepper Money Limited leverages its specialist lending platform to serve non-prime segments that traditional banks often bypass. Toyota Finance Australia Limited anchors its position through captive financing tied to certified pre-owned vehicle programs. National Australia Bank Limited competes by integrating used car loans into broader retail banking relationships.
Australia used car financing encompasses secured and unsecured credit products structured around depreciated automotive assets, typically requiring vehicle identification verification, odometer certification, and residual value assessment to determine loan-to-value ratios and pricing tiers. These instruments channel capital from institutional funders and deposit-taking institutions to individual and commercial buyers, enabling vehicle acquisition without full upfront payment while generating interest income and fee revenue for originators. Dealer financing dominates transaction volume by embedding credit at the point of sale, though personal loans are gaining ground as direct digital platforms reduce friction for repeat buyers seeking competitive rates outside dealership networks. Fleet operators represent a concentrated margin pool due to larger average ticket sizes and structured repayment schedules, even as first-time buyers drive absolute application growth.
The Australian Prudential Regulation Authority supervises authorized deposit-taking institutions in this market, while ASIC enforces disclosure standards and hardship provisions under the National Consumer Credit Protection Act, collectively elevating compliance costs but also filtering out predatory operators. The Treasury's ongoing review of open banking frameworks and comprehensive credit reporting will reshape how lenders access borrower data and price risk. Stakeholders must monitor regulatory technology investments and alternative data integration capabilities as competitive differentiators in an increasingly transparent credit environment.
Market Dynamics
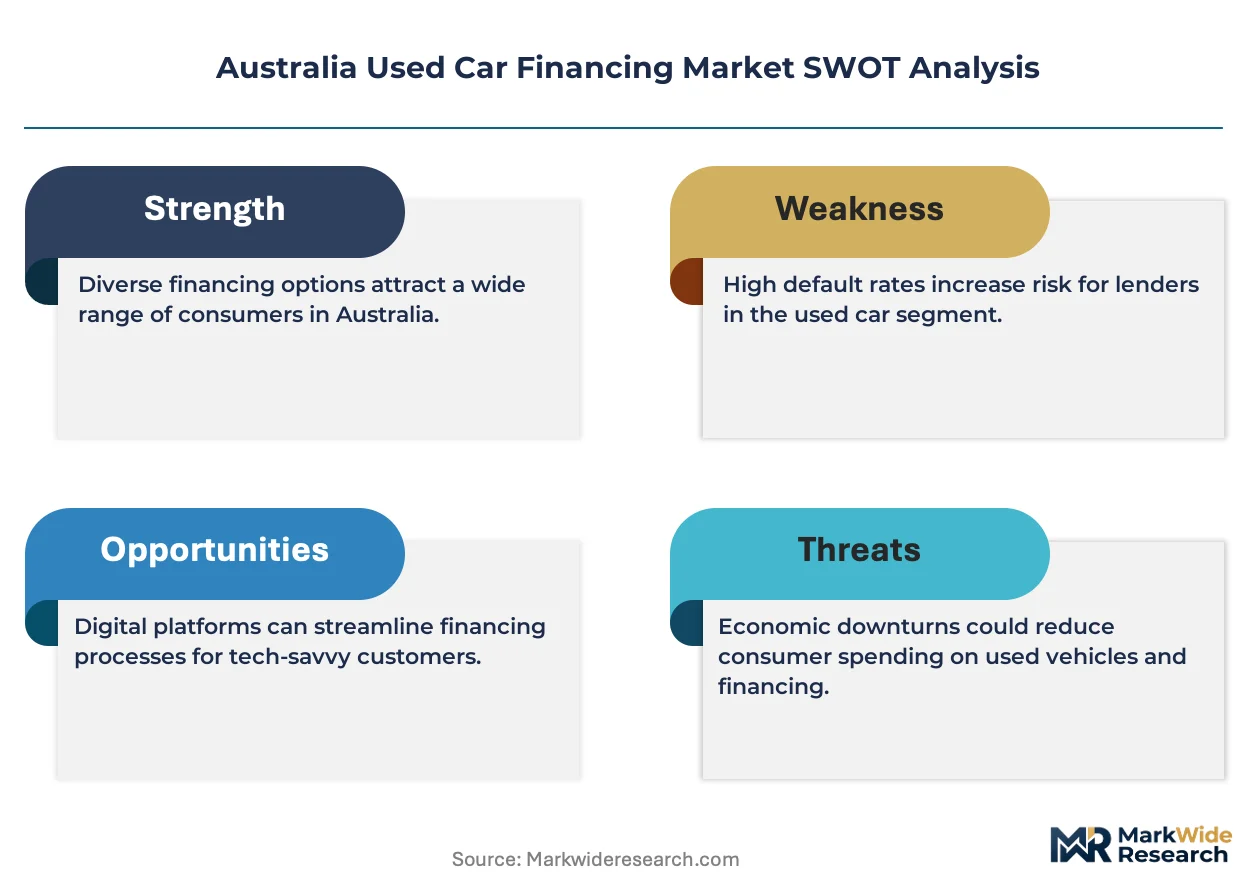
ASIC's responsible lending obligations under the National Consumer Credit Protection Act are compressing approval velocity and forcing lenders toward granular income verification infrastructure. This regulatory pressure redistributes competitive advantage toward specialist platforms with embedded compliance technology.
Growth Catalysts
- First-time buyer expansion:Digital lending platforms reduce friction for credit-thin applicants entering vehicle ownership. New South Wales and Victoria sustain concentrated application volumes through urban density.
- Comprehensive credit reporting:Treasury's open banking frameworks enable richer borrower data access. Lenders price risk with greater precision across non-prime segments.
- Fleet operator demand:Structured repayment schedules and larger ticket sizes attract institutional funding. Commercial buyers generate predictable interest income streams.
Market Restraints
- Residual value uncertainty:Depreciated asset collateral creates loan-to-value compression risk. Odometer certification and vehicle history verification add underwriting cost layers.
- Dealer network concentration:Point-of-sale financing dominance limits direct channel penetration. Embedded credit arrangements capture majority transaction flow.
- ASIC disclosure burdens:Hardship provision enforcement elevates operational compliance expenditure. Smaller originators face disproportionate regulatory technology investment requirements.
Strategic Opportunities
- Western Australia penetration:Mining sector vehicle turnover creates underbanked commercial financing demand. Resource-dependent regions exhibit lower digital platform saturation.
- Certified pre-owned integration:Captive programs tied to manufacturer-backed vehicle programs build retention. Structured residual value guarantees differentiate pricing tiers.
- Alternative data convergence:Banking transaction feeds and employment verification APIs compress assessment timelines. Real-time income validation reduces documentation friction.
Industry Challenges
- Credit assessment talent scarcity:Underwriters with non-prime portfolio experience command premium compensation. Specialist risk modeling expertise concentrates among incumbent platforms.
- Legacy system integration:Core banking infrastructure modernization demands sustained capital deployment. Real-time decisioning engines require parallel technology stack investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Used Car Financing Market |
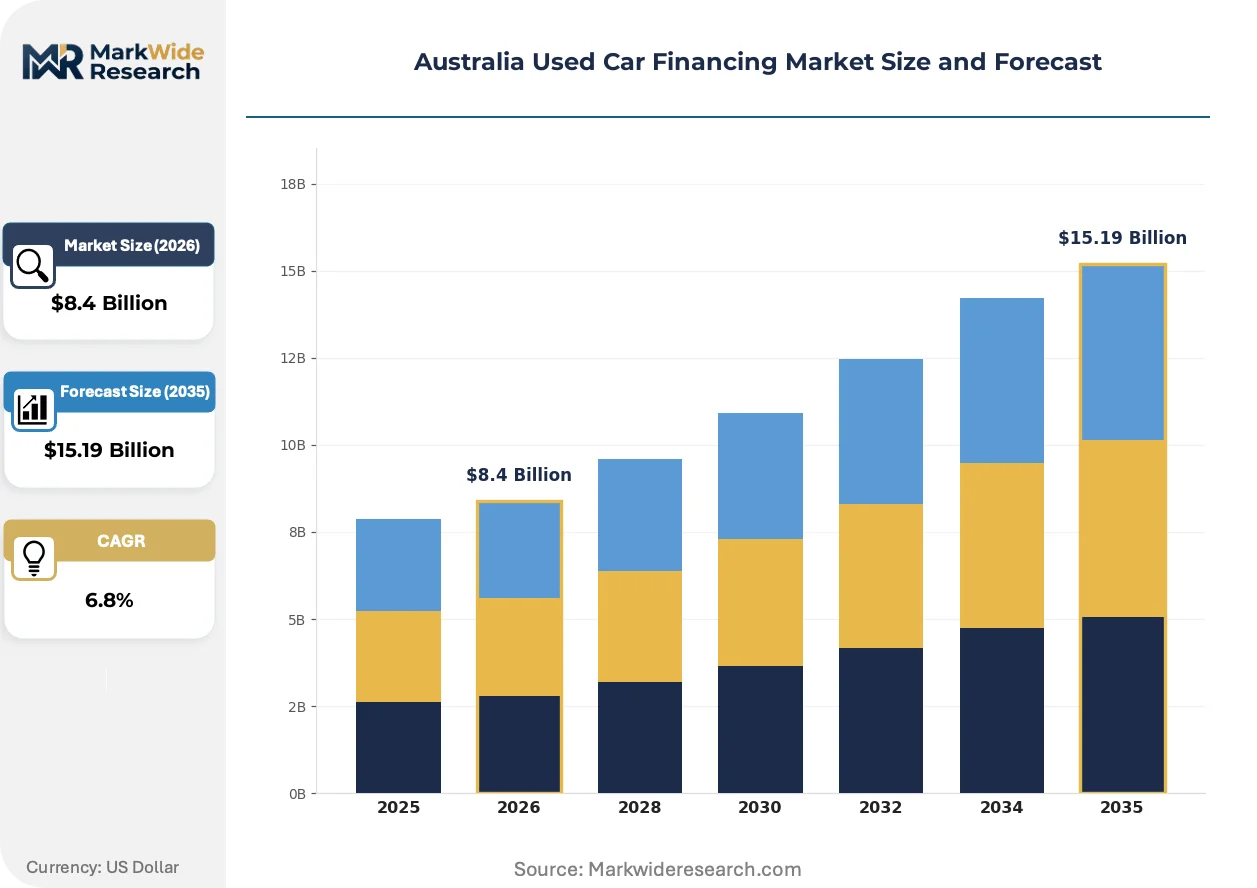
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Personal Loans, Dealer Financing, Lease Financing, Credit Union Loans Customer Segment: First-Time Buyers, Repeat Buyers, Fleet Operators, Businesses Vehicle Condition: Certified Pre-Owned, Non-Certified, Classic Cars, Luxury Used Cars Loan Duration: Short-Term, Medium-Term, Long-Term, Seasonal Financing |
| Companies Covered | Pepper Money Limited, Toyota Finance Australia Limited, National Australia Bank Limited, CommBank, Nissan Financial Services Australia Pty Ltd, The Australia and New Zealand Banking Group Limited, Latitude Automotive Financial Services, Liberty Financial, Plenti Pty Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Used Car Financing Market Strategic Shifts
Digital origination infrastructure is absorbing functions previously embedded in physical dealer networks. Lenders compete on assessment speed and seamless documentation workflows rather than rate alone.
Automated income verification through open banking APIs is absorbing manual payslip collection processes. Non-bank lenders deploy these tools most aggressively to compress approval timelines below traditional bank benchmarks. The technology is absorbing compliance burden from ASIC's responsible lending requirements while expanding addressable borrower pools.
Treasury's ongoing open banking framework review is reshaping data access permissions for credit providers. Lenders gain structured access to transaction histories that previously required borrower-initiated disclosure. Queensland and South Australia exhibit slower institutional adaptation, creating temporary competitive asymmetry.
Direct digital platforms are disintermediating dealer-embedded financing for repeat purchasers. Second-time buyers with established credit histories bypass showroom credit desks to secure competitive unsecured personal loans. This channel rotation concentrates among metropolitan Victorian and New South Wales applicants with existing banking relationships.
Australia Used Car Financing Market Segmentation
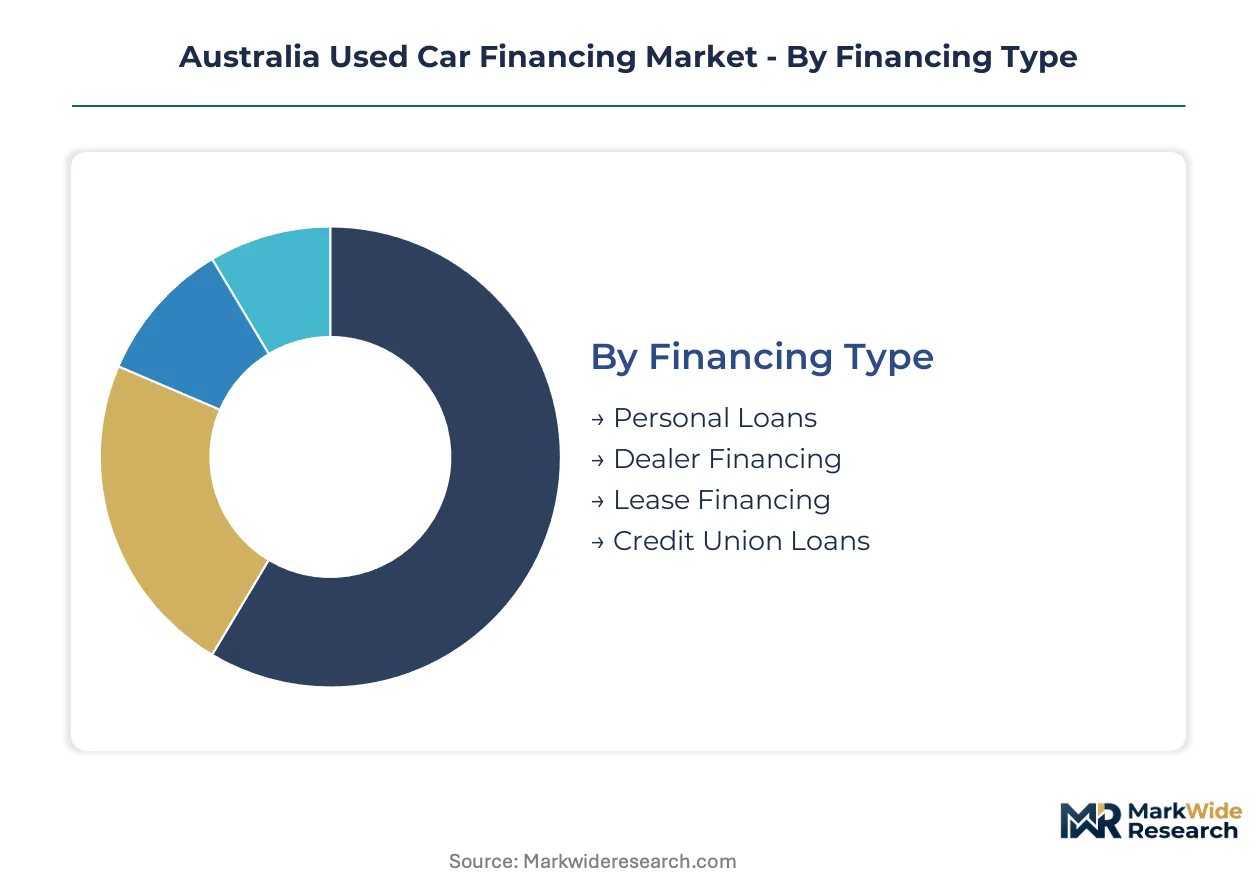
Used car financing in Australia fragments across four structural dimensions that determine origination cost, risk pricing, and channel strategy. Each segmentation axis carries distinct capital requirements and regulatory exposure that shape lender portfolio construction.
Financing Type:
Capital intensity varies sharply across origination channels, with captive dealer platforms requiring the heaviest technology and compliance infrastructure.
- Personal Loans:Unsecured credit products issued directly by banks and non-bank lenders, priced off borrower credit scores rather than vehicle collateral. Demand concentrates in metropolitan New South Wales and Victoria where established banking relationships reduce acquisition friction.
- Dealer Financing:Point-of-sale credit embedded through showroom networks, requiring residual value assessment and odometer verification infrastructure. This channel captures majority transaction volume through captive finance subsidiaries and third-party originators.
- Lease Financing:Operating and finance lease structures with balloon payment mechanics, common among commercial buyers seeking off-balance-sheet treatment.
- Credit Union Loans:Member-owned cooperative products with restricted eligibility criteria and rate advantages tied to deposit relationships.
Most installed capacity flows through Dealer Financing. Expansion is steepest in Personal Loans as direct digital platforms disintermediate showroom networks.
Customer Segment:
Portfolio yield correlates with customer sophistication, separating thin-file applicants from established credit relationships.
- First-Time Buyers:Credit-thin applicants entering vehicle ownership with limited repayment history, driving absolute application growth through digital onboarding tools. ASIC's responsible lending obligations force granular income verification for this cohort.
- Repeat Buyers:Established borrowers with demonstrated repayment capacity, often bypassing dealer financing for competitive unsecured personal loan rates through existing banking channels.
- Fleet Operators:Commercial buyers with structured repayment schedules and larger average ticket sizes, attracting institutional funding through predictable interest income streams.
- Businesses:Small and medium enterprises acquiring depreciated assets for operational use, requiring vehicle identification verification and commercial registration documentation.
Application volume concentrates with First-Time Buyers. Margin expansion is most pronounced among Fleet Operators.
Vehicle Condition:
Collateral quality determines loan-to-value ratios and residual risk exposure across the depreciation curve.
- Certified Pre-Owned:Manufacturer-backed vehicles with warranty coverage and inspection protocols, commanding tighter pricing spreads due to residual value guarantees. Toyota Finance Australia anchors volume through captive programs tied to this segment.
- Non-Certified:Depreciated assets without formal inspection backing, requiring independent vehicle history verification and elevated risk premiums.
- Classic Cars:Collectible vehicles with appreciation potential, demanding specialized appraisal expertise and restricted lender appetite.
- Luxury Used Cars:Premium marques with steeper depreciation curves but concentrated demand in Sydney and Melbourne metropolitan corridors.
Certified Pre-Owned vehicles carry the lowest loss severity. Collector and luxury segments exhibit the shallowest lender participation.
Loan Duration:
Funding cost and interest rate risk accumulate across maturity structures, separating working capital solutions from long-dated amortization.
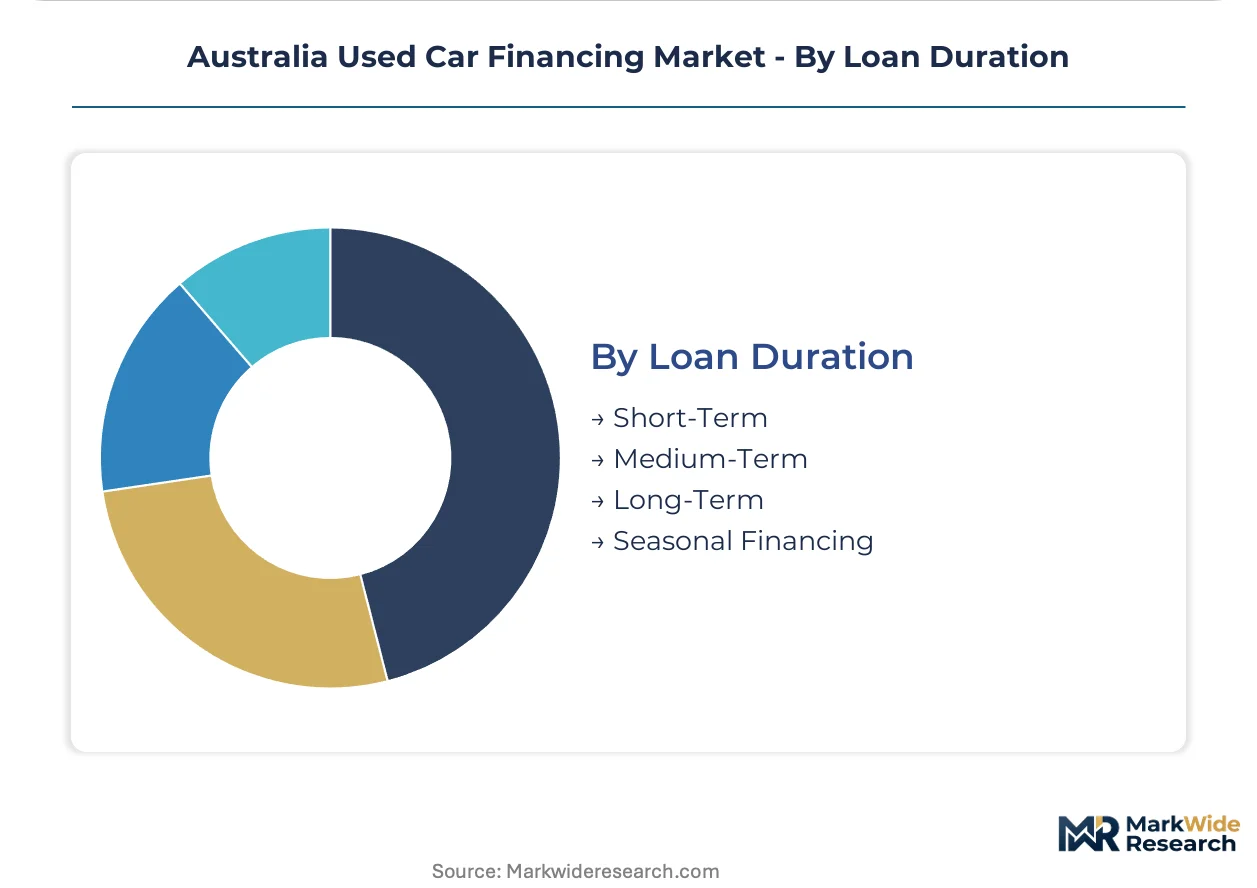
- Short-Term:Facilities under 24 months with accelerated principal repayment, common among fleet turnover and temporary replacement vehicles.
- Medium-Term:24-to-60 month structures matching typical vehicle ownership cycles, dominating consumer origination volume.
- Long-Term:Extended amortization beyond 60 months with elevated total interest cost, often paired with older collateral requiring stricter loan-to-value limits.
- Seasonal Financing:Agricultural and mining sector products aligned with commodity cash flow cycles, concentrated in Western Australia and Queensland resource corridors.
Medium-Term structures anchor portfolio composition. Seasonal Financing commands the widest spreads to compensate for cash flow volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist underwriters with non-prime portfolio expertise concentrate in Sydney and Melbourne, anchoring origination capacity for credit-thin applicants across Australia's eastern seaboard.
New South Wales
Urban density in Greater Sydney sustains the nation's highest used vehicle turnover rates, driving concentrated loan origination volumes through dealer networks. ASIC's responsible lending obligations force granular income verification infrastructure investment across Sydney-based platforms. The Parramatta-Blacktown corridor hosts the densest cluster of digital lending operations targeting first-time buyer segments.
Victoria
Metropolitan Melbourne's established banking relationships accelerate direct personal loan uptake among repeat purchasers bypassing showroom financing. The National Consumer Credit Protection Act elevates compliance technology spend for Melbourne-headquartered originators. The Dandenong automotive precinct anchors captive finance subsidiary operations tied to certified pre-owned vehicle programs.
Queensland
Brisbane-Gold Coast urban sprawl generates steady fleet operator demand from construction and logistics SMEs seeking depreciated commercial assets. Treasury's open banking framework review proceeds slower here than southern states, creating temporary competitive asymmetry in data access permissions. The Sunshine Coast exhibits rising digital platform penetration among younger first-time buyer cohorts.
Western Australia
Mining sector vehicle turnover in the Pilbara and Goldfields generates underbanked commercial financing demand with structured seasonal repayment requirements. The state's lower digital platform saturation preserves dealer network dominance in transaction flow. Perth-based specialist lenders command premium pricing for resource corridor fleet exposure.
Australia Used Car Financing Market Competitive Environment
Capital-heavy deposit-taking institutions compete with asset-light non-bank originators for borrower relationships across secured and unsecured credit products. The market structure fragments across four distinct tiers: major bank retail divisions, captive automotive finance subsidiaries, specialist non-prime platforms, and emerging digital direct lenders. Strategic archetypes separate balance-sheet-heavy incumbents with branch infrastructure from API-native challengers with automated decisioning engines. Dominant competitive moves include regulatory technology investment to compress ASIC compliance costs and open banking integration to accelerate income verification workflows.
Among specialist non-bank originators, Pepper Money Limited and Liberty Financial exemplify the non-prime platform archetype with embedded compliance infrastructure. Toyota Finance Australia Limited occupies the captive finance position, anchoring certified pre-owned vehicle program penetration. National Australia Bank Limited represents the integrated retail banking approach, folding used car products into broader consumer relationship architectures.
| Leading Market Players |
|---|
| Pepper Money Limited |
| Toyota Finance Australia Limited |
| National Australia Bank Limited |
| CommBank |
| Nissan Financial Services Australia Pty Ltd |
| The Australia and New Zealand Banking Group Limited |
| Latitude Automotive Financial Services |
| Liberty Financial |
| Plenti Pty Limited |
| Others |
Value Chain & Pricing Dynamics
Captive-dealer versus direct-lender bifurcation splits pricing power and sourcing logic across Australia's used car financing landscape. Dealer-embedded credit commands rate premiums through point-of-sale convenience while direct personal loans compress margins via digital platform competition, reshaping how capital flows from institutional funders to borrowers.
Pricing Analysis
Bundled residual value guarantees versus unbundled unsecured credit structures define the dominant pricing split. Three-tier pricing stratifies across premium certified pre-owned programs, standard dealer-arranged financing, and economy-tier personal loans for thin-file applicants. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because non-bank lenders deploy automated income verification to undercut traditional bank benchmarks. Fleet operators exhibit the least price sensitivity due to structured repayment schedules, while first-time buyers in New South Wales and Victoria show acute rate responsiveness.
Supply Chain Analysis
Dual-sourcing requirements from ASIC's responsible lending obligations force lenders to maintain parallel income verification infrastructure across proprietary systems and open banking APIs. Capital draws from domestic authorized deposit-taking institutions, securitization markets, and wholesale funding lines. Raw material dependencies include credit bureau data feeds, vehicle history databases, and employment verification APIs. Single-source vulnerability concentrates in comprehensive credit reporting infrastructure where Treasury's open banking framework remains incomplete. Distribution runs through captive dealer networks, direct digital platforms, and broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIC's National Consumer Credit Protection Act compounds competitive advantage for lenders with embedded compliance technology, elevating regulatory infrastructure from cost center to strategic differentiator.
For Market Incumbents: Deepen vertical integration into alternative data aggregation to compress ASIC-mandated assessment timelines. Incorporate real-time banking transaction feeds and employment verification APIs to defend against API-native challengers. Expand certified pre-owned captive programs to lock in residual value guarantees and rate premiums. For New Entrants and Emerging Players: The premium-to-economy rate spread in Western Australia mining corridors offers white-space entry for specialist non-prime platforms. Target underbanked fleet operators in resource-dependent regions with seasonal repayment structures. Deploy broker networks rather than direct digital acquisition to bypass entrenched dealer relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory technology investment thresholds exclude sub-scale originators. Long-term viability favors platforms with automated decisioning engines and open banking integration capabilities. Target acquisition archetypes include specialist non-prime lenders with embedded compliance infrastructure. Watch Treasury's comprehensive credit reporting rollout as inflection indicator for data-access competitive asymmetry.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Investment | ASIC's responsible lending obligations elevate automated compliance from cost to competitive moat. |
| Open Banking Integration | Treasury's framework review enables real-time income validation that compresses approval timelines below traditional benchmarks. |
| Certified Pre-Owned Program Expansion | Captive financing tied to manufacturer-backed vehicles builds borrower retention through residual value guarantees. |
| Alternative Data Partnership | Employment verification APIs and banking transaction feeds expand addressable pools for credit-thin applicants. |
| Western Australia Market Entry | Mining sector vehicle turnover generates underbanked commercial demand with premium pricing power. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged lending operations executives, credit risk officers at authorized deposit-taking institutions, dealer finance managers, regulatory compliance leads, and open banking technology providers. Secondary validation drew from ASIC regulatory filings, APRA prudential statistics, Treasury consultation papers, and securitization trustee reports. Bottom-up loan origination data triangulated against top-down funding flow estimates.
Segment-weighting approaches distributed value and volume across financing type, customer segment, vehicle condition, and loan duration dimensions. CAGRs derived from fitted growth curves applied to historical origination trajectories across the projection horizon. Forecast inputs incorporated regulatory implementation timelines for open banking frameworks and evolving responsible lending interpretation.
Caveats apply where ASIC enforcement intensity or Treasury's comprehensive credit reporting rollout timing could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and funding market liquidity. Deviation in responsible lending judicial interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Digital Lending Software Market