
 United Kingdom Auto Loan Market | 2026-2036
United Kingdom Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Auto Loan Market Insights
FCA Consumer Duty compliance is reorganizing which lenders can operate profitably in the United Kingdom auto loan space. Black Horse Finance leverages its captive finance relationship with Lloyds Banking Group to sustain broad dealer network coverage. MotoNovo Finance anchors its position through technology leadership in digital loan origination platforms.
United Kingdom auto loans represent secured and unsecured credit instruments collateralized by passenger vehicles, with interest rates indexed to the Bank of England base rate plus risk-adjusted spreads, designed to enable consumer and commercial vehicle acquisition without full capital outlay. The Personal Contract Purchase segment dominates origination volumes due to its balloon-payment structure aligning with British depreciation expectations. Electric vehicle financing within the Vehicle Type dimension is attracting preferential rate pricing as lenders compete for green-asset exposure.
The Financial Conduct Authority enforces Consumer Duty standards requiring transparent affordability verification, while the Bank of England's Prudential Regulation Authority governs capital adequacy ratios constraining lender balance-sheet expansion. The Financial Ombudsman Service adjudicates disputes, creating reputational risk that shapes product design and complaint-handling investment. Stakeholders must monitor how the FCA's pending motor finance commission disclosure rules will reshape broker-lender economics and consumer choice architecture.
Market Dynamics
The Financial Conduct Authority's Consumer Duty rules are compressing lender margins while simultaneously redistributing origination volume toward dealers with compliant infrastructure. This regulatory pressure is forcing a structural separation between balance-sheet lenders and thin-capital intermediaries.
Growth Catalysts
- Electric vehicle transition:The UK government's Zero Emission Vehicle mandate is accelerating demand for green-asset financing products. Lenders are building dedicated EV underwriting capabilities to capture this origination pool.
- FCA Consumer Duty:The regulator's transparency requirements are advantaging established lenders with pre-existing compliance infrastructure. This is consolidating origination relationships around fewer, better-capitalized players.
- Dealer financing partnerships:Used car dealerships are deepening captive finance arrangements as their primary customer acquisition channel. This is embedding loan origination directly into the vehicle purchase journey.
Market Restraints
- Interest rate volatility:The Bank of England's base rate adjustments are compressing net interest margins across floating-rate loan books. Lenders face repricing lag versus funding cost movements.
- Capital adequacy requirements:The Prudential Regulation Authority's risk-weighting rules constrain balance-sheet expansion for high-volume originators. This limits aggressive market share pursuit.
- Commission disclosure rules:Pending FCA motor finance disclosure requirements threaten broker-lender economics. Intermediary compensation structures face fundamental restructuring.
Strategic Opportunities
- Greater London EV concentration:The capital's Ultra Low Emission Zone is creating a geographic cluster of high-intent electric vehicle buyers. Lenders can deploy specialized products to this postcode-concentrated demand.
- Digital origination platforms:Technology-enabled instant decisioning is reducing friction in the dealer sales process. First-movers are capturing exclusive dealership relationships.
- Personal Contract Purchase innovation:Balloon-payment structures aligned with British depreciation expectations retain origination dominance. Product design refinement around residual value risk transfer offers differentiation.
Industry Challenges
- Affordability verification complexity:The Financial Ombudsman Service's adjudication standards require enhanced documentation of income and expenditure assessment. Complaint-handling investment is diverting operational resources.
- Legacy system integration:Real-time regulatory reporting demands are clashing with older loan servicing platforms. Technology modernization timelines risk competitive disadvantage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Auto Loan Market |
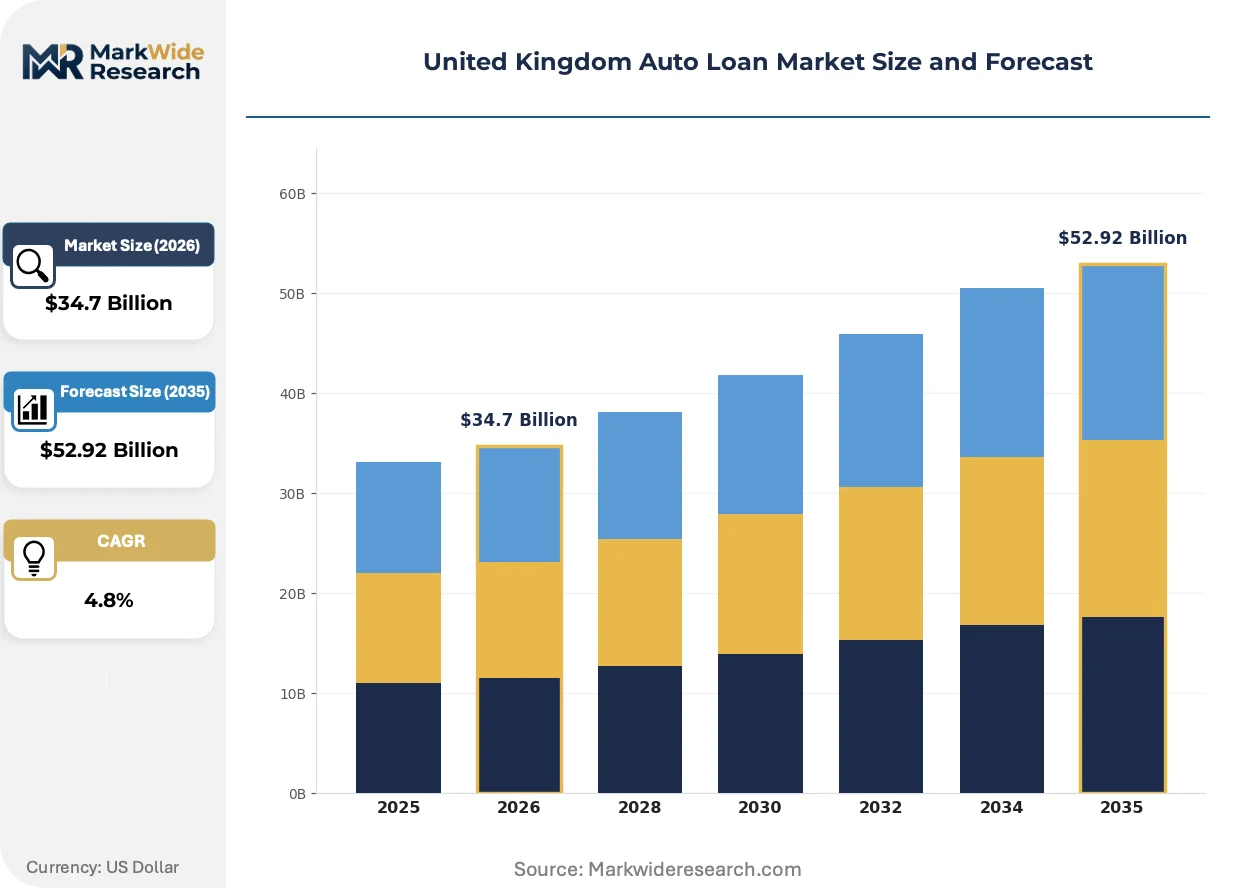
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.92 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Personal Loan, Hire Purchase, PCP, Secured Loan Lending Institution: Bank, Credit Union, Online Lender, Finance Company Customer Profile: First-Time Buyers, Young Professionals, Families, Businesses Vehicle Type: Electric, Hybrid, Saloon, SUV |
| Companies Covered | Black Horse Finance, MotoNovo Finance, Blue Motor Finance, Northridge Car Finance, Close Brothers Motor Finance, Lloyds Bank, Nationwide Building Society, Royal Bank of Scotland, Santander UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Auto Loan Market Trends and Innovations
Open banking data integration is transforming how UK lenders verify borrower affordability in real time. This technology shift is compressing decision timelines while raising compliance accuracy.
Artificial intelligence-powered credit scoring is fragmenting traditional risk segmentation models. Subprime specialists are deploying machine learning to identify thin-file borrowers previously excluded from prime pricing. The structural consequence is a compression of risk-based rate spreads as granular data substitutes for broad demographic proxies.
The Financial Conduct Authority's pending motor finance commission disclosure rules are forcing product architecture redesign. Lenders must restructure broker compensation to maintain distribution access while meeting transparency mandates. The point-of-sale finance segment is most affected, with dealers demanding alternative revenue mechanisms.
Subscription-based vehicle access models are emerging as a behavioral alternative to traditional ownership finance. Fleet operators and mobility platforms are piloting bundled insurance-maintenance-finance products. This consumption-pattern shift is most visible in corporate fleet procurement within Greater London's congestion-charged zones.
United Kingdom Auto Loan Market Segmentation
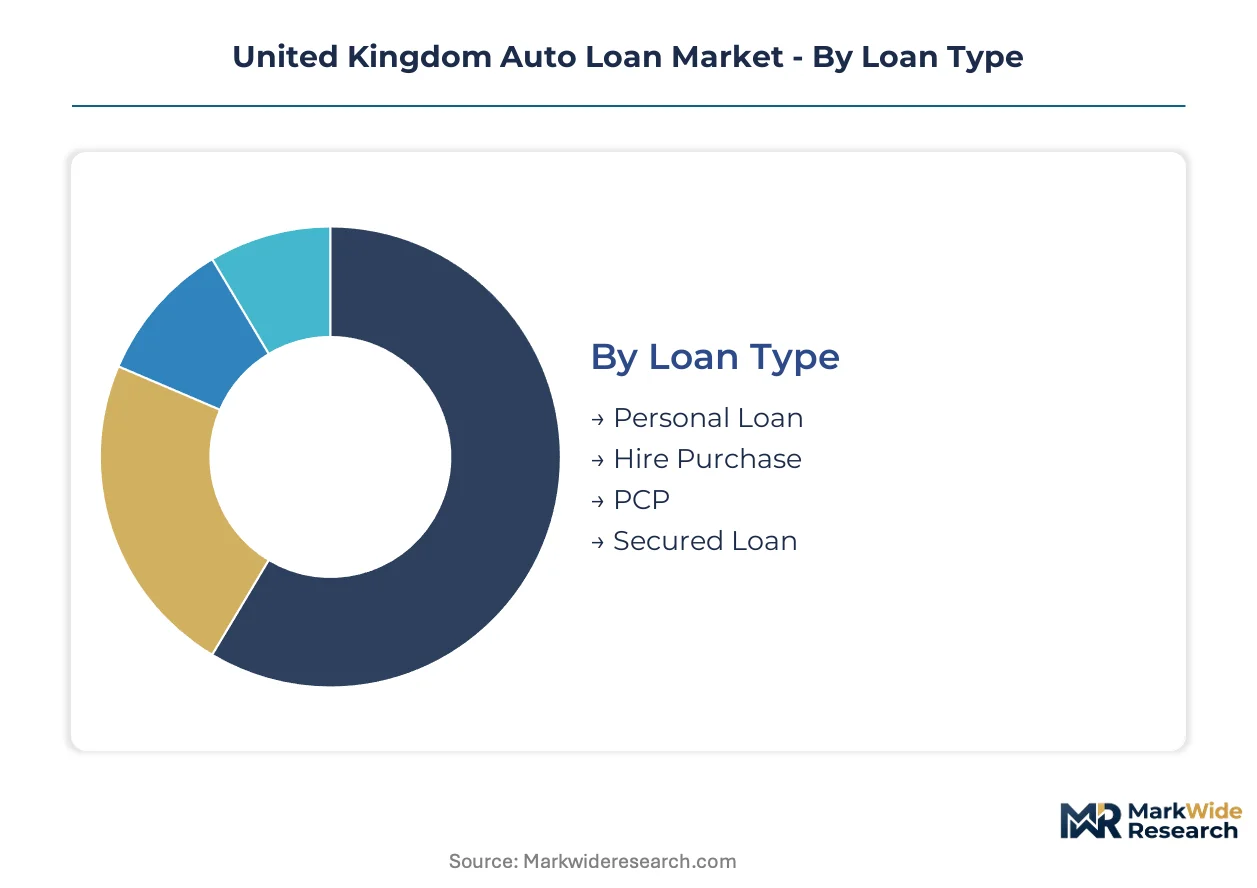
Auto loan segmentation in the United Kingdom determines which products flow through captive finance arms versus independent brokers. Channel economics vary sharply across these dimensions, shaping lender profitability and dealer partnership terms.
Loan Type:
Channel distribution diverges sharply across loan structures, with dealer-integrated products commanding exclusive placement while direct lending competes on rate transparency.
- Personal Contract Purchase (PCP):Balloon-payment structures dominate dealer forecourts, embedding residual value risk within the finance package. Greater London dealerships report PCP attachment rates above national averages due to higher vehicle turnover cycles and ULEZ-driven replacement demand.
- Hire Purchase:Fixed-term ownership transfer products attract borrowers seeking outright title certainty. Northern England postcodes show concentrated demand where vehicle retention periods exceed five years and depreciation exposure is minimized through longer holding.
- Personal Loan:Unsecured bank products compete on headline APR transparency, bypassing dealer commission structures entirely.
- Secured Loan:Asset-backed instruments from specialist lenders serve subprime segments with elevated risk-adjusted pricing.
PCP dominates installed base across all UK regions. Hire Purchase is where expansion concentrates among credit unions building dealer networks.
Lending Institution:
Cost-tier positioning separates balance-sheet lenders from thin-capital intermediaries, with regulatory capital requirements determining viable scale.
- Bank:Deposit-funded institutions leverage base-rate sensitivity and existing current account relationships. The Prudential Regulation Authority's capital adequacy framework constrains aggressive market share pursuit, concentrating prime-rate competition among the five largest clearing banks.
- Finance Company:Captive arms of manufacturer groups control point-of-sale placement through exclusive dealer agreements. Black Horse Finance maintains broad coverage through Lloyds Banking Group infrastructure, while Volkswagen Financial Services anchors continental European parentage with UK-specific product adaptation.
- Credit Union:Member-owned cooperatives serve community-bonded borrowers with rate caps reflecting ethical lending mandates.
- Online Lender:Digital-native platforms compete on instant decisioning speed, capturing broker-referred volume outside dealer relationships.
Finance Company channels dominate point-of-sale origination volume. Online Lender segments are climbing the fastest as aggregator platforms redirect comparison-shopping behavior.
Customer Profile:
Application-based segmentation aligns product design with life-stage vehicle needs and repayment capacity verification complexity.
- Families:Multi-vehicle households generate consolidated finance applications with cross-collateralization potential. South East England concentrations reflect dual-income suburban demographics and school-run vehicle requirements driving SUV preference.
- Young Professionals:Thin-file borrowers with limited credit history attract AI-powered scoring innovation from subprime specialists. Urban employment clustering in Manchester and Birmingham creates geographic origination pools for income-verification-light products.
- First-Time Buyers:Entry-level borrowers face stringent FCA Consumer Duty affordability assessments.
- Businesses:Fleet procurement segments demand VAT-efficient structures and mileage-based pricing flexibility.
Families represent the largest outstanding balance pool. Young Professionals are gaining share fastest through digital channel migration.
Vehicle Type:
Geographic demand concentration creates postcode-specific origination opportunities aligned with local policy incentives.
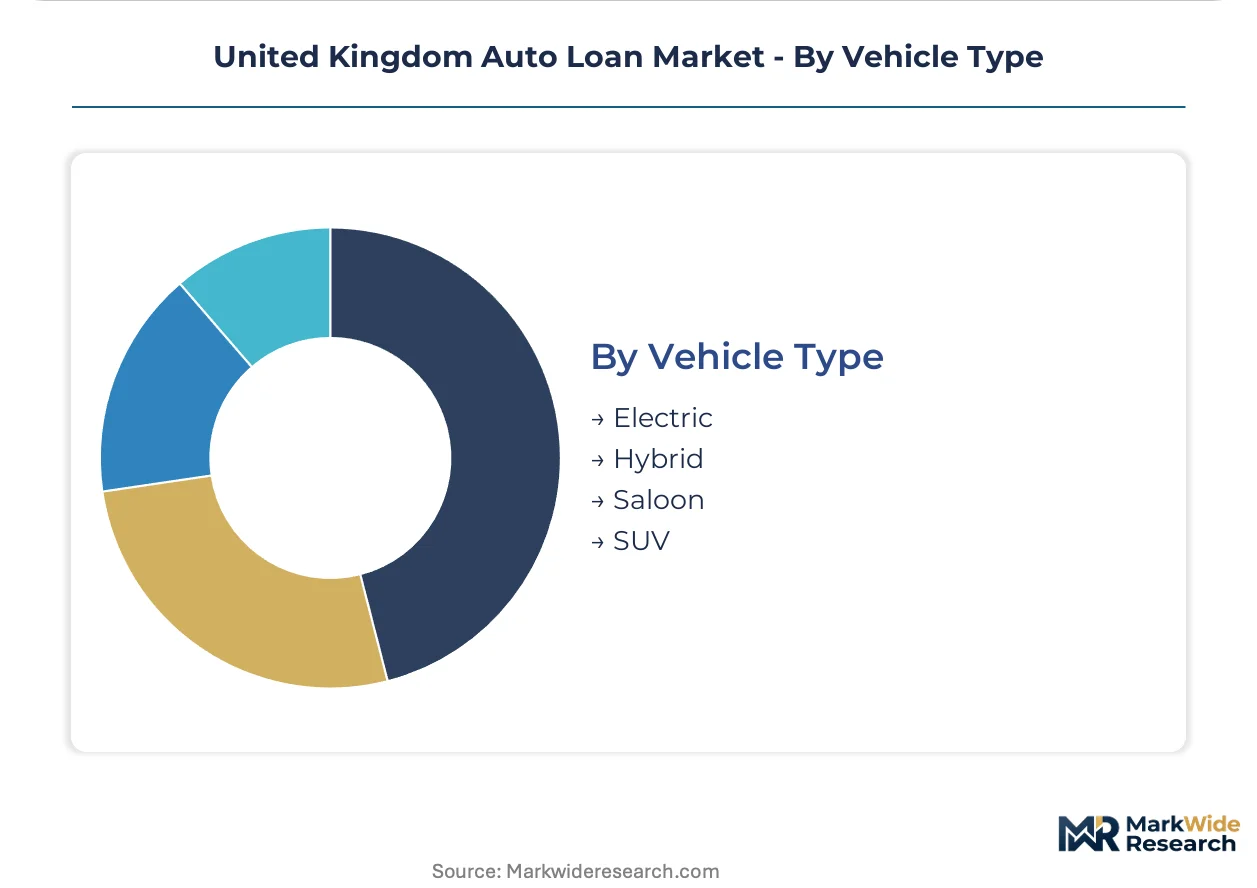
- Electric:Zero-emission vehicles attract preferential rate pricing as lenders compete for green-asset exposure. London's Ultra Low Emission Zone and expanding clean air zones in Bristol, Birmingham, and Glasgow concentrate high-intent buyers in specific postcode clusters.
- Hybrid:Transitional powertrains serve buyers hedging against charging infrastructure gaps. South East England demand reflects commuter belt driving patterns where electric range covers weekday use but hybrid flexibility addresses longer journeys.
- SUV:Higher-ticket segments generate larger absolute finance values with extended terms.
- Saloon:Traditional body styles retain corporate fleet preference for executive vehicle policies.
Hybrid vehicles dominate current origination volumes. Electric segments show steepest expansion trajectory as mandate deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals and family households with dual incomes dominate auto loan origination across England's economic corridors. The Financial Conduct Authority's Consumer Duty rules apply uniformly, yet regional compliance infrastructure varies sharply. Postcode-level demand clusters around congestion charging zones and clean air mandates.
Greater London
Ultra Low Emission Zone penalties are accelerating electric vehicle replacement cycles among commuter households. The Mayor of London's expanded ULEZ boundaries are concentrating high-intent EV buyers in outer borough postcodes. Canary Wharf and City of London employment clusters generate premium vehicle finance applications with shorter replacement intervals.
South East England
Suburban family demographics with school-run vehicle requirements are driving SUV and multi-car household financing. The Department for Transport's EV chargepoint grants are supporting home installation among detached property owners. Guildford and Reading commuter belt concentrations show elevated Personal Contract Purchase attachment rates.
Midlands
Manufacturing employment bases sustain Hire Purchase preference for longer vehicle retention periods. Birmingham's Clean Air Zone is creating localized EV transition demand distinct from national patterns. West Midlands automotive supply chain workers access manufacturer captive finance through employee schemes.
North England
Credit union expansion is penetrating dealer networks previously served by bank branches. Manchester and Leeds city centre employment growth is attracting young professional borrowers with thin-file credit histories. Northern Powerhouse transport investment is extending commuter catchments and associated vehicle finance demand.
Scotland
Low Emission Zones in Glasgow and Edinburgh are replicating London's EV financing concentration at smaller scale. Transport Scotland's interest-free electric vehicle loans are displacing commercial bank products in eligible postcodes. Aberdeen's energy sector employment volatility is creating income verification complexity for affordability assessments.
United Kingdom Auto Loan Market Competitive Landscape
Player mix skews toward bank-owned captive finance arms with deposit-funded balance sheets. The sector shows moderate concentration around five clearing banks and their motor finance subsidiaries. Two strategic archetypes dominate: integrated banking groups leveraging current account relationships, and independent finance companies competing on digital origination speed. Competitive moves center on exclusive dealership network expansion and real-time affordability verification technology deployment.
Within the banking group tier, Lloyds Bank and its Black Horse Finance subsidiary exemplify integrated retail and motor finance operations. Santander UK represents the international bank archetype with UK-specific product adaptation. Among independent specialists, MotoNovo Finance occupies a position defined by technology-led instant decisioning capabilities.
| Leading Market Players |
|---|
| Black Horse Finance |
| MotoNovo Finance |
| Blue Motor Finance |
| Northridge Car Finance |
| Close Brothers Motor Finance |
| Lloyds Bank |
| Nationwide Building Society |
| Royal Bank of Scotland |
| Santander UK |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day funding pipeline intervals from loan application to dealer settlement concentrate origination power among balance-sheet lenders with deposit stability, compressing thin-capital intermediaries into rate-taker positions and amplifying pricing power for those with Prudential Regulation Authority capital buffers.
Pricing Analysis
Base-rate-plus-spread contracts indexed to the Bank of England policy rate dominate UK auto loan pricing, with risk-adjusted margins varying by borrower credit tier and vehicle collateral depreciation profile. Price differentiation rests on FCA Consumer Duty compliance infrastructure costs and real-time affordability verification capability rather than simple credit scoring. Pricing pressure stems from the regulator's pending motor finance commission disclosure rules threatening broker-lender economics. Fleet procurement segments show lowest price sensitivity due to VAT efficiency priorities, while young professional thin-file borrowers face highest rate elasticity.
Supply Chain Analysis
The United Kingdom and Germany anchor captive finance origination through manufacturer-affiliated lenders with exclusive dealer network access. Vehicle collateral valuation services, credit reference agency data feeds, and open banking infrastructure providers constitute critical input dependencies. Supply chain risk concentrates in single-source vulnerability to Experian and Equifax credit data monopolies. Distribution runs through point-of-sale dealer integration rather than direct-to-consumer channels, embedding loan origination within vehicle purchase journeys.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among dealer groups consolidating forecourt networks, shifting origination volume toward fewer distribution gatekeepers with captive finance exclusivity demands.
For Market Incumbents: Fortify dealer exclusivity agreements through technology co-investment in instant decisioning platforms, insulating against MotoNovo Finance digital origination speed advantages. Deepen open banking integration to sustain FCA Consumer Duty compliance cost advantages that thin-capital intermediaries cannot replicate. Prioritize balance-sheet scale to absorb Prudential Regulation Authority capital adequacy constraints that constrain aggressive pricing. For New Entrants and Emerging Players: Differentiate on AI-powered thin-file credit scoring for young professional segments in Manchester and Leeds urban employment clusters where traditional risk models exclude qualified borrowers. Target credit union partnership channels in North England postcodes where community-bonded lending ethics align with ethical finance positioning. Deploy aggregator platform referral relationships as primary customer acquisition mechanism outside dealer-controlled distribution. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because FCA Consumer Duty rules are structurally consolidating origination around fewer better-capitalized lenders with pre-existing compliance investment. Acquisition targets should emphasize digital origination platforms with exclusive dealership relationships and real-time affordability verification technology. Watch the Financial Ombudsman Service complaint adjudication volume as signal of lender operational risk exposure and reputational capital depletion.| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking Integration | Real-time affordability verification compresses decision timelines while raising FCA Consumer Duty compliance accuracy. |
| EV-Only Product Line Launch | Zero Emission Vehicle mandate deadlines concentrate high-intent buyers in Greater London ULEZ postcode clusters. |
| Dealer Network Exclusivity Expansion | Point-of-sale origination embedding captures vehicle purchase journey before rate comparison shopping begins. |
| AI Credit Scoring Investment | Machine learning identifies thin-file borrowers previously excluded, fragmenting traditional risk segmentation models. |
| Residual Value Risk Transfer Instruments | Balloon-payment structure refinement aligns PCP products with British depreciation expectations and lender balance-sheet protection. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Bank of England regulatory filings, Financial Conduct Authority consultation papers, and dealer network financial disclosures. Primary interviews engaged motor finance underwriting directors, dealership operations managers, credit union lending officers, and open banking technology providers. Secondary sources encompassed vehicle registration databases, Prudential Regulation Authority capital adequacy returns, and Financial Ombudsman Service complaint statistics. Bottom-up origination volume analysis triangulates against top-down market sizing from banking group segment reporting.
Segmentation dimensions modeled encompass loan type structure, lending institution category, customer profile archetype, and vehicle propulsion technology across the projection horizon. CAGRs derive from regression analysis against Bank of England base rate scenarios and electric vehicle mandate compliance timelines. Forecast inputs incorporate ULEZ expansion schedules, clean air zone policy implementation, and captive finance dealer exclusivity contract renewal patterns.
Material uncertainties — Bank of England monetary policy reversals, FCA commission disclosure rule finalization, and electric vehicle residual value volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory implementation timelines and consumer adoption elasticities. Recalibration cycles align with material shifts in Prudential Regulation Authority capital requirements and Financial Ombudsman Service adjudication standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Microfinance Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market