
 Japan Car Loan Market | 2026-2036
Japan Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Car Loan Market Insights
Modular loan packaging is realigning buyer choice across Japan's auto finance sector. Toyota Financial Services leverages captive financing ties to anchor its position in dealer-channel distribution. Mitsubishi UFJ Lease & Finance competes through diversified corporate and retail product lines. Sumitomo Mitsui Trust Bank differentiates via digital underwriting platforms that streamline approval workflows.
A car loan constitutes a secured or unsecured credit instrument collateralized by a vehicle, governed by interest rate terms spanning fixed, variable, floating, or promotional structures, with repayment schedules calibrated to borrower cash flow profiles. Its commercial purpose centers on enabling vehicle acquisition while generating interest income for lenders and managing default risk through collateral valuation and credit scoring methodologies. Secured loans dominate outstanding portfolio value due to lower loss severity from vehicle repossession rights. Individual borrowers represent the fastest-expanding customer segment as digital origination reduces branch dependency. Variable rate products attract rate-sensitive applicants seeking initial payment relief, though fixed rate structures retain preference among risk-averse households.
METI's automotive industry policies, the Financial Services Agency's consumer credit oversight, and JIS standards for vehicle valuation collectively shape product design, disclosure requirements, and collateral assessment protocols across Japanese lenders. The FSA's interest rate caps and cooling-off period mandates constrain pricing flexibility while elevating transparency burdens on originators. Stakeholders must monitor the convergence of embedded finance platforms with used-vehicle market liquidity as the decisive factor for portfolio yield management.
Market Dynamics
Digital origination platforms are compressing branch-based lending timelines while METI's green mobility incentives redirect credit flows toward electrified vehicle segments. This structural pivot is reshaping collateral valuation methodologies and borrower acquisition costs across Japanese auto finance.
Growth Catalysts
- Green Mobility Incentives:METI's subsidy frameworks for battery-electric and hybrid vehicles are expanding loan eligibility for low-emission models. Lenders are integrating carbon-intensity scoring into underwriting protocols.
- Digital Underwriting:API-connected income verification and real-time credit scoring are collapsing approval cycles from days to hours. Regional banks are deploying cloud-native platforms to match megabank efficiency.
- Used-Vehicle Market Liquidity:Standardized JIS residual value assessments are deepening secondary market depth. Enhanced collateral recovery rates are improving secured loan risk-adjusted returns.
Market Restraints
- FSA Interest Rate Caps:The Financial Services Agency's maximum lending rate restrictions are compressing net interest margins on subprime segments. Originators face profitability pressure on smaller-ticket loans.
- Demographic Contraction:Japan's shrinking working-age population is constraining first-time borrower formation. Rural prefectures exhibit accelerating loan book runoff as younger cohorts migrate to urban centers.
- Collateral Depreciation Volatility:Semiconductor supply disruptions and model-cycle acceleration are destabilizing residual value forecasting. Lenders carry heightened mark-to-market exposure on leased vehicle portfolios.
Strategic Opportunities
- Embedded Finance Integration:Direct-to-consumer auto platforms are creating white-label lending partnerships. Captive finance arms can extend distribution without physical dealership expansion.
- Subscription-to-Ownership Pathways:Flexible lease-convert structures are capturing younger borrowers averse to traditional amortization. These products build credit history while preserving mobility optionality.
- Prefectural Green Zones:Aichi and Osaka prefectures are piloting zero-interest municipal supplements for commercial EV adoption. Local government co-guarantees are de-risking fleet finance origination.
Industry Challenges
- Legacy Core System Integration:Regional lenders face technical debt when connecting digital front-ends to 1980s-era loan servicing platforms. Middleware costs are eroding projected efficiency gains from automation.
- Credit Bureau Data Fragmentation:Multiple scoring systems across JIC, CIC, and private bureaus create inconsistent risk assessments. Cross-referencing requirements are elongating underwriting workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Car Loan Market |
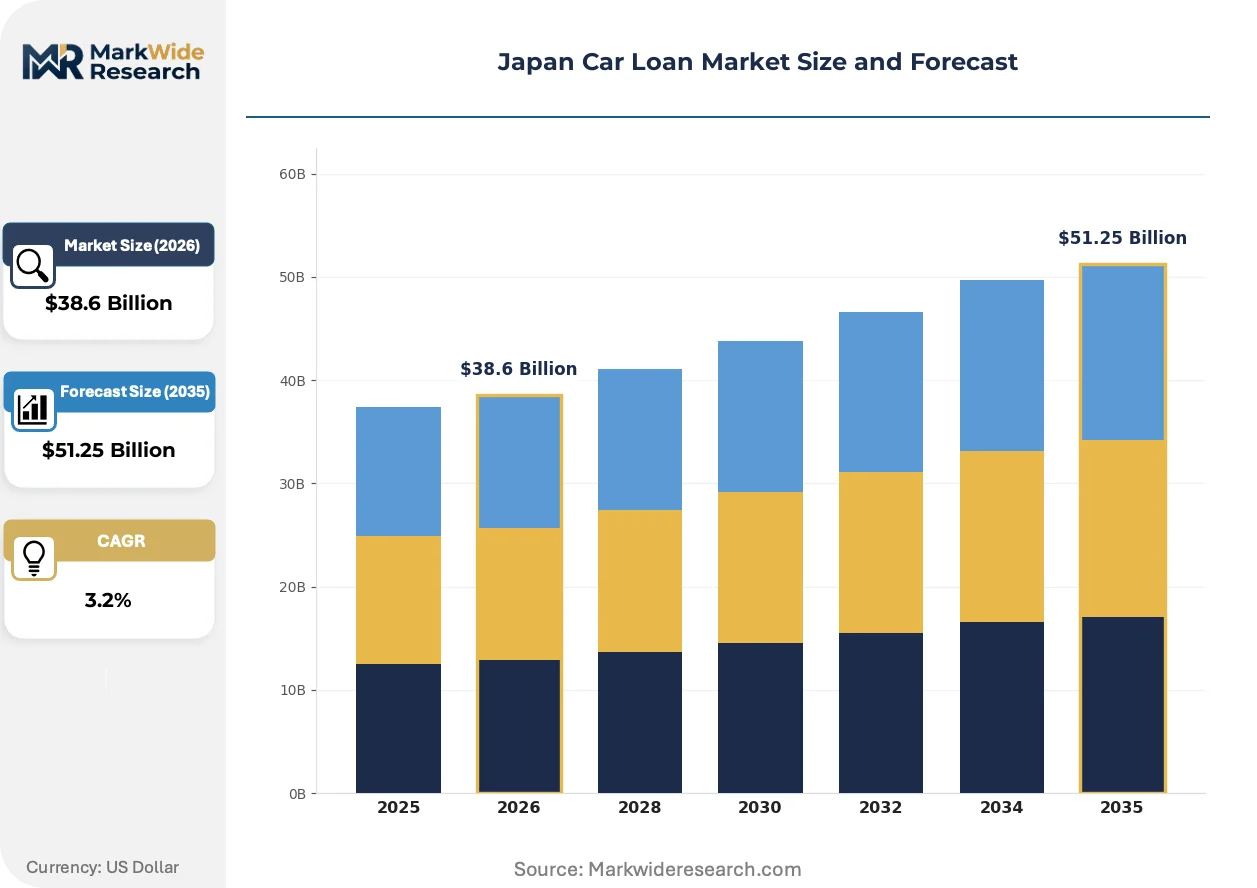
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Lease Financing, Personal Loans Customer Type: Individual Borrowers, Corporates, Small Businesses, Startups Repayment Tenure: Short-Term, Medium-Term, Long-Term, Flexible Tenure Interest Rate Type: Fixed Rates, Variable Rates, Floating Rates, Promotional Rates |
| Companies Covered | Orient Corporation, SURUGA bank Ltd, Toyota Financial Services, Mitsubishi UFJ Lease & Finance, MARUHAN Japan Bank Lao Co., Ltd, Honda Finance, Bank of Kyoto, Ltd, Sumitomo Mitsui Trust Bank, Nissan Motor Acceptance Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Car Loan Market Trends and Innovations
API-driven ecosystem integration is dissolving traditional boundaries between vehicle commerce, financing, and insurance. This convergence is spawning modular product architectures that unbundle and reassemble legacy auto loan constructs.
Artificial intelligence-powered income verification is expanding into pay-slip parsing, gig-economy transaction analysis, and multi-balance-sheet assessment. Digital-first lenders are deploying these tools to underbanked segments previously excluded from prime rate tiers. The technology is expanding into rural prefectures where traditional employment documentation remains sparse.
METI's carbon-neutral vehicle roadmap is mandating disclosure of financed emissions across institutional portfolios. Lenders must now report scope-three exposure tied to collateral vehicle lifetime emissions. The regulation is compressing availability of internal-combustion-only loan products and accelerating green-linked pricing differentiation.
Direct digital origination is displacing dealer-mediated application submission among younger borrower cohorts. Smartphone-native comparison platforms are aggregating rate offers across captive, bank, and credit union channels. This behavioral shift concentrates in the Greater Tokyo Area where digital literacy and platform penetration rates exceed national averages.
Japan Car Loan Market Segmentation
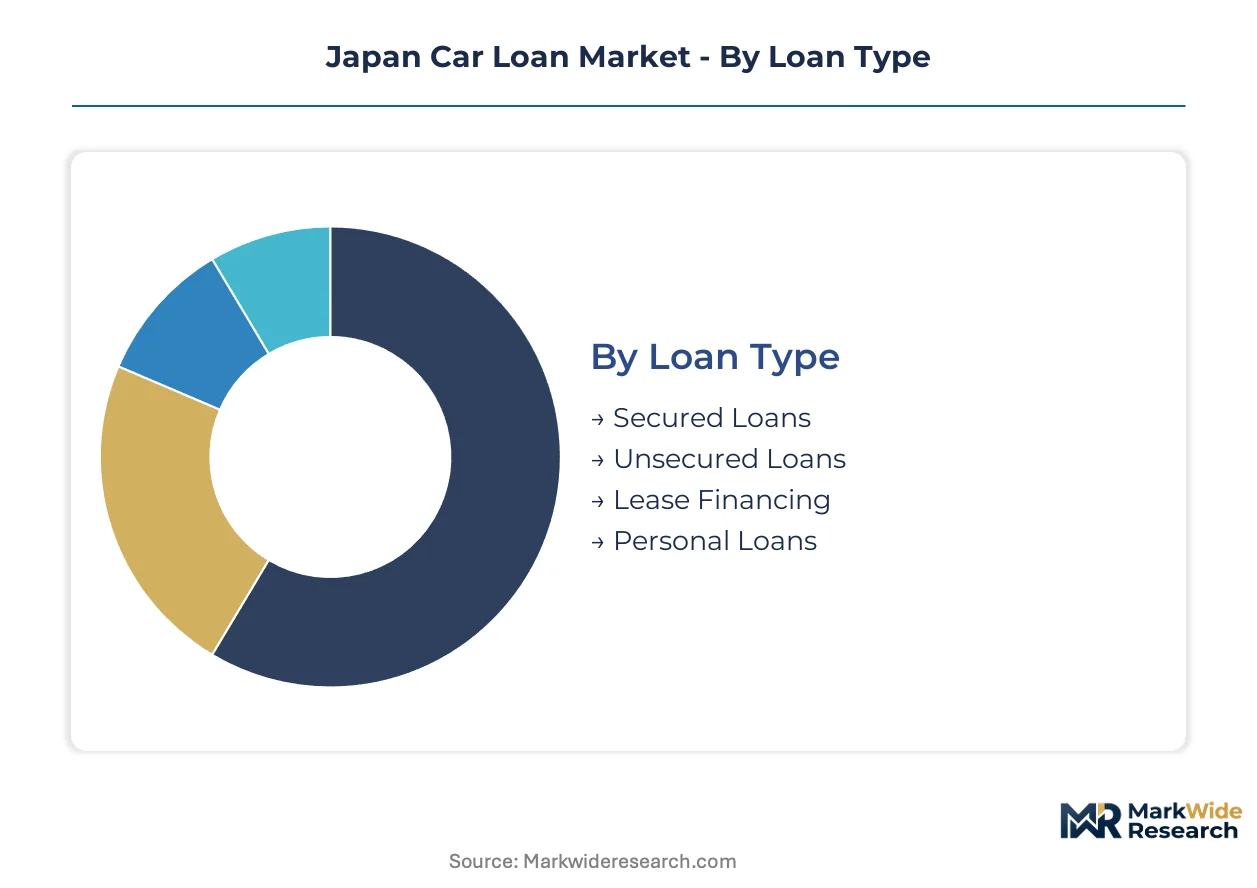
Segmentation in Japan's auto finance market determines collateral treatment, underwriting protocols, and regulatory disclosure obligations. Lenders structure product architectures around loan security, borrower entity type, duration profiles, and rate sensitivity to optimize risk-adjusted returns.
Loan Type:
Supply concentration in secured products reflects Japan's strong legal framework for vehicle repossession and residual value recovery.
- Secured Loans:Collateralized by vehicle title with registered security interest under Japan's Civil Code. Greater Tokyo Area dealerships channel the majority of origination volume, supported by standardized JIS valuation protocols that streamline collateral assessment.
- Unsecured Loans:Credit extensions relying solely on borrower creditworthiness without asset attachment. Osaka Prefecture shows elevated demand among established professionals with stable income documentation, though FSA interest rate caps compress pricing flexibility.
- Lease Financing:Operating and finance lease structures with residual value risk retention by lessor. Fleet operators in Aichi Prefecture favor this structure for commercial vehicle procurement.
- Personal Loans:General-purpose credit instruments applied to vehicle acquisition without specific collateral linkage. Digital platforms in urban centers are expanding accessibility for thin-file borrowers.
Secured loans absorb the bulk of installed capacity; lease financing is expanding most quickly amid fleet electrification mandates.
Customer Type:
Cost tier differentiation separates mass-market retail from specialized corporate underwriting with divergent documentation requirements.
- Individual Borrowers:Natural persons financing personal vehicle acquisition through salary-backed repayment. Digital origination platforms in the Greater Tokyo Area are collapsing approval timelines for this segment.
- Corporates:Established enterprises financing fleet vehicles or executive automobiles. Aichi Prefecture manufacturers dominate this category with centralized procurement and bulk rate negotiations.
- Small Businesses:Sole proprietorships and limited companies with mixed personal-commercial vehicle usage. METI's green mobility incentives are redirecting demand toward electrified models in this segment.
- Startups:Early-stage ventures with limited operating history seeking vehicle finance. Alternative data underwriting is penetrating this underserved tier in Osaka and Tokyo metropolitan zones.
Individual borrowers command the largest share of origination volume; startups are climbing the fastest as fintech platforms reduce traditional barriers.
Repayment Tenure:
Volume distribution skews toward medium-term structures that balance monthly affordability with total interest burden.
- Short-Term:Repayment schedules under 36 months with accelerated principal amortization. Premium vehicle purchasers in urban prefectures select this structure to minimize interest expense.
- Medium-Term:Three-to-seven year amortization aligning with standard vehicle ownership cycles. This structure dominates mass-market origination across all major metropolitan areas.
- Long-Term:Extended schedules exceeding seven years with lower monthly obligations. Rural prefectures exhibit higher uptake as borrowers prioritize cash flow preservation.
- Flexible Tenure:Adjustable repayment periods with step-up or step-down payment options. Subscription-to-ownership pathways are embedding this structure for younger cohorts.
Medium-term structures carry the majority of outstanding balance; flexible tenure options are gaining share fastest among digital-native borrowers.
Interest Rate Type:
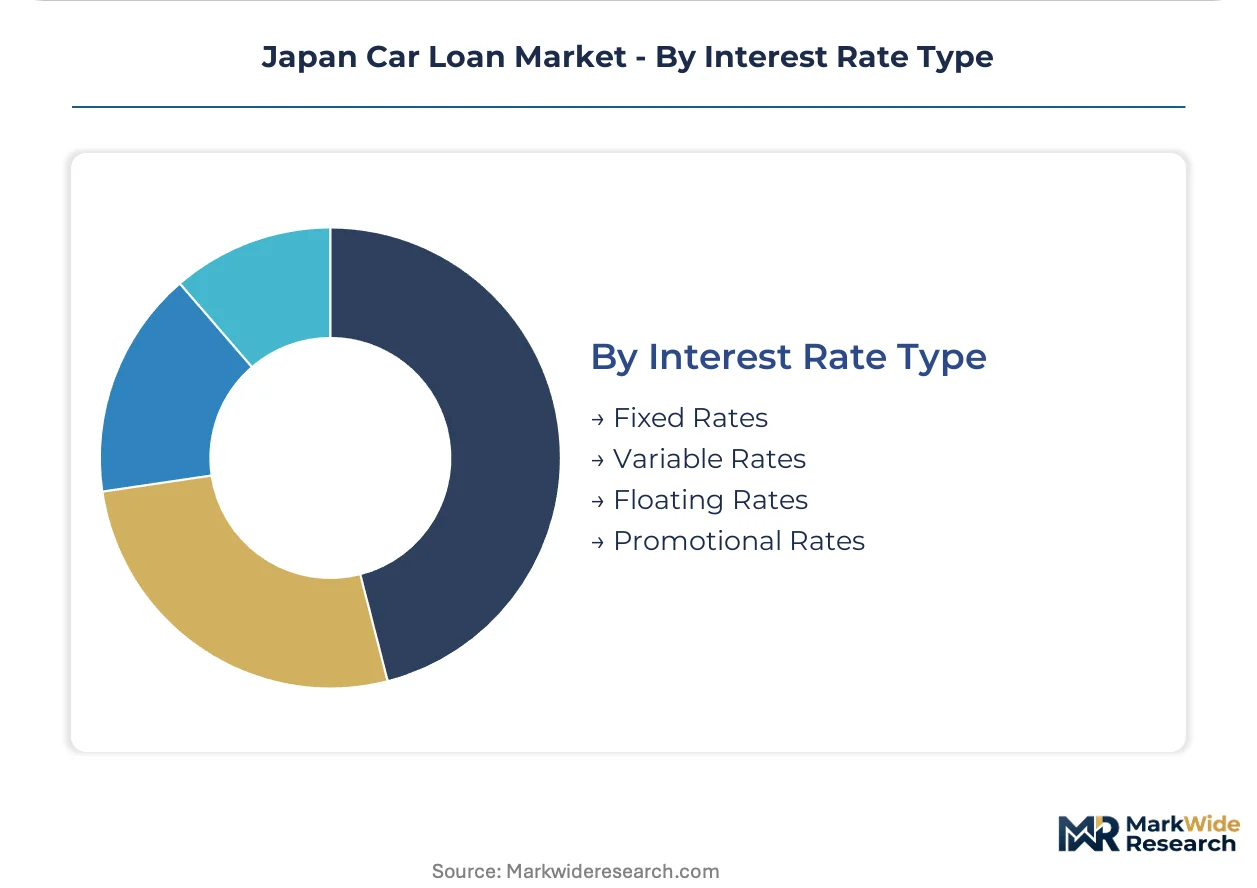
Margin compression in fixed-rate products is driving product innovation around hybrid and promotional structures.
- Fixed Rates:Locked interest charges throughout loan duration eliminating payment uncertainty. Risk-averse households in the Greater Tokyo Area prefer this predictability despite higher initial rates.
- Variable Rates:Benchmark-linked pricing adjusting with Bank of Japan policy shifts. Rate-sensitive applicants in Osaka Prefecture accept payment volatility for front-loaded affordability.
- Floating Rates:Hybrid structures with initial fixed period converting to variable adjustment. This product bridges borrower preferences in transitional rate environments.
- Promotional Rates:Subsidized or zero-interest offers tied to manufacturer sales campaigns. Captive finance arms deploy these instruments to accelerate inventory turnover.
Fixed-rate products retain the dominant share of outstanding portfolio; promotional rate structures are expanding most quickly through embedded finance partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Special Zones for Structural Reform function as concentrated laboratories for auto finance innovation, accelerating digital lending pilots and green vehicle subsidy integration that subsequently diffuse to national markets.
Greater Tokyo Area
Individual borrowers dominate origination volume as smartphone-native comparison platforms aggregate rate offers across captive, bank, and credit union channels. METI's green mobility incentives redirect credit flows toward battery-electric models in this corridor. Digital underwriting platforms in Tokyo compress approval cycles from days to hours, establishing the benchmark for nationwide efficiency targets.
Osaka Prefecture
Established professionals with stable income documentation drive demand for unsecured credit instruments. The Financial Services Agency's interest rate caps constrain pricing flexibility on subprime segments here. Alternative data underwriting penetrates underserved startup tiers in the metropolitan zone, expanding accessibility beyond traditional employment documentation.
Aichi Prefecture
Commercial fleet operators favor lease financing structures for vehicle procurement amid electrification mandates. Manufacturers in this industrial heartland negotiate centralized bulk rate arrangements for executive automobile programs. Zero-interest municipal supplements for commercial EV adoption pilot here, with local government co-guarantees de-risking fleet finance origination.
Kyushu
Rural prefectures exhibit higher uptake of long-term repayment schedules as borrowers prioritize cash flow preservation over total interest minimization. Demographic contraction constrains first-time borrower formation in this region. Regional banks deploy cloud-native platforms to match megabank efficiency, though legacy core system integration erodes projected automation gains.
Hokkaido
Accelerating loan book runoff characterizes this northern prefecture as younger cohorts migrate to urban centers. Flexible tenure options with step-up or step-down payment structures gain traction among residual populations. JIS standardized residual value assessments deepen secondary market liquidity, improving secured loan risk-adjusted returns despite shrinking addressable demand.
Japan Car Loan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's auto finance sector, creating a tiered structure where scale advantages clash with agility premiums. Captive finance arms leverage manufacturer ties to anchor dealer-channel distribution, while independent lenders pursue digital differentiation to circumvent physical network requirements. Three archetypes dominate: bank-affiliated diversified lenders, manufacturer-captive specialists, and fintech-enabled digital platforms. Competitive intensity concentrates around embedded finance partnerships and subscription-to-ownership product architectures as primary vectors for customer acquisition.
Among bank-affiliated diversified lenders, Mitsubishi UFJ Lease & Finance and Sumitomo Mitsui Trust Bank exemplify the tier where corporate and retail product breadth intersects with digital underwriting capability. Toyota Financial Services occupies a position within the captive finance archetype, representing manufacturer-anchored distribution without physical dealership expansion requirements. These three entities anchor the competitive structure, with each sitting within distinct strategic postures that shape portfolio composition and origination channel economics.
| Leading Market Players |
|---|
| Orient Corporation |
| SURUGA bank Ltd |
| Toyota Financial Services |
| Mitsubishi UFJ Lease & Finance |
| MARUHAN Japan Bank Lao Co., Ltd |
| Honda Finance |
| Bank of Kyoto, Ltd |
| Sumitomo Mitsui Trust Bank |
| Nissan Motor Acceptance Corporation |
| Others |
Pricing and Supply Chain Analysis
API-connected income verification systems are collapsing loan approval timelines from days to hours while simultaneously compressing origination cost structures and redistributing pricing power toward digital-first lenders with cloud-native infrastructure. This technological shift simultaneously elevates operational efficiency and concentrates margin advantage among platforms with scale economies in automated underwriting.
Pricing Analysis
Short lead-time approvals command premium pricing as borrowers prioritize speed over rate minimization in the Greater Tokyo Area. The dominant structure stratifies across premium digital-express tiers, standard branch-mediated products, and economy-focused used-vehicle programs. Price differentiation hinges on credit bureau depth and documentation automation level. Cost compression in subprime segments is intensifying because FSA interest rate caps constrain pricing flexibility. Rate-sensitive applicants in Osaka Prefecture exhibit highest price sensitivity, while risk-averse households in Aichi accept premium fixed-rate predictability.
Supply Chain Analysis
Regional distribution centers in the Greater Tokyo Area, Osaka Prefecture, and Aichi Prefecture anchor hub-and-spoke patterns for vehicle collateral valuation and documentation processing. Japan's auto finance supply chain draws from domestic banking infrastructure, cloud computing services, and third-party credit data providers. Semiconductor supply disruptions and legacy core system technical debt create single-source vulnerability in regional bank digital transformation. Distribution runs through captive finance arms, independent bank branches, and embedded finance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's car loan market sits in a technology-transition phase where AI-powered underwriting platforms are displacing legacy branch-dependent origination workflows. Digital-native comparison aggregators are reshaping borrower acquisition economics.
For Market Incumbents: Cement dealer-channel exclusivity through embedded finance API integration that locks inventory-linked origination workflows. Expand captive financing data moats by integrating vehicle telematics into dynamic pricing models. FSA interest rate caps threaten subprime profitability; vertical integration into residual value forecasting services preserves margin through ancillary revenue streams.
For New Entrants and Emerging Players: Automotive marketplace platforms represent the most penetrable channel partner type for white-label lending partnerships. Target startup borrowers in Osaka and Tokyo metropolitan zones where alternative data underwriting gaps persist. Pursue subscription-to-ownership product architectures that capture younger cohorts averse to traditional amortization structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by megabank digital transformation programs seeking fintech capability infusion. Long-term viability favors platforms with demonstrated JIS valuation protocol integration and METI green mobility incentive alignment. Watch fleet electrification mandate acceleration as the decisive inflection indicator for lease financing portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Integration | Captive finance arms extend distribution without physical dealership network expansion requirements. |
| AI-Powered Income Verification Deployment | Digital-first lenders penetrate underbanked segments previously excluded from prime rate tiers. |
| Green-Linked Pricing Differentiation | METI carbon-neutral vehicle roadmap mandates compress internal-combustion-only loan product availability. |
| Residual Value Forecasting Investment | JIS standardized assessments deepen secondary market liquidity and improve secured loan risk-adjusted returns. |
| Subscription-to-Ownership Product Launch | Flexible lease-convert structures capture younger borrowers averse to traditional amortization schedules. |
Research Methodology
Document review covered FSA regulatory filings, METI automotive policy directives, JIS valuation standards, and lender annual disclosures, complemented by interviews with auto finance product managers, digital platform engineers, dealership operations directors, and credit risk officers. Secondary validation drew from Bank of Japan monetary policy reports, vehicle registration databases, and prefectural economic statistics. Bottom-up origination volume estimates triangulated against top-down market sizing from banking sector aggregates.
Cross-reference approaches balanced historical origination trajectory analysis against panel input from lending executives across the projection horizon. Segmentation modeling incorporated loan security type, borrower entity classification, repayment tenure profiles, and interest rate sensitivity dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory intervention timing and technology adoption S-curves. Forecast inputs included electrification penetration curves and digital platform market share trajectories.
Several conditions sit outside the modeled scope, including extreme Bank of Japan policy rate movements, abrupt FSA interest rate cap revisions, and semiconductor supply disruption recurrence beyond baseline assumptions. Forecasts reflect documented assumptions about borrower migration patterns and technology diffusion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Machinery Rental and Leasing Market