
 France Car Loan Market | 2026-2036
France Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
France Car Loan Market Insights
Dealer financing networks is reconfiguring how French consumers access vehicle credit, with captive finance arms and independent lenders competing for point-of-sale dominance. BNP Paribas Personal Finance leverages its established retail banking infrastructure to sustain high origination volumes across metropolitan France. Societe Generale anchors its position through integrated automotive partnerships with major dealership groups. Cofidis differentiates via streamlined digital onboarding that reduces approval friction for individual borrowers.
France car loans constitute secured and unsecured credit instruments collateralized by vehicle titles, typically structured with fixed or variable interest rates over durations spanning twelve to eighty-four months, designed to facilitate consumer and commercial vehicle acquisition. The primary commercial purpose centers on enabling mobility asset ownership while generating interest income and fee-based revenue for originating institutions. Secured loans dominate the loan type dimension, reflecting lender preference for collateralized risk and lower provisioning requirements. Fixed rate products anchor the interest rate type category, offering borrowers payment predictability amid ECB monetary policy fluctuations. Dealer financing occupies a concentrated margin pool within the distribution channel segment, capturing origination volume at the point of vehicle transaction.
France's car loan market operates under ECB prudential supervision, complemented by French Prudential Supervision and Resolution Authority (ACPR) consumer protection mandates and EU Consumer Credit Directive harmonization requirements. These frameworks impose affordability assessment standards, cooling-off period obligations, and transparent annual percentage rate disclosure rules that shape product design and lender compliance costs. Stakeholders must monitor evolving ECB rate trajectories and potential EU Green Deal alignment requirements for automotive finance portfolios.
Market Dynamics
France's car loan market is experiencing fundamental reconfiguration as the EU Green Deal's vehicle emission standards redirect credit flows from internal combustion engines toward electric and hybrid powertrains. This regulatory pressure is compressing residual values for conventional vehicles while elevating demand for green financing products across Île-de-France and regional metropolitan centers.
Growth Catalysts
- EU Green Deal alignment:Stricter emission standards are channeling lender capital toward electric vehicle portfolios, creating dedicated green loan products with preferential rate structures for qualifying borrowers.
- Île-de-France commuter density:Parisian metropolitan expansion sustains robust origination volumes as higher disposable incomes and limited public transit coverage drive private vehicle dependency.
- Digital onboarding platforms:Streamlined application workflows reduce approval friction, cutting time-to-funding from days to hours for individual borrowers seeking used vehicle financing.
Market Restraints
- ECB rate volatility:Monetary policy uncertainty compresses net interest margins for fixed-rate products, forcing lenders to reprice portfolios or absorb margin erosion.
- Residual value concentration:French leasing companies face concentrated exposure to diesel vehicle depreciation as secondary market demand collapses under environmental zone restrictions.
- ACPR compliance costs:Affordability assessment mandates and cooling-off period obligations increase operational overhead, particularly for smaller independent finance houses.
Strategic Opportunities
- Auvergne-Rhône-Alpes expansion:Lyon-Grenoble corridor presents underpenetrated origination potential as automotive manufacturing concentration supports stable employment-backed credit demand.
- Battery-as-a-service bundling:Separating electric vehicle battery costs from chassis financing extends loan tenors while reducing monthly payment burdens for price-sensitive segments.
- Occitanie rural electrification:Sparse charging infrastructure creates opportunity for integrated finance-energy packages combining vehicle loans with home charging installation credit.
Industry Challenges
- Data science talent scarcity:Predictive credit scoring for electric vehicle residual values requires specialized modeling expertise that traditional automotive lenders lack in-house.
- Legacy core banking integration:Incumbent institutions struggle to embed real-time vehicle telemetry data into risk monitoring frameworks without wholesale system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Car Loan Market |
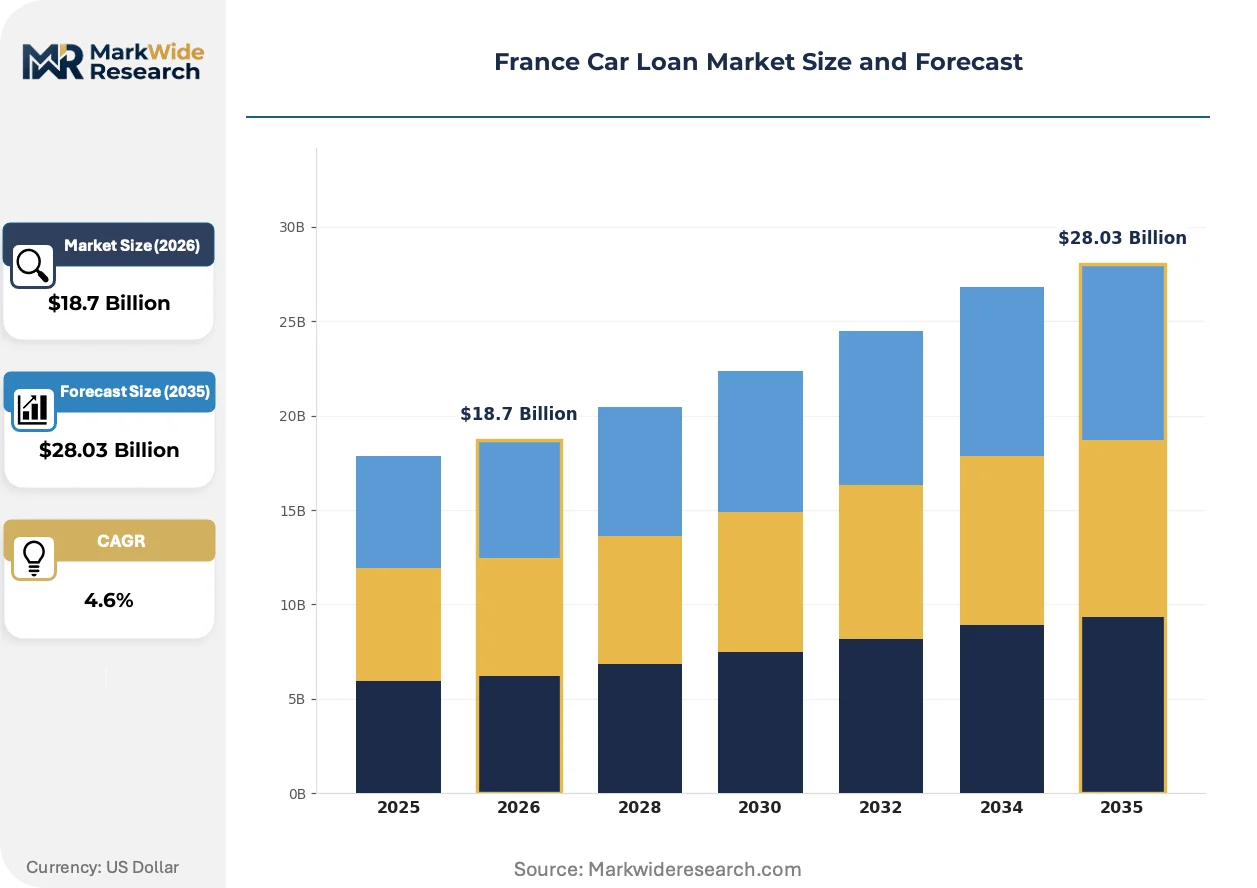
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Personal Loans, Dealer Financing Customer Type: Individual Borrowers, Business Clients, Fleet Operators, Commercial Buyers Loan Duration: Short-Term, Medium-Term, Long-Term, Flexible Terms Interest Rate Type: Fixed Rate, Variable Rate, Adjustable Rate, Promotional Rates |
| Companies Covered | Credit Agricole, Societe Generale, BNP Paribas Personal Finance, Banque Populaire, Cofidis, Cetelem, Cofinoga, Floa Bank, Younited Credit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Car Loan Market Trends and Innovations
Digital origination platforms are compressing approval cycles from days to minutes across French automotive finance. This acceleration is rendering obsolete paper-based verification workflows and reshaping competitive advantage toward API-first infrastructure.
Embedded finance APIs are rendering obsolete the traditional dealership referral model. Captive finance arms at Stellantis and Renault are deploying white-label lending interfaces directly into online vehicle configurators, capturing borrowers before physical showroom visits. This convergence of automotive retail and banking infrastructure is compressing customer acquisition costs while elevating retention rates through integrated servicing portals.
The EU Green Deal's delegated act on sustainable finance taxonomy is reclassifying automotive credit exposure. Lenders must now document environmental performance of financed vehicles to qualify for preferential capital treatment under ECB guidance. French institutions are responding by embedding carbon intensity metrics into loan pricing engines, with electric vehicle borrowers accessing rate discounts of 50-100 basis points versus comparable internal combustion financing.
Subscription mobility models are fragmenting traditional ownership finance demand. Younger borrowers in Paris and Lyon increasingly prefer flexible vehicle access contracts bundling insurance, maintenance, and mileage allowances over fixed-term loans. This behavioral pivot is forcing lenders to develop residual risk products supporting fleet-based subscription providers rather than individual retail borrowers.
France Car Loan Market Segmentation
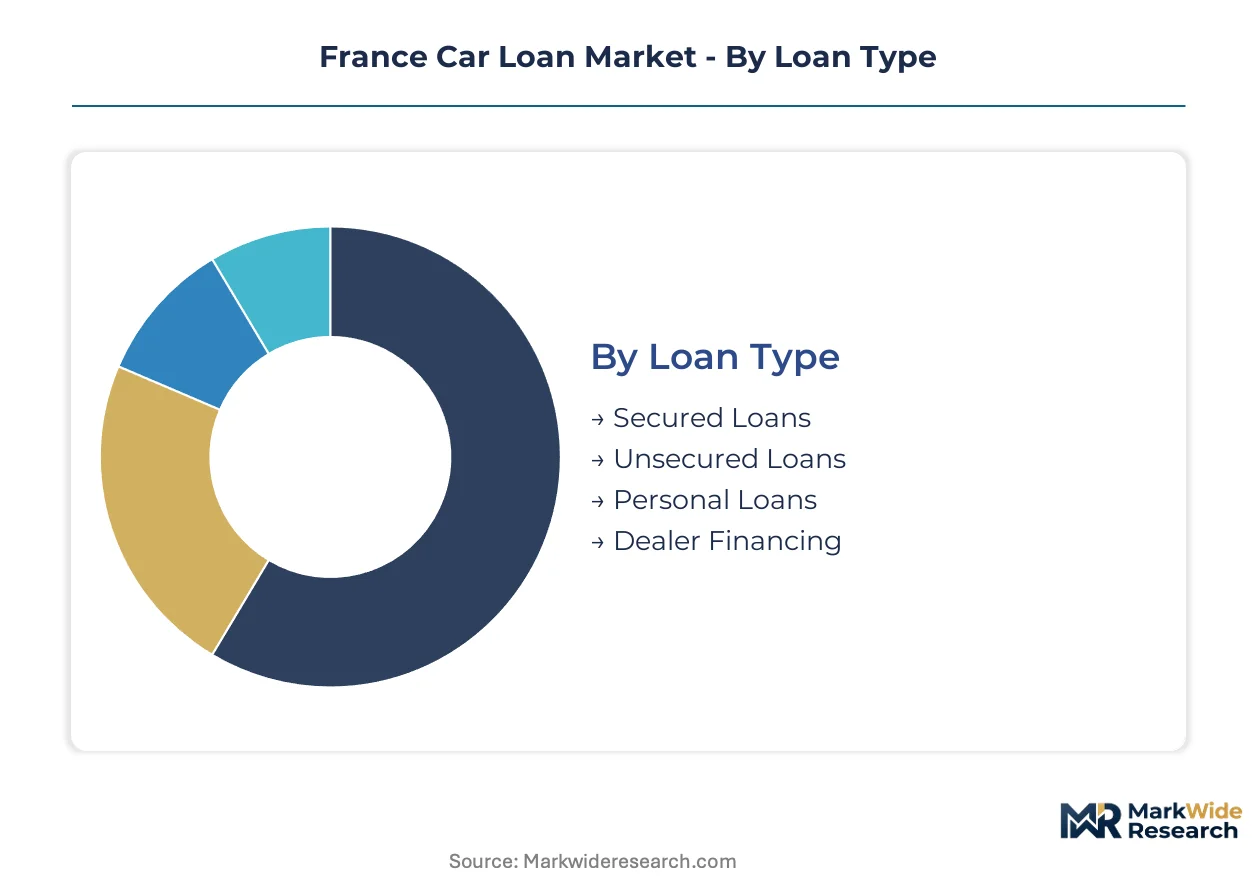
Segmentation in France's car loan market reveals how lenders structure products around collateral risk, borrower profiles, and duration preferences. These divisions shape pricing engines, provisioning requirements, and distribution channel investments across the Île-de-France corridor and regional metropolitan centers.
Loan Type:
Mature collateralization structures dominate origination volumes, though emerging unsecured formats are gaining traction among digital-native borrowers.
- Secured Loans:Vehicle titles serve as primary collateral, enabling lower interest rate spreads and reduced capital charges under ECB prudential frameworks. Île-de-France dealerships originate concentrated volumes of these products for new electric vehicle acquisitions.
- Unsecured Loans:Credit decisions rely on borrower credit scoring without asset backing, commanding rate premiums of 150-300 basis points above secured alternatives. Demand concentrates among Parisian professionals purchasing premium used vehicles where title transfer complexity deters collateralization.
- Personal Loans:General-purpose credit instruments applied to vehicle acquisition without specific asset linkage, typically carrying shorter tenors and higher monthly payments.
- Dealer Financing:Point-of-sale credit products originated through captive finance arms and independent lender partnerships, capturing borrowers at maximum purchase intent moments.
Secured loans handle the majority of throughput; dealer financing is expanding most quickly as embedded finance APIs penetrate online vehicle configurators.
Customer Type:
Cost tier differentiation separates mass-market individual products from bespoke commercial facilities with customized servicing structures.
- Individual Borrowers:Retail consumers seeking personal vehicle acquisition, typically financing single units through standardized application workflows with automated income verification.
- Business Clients:Corporate entities financing director and employee vehicles, requiring fleet management integration and consolidated billing capabilities that smaller lenders cannot support.
- Fleet Operators:Multi-vehicle financing for logistics, rental, and service companies, structured with residual value guarantees and seasonal payment flexibility. Auvergne-Rhône-Alpes manufacturing concentration sustains stable demand from commercial vehicle deployers.
- Commercial Buyers:Sole traders and small enterprises acquiring vehicles for revenue-generating activities, often blending personal and business credit profiles in underwriting assessments.
Individual borrowers anchor origination volume; fleet operators are climbing the fastest as subscription mobility models fragment traditional ownership demand.
Loan Duration:
Volume distribution skews toward medium tenors that balance affordability with residual value risk containment.
- Short-Term:Twelve to twenty-four month structures for used vehicle purchases and lease buyouts, minimizing interest expense for creditworthy borrowers with liquidity flexibility.
- Medium-Term:Thirty-six to sixty month products dominating new vehicle finance, aligning depreciation curves with payment schedules. This tenor captures peak demand across all French regions.
- Long-Term:Seventy-two to eighty-four month extensions for electric vehicle battery-inclusive financing, reducing monthly burdens as sticker prices exceed internal combustion equivalents.
- Flexible Terms:Adjustable duration products with early repayment options and payment holiday provisions, appealing to gig economy workers with irregular income patterns.
Medium-term structures handle the majority of throughput; flexible terms are gaining share fastest among younger borrowers in Lyon and Paris.
Interest Rate Type:
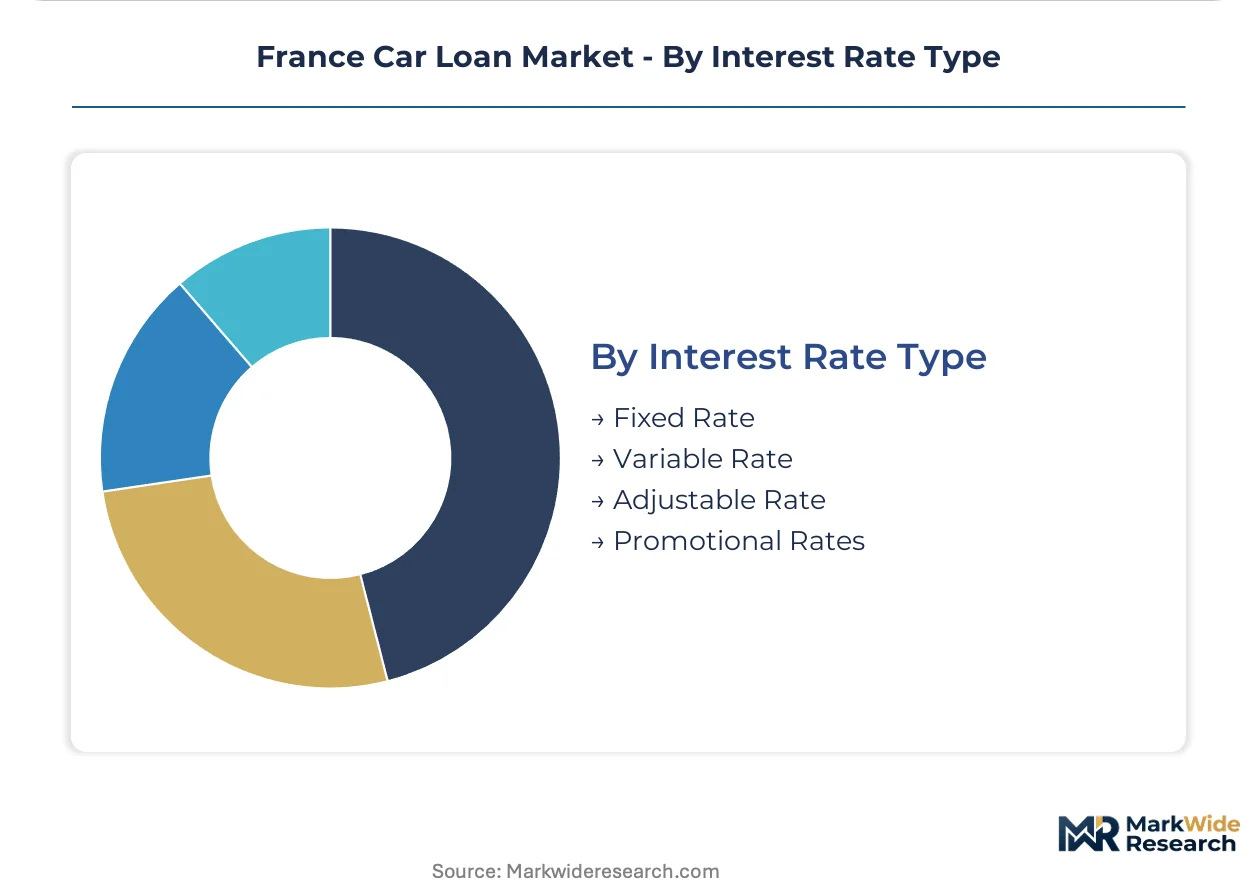
Margin concentration favors fixed-rate products that transfer ECB policy risk to lender balance sheets in exchange for borrower payment certainty.
- Fixed Rate:Predetermined interest costs throughout the loan life, insulating borrowers from ECB refinancing rate volatility. These products anchor French retail automotive finance.
- Variable Rate:Interest costs indexed to ECB reference rates or Euribor, transferring monetary policy risk to borrowers while offering initial rate discounts. Demand concentrates among financially sophisticated commercial buyers.
- Adjustable Rate:Hybrid structures with fixed initial periods transitioning to variable terms, attempting to balance early payment predictability with lender margin protection.
- Promotional Rates:Subsidized financing offered by captive finance arms to move vehicle inventory, often requiring manufacturer buy-downs that compress net interest margins.
Fixed rate products handle the majority of throughput; promotional rates are expanding most quickly as Stellantis and Renault deploy zero-percent campaigns to defend market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's national incentive framework for electric vehicle acquisition is redirecting credit demand toward specific metropolitan corridors where charging infrastructure and household incomes align with green loan eligibility criteria.
Île-de-France
Parisian commuter density and constrained public transit coverage sustain concentrated origination volumes across the capital region. The ACPR's affordability assessment mandates shape product design for high-income borrowers financing premium electric models. La Défense and inner-ring suburbs generate disproportionate demand for medium-term secured loans tied to battery-inclusive vehicle purchases.
Auvergne-Rhône-Alpes
Lyon-Grenoble automotive manufacturing concentration supports stable employment-backed credit demand from industrial workforce segments. EU Green Deal emission standards accelerate fleet electrification among regional logistics operators. Saint-Étienne and Chambéry sub-markets exhibit rising penetration of flexible-term products accommodating seasonal income patterns in tourism-dependent sectors.
Provence-Alpes-Côte d'Azur
Tourism-driven seasonal employment creates distinctive demand for payment holiday provisions and adjustable-duration structures. Marseille's port logistics sector generates commercial vehicle financing volume with residual value guarantee requirements. Nice-Cannes corridor shows elevated unsecured loan uptake among service professionals acquiring premium used vehicles.
Hauts-de-France
Industrial restructuring in Lille and Valenciennes is compressing traditional manufacturing-backed credit demand while elevating gig economy borrower segments. Regional low-emission zone expansion accelerates diesel vehicle trade-in cycles toward electric replacement financing. Douai automotive cluster proximity sustains captive finance arm partnerships with major dealership networks.
Occitanie
Rural electrification gaps create structural barriers to electric vehicle adoption despite national incentive availability. Toulouse aerospace employment concentration supports stable prime borrower segments for conventional secured products. Montpellier and Perpignan sub-markets show emerging demand for integrated finance-energy packages combining vehicle loans with residential charging infrastructure credit.
France Car Loan Market Competitive Landscape
On the supply side, the industry is moderately consolidated around established banking groups with captive finance specialization and emerging digital-native challengers. Three strategic archetypes dominate: universal bank personal finance divisions leveraging retail infrastructure, independent consumer credit specialists emphasizing digital velocity, and manufacturer-captive lenders integrating point-of-sale distribution. Competitive dynamics center on embedded finance API deployment and green loan product differentiation rather than rate-based confrontation.
Within the universal bank tier, BNP Paribas Personal Finance, Societe Generale, and Credit Agricole represent the incumbent positioning archetype. These institutions anchor market presence through branch network origination capacity and established dealership relationships. Cofidis and Younited Credit exemplify the digital-native challenger model, occupying positions defined by streamlined onboarding workflows and reduced approval friction. The competitive terrain rewards institutions capable of embedding carbon-intensity metrics into pricing engines while maintaining compliance with ACPR consumer protection mandates.
| Leading Market Players |
|---|
| Credit Agricole |
| Societe Generale |
| BNP Paribas Personal Finance |
| Banque Populaire |
| Cofidis |
| Cetelem |
| Cofinoga |
| Floa Bank |
| Younited Credit |
| Others |
Pricing and Supply Chain Analysis
German captive finance arms anchor upstream pricing power in France's automotive credit ecosystem, concentrating margin pools at the point-of-sale origination tier where Stellantis and Renault deploy zero-percent promotional campaigns. This concentration compresses net interest margins for independent lenders while elevating acquisition cost differentials across Île-de-France dealership networks.
Pricing Analysis
Volume-discount tiering structures dominate French car loan pricing, with captive finance arms offering 50-100 basis point rate reductions for electric vehicle borrowers against comparable internal combustion financing. Price differentiation hinges on carbon intensity metrics embedded in ECB sustainable finance taxonomy compliance and borrower credit scoring tiers. Pricing pressure stems from ECB monetary policy volatility compressing fixed-rate product margins. Individual borrowers in Paris exhibit lowest price sensitivity due to higher disposable incomes, while gig economy workers in Lyon and Marseille drive demand for flexible-term products with rate premiums.
Supply Chain Analysis
Supplier-financing facilities extended by BNP Paribas Personal Finance and Societe Generale anchor working capital flows across French dealership networks, enabling inventory carrying capacity at point-of-sale origination nodes. Geographic supply concentration draws from Germany, Spain, and Belgium for vehicle assembly components and captive finance technology platforms. Raw material dependencies center on lithium-ion battery cells, semiconductor chips, and aluminum chassis inputs. Single-source vulnerability concentrates in battery supply agreements with Asian manufacturers. Distribution runs through embedded finance APIs penetrating online vehicle configurators before physical showroom visits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
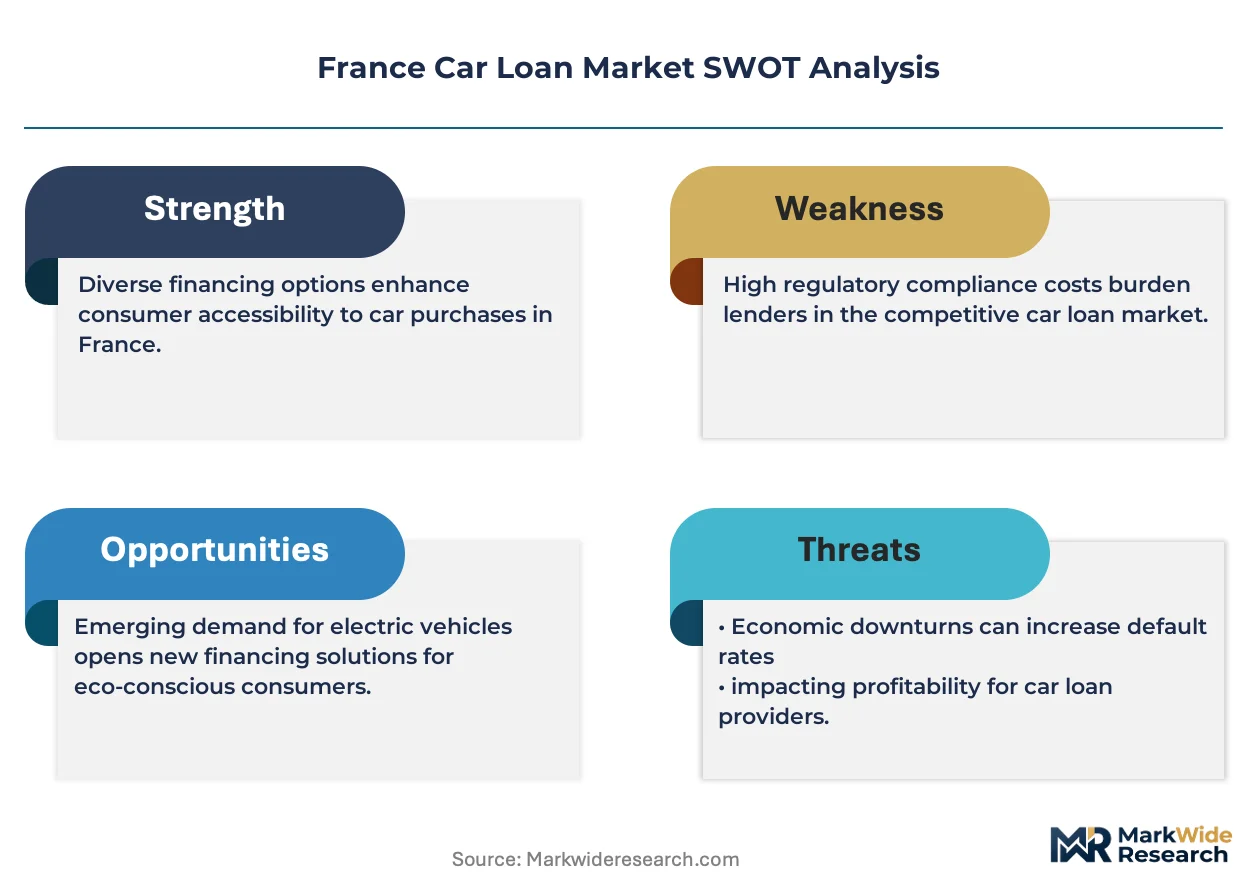
France's car loan market sits in early-cycle expansion as EU Green Deal emission standards redirect credit flows toward electric vehicle portfolios, creating dedicated green loan products with preferential rate structures that expand addressable penetration among environmentally motivated borrowers.
For Market Incumbents: Pre-empt digital-native challengers by accelerating API-first infrastructure deployment that compresses approval cycles from days to minutes. Defend against Cofidis and Younited Credit's streamlined onboarding velocity through integrated automotive partnerships with major dealership groups. Prioritize vertical integration into battery-as-a-service bundling capabilities that extend loan tenors while reducing monthly payment burdens. For New Entrants and Emerging Players: Establish a beachhead in Auvergne-Rhône-Alpes corridor where Lyon-Grenoble automotive manufacturing concentration supports underpenetrated origination potential among industrial workforce segments. Target Occitanie rural electrification gaps with integrated finance-energy packages combining vehicle loans with home charging installation credit. Deploy white-label lending interfaces through regional credit union partnerships to bypass established dealership network control. For Investors and Strategic Acquirers: Capital is best deployed toward digital-native challengers with proven API infrastructure and green loan product differentiation capabilities rather than legacy universal bank personal finance divisions burdened by branch network overhead. Long-term viability over the next decade hinges on carbon-intensity metric integration into pricing engines and real-time vehicle telemetry data embedding into risk monitoring frameworks. Monitor ECB rate trajectory stabilization as inflection indicator for fixed-rate product margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Green Loan Product Launch | EU Green Deal taxonomy compliance unlocks preferential ECB capital treatment for qualifying electric vehicle portfolios. |
| Embedded Finance API Integration | White-label lending interfaces in Stellantis and Renault online configurators capture borrowers before showroom visits. |
| Battery-as-a-Service Bundling | Separating battery costs from chassis financing extends tenors while reducing monthly burdens for price-sensitive segments. |
| Regional Expansion in Auvergne-Rhône-Alpes | Lyon-Grenoble manufacturing concentration supports stable employment-backed credit demand from logistics operators. |
| Charging Infrastructure Partnership | Integrated finance-energy packages in Occitanie address rural electrification gaps constraining electric vehicle adoption. |
Research Methodology
Initial hypotheses were tested against primary input from captive finance arm executives, dealership operations managers, ACPR regulatory affairs specialists, and fintech platform engineers, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including ECB prudential guidance documents, ACPR consumer protection circulars, EU Consumer Credit Directive implementation reports, and vehicle registration databases from IHS Markit. Bottom-up origination volume modeling triangulated against top-down macroeconomic scenario analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning loan type, customer category, duration preference, interest rate structure, and regional adoption patterns. CAGRs were derived through regression analysis against ECB policy rate trajectories and electric vehicle penetration curves. Industry-specific forecast inputs incorporated EU Green Deal delegated act implementation timelines and residual value depreciation models for diesel vehicle exposure.
Stress conditions across ECB refinancing rate volatility, electric vehicle battery cost curves, and ACPR compliance cost escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and technological adoption curves. Macroeconomic contraction, accelerated EU emission standard tightening, or breakthrough battery technology cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Used Car Financing Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Microfinance Market