
 North America Motorcycle Loan Market | 2026-2036
North America Motorcycle Loan Market Size, Share, and Industry Trends Forecast 2026-2036
North America Motorcycle Loan Market Insights
Aluminum is rebalancing frame economics as manufacturers substitute steel to reduce vehicle weight and improve fuel efficiency. Harley-Davidson Financial Services leverages its captive finance model to sustain deep integration with dealer networks across the United States. Bank of America Corporation anchors its motorcycle lending through broad retail branch penetration and digital origination platforms. Ally Financial Inc. differentiates via flexible lease structures that compete with traditional installment products.
A motorcycle loan is a secured or unsecured credit instrument collateralized by a powersport vehicle, typically carrying terms from 24 to 84 months with annual percentage rates indexed to borrower credit tiers and vehicle depreciation curves. Its primary commercial purpose is to bridge the gap between manufacturer sticker prices and consumer liquidity, enabling unit sales while generating interest income for originators. Secured loans dominate portfolio composition due to lower loss severity from recoverable collateral, while leasing exhibits the fastest structural expansion as riders prioritize access over ownership. First-time buyers concentrate in the subprime tier where promotional rate products attract entry-level purchasers, though experienced riders command the deepest margin pools through prime-rate refinancing and accessory bundling.
The Consumer Financial Protection Bureau shapes underwriting standards through enforcement of fair lending statutes, while the Office of the Comptroller of the Currency governs national bank capital reserves against motorcycle receivables. State-level usury ceilings in Texas and California create a fragmented compliance map that originators must navigate across jurisdictions. Stakeholders should monitor how the Federal Reserve's benchmark rate trajectory alters promotional financing programs and borrower qualification thresholds.
Market Dynamics
The Consumer Financial Protection Bureau's intensifying scrutiny of subprime auto lending is compressing risk tolerance across motorcycle originators, forcing portfolio rebalancing toward prime tiers and secured collateral structures.
Growth Catalysts
- Recreational Touring Rider Expansion:This buyer segment is accelerating loan origination volumes in year-round riding states, particularly Texas and Florida, where extended seasons sustain higher utilization rates.
- CFPB Fair Lending Enforcement:Standardized underwriting protocols are reducing discrimination exposure and expanding addressable borrower pools through algorithmic qualification models.
- Aluminum Frame Substitution:Manufacturers replacing steel with aluminum are lowering vehicle weight, improving fuel efficiency, and extending product lifecycles that collateralize longer loan terms.
Market Restraints
- Prime-Borrower Concentration Risk:Portfolio migration toward super-prime tiers is compressing net interest margins and reducing yield spreads across originator balance sheets.
- State Usury Fragmentation:Divergent interest rate ceilings between Texas and California create compliance arbitrage complexity and limit national product standardization.
- Electric Motorcycle Depreciation Uncertainty:Unproven residual value curves for battery-powered units are elevating loss severity assumptions and tightening advance rates.
Strategic Opportunities
- Access-Over-Ownership Leasing:Flexible lease structures are capturing riders who prioritize usage rights and upgrade flexibility over traditional installment ownership.
- Accessory Bundling Finance:Prime-tier refinancing products combined with gear and service packages are deepening customer lifetime value and cross-sell penetration.
- Digital Origination Platforms:Branchless application workflows are reducing acquisition costs and expanding reach into rural markets underserved by physical dealer networks.
Industry Challenges
- Subprime Underwriting Expertise Deficit:Originators face talent scarcity in alternative data modeling and behavioral risk scoring for thin-file borrowers.
- Federal Reserve Rate Volatility:Promotional financing program profitability swings with benchmark rate trajectory, requiring dynamic pricing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Motorcycle Loan Market |
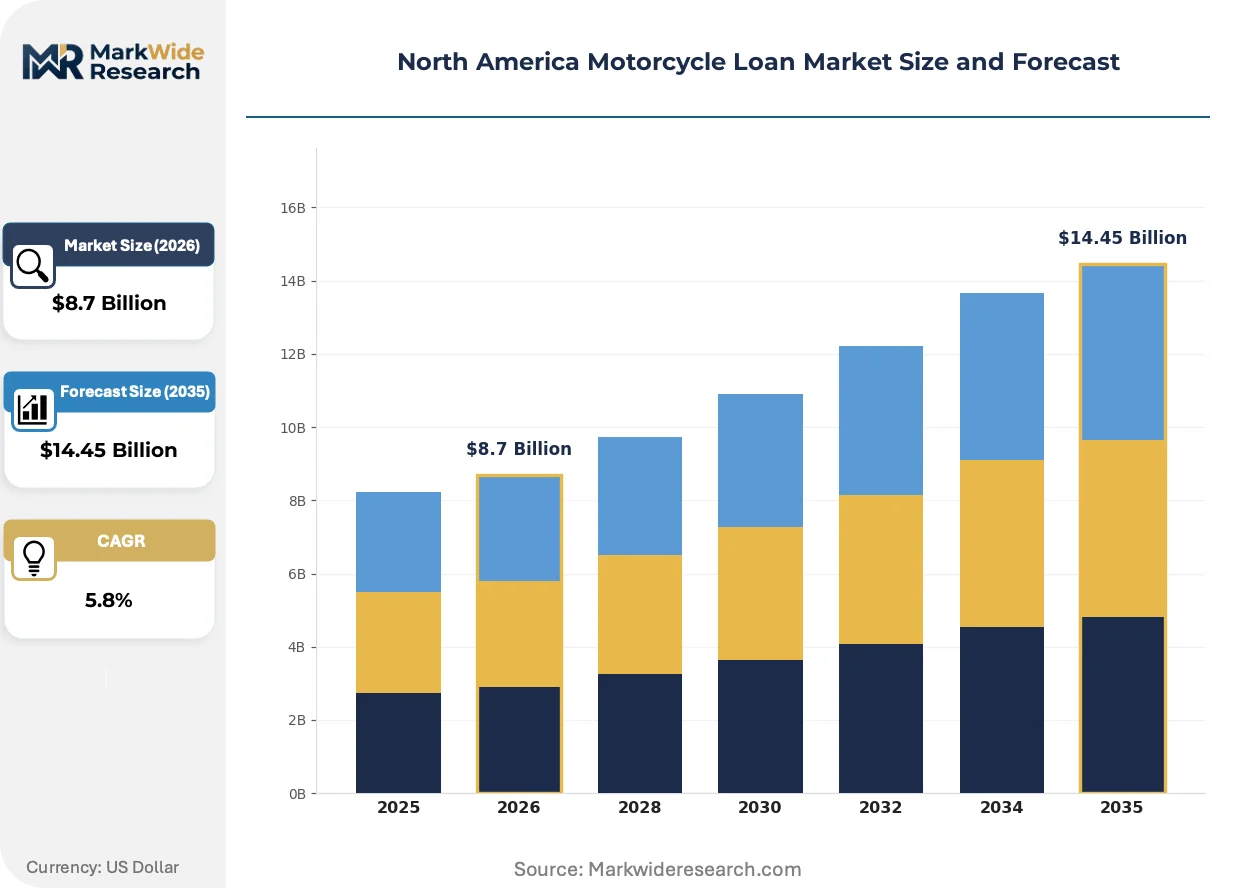
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Leasing, Installment Loans Customer Type: First-Time Buyers, Experienced Riders, Dealerships, Rental Companies Loan Tenure: Short-Term, Medium-Term, Long-Term, Seasonal Interest Rate Type: Fixed Rate, Variable Rate, Promotional Rate, Adjustable Rate |
| Companies Covered | The Kawasaki Motors Corp., U.S.A., Bank of America Corporation, Harley-Davidson Financial Services, TD Auto Finance, JPMorgan Chase & Co., American Honda Finance Corporation, Wells Fargo & Company, Ally Financial Inc., Yamaha Motor Finance Corporation, U.S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Motorcycle Loan Market Trends and Innovations
Digital origination infrastructure is fundamentally restructuring how motorcycle credit is sourced, priced, and serviced across North American markets. Three convergent developments are compressing traditional intermediation layers.
Artificial intelligence-driven credit decisioning is overtaking legacy FICO-centric underwriting models in subprime tier qualification. Lenders deploying machine learning algorithms assess alternative data streams including utility payment histories and gig-economy income verification. Recreational touring riders with non-traditional employment profiles are accessing financing previously gated by bureau-score thresholds.
The Consumer Financial Protection Bureau's 2023 updated guidance on disparate impact testing is compelling originators to document algorithmic fairness across protected classes. Lenders must now maintain audit trails for automated underwriting decisions affecting subprime applicant pools. Texas and California originators are investing in explainable AI frameworks to satisfy examination protocols.
Subscription-based vehicle access is displacing conventional installment purchase patterns among urban millennial and Gen-Z rider segments. Riders in California metropolitan corridors increasingly favor monthly payment structures bundling insurance, maintenance, and upgrade privileges. Dealer finance and insurance departments are reconfiguring compensation structures to capture recurring revenue streams rather than front-loaded origination fees.
North America Motorcycle Loan Market Segmentation
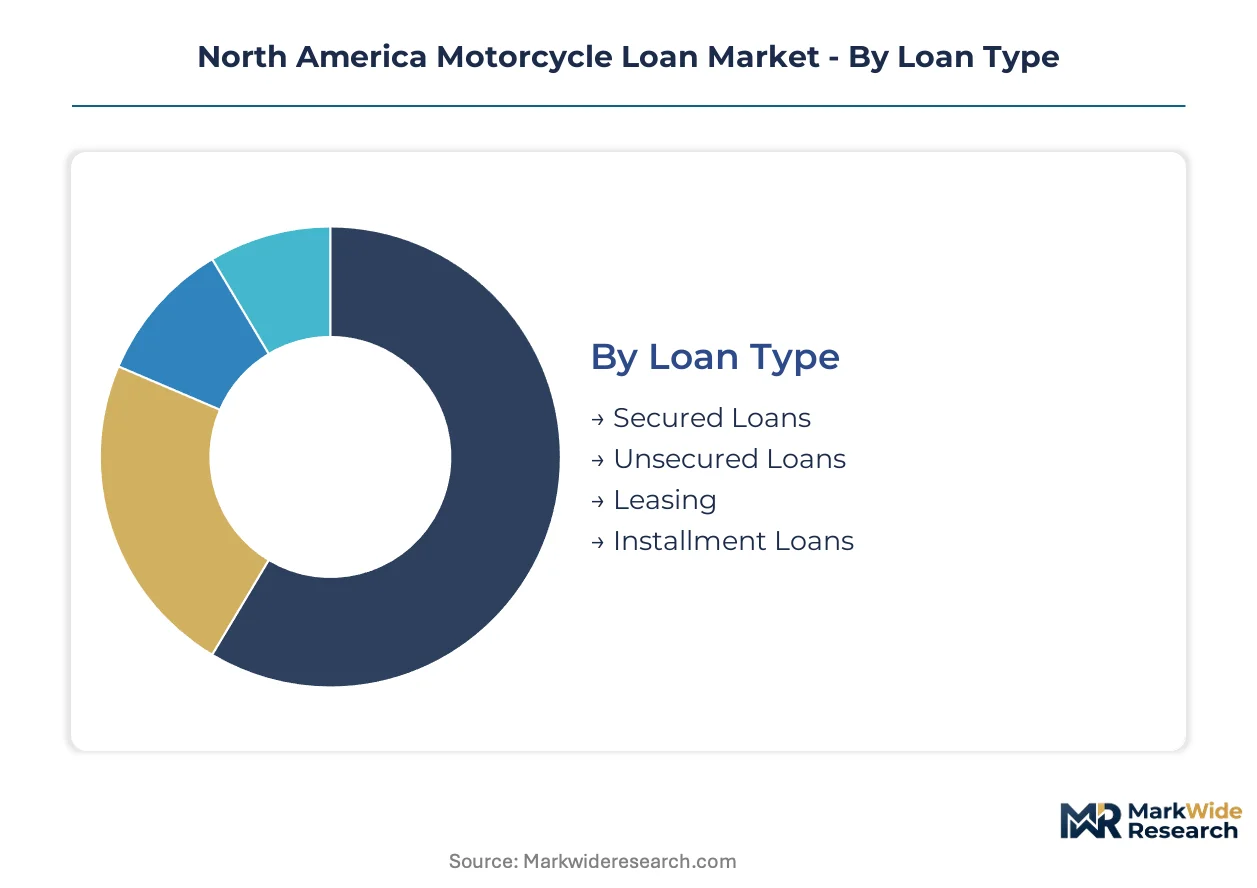
Segmentation in motorcycle lending reveals how collateral structures, borrower experience levels, and rate mechanisms distribute risk and return across originator portfolios. Lenders calibrate product design to match depreciation curves with repayment schedules while navigating divergent state regulatory environments.
Loan Type:
Upgrade cycles and replacement patterns vary sharply by how title transfers, creating distinct residual risk profiles for originators.
- Secured Loans:Collateralized by the vehicle title, these instruments carry lower loss severity due to recoverable asset backing. Demand concentrates in Texas and Florida where year-round riding sustains higher collateral utilization rates and stronger recovery values at auction.
- Leasing:Monthly payment structures bundle usage rights without ownership transfer, attracting riders prioritizing access over long-term equity. California metropolitan corridors show fastest adoption among millennial and Gen-Z segments seeking upgrade flexibility.
- Unsecured Loans:Signature-based credit extensions rely solely on borrower creditworthiness without vehicle collateral. Thin-file applicants in subprime tiers access these products where traditional secured qualification fails.
- Installment Loans:Fixed-schedule amortization structures dominate dealer captive finance programs. Harley-Davidson Financial Services leverages deep dealer integration to originate these products at point of sale.
Volume placements concentrate in Secured Loans; the faster expansion belongs to Leasing.
Customer Type:
Cost tier differentiation separates thin-margin acquisition lending from high-yield refinancing and accessory bundling opportunities.
- Experienced Riders:Prime-credit borrowers with established riding histories command deepest margin pools through rate refinancing and gear financing add-ons. This segment drives cross-sell penetration in Bank of America Corporation's branch network.
- First-Time Buyers:Entry-level purchasers concentrate in subprime credit tiers where promotional rate products reduce qualification barriers. Ally Financial Inc. targets this cohort with flexible lease alternatives to traditional installment structures.
- Dealerships:Floorplan financing enables inventory carrying costs for retail networks. Captive finance arms prioritize these relationships to secure origination volume commitments.
- Rental Companies:Fleet acquisition financing supports commercial powersport rental operations in tourist-heavy geographies. Seasonal cash flow patterns require specialized amortization structures.
Revenue concentration sits with Experienced Riders; First-Time Buyers are gaining share fastest through digital origination expansion.
Loan Tenure:
Depreciation velocity and collateral lifecycle dictate optimal matching between term length and vehicle type.
- Medium-Term:36-60 month structures align with mainstream motorcycle depreciation curves and borrower income stability. This bracket dominates conventional sportbike and cruiser financing in prime credit tiers.
- Long-Term:Extended 72-84 month amortization reduces monthly payments for high-displacement touring motorcycles. Recreational touring riders in year-round riding states favor these structures for premium vehicle acquisitions.
- Short-Term:24-36 month rapid amortization suits used vehicle purchases and subprime borrowers rebuilding credit profiles. Higher monthly payments filter for stronger near-term liquidity.
- Seasonal:Balloon structures with concentrated payments during riding months accommodate agricultural and construction workers with irregular income patterns. Texas and Florida originators tailor these products to regional employment cycles.
Application concentration favors Medium-Term structures; Long-Term financing shows steepest expansion trajectory as vehicle prices climb.
Interest Rate Type:
Margin protection and borrower qualification flexibility trade off across rate mechanism selection.
- Fixed Rate:Locked APR throughout the loan term eliminates payment uncertainty for risk-averse borrowers. Prime-tier originators deploy these products when Federal Reserve benchmark rates suggest upward trajectory.
- Promotional Rate:Teaser pricing structures attract subprime and first-time buyer segments through manufacturer-subsidized programs. Loss of subsidy protection elevates originator exposure to rate volatility.
- Variable Rate:Index-tied pricing transfers benchmark rate risk to borrowers while protecting lender margins. Experienced riders with stronger liquidity positions accept these structures for lower initial rates.
- Adjustable Rate:Hybrid mechanisms with initial fixed periods transitioning to variable structures balance acquisition pricing with long-term margin protection. Complex disclosure requirements elevate compliance costs.
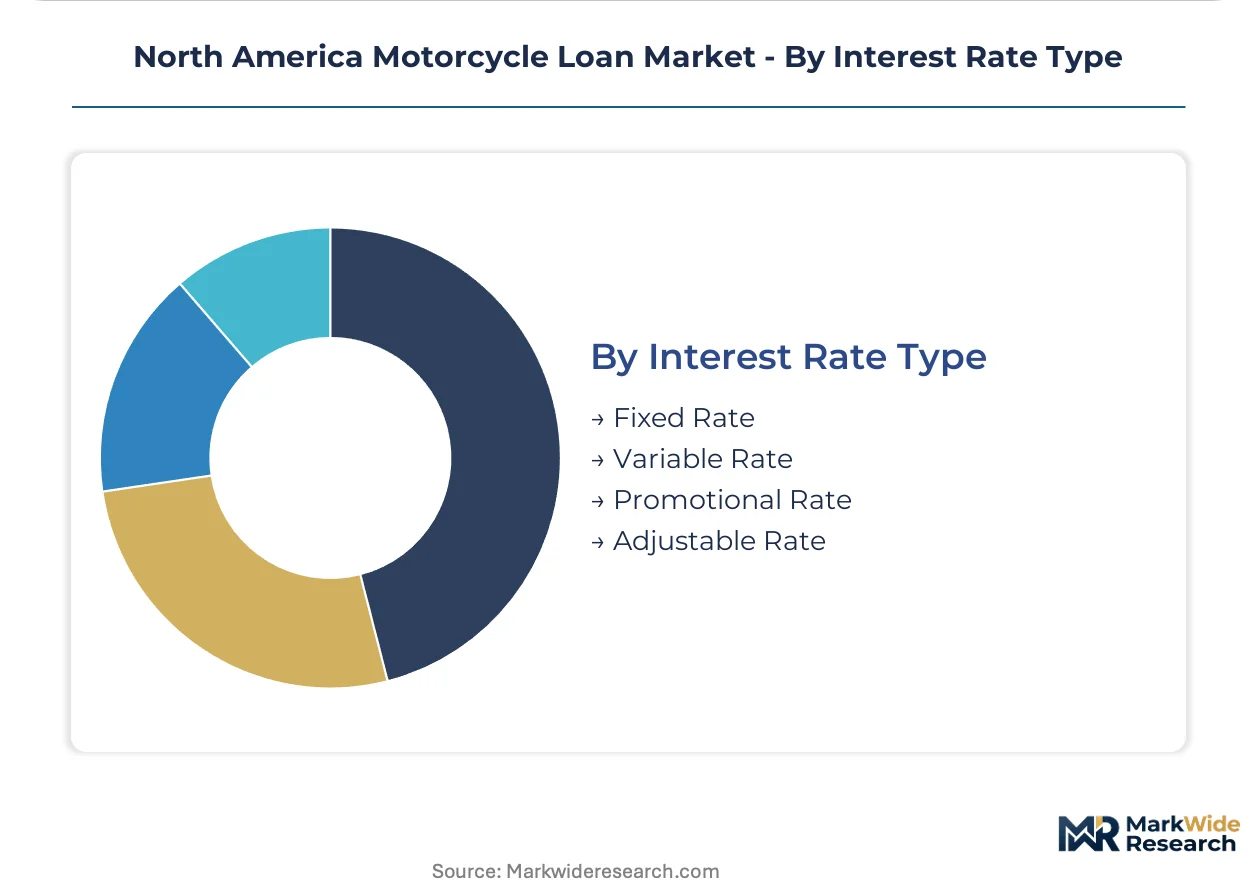
Origination volume clusters in Fixed Rate products; Promotional Rate structures are expanding most quickly through manufacturer captive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Loan origination volumes concentrate in year-round riding states where extended seasons sustain higher collateral utilization and stronger recovery values. Texas, Florida, and California anchor regional demand through distinct borrower demographics and regulatory environments. The Consumer Financial Protection Bureau shapes underwriting standards across all three markets, while state-level usury ceilings create fragmented compliance requirements.
United States
Recreational touring riders and first-time buyers drive origination growth in Texas and Florida, where mild winters extend riding seasons. The Consumer Financial Protection Bureau enforces fair lending statutes and algorithmic fairness requirements through updated 2023 guidance on disparate impact testing. California metropolitan corridors show fastest leasing adoption among millennial and Gen-Z segments seeking subscription-based vehicle access.
California
Electric motorcycle financing faces residual value uncertainty as battery depreciation curves remain unproven, tightening advance rates for originators. State usury ceilings limit interest rate flexibility compared to Texas, forcing product standardization compromises. Los Angeles and San Francisco Bay Area clusters concentrate digital-native borrowers prioritizing flexible lease structures over traditional installment ownership.
Texas
Higher usury thresholds attract subprime lending activity from national originators seeking yield spread expansion. Seasonal balloon structures accommodate agricultural and construction workers with irregular income patterns tied to regional employment cycles. Dallas-Fort Worth and Houston metropolitan areas anchor floorplan financing volumes for dealer inventory carrying costs.
Florida
Retiree and snowbird demographics sustain premium touring motorcycle demand with extended loan tenures reaching 72-84 months. The state's lack of income tax supports disposable income allocation toward powersport vehicle acquisition. Miami and Tampa Bay clusters concentrate tourist-facing rental fleet financing requiring specialized amortization structures.
Canada
Shorter riding seasons compress origination windows into spring and summer months, elevating dealer floorplan financing seasonality. The Office of the Superintendent of Financial Institutions governs national bank capital reserves against motorcycle receivables. Ontario and Quebec manufacturing corridors anchor captive finance operations for US-based manufacturers distributing into Canadian markets.
North America Motorcycle Loan Market Competitive Landscape
Portfolio diversification dominates the current landscape as originators rebalance toward prime tiers and secured collateral structures. The market exhibits tiered consolidation with captive finance arms, national banking networks, and specialized consumer lenders occupying distinct competitive positions. Three strategic archetypes prevail: manufacturer-captive integrators, branch-network deposit banks, and digital-first alternative lenders. M&A activity and technology licensing partnerships represent the dominant competitive moves as firms acquire alternative data modeling capabilities and deploy AI-driven underwriting infrastructure.
Within the captive finance tier, Harley-Davidson Financial Services and American Honda Finance Corporation exemplify deep manufacturer-dealer integration with point-of-sale origination dominance. Bank of America Corporation and JPMorgan Chase & Co. anchor the national banking vector through retail branch penetration and digital platform scale. Ally Financial Inc. occupies a specialized position in flexible lease structures competing with traditional installment products.
| Leading Market Players |
|---|
| The Kawasaki Motors Corp., U.S.A. |
| Bank of America Corporation |
| Harley-Davidson Financial Services |
| TD Auto Finance |
| JPMorgan Chase & Co. |
| American Honda Finance Corporation |
| Wells Fargo & Company |
| Ally Financial Inc. |
| Yamaha Motor Finance Corporation, U.S.A. |
| Others |
Pricing and Supply Chain Analysis
The Consumer Financial Protection Bureau's algorithmic fairness mandates gate qualified supply for originators seeking premium-tier pricing access, as compliance infrastructure investments separate scalable national lenders from regional competitors unable to absorb audit and explainable AI development costs.
Pricing Analysis
Volume concentration in subprime secured loans compresses margins while prime-tier refinancing and accessory bundling commands yield expansion. Pricing stratifies across captive manufacturer programs, bank branch networks, and digital-first alternative lenders based on cost of funds and underwriting sophistication. Promotional rate subsidies from Harley-Davidson Financial Services and American Honda Finance Corporation intensify pricing pressure in entry-level segments. First-time buyers exhibit highest price sensitivity, while experienced riders with prime credit profiles accept premium rates for convenience and bundled service offerings.
Supply Chain Analysis
CFPB certification and state-level usury compliance requirements concentrate qualified origination capacity among national banks and captive finance arms with dedicated legal infrastructure. Funding sources draw from retail deposit bases, securitization markets, and manufacturer balance sheet commitments across the United States, Canada, and select cross-border institutional investors. Single-source vulnerability emerges from dependence on credit bureau data monopolies and legacy loan servicing platforms. Distribution runs through captive dealer networks, direct-to-consumer digital platforms, and third-party lead aggregation services.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subprime underwriting expertise scarcity props pricing power for originators capable of deploying alternative data models, as talent bottlenecks in behavioral risk scoring constrain competitive entry.
For Market Incumbents: Lock in dealer network exclusivity through floorplan financing commitments and point-of-sale technology integration before digital-native competitors achieve scale. Invest in explainable AI audit trail infrastructure to preempt CFPB examination exposure. Acquire alternative data modeling capabilities through targeted technology licensing rather than organic development. For New Entrants and Emerging Players: Enter via unsecured lending products for thin-file gig-economy borrowers in California metropolitan corridors where traditional secured qualification fails. Target first-time buyer segments with subscription-based access models displacing conventional installment ownership. Deploy branchless digital origination to capture rural markets underserved by physical dealer networks. For Investors and Strategic Acquirers: Federal Reserve benchmark rate stabilization is the leading indicator that promotional financing program profitability will recover, warranting exposure to originators with dynamic pricing infrastructure. Position for five-to-ten year consolidation as regulatory compliance costs force mid-tier regional lenders toward exit. Monitor CFPB enforcement action frequency as signal for portfolio rebalancing timing toward prime-tier secured structures.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Data Infrastructure Investment | Machine learning underwriting expands addressable borrower pools beyond FICO-centric models for gig-economy applicants. |
| Captive Dealer Network Expansion | Harley-Davidson Financial Services leverages point-of-sale integration to lock out competing originators from premium cruiser volume. |
| Digital Origination Platform Deployment | Branchless acquisition cost reduction enables penetration of rural Texas and Florida markets lacking physical infrastructure. |
| Securitization Market Access | Institutional funding diversification reduces reliance on manufacturer balance sheet capacity for portfolio growth. |
| Subscription-Based Product Launch | California millennial and Gen-Z riders prioritize bundled access models over traditional installment ownership structures. |
Research Methodology
Multi-period observation of origination volume trends, promotional rate program structures, and state-level regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with captive finance executives, digital lending platform operators, dealer finance and insurance managers, and CFPB policy specialists. Secondary validation incorporated SEC 10-K filings from publicly traded originators, NCUA call report data, state banking commissioner enforcement records, and securitization prospectus disclosures. Bottom-up loan-level performance data triangulated against top-down macroeconomic indicators including Federal Reserve benchmark rate trajectories and regional unemployment patterns.
Segment-weighting across loan type, customer experience tier, tenure structure, and interest rate mechanism informed volume and value projections across the analysis window. CAGRs were derived from regression analysis of historical origination growth against disposable income trends and vehicle sales correlations. Industry-specific forecast inputs included recreational touring rider demographic expansion rates and electric motorcycle residual value curve development.
Revisions become necessary when CFPB enforcement priorities shift toward disparate impact testing in algorithmic underwriting, Federal Reserve rate volatility exceeds modeled scenarios, or electric motorcycle collateral performance diverges from depreciation assumptions. A model refresh is warranted upon material change in state usury ceiling legislation or manufacturer captive finance subsidy levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Microfinance Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market