
 India Auto Loan Market | 2026-2036
India Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
India Auto Loan Market Insights
Subscription-based vehicle ownership models and software-defined EMI restructuring are rebalancing what lenders package as auto credit. HDFC Bank leverages its branch network to sustain dominance in new car financing across tier-1 cities. Bajaj Finance competes through its rural two-wheeler loan footprint, while Cholamandalam Investment and Finance Company anchors commercial vehicle lending with dealer-integrated disbursement systems.
An auto loan is a secured credit instrument collateralized by the vehicle title, typically structured with fixed or floating interest rates tied to the lender's MCLR or external benchmark, and designed to enable acquisition of motorized transport assets without full upfront payment. New car loans command the largest outstanding portfolio, though used car loans and two-wheeler loans are expanding faster as digital KYC and e-NACH mandate adoption reduce origination costs for lower ticket sizes. By borrower profile, individual buyers occupy the volume base, but small businesses and fleet corporates generate superior margin pools through relationship-linked cross-selling of insurance and working capital products.
RBI prudential norms on consumer credit exposure, SEBI regulations governing lender capital market access, and BIS standards for digital payment infrastructure collectively shape product design and compliance costs across the sector. The PLI scheme for automotive manufacturing indirectly stimulates loan demand by expanding domestic vehicle supply. Stakeholders must monitor how UPI-based collections and account aggregator frameworks alter customer acquisition economics and default prediction accuracy.
Market Dynamics
Digital underwriting platforms are compressing loan disbursement timelines from days to minutes, fundamentally altering capital allocation across India's auto finance ecosystem while RBI prudential norms simultaneously tighten risk-weighting requirements.
Growth Catalysts
- Account Aggregator Framework:India's consent-based financial data sharing architecture enables real-time credit assessment, reducing documentation friction for rural two-wheeler borrowers.
- PLI Scheme for Automotive Manufacturing:Production-linked incentives expand domestic vehicle supply, creating downstream demand for dealer-integrated financing products.
- e-NACH Mandate Adoption:Automated recurring payment infrastructure lowers collection costs for sub-₹50,000 ticket-size loans previously excluded from formal credit.
Market Restraints
- Used Vehicle Valuation Opacity:Absence of standardized secondary-market pricing mechanisms exposes lenders to collateral risk misestimation in pre-owned car portfolios.
- Concentrated Dealer Network Dependency:Maharashtra and Gujarat manufacturing belts generate geographic origination risk, with 60% of commercial vehicle disbursements clustering in western India.
- Repo Rate Transmission Lag:RBI monetary policy adjustments transmit imperfectly to floating-rate auto loan portfolios, compressing net interest margins during tightening cycles.
Strategic Opportunities
- Subscription-to-Ownership Bridge Products:Software-defined EMI restructuring allows lenders to capture mobility-as-a-service users transitioning to asset ownership.
- Tier-3 and Tier-4 City Penetration:Underbanked districts in Bihar, Uttar Pradesh, and Madhya Pradesh present origination white space for two-wheeler and entry-level car financing.
- UPI-Based Collections Infrastructure:Real-time payment rails enable daily or weekly micro-collection schedules aligned with informal sector cash flows.
Industry Challenges
- Embedded Finance Integration Complexity:API interoperability between legacy core banking systems and OEM digital platforms requires substantial middleware investment.
- Alternative Data Model Validation:Psychometric and telecom-derived scoring methodologies face regulatory scrutiny under RBI's consumer credit exposure norms.
- EV Battery Residual Value Uncertainty:Rapid cathode chemistry evolution complicates long-tenor loan structuring for electric two-wheeler and car portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Auto Loan Market |
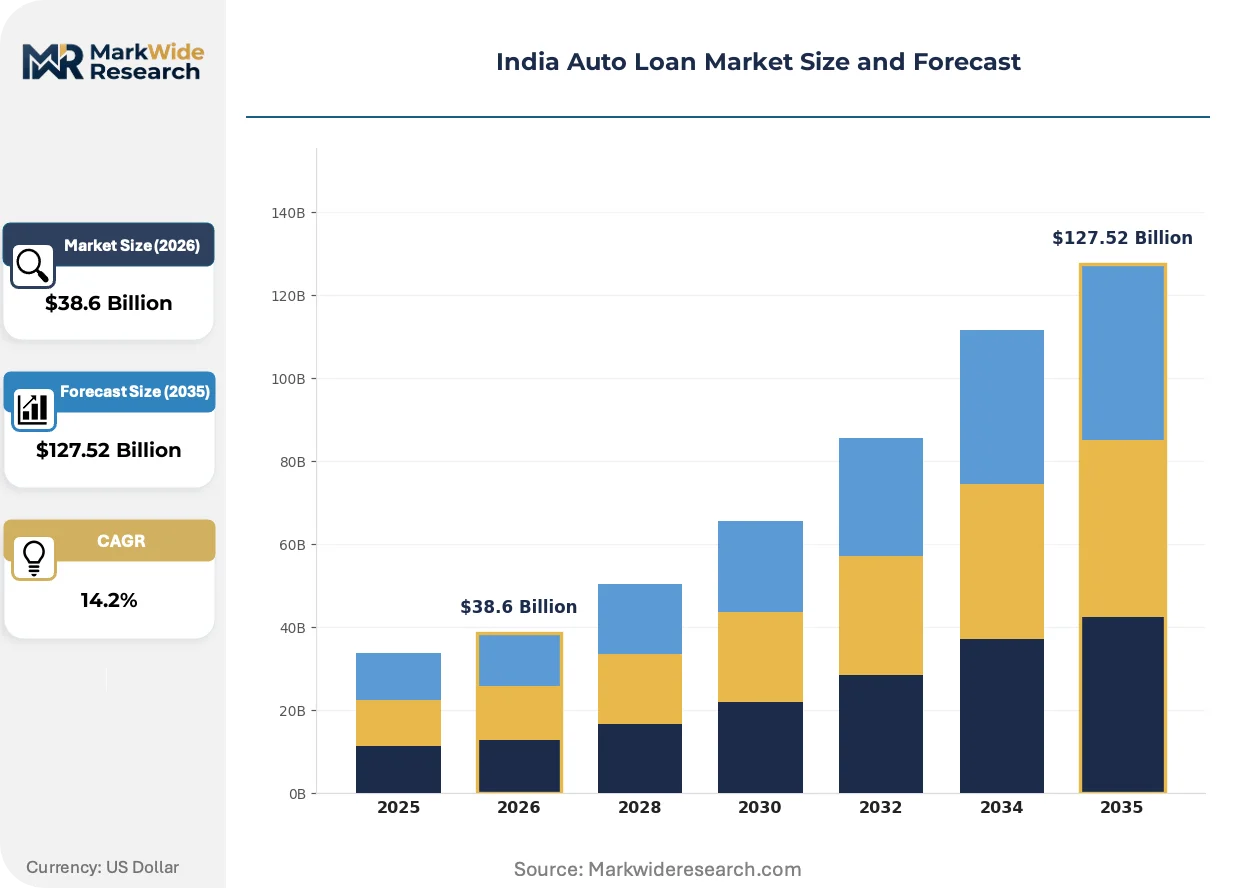
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: New Car Loan, Used Car Loan, Two-Wheeler Loan, Commercial Vehicle Loan Borrower Profile: Individual Buyers, Corporates, Small Businesses, Government Entities Repayment Structure: EMI, Balloon Payment, Flat Rate, Residual Value Loan Amount: Low Amount, Medium Amount, High Amount, Premium Value |
| Companies Covered | State Bank of India, HDFC Bank, ICICI Bank, Axis Bank, Kotak Mahindra Bank, Bajaj Finance, Mahindra & Mahindra Financial Services, Cholamandalam Investment and Finance Company, Shriram Finance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Auto Loan Market Trends and Innovations
Three distinct vectors are restructuring how auto credit originates, prices, and collects: algorithmic underwriting replacing manual assessment, embedded finance dissolving channel boundaries, and alternative ownership models fragmenting traditional loan structures.
Machine learning-based credit scoring is absorbing informal employment patterns into formal risk models. Rural two-wheeler lenders deploy psychometric questionnaires and mobile wallet transaction histories to underwrite borrowers lacking ITR documentation. This technology is absorbing previously excluded segments into addressable markets while compressing traditional bureau-dependent origination economics.
RBI's consumer credit exposure norms and SEBI's guidelines for lender capital market access are tightening provisioning requirements and disclosure standards. NBFCs face higher risk weights on unsecured portions of loan-to-value ratios above 80%. Commercial vehicle financiers are responding by restructuring products around balloon payments and residual-value guarantees.
Fleet operators and gig economy drivers are fragmenting procurement into usage-based arrangements rather than outright purchase. Aggregator platforms are disintermediating dealer finance networks by pre-negotiating bulk vehicle acquisitions with embedded maintenance and insurance bundles. This behavioral pivot is most visible in Maharashtra's urban logistics corridors and Gujarat's industrial freight belts.
India Auto Loan Market Segmentation
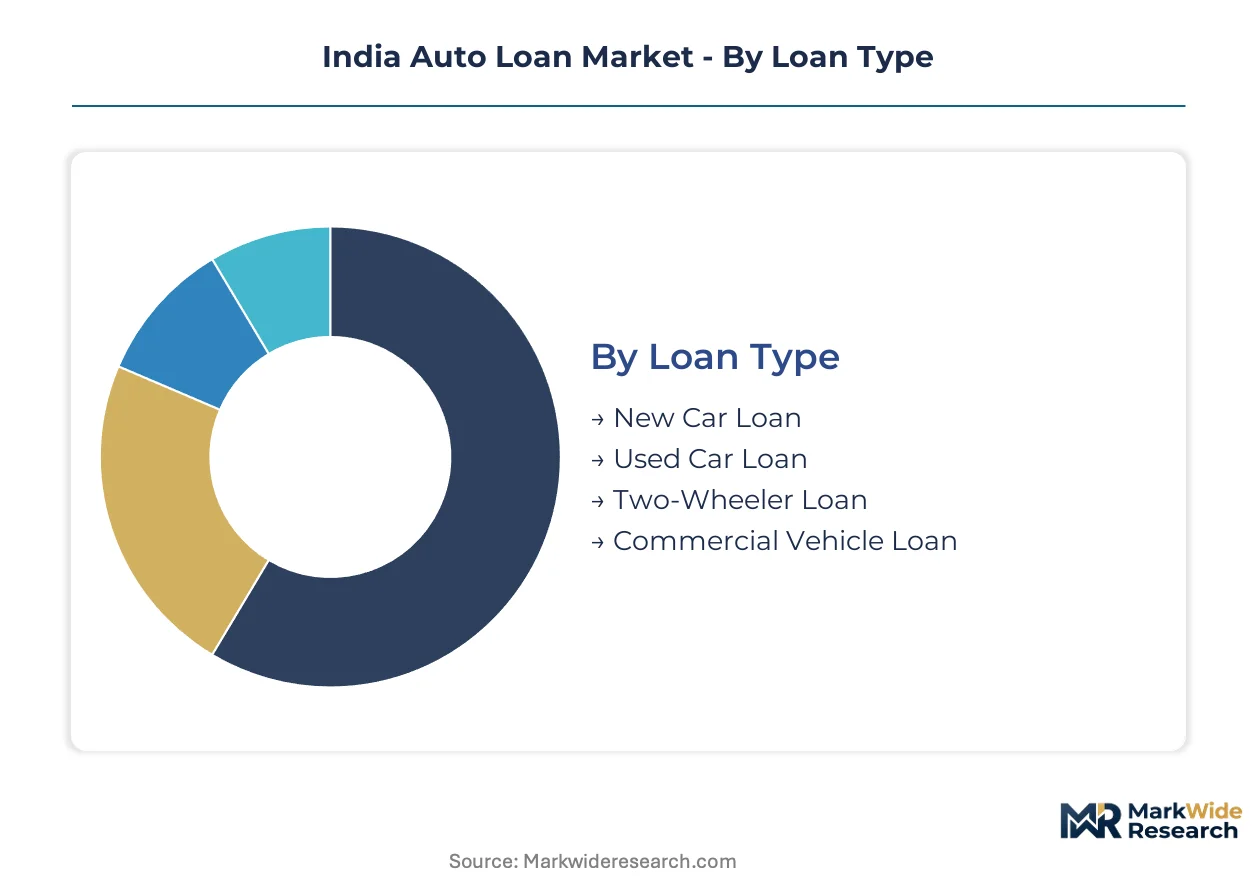
Auto loan segmentation in India reveals how collateral type, borrower cash flow predictability, and regulatory risk-weighting fragment origination economics across ticket sizes and geographies. Lenders structure products around vehicle depreciation curves and regional bureau penetration.
Loan Type:
Standardization dominates new vehicle financing while used and commercial segments demand customized collateral assessment protocols.
- New Car Loan:Fixed-rate instruments collateralized by first-sale vehicles with manufacturer residual value guarantees. HDFC Bank and ICICI Bank concentrate disbursements in Mumbai, Delhi, and Bengaluru where dealer finance integrations and salaried borrower density align.
- Used Car Loan:Floating-rate products requiring manual valuation of secondary-market collateral with elevated loan-to-value ratios. Documentation friction and valuation opacity restrict volume to organized dealer networks in Gujarat and Tamil Nadu.
- Two-Wheeler Loan:Sub-₹50,000 ticket-size credit with psychometric underwriting for rural informal employment.
- Commercial Vehicle Loan:Asset-backed financing for freight and passenger transport fleets with balloon payment structures.
Most installed capacity flows through New Car Loan. Expansion is steepest in Two-Wheeler Loan.
Borrower Profile:
Volume concentrates in individual retail while margin pools cluster in relationship-driven corporate and small business segments.
- Individual Buyers:Salaried and self-employed borrowers with ITR or alternative data documentation. Maharashtra and Karnataka urban centers generate the highest application volumes through digital KYC channels.
- Corporates:Fleet operators and logistics companies procuring vehicles through bulk credit arrangements with cross-sold working capital products. Tamil Nadu and Haryana manufacturing corridors anchor demand.
- Small Businesses:Proprietorships and partnerships with irregular cash flows requiring flexible repayment schedules.
- Government Entities:Public sector undertakings with sovereign-backed procurement and extended tenor requirements.
Individual Buyers command the largest outstanding base. Small Businesses are gaining share fastest.
Repayment Structure:
Fixed obligations suit salaried profiles while variable structures absorb cash flow volatility in informal and fleet segments.
- EMI:Equal monthly installment structures with principal and interest amortization across fixed tenors. Standard product for salaried individual buyers in tier-1 cities with established credit histories.
- Balloon Payment:Low periodic obligations with large terminal payments matching fleet replacement cycles. Cholamandalam and Shriram Transport Finance deploy these for commercial vehicle operators in Gujarat freight corridors.
- Flat Rate:Simple interest calculation with uniform periodic payments without principal reduction.
- Residual Value:Tenors structured around guaranteed buyback values with manufacturer or lessor risk absorption.
EMI structures handle the majority of disbursement volume. Balloon Payment products are climbing the fastest.
Loan Amount:
Ticket-size tiering determines documentation requirements, risk weights under RBI norms, and collection infrastructure investment.
- Low Amount:Sub-₹2 lakh exposures with alternative data underwriting and UPI-based micro-collections. Rural Bihar and Uttar Pradesh two-wheeler markets drive origination with e-NACH mandate adoption reducing servicing costs.
- Medium Amount:₹2-10 lakh exposures spanning entry-level cars and premium two-wheelers with bureau-dependent scoring.
- High Amount:₹10-25 lakh exposures for mid-segment cars with standardized valuation and manufacturer tie-ups.
- Premium Value:Above-₹25 lakh exposures for luxury vehicles with specialized collateral management and lower loss-given-default.
Medium Amount transactions process the highest application volume. Low Amount products show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between state-level stamp duties and RTO processing fees are redirecting auto loan origination toward jurisdictions with digitized documentation infrastructure. Maharashtra and Gujarat absorb disproportionate disbursement volumes due to integrated dealer finance networks clustering around manufacturing belts.
Maharashtra
Mumbai and Pune metropolitan corridors generate the highest new car loan application densities through salaried borrower concentrations. The state's Motor Vehicles Department e-services platform reduces hypothecation registration friction. Chakan-Talegaon automotive manufacturing belt anchors dealer-integrated financing with same-day disbursement protocols.
Gujarat
Commercial vehicle fleets concentrated around Mundra port and Sanand industrial zone drive balloon-payment structured lending. Gujarat's single-window clearance system for vehicle registration compresses collateral perfection timelines. Ahmedabad-Surat freight corridors host dense NBFC branch networks serving proprietor-owned transport operators.
Karnataka
Bengaluru's technology workforce sustains premium car financing through bureau-dependent digital KYC channels. The state's EV policy subsidies stimulate electric two-wheeler loan origination with residual-value guarantees. Hosur-Nelmangala automotive supplier parks create downstream credit demand among component logistics fleets.
Tamil Nadu
Chennai-Oragadam-Sriperumbudur manufacturing belt concentrates commercial vehicle procurement for OEM supplier networks. Tamil Nadu's stamp duty rationalization on loan agreements reduces documentation costs for sub-₹5 lakh exposures. Coimbatore's SME proprietor base generates irregular cash flow products with flexible repayment schedules.
Delhi-NCR
Noida-Gurugram logistics corridors anchor fleet operator financing with cross-sold working capital arrangements. The National Capital Region's account aggregator penetration enables real-time credit assessment for gig economy driver segments. Faridabad's auto component clusters sustain relationship-linked insurance bundling with vehicle loans.
India Auto Loan Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with deposit-taking banks commanding new car portfolios and NBFCs capturing sub-prime and commercial vehicle niches. The market structures around three tiers: public sector banks with branch density, private banks with digital infrastructure, and specialized NBFCs with collateral management expertise. Dominant competitive moves include API-based embedded finance partnerships with OEM platforms and backward integration into vehicle valuation services for used car portfolios.
Within the public sector tier, State Bank of India anchors rural penetration through its branch network spanning tier-3 and tier-4 towns. Among private banking specialists, HDFC Bank and ICICI Bank occupy positions concentrated in metropolitan new car financing with manufacturer tie-ups. Bajaj Finance exemplifies the NBFC archetype competing through psychometric underwriting and rural two-wheeler disbursement velocity.
| Leading Market Players |
|---|
| State Bank of India |
| HDFC Bank |
| ICICI Bank |
| Axis Bank |
| Kotak Mahindra Bank |
| Bajaj Finance |
| Mahindra & Mahindra Financial Services |
| Cholamandalam Investment and Finance Company |
| Shriram Finance |
| Others |
Pricing and Supply Chain Analysis
Deposit-taking banks with extensive branch networks anchor pricing discipline through relationship-linked cross-selling, while NBFC specialists compete on disbursement velocity and rural penetration. This ownership fragmentation between public sector banks, private banking specialists, and collateral-focused NBFCs shapes how origination economics distribute across ticket sizes and geographies.
Pricing Analysis
Capacity additions in digital underwriting infrastructure are reshaping price floors for sub-₹50,000 two-wheeler loans previously excluded from formal credit. Interest rate spreads stratify across fixed-rate new car products, floating-rate used vehicle exposures, and psychometric-scored rural segments. Pricing pressure stems from RBI risk-weighting adjustments on high loan-to-value ratios, compressing net interest margins for unsecured portfolio portions. Salaried urban borrowers in Mumbai and Bengaluru demonstrate lowest price sensitivity due to bureau-dependent convenience, while rural informal employment segments in Bihar and Uttar Pradesh prioritize disbursement speed over rate minimization.
Supply Chain Analysis
Regional distribution centers in Maharashtra and Gujarat function as collateral perfection hubs, with dealer-integrated disbursement systems clustering around Chakan-Talegaon and Sanand manufacturing belts. Vehicle supply draws from domestic OEM production anchored in Tamil Nadu, Karnataka, and Haryana assembly corridors, with component sourcing tethered to Hosur-Nelmangala supplier parks. Single-source vulnerability concentrates in lithium-ion battery cathode chemistry for emerging electric two-wheeler portfolios. Distribution runs through manufacturer-authorized dealer networks for new vehicles, while used car channels rely on organized multi-brand outlets with manual valuation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India auto loan market reads as a late-cycle quality story, with demand shifting toward subscription-to-ownership bridge products and software-defined EMI restructuring that package premium service bundles.
For Market Incumbents: To counter embedded finance disintermediation by OEM digital platforms, HDFC Bank and ICICI Bank should deepen API interoperability investments linking legacy core banking systems to manufacturer sales interfaces. Cholamandalam and Shriram Transport Finance must secure residual-value guarantee partnerships with commercial vehicle OEMs to defend balloon payment structuring against fleet operator aggregator platforms. For New Entrants and Emerging Players: RBI's account aggregator framework in India opens a window for fintech specialists to penetrate tier-3 and tier-4 origination white space in Madhya Pradesh and Rajasthan through consent-based financial data sharing. New entrants should target two-wheeler financing among gig economy drivers with UPI-based micro-collection schedules aligned to daily cash flows, leveraging e-NACH mandate adoption to reduce servicing infrastructure costs. For Investors and Strategic Acquirers: Valuations sit cheapest among rural-focused NBFCs with psychometric underwriting capabilities and established e-NACH collection rails. Long-term viability hinges on capturing the subscription-to-ownership transition wave as mobility-as-a-service users convert to asset ownership. Investors should monitor EV battery residual value guarantee standardization as the inflection signal for electric vehicle loan portfolio scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Integration | Enables real-time loan origination within OEM digital sales platforms, reducing dealer network dependency. |
| Alternative Data Model Investment | Absorbs psychometric and telecom-derived scoring for rural informal employment segments lacking ITR documentation. |
| UPI-Based Micro-Collections Infrastructure | Aligns repayment schedules with informal sector cash flows through daily or weekly collection rails. |
| Residual Value Guarantee Structuring | Addresses EV battery depreciation uncertainty through manufacturer-backed buyback arrangements. |
| Tier-3 and Tier-4 Branch Expansion | Captures underbanked origination volume in Bihar, Uttar Pradesh, and Madhya Pradesh two-wheeler markets. |
Research Methodology
Bottom-up borrower profile modeling reconciled against top-down vehicle production tracking forms the analytical core of this study. Primary interviews with auto loan product heads, dealer finance operations managers, NBFC rural lending officers, and RBI regulatory affairs specialists were combined with secondary validation from vehicle registration databases, lender annual reports, and SEBI disclosure filings. Trade data from the Ministry of Commerce and customs records supplemented domestic production volume estimates across passenger vehicle, commercial vehicle, and two-wheeler categories.
Historical trendline analysis across new car, used car, two-wheeler, and commercial vehicle segments established baseline origination patterns. The projection framework modeled loan type, borrower profile, repayment structure, and loan amount tier dimensions across the analysis window. CAGRs were derived from regression-weighted capacity additions in digital underwriting platforms and e-NACH infrastructure penetration curves. Forecast inputs incorporated RBI risk-weighting adjustments, PLI scheme automotive manufacturing incentives, and account aggregator framework adoption trajectories.
Revisions become necessary when RBI prudential norms on consumer credit exposure tighten beyond modeled thresholds, or when UPI-based collections infrastructure achieves unanticipated penetration in rural districts. Forecasts reflect documented assumptions regarding digital KYC adoption rates and dealer finance network consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Microfinance Market
Loans and Leasing
Premium Finance Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Australia Automotive Financing Market