
 Loan Origination Software Market | 2026-2036
Loan Origination Software Market Size, Share, and Industry Trends Forecast 2026-2036
Loan Origination Software Market Analysis
GDPR-equivalent data privacy mandates in the European Union are shifting compliance burdens onto smaller lenders who previously relied on manual underwriting workflows. ICE Mortgage Technology leverages its vertically integrated platform to sustain dominance across correspondent and retail lending channels. Fiserv anchors its position through embedded banking partnerships that extend loan origination capabilities into core banking infrastructure. Finastra competes aggressively in the credit union segment, where its Phoenix platform occupies a differentiated niche against larger incumbents.
Loan origination software encompasses the digital infrastructure that automates borrower qualification, document verification, underwriting decisioning, and closing coordination across consumer, commercial, and mortgage credit products. These platforms integrate with credit bureaus, appraisal management companies, and government-sponsored enterprise portals through standardized API protocols to compress cycle times from application to funding. Cloud-based deployment leads the product type dimension as regional banks abandon on-premises maintenance contracts in favor of subscription models with automatic compliance updates. Artificial intelligence within the technology dimension is accelerating fastest, with machine learning models now handling income verification and fraud detection that previously required manual analyst review.
The US Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures and qualified mortgage standards that shape software feature requirements for domestic lenders. The EU's Digital Operational Resilience Act and GDPR impose cross-border data residency and breach notification obligations on vendors serving European banks. Stakeholders must monitor how open banking API mandates from the CFPB and PSD2 in Europe reshape borrower data access permissions and competitive dynamics between incumbent platforms and fintech challengers.
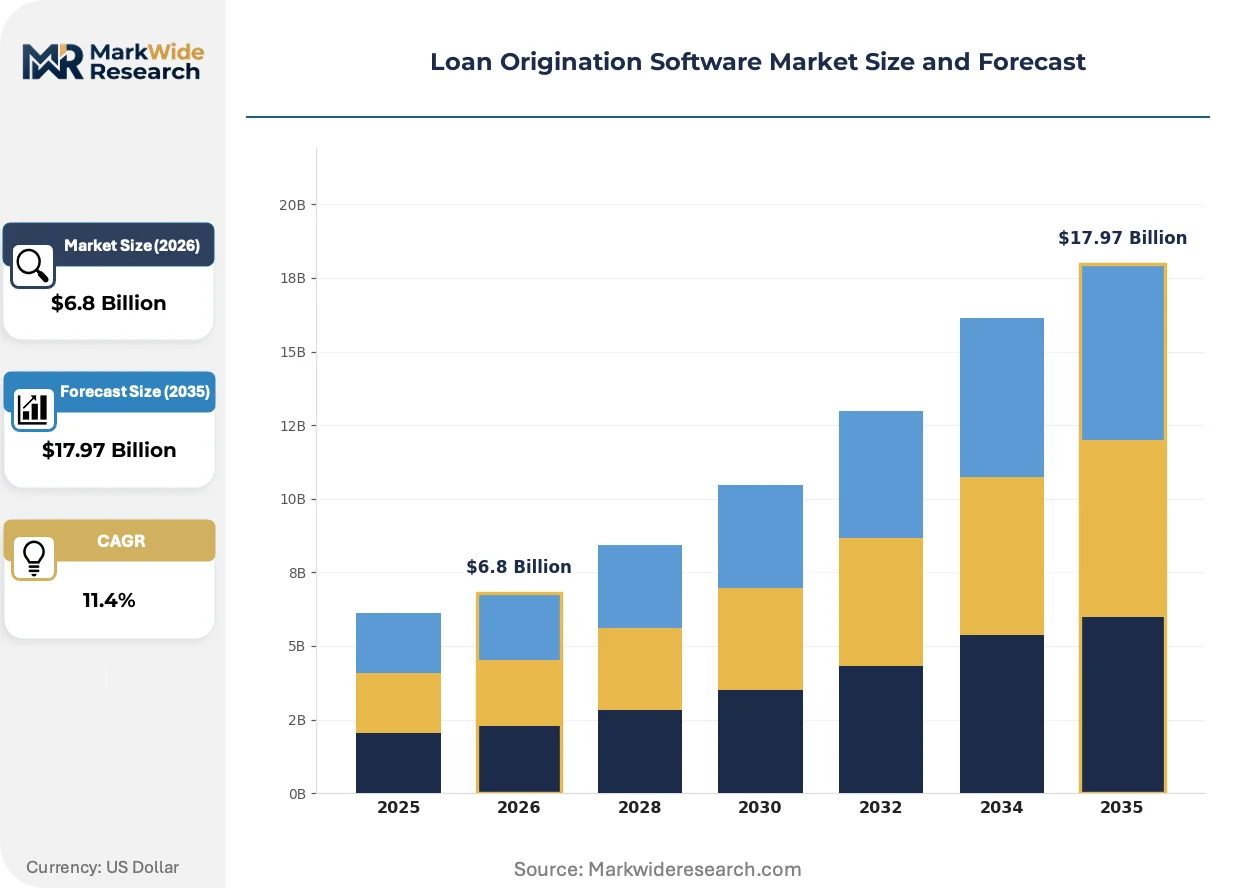
Market Dynamics
Cloud migration among community banks and credit unions is compressing deployment cycles from months to weeks, forcing legacy on-premises vendors to pivot subscription architectures or surrender market position to SaaS-native competitors.
Growth Catalysts
- Open Banking Mandates:The US Consumer Financial Protection Bureau's data-sharing rules require API-enabled borrower verification, compelling lenders to upgrade from paper-based workflows to integrated digital platforms.
- Artificial Intelligence:Machine learning models now handle income verification and fraud detection that previously required manual analyst review, reducing underwriting cycle times by half for early adopters.
- Credit Union Modernization:Member-owned institutions with assets under $10 billion are abandoning legacy core systems for cloud-native origination stacks to compete with larger regional banks on speed-to-close.
Market Restraints
- Implementation Costs:Mid-tier lenders face six-figure integration expenses connecting new origination platforms to existing core banking systems, delaying procurement decisions.
- Data Residency Requirements:The EU's Digital Operational Resilience Act and GDPR impose cross-border data localization obligations that fragment vendor architectures and inflate compliance overhead.
- Technical Debt:COBOL-dependent legacy infrastructure at established banks creates middleware complexity that slows API adoption and extends vendor onboarding timelines.
Strategic Opportunities
- Embedded Finance Convergence:Non-bank platforms—auto dealers, homebuilders, fintechs—seek white-labeled origination modules, opening distribution channels outside traditional banking relationships.
- Commercial Real Estate Digitization:Underpenetrated CRE lending workflows present expansion potential as property investors demand the same digital convenience retail borrowers now expect.
- State-Level Licensing Automation:Multi-state lenders face fragmented compliance requirements; platforms that automate NMLS reporting and state-specific disclosure generation capture premium pricing power.
Industry Challenges
- API Talent Scarcity:Vendors and lenders alike compete for engineers experienced in mortgage industry data standards, inflating compensation costs and delaying product roadmaps.
- Integration Complexity:Connecting origination platforms to disparate loan servicing systems, document management repositories, and investor delivery channels requires bespoke middleware that fragments vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loan Origination Software Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-premises, Cloud-based, Hybrid, Mobile End User: Banks, Credit Unions, Non-banking Financial Institutions, Mortgage Lenders Technology: Blockchain, Artificial Intelligence, Machine Learning, Data Analytics Deployment Model: Public Cloud, Private Cloud, Community Cloud, Multi-tenant |
| Companies Covered | ICE Mortgage Technology (Ellie Mae), Fiserv, Finastra, FICO, MeridianLink, Calyx, LendFoundry, TurnKey Lender, ABLE Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loan Origination Software Market Emerging Trajectories
Artificial intelligence and regulatory mandates are converging to reshape how lenders acquire, verify, and decision borrowers, compressing the traditional origination timeline while elevating compliance automation from feature to baseline requirement.
Machine learning-powered income verification is automating document classification and cash-flow analysis that previously required manual underwriter review. Regional banks with assets between $10 billion and $100 billion are deploying these tools fastest, seeking parity with money-center competitors on pull-through rates. The technology is automating exception handling for self-employed borrowers and gig-economy income streams that conventional verification methods struggle to assess.
The EU's Digital Operational Resilience Act imposes strict third-party risk management and incident reporting obligations on software vendors serving European credit institutions. Vendors must now maintain operational resilience testing and contractual exit provisions that inflate compliance costs. Smaller lenders in Germany and France are consolidating vendor relationships to reduce DORA audit burden, favoring integrated platforms over best-of-breed point solutions.
Subscription pricing models are displacing perpetual license arrangements as credit unions and community banks prioritize operational flexibility over capital ownership. Vendors now capture recurring revenue through usage-based tiers tied to loan volume rather than seat counts. This shift is most pronounced among institutions with under $5 billion in assets, where CFOs face pressure to convert fixed IT costs to variable expense structures aligned with origination cyclicality.
Loan Origination Software Market Segmentation
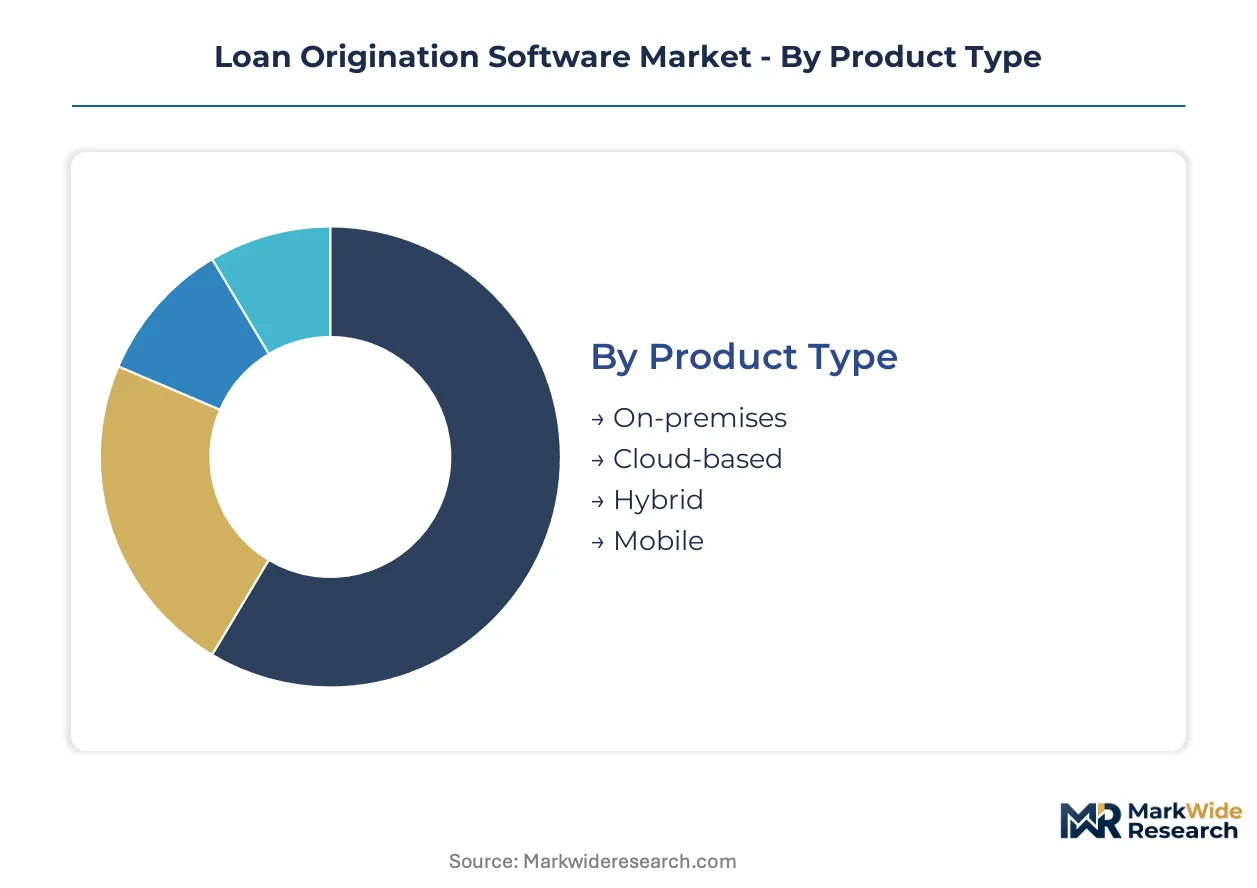
Lenders select origination platforms based on regulatory complexity, integration burden, and borrower experience requirements. Segmentation reveals how deployment choices and technology investments cluster across institution types and risk appetites.
Product Type:
Deployment architecture determines capital allocation, compliance update velocity, and disaster recovery posture for lenders with varying technical maturity.
- Cloud-based:Subscription models deliver automatic regulatory patches and elastic compute for origination volume spikes. Regional banks with assets between $10 billion and $100 billion are consolidating here to escape on-premises maintenance overhead.
- On-premises:Legacy installations persist at money-center banks with bespoke security requirements and captive data centers. These institutions prioritize air-gapped environments over vendor-managed infrastructure despite higher total cost of ownership.
- Hybrid:Split architectures isolate sensitive underwriting data on-premises while pushing borrower-facing workflows to cloud edge nodes.
- Mobile:Native applications serve loan officers in field environments, particularly at community banks with distributed branch networks.
Cloud-based leads on scale; mobile leads on momentum.
End User:
Institution charter shapes procurement timelines, feature priorities, and vendor relationship structures across the origination ecosystem.
- Banks:Federally chartered institutions demand enterprise-grade API throughput and investor delivery automation. Their procurement cycles stretch 12-18 months given compliance committee oversight.
- Credit Unions:Member-owned structures prioritize member experience metrics and flexible pricing tied to origination volume rather than seat licenses.
- Mortgage Lenders:Non-depository originators require correspondent channel integration and rapid investor onboarding capabilities.
- Non-banking Financial Institutions:Auto finance and consumer lenders seek white-label modules for embedded deployment at point-of-sale.
Banks lead on scale; non-banking financial institutions lead on momentum.
Technology:
Intelligence layer investments separate commodity workflow automation from differentiated decisioning speed and fraud precision.
- Artificial Intelligence:Neural networks now parse bank statements, tax returns, and employment records without human intervention. Early adopters at regional banks have compressed income verification from days to minutes.
- Machine Learning:Supervised models trained on historical performance data flag application anomalies and predict default probability with greater accuracy than legacy scorecards.
- Data Analytics:Descriptive dashboards help lenders identify pipeline bottlenecks and optimize pull-through rates by loan officer and channel.
- Blockchain:Distributed ledger pilots target mortgage document notarization and secondary market transparency, though production deployment remains limited.
Artificial intelligence leads on scale; machine learning leads on momentum.
Deployment Model:
Infrastructure tenancy choices reflect data sovereignty requirements, multi-jurisdictional footprint, and sensitivity to vendor concentration risk.
- Public Cloud:Shared infrastructure from hyperscale providers delivers lowest unit economics for lenders without specialized compliance needs.
- Private Cloud:Dedicated single-tenant environments satisfy EU data residency mandates and US federal banking agency examination expectations.
- Community Cloud:Industry-specific instances serve credit union service organizations and bank consortiums seeking collective bargaining power with vendors.
- Multi-tenant:Logical separation within shared physical infrastructure balances cost efficiency with configurable security policies.
Public cloud leads on scale; private cloud leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered large-scale digital mortgage origination during the post-2008 financial crisis regulatory rebuild, establishing the technical and compliance frameworks that now propagate to other jurisdictions.
United States
Regional banking networks with assets between $10 billion and $100 billion drive cloud platform procurement as they compete with money-center institutions on pull-through rates. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures and qualified mortgage standards that shape software feature requirements. Dallas and Charlotte host concentrated vendor development operations serving correspondent lending channels.
United Kingdom
Open banking APIs mandated by the Financial Conduct Authority accelerate lender migration from legacy underwriting workflows to integrated digital stacks. The Prudential Regulation Authority supervises operational resilience expectations for core banking system integrations. London's fintech corridor attracts venture-backed origination platform challengers targeting building society modernization.
Germany
Savings banks and cooperative credit institutions consolidate vendor relationships to reduce audit burden under the Digital Operational Resilience Act. BaFin enforces third-party risk management obligations on software vendors serving regulated credit institutions. Frankfurt's banking cluster demands multi-tenant cloud architectures satisfying federal data residency requirements.
India
Housing finance companies and non-banking financial companies deploy mobile-first origination modules to penetrate semi-urban and rural borrower segments. The Reserve Bank of India regulates digital lending practices and data localization mandates for credit information. Mumbai and Bengaluru concentrate fintech development labs partnering with regional banks on vernacular-language application interfaces.
Australia
Customer-owned banks and mutuals prioritize member experience metrics in procurement decisions, favoring platforms with flexible volume-based pricing. The Australian Prudential Regulation Authority supervises operational risk management for outsourced technology functions. Sydney hosts Asia-Pacific headquarters for global vendors adapting European compliance architectures to local regulatory frameworks.
Loan Origination Software Market Vendor Landscape
The competitive structure tilts toward vertically integrated platform providers with captive data assets and correspondent channel relationships. Tier-one incumbents anchor positions through embedded banking partnerships and automatic compliance update subscriptions. Mid-tier specialists compete on credit union segment focus and rapid deployment timelines. Dominant competitive moves include strategic API standardization efforts and geographic expansion through white-label distribution.
Within the vertically integrated tier, ICE Mortgage Technology and Fiserv exemplify archetypes combining loan origination with adjacent servicing and data analytics capabilities. Finastra occupies a differentiated position serving member-owned institutions with modular deployment options. These anchors represent contrasting strategic bets on consolidation versus specialization as cloud migration accelerates across regional banking networks.
| Leading Market Players |
|---|
| ICE Mortgage Technology (Ellie Mae) |
| Fiserv |
| Finastra |
| FICO |
| MeridianLink |
| Calyx |
| LendFoundry |
| TurnKey Lender |
| ABLE Platform |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in loan origination software have consolidated fragmented point-solution vendors into platform plays, tightening pricing discipline through subscription bundling while compressing supplier margins via volume commitments to cloud infrastructure providers.
Pricing Analysis
Usage-based subscription tiers tied to monthly loan volume dominate pricing structures across community banks and credit unions. Price differentiation rests on API throughput ceilings and automated compliance update frequency. Cost compression in the mid-market tier is intensifying because regional banks with assets between $10 billion and $100 billion negotiate enterprise discounts against SaaS-native challengers. Credit unions with assets under $5 billion exhibit the highest price sensitivity, while money-center banks with captive data centers show the least.
Supply Chain Analysis
Reverse-logistics flows for loan origination software center on data migration services and decommissioned on-premises hardware recovery as lenders abandon legacy installations. Engineering talent concentrates in the United States, India, and Ireland. Platform development draws from cloud compute infrastructure, mortgage industry data standards expertise, and regulatory compliance content libraries. Single-source vulnerability in specialized API engineering talent inflates compensation costs and delays product roadmaps. Distribution runs through direct enterprise sales teams and credit union service organization consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Loan origination software offers margin-expansion potential as cloud-native architectures displace high-maintenance on-premises deployments, converting fixed license revenue to recurring subscription streams with automatic compliance update premiums.
For Market Incumbents: Acquire specialized AI underwriting engines to fortify income verification automation against fintech challengers deploying neural network models. Consolidate correspondent channel relationships through embedded banking partnerships that extend origination capabilities into core banking infrastructure. Deepen backward integration into appraisal management and document notarization services to capture margin from adjacent workflow steps.
For New Entrants and Emerging Players: Machine learning-powered exception handling for self-employed borrowers presents the most penetrable wedge against established platforms. Target credit unions with assets under $10 billion seeking rapid deployment timelines and volume-based pricing flexibility. Pursue white-label distribution through auto dealer and homebuilder point-of-sale channels to bypass entrenched banking procurement cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialists with concentrated credit union relationships and modular deployment architectures. Long-term viability favors platforms with captive data assets and correspondent channel integration that sustain switching costs. Monitor CFPB open banking rule implementation timelines as an inflection indicator for API-enabled borrower verification demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating point solutions into unified stacks reduces vendor audit burden under DORA and CFPB rules. |
| Acquisition of Specialist Firm | Buying AI underwriting engines accelerates income verification automation for regional bank customers. |
| Strategic Partnership | Embedded banking alliances with Fiserv extend origination capabilities into core banking infrastructure. |
| Geographic Expansion | White-label distribution through EU savings banks captures DORA-mandated vendor consolidation demand. |
| Product Launch | Commercial real estate digitization modules address underpenetrated property investor workflows. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief lending officers, core banking integration specialists, credit union procurement committees, and mortgage technology vendors with secondary validation against SEC filings from publicly traded platform providers, FFIEC call report data, and CFPB regulatory guidance documents. Bottom-up loan volume modeling and top-down IT spending allocation analysis were triangulated against vendor revenue disclosures.
Comparable historical periods anchored the projection horizon, with growth trajectories calibrated against prior cloud migration cycles in financial services. Segmentation dimensions modeled include deployment architecture, institution charter type, asset size tier, integration complexity, and regional regulatory cluster. CAGRs were derived from volume-weighted average growth across institution size bands, incorporating inputs from mortgage origination cyclicality patterns and open banking API mandate implementation schedules.
The model holds under steady regulatory implementation timelines; deviation in CFPB enforcement intensity or EU DORA audit scope expansion would shift vendor consolidation velocity. Practitioners should monitor Fed interest rate trajectories and regional bank M&A activity for early signals of origination volume and procurement budget sensitivity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Invoice Factoring Market