
 Battery Leasing Service Market | 2026-2036
Battery Leasing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Leasing Service Market Analysis
China's gigafactory belt is tilting toward service-oriented battery deployment as domestic automakers expand beyond direct sales. Contemporary Amperex Technology Co. Ltd. leverages its cell-to-pack manufacturing scale to anchor leasing programs for commercial EV fleets. NIO sustains its battery-as-a-service subscription model through dedicated swap station networks in major Chinese metropolitan areas. Tesla competes with integrated lease-to-own structures that tie vehicle financing directly to energy storage performance guarantees.
Battery leasing service constitutes a contractual arrangement where energy storage assets remain under provider ownership while users pay periodic fees for access, cycling rights, and maintenance coverage, typically structured around guaranteed capacity thresholds and defined cycle-life parameters. The primary commercial purpose centers on converting battery procurement from capital expenditure to operational expenditure, thereby transferring degradation risk and residual value uncertainty to specialized asset managers. Subscription frameworks dominate revenue pools in electric vehicle applications where predictable monthly outlays align with fleet budgeting cycles, while pay-per-use structures capture fastest expansion in renewable energy storage where dispatch frequency varies seasonally. Solid-state chemistry segments attract premium lease pricing due to extended cycle warranties, though lithium-ion configurations occupy the bulk of deployed capacity through established recycling reverse logistics.
The EU Battery Regulation and REACH compliance frameworks mandate carbon footprint disclosure and recycled content thresholds that favor leasing models with centralized battery stewardship. China's MIIT issues GB standards governing battery swap interoperability that directly enable NIO and Gogoro network architectures. India's BIS certification and PLI scheme incentives for advanced chemistry cell manufacturing are stimulating domestic leasing platform development. Stakeholders must monitor how evolving extended producer responsibility regimes reshape asset ownership economics and residual value recovery obligations across jurisdictions.
Market Dynamics
Capital expenditure avoidance among commercial fleet operators is compressing battery ownership structures toward operational expenditure models, transferring degradation risk to specialized asset managers and reshaping competitive positioning across the energy storage value chain.
Growth Catalysts
- EU Battery Regulation due diligence mandates:Centralized battery stewardship requirements accelerate service-based deployment across member states as operators seek compliance through outsourced asset management.
- Commercial EV fleet electrification:Predictable monthly budgeting cycles align with subscription frameworks, pulling logistics operators away from direct procurement.
- Solid-state chemistry maturation:Extended cycle warranties enable premium lease pricing structures that improve provider unit economics.
Market Restraints
- Lithium supply concentration:Processing capacity bottlenecks in South American salt flats and Australian hard-rock mines create input cost volatility for lease rate stability.
- Residual value uncertainty:Second-life application economics remain unproven at scale, compressing provider balance sheet capacity.
- Grid interconnection queues:Stationary storage deployment delays in deregulated electricity markets constrain behind-the-meter lease expansion.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives stimulate platform development for two-wheeler and three-wheeler battery subscription services.
- Vehicle-to-grid integration:Bidirectional charging hardware convergence with energy trading software creates new revenue streams for fleet lease providers.
- Renewable energy storage dispatch variability:Pay-per-use structures capture seasonal cycling patterns that subscription models cannot address.
Industry Challenges
- Battery management system firmware standardization:Proprietary state-of-health algorithms across cell suppliers complicate unified lease portfolio management.
- Specialized technician scarcity:High-voltage safety certification requirements outpace vocational training program output in key deployment corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Leasing Service Market |
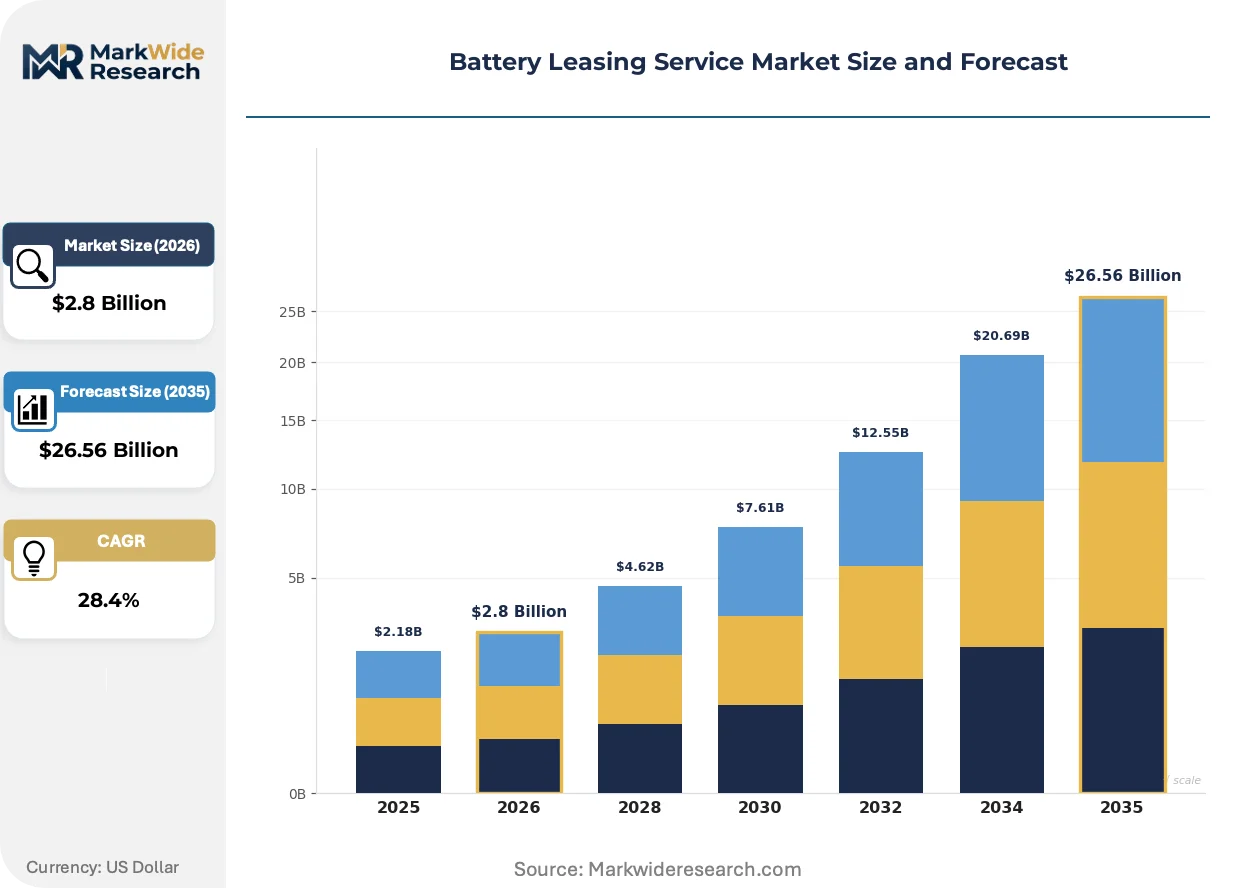
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.56 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Pay-per-Use, Lease-to-Own, Maintenance Services End User: Electric Vehicles, Consumer Electronics, Renewable Energy, Industrial Equipment Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Distribution Channel: Direct Sales, Retail Partnerships, Online Platforms, Resellers |
| Companies Covered | Tesla, Contemporary Amperex Technology Co. Ltd., NIO, Renault Group, Gogoro, Sun Mobility, Oyika, Neuron, XPENG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Leasing Service Market Emerging Trajectories
Digital twin architectures are virtualizing physical battery assets into software-defined resources, enabling predictive degradation modeling and dynamic lease pricing that responds to real-time cycling conditions rather than static calendar terms.
Cell-to-pack manufacturing architectures are eliminating module-level redundancy, reducing pack mass and cost while improving volumetric energy density. Commercial vehicle OEMs in Germany's manufacturing corridor adopt these configurations fastest, integrating lease-ready battery systems at the factory floor. The technology is virtualizing traditional aftermarket service relationships into continuous remote monitoring contracts.
REACH compliance frameworks and the EU Battery Regulation's carbon footprint disclosure requirements are mandating supply chain traceability from mining through recycling. Leasing providers with centralized stewardship capture compliance data more efficiently than fragmented ownership models. Germany's KBA and France's national environmental agencies coordinate enforcement timelines that favor service-based deployment.
Fleet procurement departments now specify guaranteed capacity thresholds rather than nominal kilowatt-hour ratings, unbundling performance risk from hardware acquisition. Energy-as-a-service platforms displace direct equipment purchasing in municipal bus electrification programs. This behavioral shift concentrates most visibly in German metropolitan transit authorities and Dutch regional logistics hubs.
Battery Leasing Service Market Segmentation
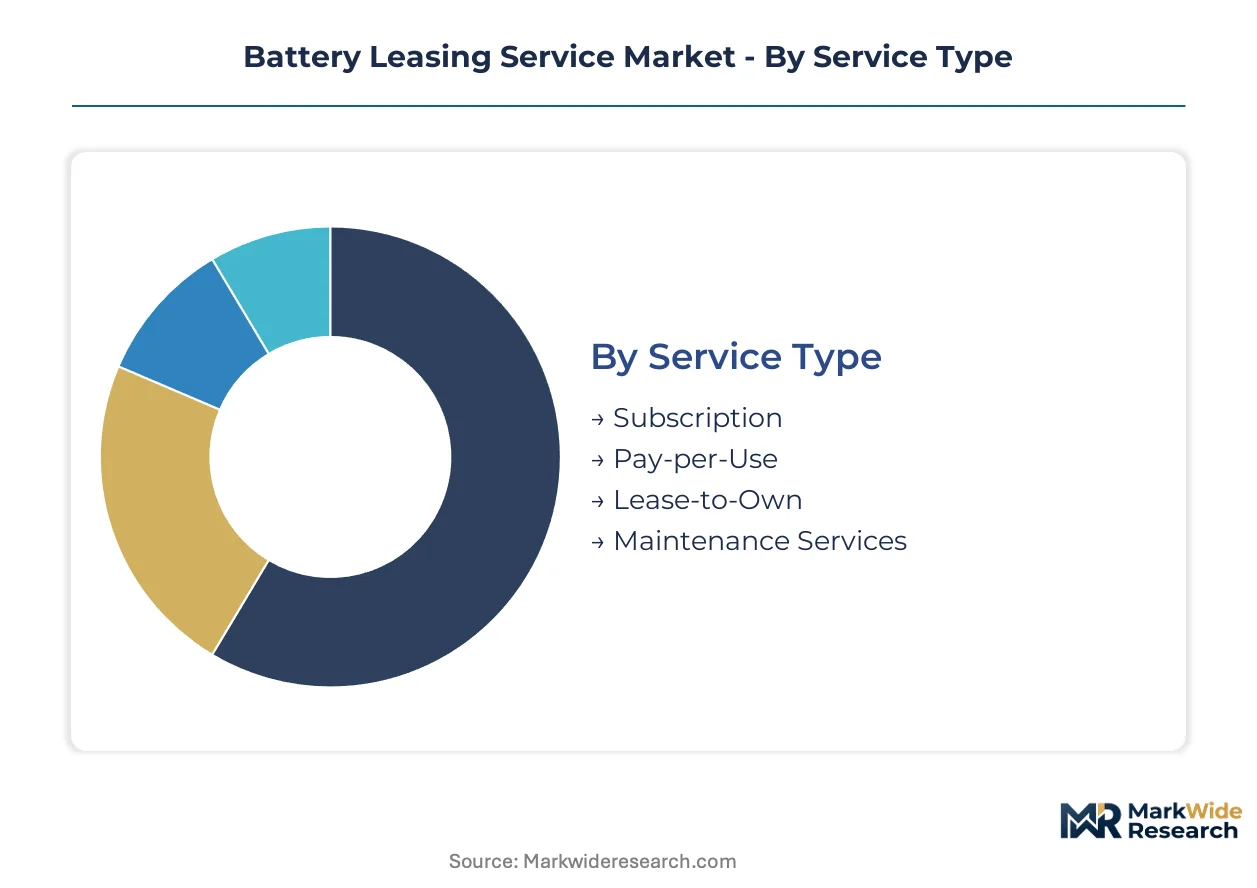
Battery leasing service providers structure pricing and risk allocation around how customers consume cycling capacity. Segment boundaries determine whether providers capture value through predictable subscriptions or variable usage fees.
Service Type:
Subscription models turn over fastest with monthly billing cycles, while lease-to-own structures extend across multi-year depreciation schedules.
- Subscription:Fixed periodic fees cover guaranteed capacity thresholds and maintenance coverage. Commercial EV fleets in Germany's manufacturing corridor favor this structure for predictable operational expenditure budgeting aligned with fleet management cycles.
- Pay-per-Use:Variable fees tied to actual energy throughput or cycling events. Renewable energy storage applications in seasonal dispatch markets concentrate here, as providers cannot forecast annual utilization with sufficient precision for fixed-rate structures.
- Lease-to-Own:Periodic payments accumulate toward eventual ownership transfer. Consumer electronics segments in China's metropolitan areas adopt this model where residual value certainty supports purchase-option pricing at contract term.
- Maintenance Services:Standalone coverage for battery health monitoring and degradation management. Industrial equipment operators purchase these separately when ownership retention is mandated by capital budgeting protocols.
Subscription dominates installed base. Pay-per-use is where expansion concentrates.
End User:
Application velocity separates high-frequency cycling segments from long-dormancy deployments, reshaping provider working capital requirements.
- Electric Vehicles:Passenger cars, commercial vans, and heavy-duty trucks constitute the primary revenue pool. Germany's KBA registration data shows fleet operators converting fastest from ownership to service models under EU Battery Regulation compliance pressure.
- Consumer Electronics:Smartphones, laptops, and portable power stations generate shorter contract terms. India's PLI scheme for advanced chemistry cells stimulates domestic platform development for two-wheeler battery subscriptions.
- Renewable Energy:Grid-scale and behind-the-meter storage installations cycle seasonally. France's national environmental agencies coordinate enforcement timelines that favor service-based deployment for utility-scale assets.
- Industrial Equipment:Forklifts, material handling systems, and stationary backup power systems. Extended duty cycles and harsh operating environments concentrate demand in German manufacturing clusters with established technician certification programs.
Electric vehicles anchor provider balance sheets. Renewable energy storage is gaining share fastest.
Battery Type:
Chemistry selection determines residual value recovery timelines and second-life application economics.
- Lithium-Ion:NMC, LFP, and NCA cathode configurations occupy the bulk of deployed capacity. Established recycling reverse logistics in Germany and China support lease portfolio management at scale.
- Lead-Acid:Mature chemistry with compressed lease pricing due to limited cycle life. Industrial backup power applications in India's commercial hubs retain this chemistry for cost-sensitive deployments.
- Nickel-Metal Hydride:Hybrid electric vehicle applications and select consumer electronics. Japan's METI technology roadmaps show declining allocation for new lease origination as lithium-ion costs compress.
- Solid-State:Emerging chemistry with extended cycle warranties enabling premium lease pricing. China's MIIT GB standards development and Germany's automotive OEM pilot programs concentrate early deployment.
Lithium-ion dominates installed base. Solid-state is where expansion concentrates.
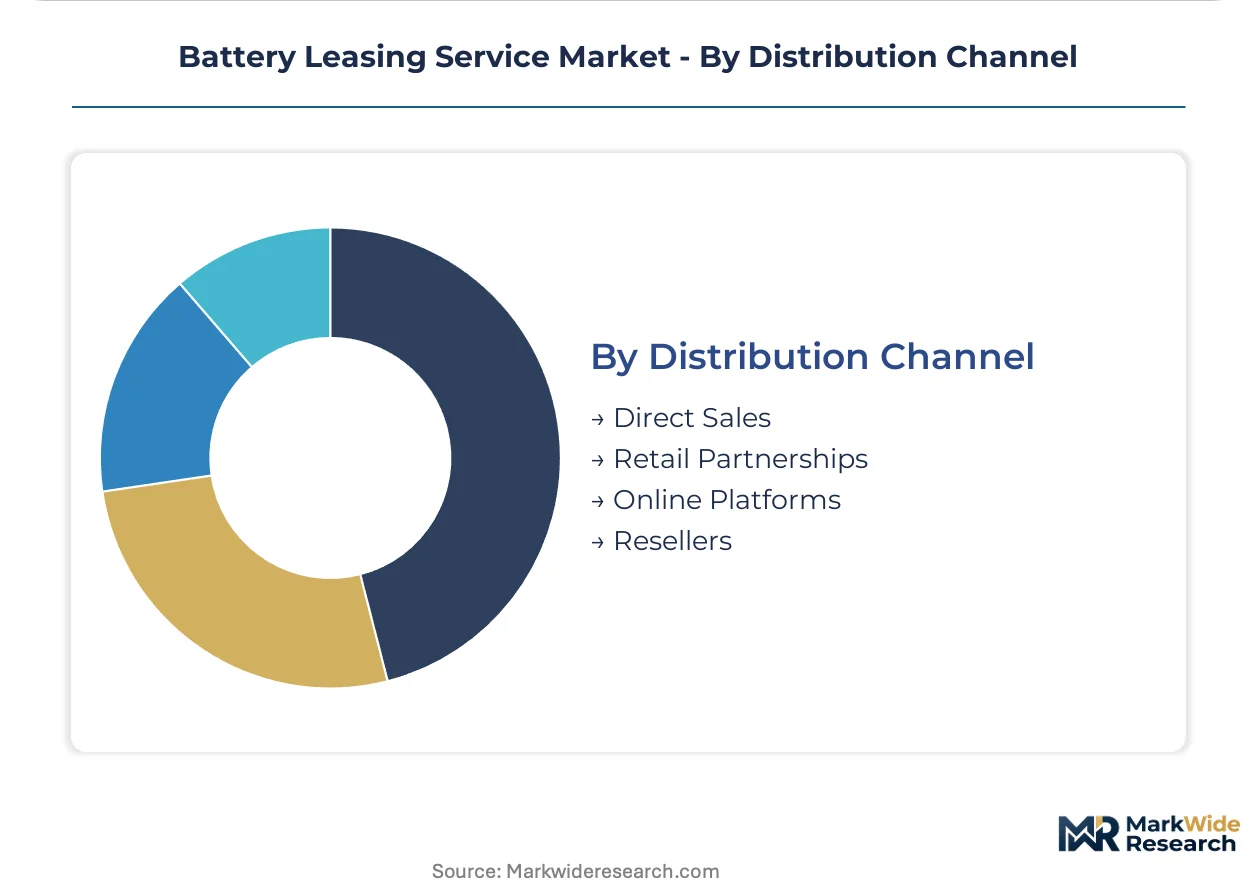
Distribution Channel:
Channel selection determines customer acquisition economics and service integration depth.
- Direct Sales:Provider-owned account teams serve enterprise fleet operators. Germany's commercial vehicle OEMs and energy utilities co-develop leasing infrastructure through direct procurement relationships.
- Retail Partnerships:Electronics retailers and automotive dealerships originate consumer-facing contracts. India's urban centers see two-wheeler battery subscription origination through established dealer networks.
- Online Platforms:Digital origination with automated credit and usage tracking. China's NIO sustains battery-as-a-service subscriptions through integrated mobile platform management.
- Resellers:Third-party brokers aggregate fragmented demand for provider underwriting. Industrial equipment segments in France utilize specialized resellers with vertical expertise in material handling sectors.
Direct sales dominates installed base. Online platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor treats battery leasing as compliance infrastructure, while China's gigafactory belt deploys it as a customer acquisition mechanism. India's two-wheeler corridors and the US commercial fleet hubs each apply distinct risk-transfer logics to the same contractual form.
China
Domestic automakers beyond direct sales are tilting toward service-oriented battery deployment. MIIT issues GB standards governing battery swap interoperability that directly enable network architectures. Contemporary Amperex Technology Co. Ltd. leverages its cell-to-pack manufacturing scale to anchor leasing programs for commercial EV fleets in the Yangtze River Delta.
Germany
Commercial fleet operators convert fastest from ownership to service models under EU Battery Regulation compliance pressure. KBA registration data shows accelerating adoption as OEMs and energy utilities co-develop leasing infrastructure. The manufacturing corridor spanning Bavaria and Baden-Württemberg concentrates swap station deployment for electric commercial vehicles.
United States
Integrated lease-to-own structures tie vehicle financing directly to energy storage performance guarantees. IRA clean vehicle credits reshape total cost of ownership calculations for fleet procurement departments. California's metropolitan transit authorities specify guaranteed capacity thresholds rather than nominal kilowatt-hour ratings in municipal bus electrification tenders.
India
Domestic platform development for two-wheeler and three-wheeler battery subscriptions accelerates under PLI scheme incentives for advanced chemistry cell manufacturing. BIS certification requirements concentrate provider investment in quality infrastructure. Maharashtra and Karnataka urban centers see subscription origination through established dealer networks for last-mile delivery fleets.
France
Utility-scale renewable energy storage installations cycle seasonally, favoring pay-per-use structures over fixed subscriptions. National environmental agencies coordinate enforcement timelines that favor service-based deployment. The Île-de-France region concentrates behind-the-meter lease expansion for commercial building energy management.
Battery Leasing Service Market Vendor Landscape
Capability concentration sits with cell manufacturers possessing vertical integration depth; scale advantage sits with automotive OEMs with captive fleet relationships. The market structures around three tiers: chemistry specialists with manufacturing scale, vehicle integrators with distribution reach, and energy utilities with grid interconnection access. Dominant competitive moves include strategic partnerships between OEMs and energy providers, plus geographic co-development of swap station networks.
Within the chemistry-specialist tier, Contemporary Amperex Technology Co. Ltd. exemplifies manufacturing-scale anchoring of leasing programs. Among vehicle-integrators with subscription-native architectures, NIO occupies a position defined by dedicated swap station networks. Tesla represents the integrated lease-to-own structure that ties vehicle financing to performance guarantees.
| Leading Market Players |
|---|
| Tesla |
| Contemporary Amperex Technology Co. Ltd. |
| NIO |
| Renault Group |
| Gogoro |
| Sun Mobility |
| Oyika |
| Neuron |
| XPENG |
| Others |
Supply Flow & Price Mechanics
South American lithium carbonate processing corridors and Australian spodumene concentrate operations anchor upstream cost structures, concentrating margin capture with cell manufacturers possessing long-term offtake agreements while lease providers downstream absorb residual value volatility through contractual risk transfer mechanisms.
Pricing Analysis
Long-term offtake contracts dominate pricing structures for lithium-ion cell procurement, though spot market exposure persists for cobalt and nickel sulfate inputs. Price differentiation rests on guaranteed capacity thresholds versus nominal kilowatt-hour ratings, with solid-state chemistry configurations commanding premium positioning against lithium-ion standard tiers. Cost compression in lithium carbonate refining is intensifying because Australian hard-rock mine expansions are accelerating feedstock availability. Commercial fleet operators exhibit highest price sensitivity due to total cost of ownership benchmarking against diesel alternatives, while municipal transit authorities demonstrate lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Export control regimes governing semiconductor-grade battery management system firmware and graphite purification technologies are constraining technology transfer flows between designated trading partners. Geographic supply concentration centers on China for cathode active material production, South Korea for cell manufacturing, and Indonesia for nickel processing. Raw material dependencies span lithium carbonate from Chilean salt flats, cobalt hydroxide from the DRC, and synthetic graphite from Heilongjiang province. Single-source vulnerability in spherical graphite anode supply presents structural risk. Distribution runs through direct sales teams serving enterprise fleet operators and online platforms for consumer-facing subscription origination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery ownership substitution by leasing models faces displacement risk from solid-state chemistry direct purchase economics as cycle warranties extend and residual value uncertainty diminishes, requiring incumbents to fortify service-based moats before technology maturation erodes the operational expenditure value proposition.
For Market Incumbents: Build swap station network density as the primary moat against emerging solid-state direct sales competitors. Secure backward integration into recycling reverse logistics to capture residual value recovery and satisfy EU Battery Regulation stewardship mandates. Deepen technician certification pipelines in Germany's manufacturing corridor to defend service response time advantages against modular battery architectures that reduce field maintenance requirements. For New Entrants and Emerging Players: Establish a beachhead in India's two-wheeler subscription segment where PLI scheme incentives are stimulating domestic platform development and established dealer networks lower customer acquisition costs. Target pay-per-use structures for renewable energy storage applications in France's seasonal dispatch markets where incumbent subscription models cannot address utilization variability. Pursue white-label battery-as-a-service partnerships with commercial vehicle OEMs lacking captive leasing infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet management platforms that consolidated during early electrification waves and now face refinancing pressure as interest rate environments shift. Five-to-ten year viability hinges on second-life application economics maturation and grid interconnection queue resolution. Target acquisition archetypes include cell-to-pack manufacturing specialists with established recycling partnerships. Monitor GB standards development progress from China's MIIT as the inflection signal for swap station interoperability investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Swap Station Network Expansion | Density advantages in Germany's manufacturing corridor lock in fleet operator switching costs. |
| Cell-to-Pack Manufacturing Scale-Up | CATL's Yangtze River Delta capacity anchors leasing program unit economics for commercial EVs. |
| Battery Swap Interoperability Certification | MIIT GB standards compliance enables NIO and Gogoro network architecture replication. |
| Recycling Reverse Logistics Integration | Centralized stewardship captures EU Battery Regulation compliance data more efficiently than fragmented ownership. |
| Vehicle-to-Grid Software Platform Development | Bidirectional charging convergence with energy trading creates new revenue streams for fleet lease providers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews, with fleet procurement directors, battery asset managers, and swap station network operators providing operational perspective while cell manufacturing executives and recycling facility operators contributed supply-side intelligence. Secondary validation drew from MIIT GB standards filings, KBA registration databases, EU Battery Regulation implementation guidance, and PLI scheme administrative records. Bottom-up lease contract origination data triangulated against top-down energy storage deployment forecasts to reconcile volume estimates.
Calibration against historical adoption curves in comparable asset-as-a-service markets informed trajectory assumptions across the projection horizon. Segmentation dimensions modeled include service type structure, end-use application velocity, battery chemistry configuration, and distribution channel economics. CAGRs were derived from installed base expansion rates adjusted for technology substitution effects. Forecast inputs incorporated lithium carbonate price volatility bands and grid interconnection queue resolution timelines.
Stress conditions across lithium supply concentration, solid-state chemistry maturation pace, and extended producer responsibility regime enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification mandates and carbon disclosure requirements. Cross-checking against IEA energy storage deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Automobile Rental and Leasing Market