
 India Surveillance Storage Market | 2026-2036
India Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
India Surveillance Storage Market Insights
Aftermarket service revenue for storage lifecycle management is fragmenting across hardware vendors, system integrators, and independent cloud operators. Dell Technologies leverages its enterprise server footprint to anchor large-scale government data center contracts. Seagate Technology Holding PLC specializes in surveillance-optimized hard drive architectures with workload ratings exceeding standard enterprise drives. Hangzhou Hikvision Digital Technology Co Ltd dominates integrated NVR-DVR bundle shipments through its India distribution network.
India surveillance storage encompasses disk arrays, solid-state modules, and cloud repositories engineered for continuous write-intensive video workloads, typically supporting 4K stream ingestion at 30 frames per second with ninety-day retention minimums. The architecture serves law enforcement evidence chains, retail loss prevention, and critical infrastructure perimeter monitoring. Hybrid storage configurations lead current deployments as organizations balance latency-sensitive local retrieval against long-term cloud economics. Cloud storage represents the fastest-expanding segment, driven by banking compliance mandates requiring off-site redundancy for ATM and branch footage. NVR systems sustain margin pools in transportation hubs where real-time analytics demand edge-computing proximity.
BIS certification requirements for electronic storage devices shape hardware import pathways and local assembly incentives under the PLI scheme. CDSCO guidelines intersect where medical facility surveillance integrates with patient data protection, while state police departments enforce retention protocols under the Indian Evidence Act. Stakeholders must weigh domestic manufacturing qualification timelines against the accelerating shift to software-defined storage orchestration.
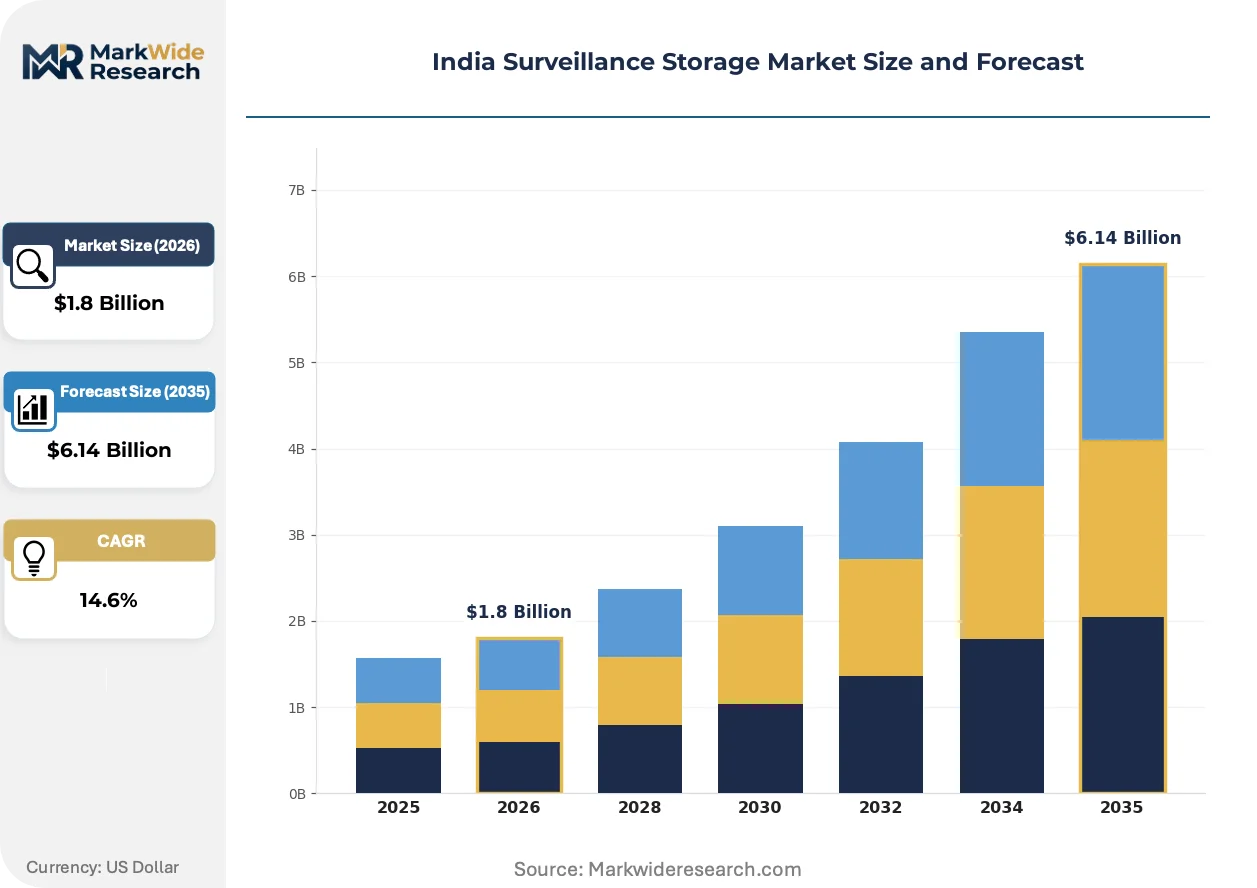
Market Dynamics
The shift from proprietary NVR hardware to software-defined storage architectures is fragmenting procurement authority between municipal IT departments and specialized system integrators across Maharashtra and Karnataka.
Growth Catalysts
- Smart city infrastructure mandates:Mumbai and Delhi municipal corporations are deploying network video recorders with centralized command centers for traffic management and public safety monitoring.
- PLI scheme for electronics manufacturing:Local assembly incentives under India's Production Linked Incentive scheme are accelerating domestic production of surveillance-optimized storage hardware.
- Banking compliance requirements:RBI mandates for off-site redundancy of ATM and branch footage are pushing financial institutions toward hybrid cloud storage configurations.
Market Restraints
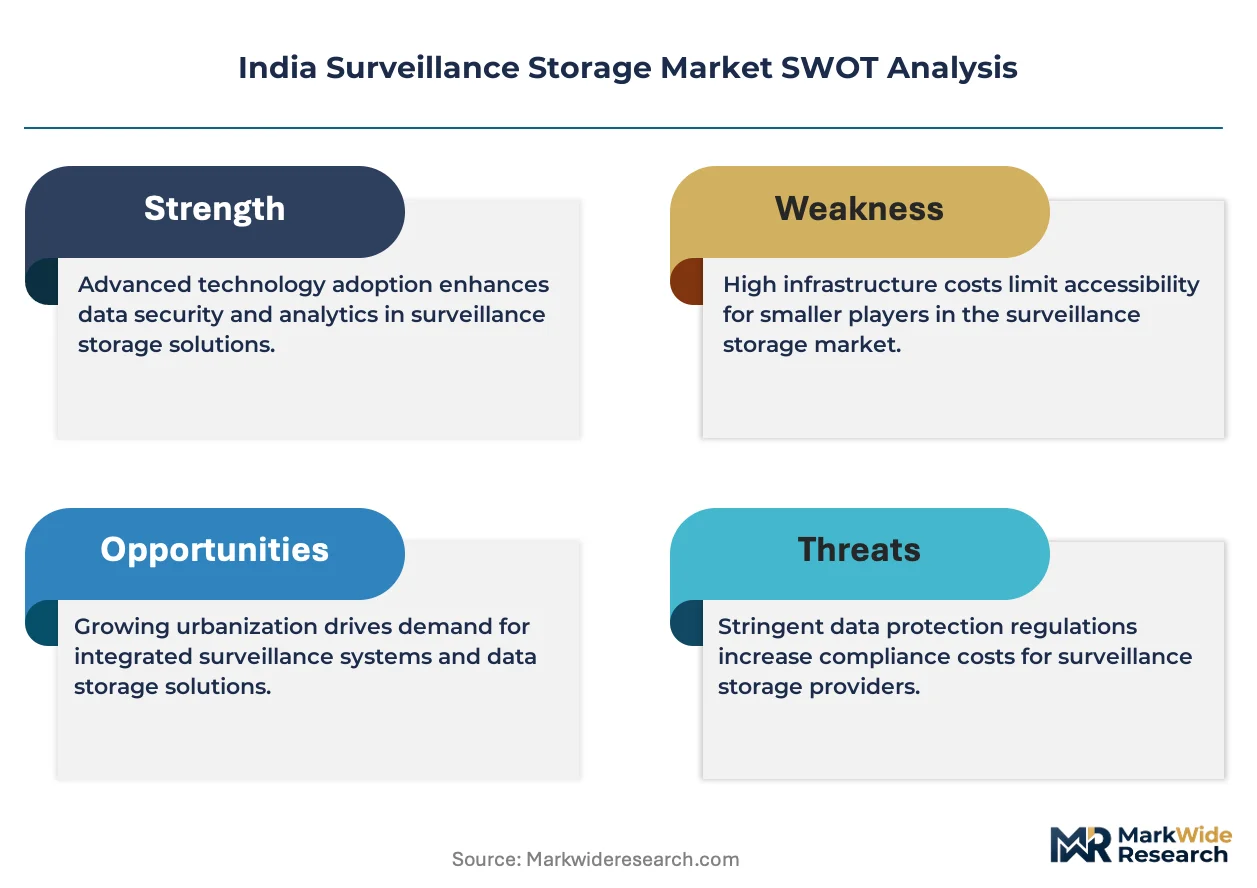
- BIS certification timelines:Bureau of Indian Standards approval processes for electronic storage devices create 4-6 month delays in hardware import pathways and product launches.
- Flash memory cost volatility:NAND flash price fluctuations constrain solid-state module adoption for continuous write-intensive surveillance workloads.
- Concentrated component sourcing:Hard drive spindle motors and controller chips depend on single-source suppliers in East Asian manufacturing clusters.
Strategic Opportunities
- Tier-2 city safe city programs:Surat, Pune, and Hyderabad are expanding camera density per square kilometer with state police department funding.
- Edge-to-cloud orchestration convergence:Transportation hubs are deploying AI-enabled NVR systems with real-time analytics and automated tiering to cloud archives.
- Healthcare surveillance integration:CDSCO guidelines for patient data protection are creating demand for encrypted storage in medical facility monitoring systems.
Industry Challenges
- Video forensics expertise shortage:Law enforcement agencies lack trained personnel for evidence chain management and metadata authentication.
- Legacy analog infrastructure retrofit costs:Small commercial establishments face capital constraints when migrating from DVR to IP-based storage architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Surveillance Storage Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NVR, DVR, Cloud Storage, Hybrid Storage Technology: IP Cameras, Analog Cameras, Wireless Cameras, Smart Cameras End User: Retail, Transportation, Government, Banking Installation Type: Indoor, Outdoor, On-premises, Remote |
| Companies Covered | Prama India Pvt Ltd, Dahua Technology Co Ltd, Hangzhou Hikvision Digital Technology Co Ltd, Dell Technologies, Seagate Technology Holding PLC, CP Plus International, Axis Communications AB, NetApp, Inc., Sparsh CCTV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Surveillance Storage Market Trends and Innovations
Storage virtualization is compressing hardware refresh cycles while regulatory mandates are forcing architectural decisions toward hybrid configurations that balance local latency against cloud economics.
Software-defined storage controllers are virtualizing physical disk arrays into pooled resource pools that municipal surveillance networks in Delhi and Mumbai deploy across distributed edge locations. State police departments are adopting these platforms to unify storage management across heterogeneous camera vendor environments. This virtualization is collapsing the traditional separation between NVR hardware and enterprise storage systems.
The Ministry of Home Affairs retention mandate for commercial establishment footage is forcing retailers to architect ninety-day minimum storage with automated tiering policies. Banking compliance teams are interpreting RBI off-site redundancy requirements as mandates for geographically separated cloud repositories. Healthcare facilities face intersecting CDSCO patient data protection rules that encrypt surveillance streams before archival.
System integrators are unbundling after-sales service contracts from hardware procurement, selling storage lifecycle management as standalone subscriptions. Municipal IT departments in Maharashtra prefer this model for smart city deployments to shift capital expenditure to operational budgets. Karnataka state police are piloting similar arrangements for safe city program maintenance.
India Surveillance Storage Market Segmentation
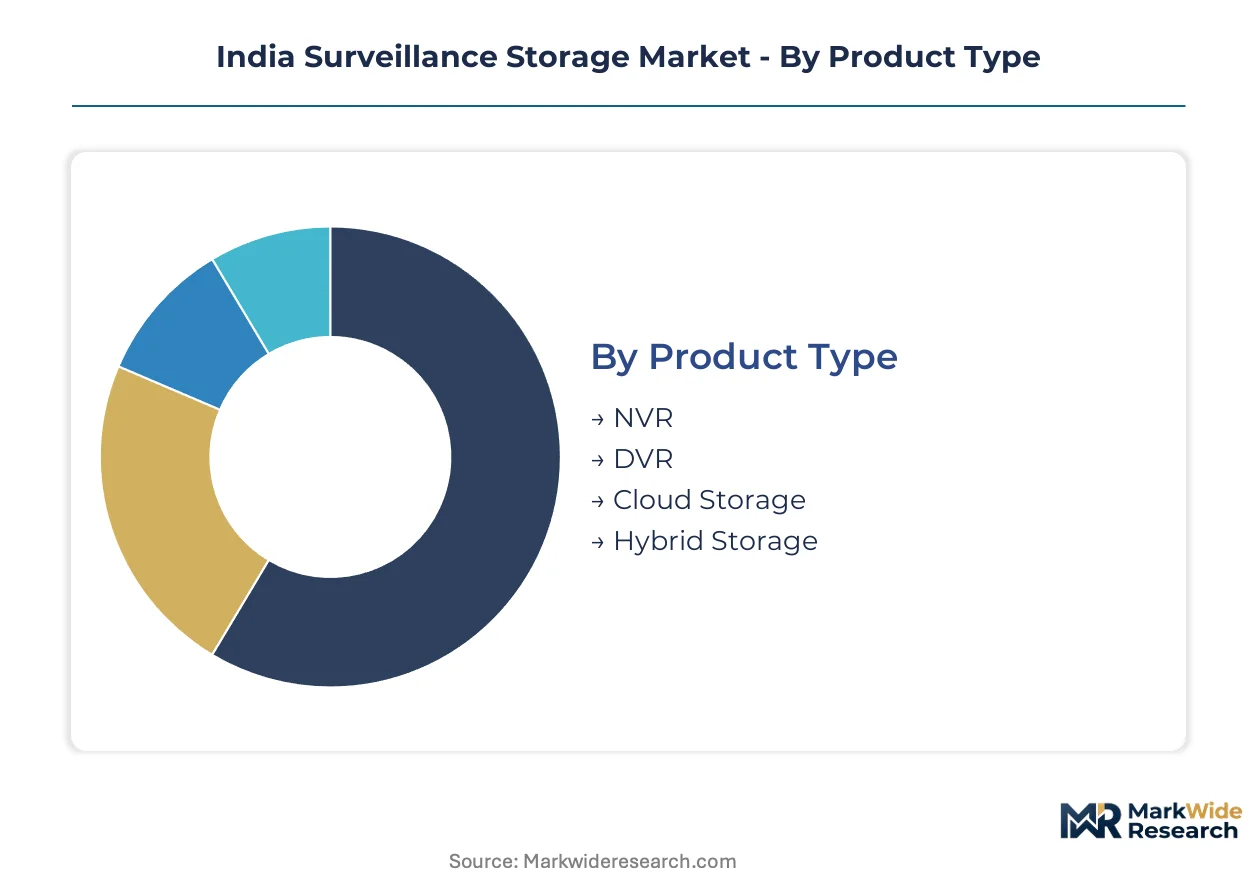
Storage procurement in India surveillance diverges sharply across product architectures, with municipal buyers favoring centralized cloud repositories while transportation operators demand edge-resident NVR systems. Segment boundaries are blurring as hybrid configurations absorb functions from discrete hardware categories.
Product Type:
Cost tier separates the India surveillance storage market into four distinct procurement buckets, from capital-intensive on-premise hardware to metered cloud subscriptions.
- NVR:Network video recorders process IP camera streams through embedded Linux controllers with RAID-5 redundancy for 64-channel ingestion. Maharashtra safe city programs in Mumbai and Pune deploy rack-mounted NVR clusters at traffic command centers where real-time analytics demand sub-100ms retrieval latency.
- Cloud Storage:Metered object repositories with automated tiering policies archive footage across geographically separated availability zones. RBI-mandated off-site redundancy for banking footage accelerates adoption among private sector lenders seeking to shift capital expenditure to operational budgets.
- DVR:Legacy analog-to-digital conversion units with coaxial input interfaces and proprietary compression codecs. Small commercial establishments in tier-2 cities retain these systems due to retrofit capital constraints.
- Hybrid Storage:Architectures combining local SSD caching with asynchronous cloud replication for 90-day retention minimums. Retail chains deploy these configurations to satisfy Ministry of Home Affairs mandates while preserving edge accessibility.
NVR commands the established base. The steepest expansion runs through Cloud Storage.
Technology:
Application context dictates camera technology selection, with perimeter monitoring demanding ruggedized hardware and indoor retail favoring discreet form factors.
- IP Cameras:Ethernet-powered devices transmitting H.265-compressed streams at 4K resolution with Power over Ethernet sourcing. Karnataka state police safe city deployments in Bangalore specify these units for centralized NVR aggregation.
- Smart Cameras:Edge-computing devices with onboard GPU acceleration for real-time object detection and behavioral analytics. Delhi Metro Rail Corporation deploys these at station platforms to reduce backhaul bandwidth to central storage.
- Analog Cameras:Coaxial-output devices with CVBS signaling and limited resolution scalability. Legacy infrastructure in government facilities continues to source these for compatibility with existing DVR investments.
- Wireless Cameras:Wi-Fi or cellular-connected units with battery backup for rapid deployment scenarios. Temporary surveillance for public events in Hyderabad utilizes these to avoid cabling infrastructure.
IP Cameras anchor current procurement volumes. Smart Cameras are climbing the fastest as AI-enabled analytics penetrate transportation and critical infrastructure.
End User:
Customer type determines retention protocols, encryption requirements, and integration complexity across the India surveillance storage value chain.
- Government:Municipal corporations and state police departments operating centralized command centers with 180-day evidence retention. Mumbai and Delhi smart city authorities specify these systems for traffic management and public safety monitoring.
- Banking:Financial institutions subject to RBI off-site redundancy mandates for ATM and branch footage. Private sector banks deploy hybrid cloud configurations with geographically separated replication.
- Retail:Commercial establishments complying with Ministry of Home Affairs video retention minimums for loss prevention. Organized retail chains in Maharashtra automate tiering policies to balance local accessibility against long-term archive economics.
- Transportation:Metro rail authorities and airport operators requiring real-time analytics with edge-computing proximity. Delhi Metro and Bangalore International Airport specify NVR systems with GPU acceleration for passenger flow optimization.
Government contracts anchor the revenue base. Banking compliance requirements are gaining share fastest as RBI mandates harden.
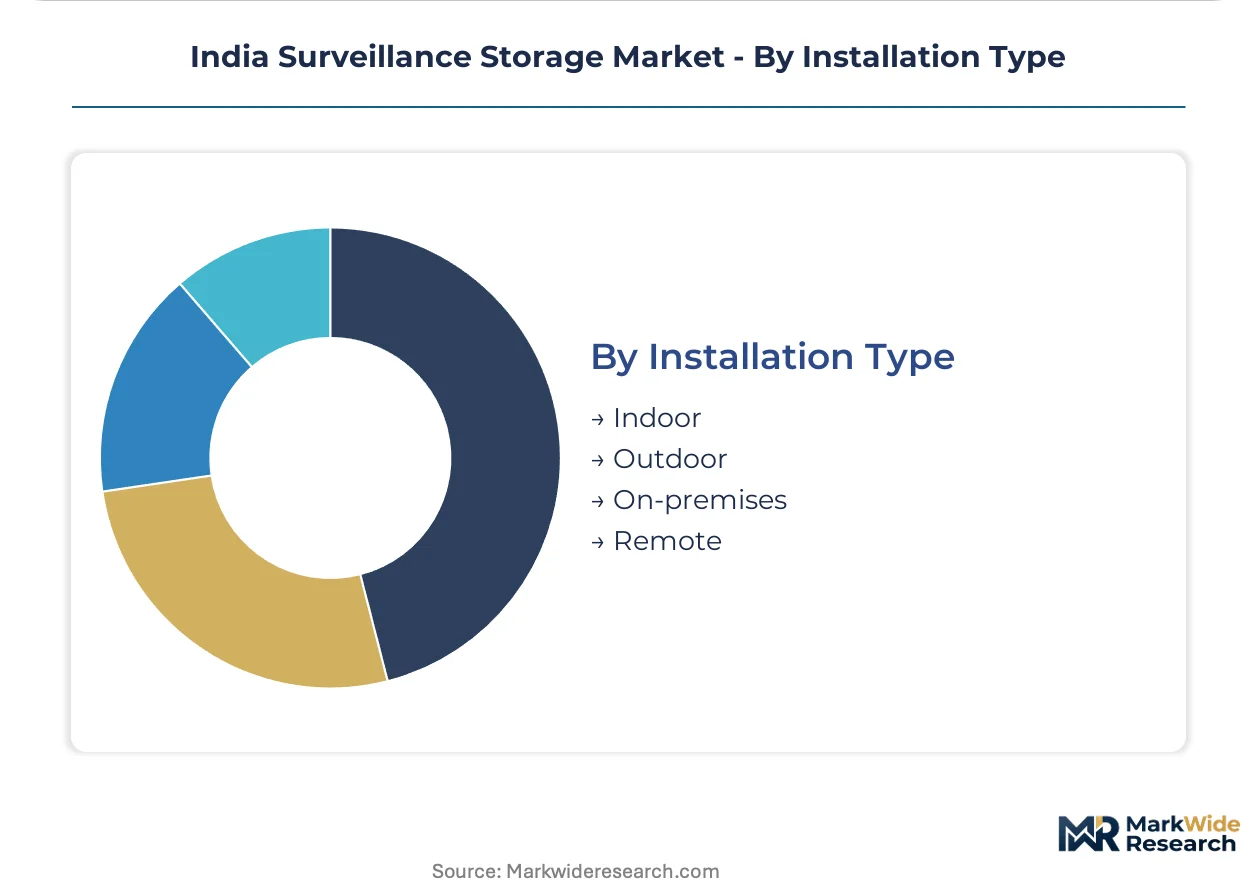
Installation Type:
Volume and environmental exposure shape hardware specifications, with outdoor deployments demanding ruggedized enclosures and wide temperature tolerances.
- Outdoor:Weather-sealed housings with IP67 ingress protection and integrated heating elements for condensation management. Mumbai municipal traffic surveillance deploys these along arterial roads with centralized NVR backhaul.
- On-premises:Local storage architectures with dedicated server rooms and UPS backup for continuous operation. Karnataka state police safe city programs specify these for evidence chain integrity.
- Indoor:Climate-controlled environments with standard enterprise storage form factors. Banking branches and retail outlets deploy these for customer-facing camera coverage.
- Remote:Distributed installations with cellular or satellite connectivity for temporary or geographically isolated sites. Border surveillance and rural infrastructure monitoring utilize these configurations.
Outdoor installations command the established base. On-premises architectures are expanding most quickly as hybrid cloud adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan buyers in Mumbai and Delhi exhibit low price elasticity for compliant storage architectures, while tier-2 city procurement remains acutely sensitive to capital expenditure constraints. This demand-elasticity contrast shapes vendor go-to-market strategies across Indian states.
Maharashtra
Mumbai's smart city command centers drive centralized NVR cluster deployment for traffic management analytics. The state police safe city program mandates 180-day evidence retention under Indian Evidence Act protocols. Pune municipal corporations are expanding camera density per square kilometer with hybrid cloud configurations.
Karnataka
Bangalore's technology parks generate concentrated demand for banking-compliant hybrid storage with RBI-mandated off-site redundancy. The state safe city program specifies IP camera aggregation standards for centralized NVR architectures. Mysore and Hubli are piloting edge-to-cloud orchestration for tier-2 surveillance networks.
Delhi-NCR
The national capital's municipal corporations deploy rack-mounted NVR systems with sub-100ms retrieval latency for real-time public safety monitoring. Ministry of Home Affairs retention mandates for commercial establishments push retailers toward automated tiering policies. Noida and Gurugram banking corridors concentrate private sector hybrid cloud adoption.
Telangana
Hyderabad's municipal surveillance networks leverage state police funding for camera density expansion across arterial corridors. The city's pharmaceutical clusters drive CDSCO-aligned encrypted storage demand for medical facility monitoring. Cyberabad technology zones anchor enterprise-grade surveillance storage procurement.
Gujarat
Surat's diamond trading hubs and textile clusters generate loss-prevention storage demand with ninety-day retention minimums. The state's industrial corridor projects specify outdoor-rated storage architectures with IP67 ingress protection. Ahmedabad municipal corporations are retrofitting analog infrastructure toward IP-based systems.
India Surveillance Storage Market Competitive Landscape
Capability concentration sits with integrated hardware-software specialists; scale advantage sits with enterprise storage incumbents with government data center footprints. The vendor base stratifies across three tiers: multinational technology conglomerates anchoring large-scale municipal contracts, regional system integrators unbundling after-sales service subscriptions, and specialized storage hardware fabricators optimizing for continuous write-intensive workloads. Dominant competitive moves include PLI scheme qualification for domestic manufacturing incentives and software-defined storage orchestration partnerships with state police departments.
Within the multinational technology tier, Dell Technologies and Seagate Technology Holding PLC occupy anchor positions for enterprise and surveillance-optimized hardware respectively. Hangzhou Hikvision Digital Technology Co Ltd exemplifies the integrated solutions archetype through its India distribution network. These three entities represent distinct competitive vectors: server infrastructure leverage, specialized drive architecture, and bundled NVR-DVR shipment scale.
| Leading Market Players |
|---|
| Prama India Pvt Ltd |
| Dahua Technology Co Ltd |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Dell Technologies |
| Seagate Technology Holding PLC |
| CP Plus International |
| Axis Communications AB |
| NetApp, Inc. |
| Sparsh CCTV |
| Others |
Pricing and Supply Chain Analysis
The Chennai-Visakhapatnam freight corridor's escalating logistics costs amplify price differentiation between domestically assembled NVR hardware and fully imported enterprise storage arrays. Supply concentration in East Asian spindle motor manufacturing tightens vendor pricing power, while BIS certification delays force buyers toward premium-tier certified alternatives.
Pricing Analysis
After-sales service contracts now drive lifetime value capture, with system integrators unbundling storage lifecycle management from hardware procurement. Three-tier pricing structure across premium, standard, and economy levels separates PLI-qualified domestic assembly from import-dependent configurations. Cost compression in standard-tier NVR hardware intensifies because municipal IT departments in Maharashtra and Karnataka are shifting capital expenditure to operational budgets. Small commercial establishments in tier-2 cities exhibit the highest price sensitivity, whereas banking compliance teams in Mumbai and Delhi demonstrate minimal elasticity for RBI-mandated redundancy architectures.
Supply Chain Analysis
Export-control restrictions on advanced GPU accelerators and high-density NAND controllers limit component flows into Indian assembly facilities. Hard drive spindle motors and controller chips draw from concentrated manufacturing in Taiwan, South Korea, and Japan. Raw material dependencies span rare-earth magnets for motor assemblies, silicon wafers for controller fabrication, and specialized aluminum substrates for disk platters. Single-source vulnerability in controller chip supply creates systemic risk for surveillance-optimized drive production. Distribution runs through authorized distributor networks anchored in Mumbai and Bangalore, with direct enterprise sales for government data center contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India surveillance storage market fragments across procurement authority shifts, as municipal IT departments wrest storage architecture decisions from traditional security integrators. This disaggregation creates specialized niches for software-defined orchestration and lifecycle subscription providers.
For Market Incumbents: Insulate government data center contracts through PLI scheme qualification and localized assembly investments. Deepen backward integration into controller firmware development to reduce East Asian chip dependency. Anchor position by embedding storage virtualization platforms within Maharashtra and Karnataka state police safe city programs before competitive alternatives mature.
For New Entrants and Emerging Players: Tier-2 city commercial banks with pending RBI compliance deadlines represent the most penetrable entry point for hybrid cloud storage offerings. Healthcare facilities navigating CDSCO encryption mandates for patient-integrated surveillance constitute a second white-space target. Pursue system integrator partnerships rather than direct hardware sales to bypass established distribution bottlenecks.
For Investors and Strategic Acquirers: Software-defined storage orchestration specialists with state police department pilots command premium positioning. Long-term viability hinges on regulatory compliance automation capabilities rather than hardware scale. Monitor BIS certification queue lengths as an inflection indicator; extended delays accelerate domestic assembly premiums and software-centric valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Qualification | Domestic assembly incentives under India's PLI scheme unlock government contract eligibility for surveillance storage hardware. |
| Software-Defined Storage Development | Virtualization platforms enable Maharashtra and Karnataka police departments to unify heterogeneous camera vendor environments. |
| Edge-to-Cloud Orchestration Partnership | Transportation authorities in Delhi Metro and Bangalore Airport deploy AI-enabled NVR systems with automated cloud tiering. |
| After-Sales Service Unbundling | Standalone storage lifecycle subscriptions shift municipal procurement from capital expenditure to operational budgets. |
| Healthcare Encryption Integration | CDSCO-aligned encrypted storage architectures capture medical facility surveillance demand intersecting patient data protection. |
Research Methodology
The analysis maps NVR hardware, cloud repositories, hybrid configurations, and software-defined architectures, each validated through municipal IT directors, state police procurement officers, banking compliance leads, and system integrator technical heads. Primary fieldwork combined with secondary validation from BIS certification records, RBI circulars on ATM surveillance, Ministry of Home Affairs retention mandates, and PLI scheme disclosure filings. Bottom-up channel shipment estimates triangulate against top-down government budget allocation analysis.
Assumption sets held regulatory enforcement timelines and NAND flash cost curves fixed while varying smart city deployment acceleration and banking compliance interpretation strictness. Segmentation modeling spans product architecture, technology tier, end-user vertical, and installation environment across the projection horizon. CAGRs derive from installed base expansion rates, replacement cycle compression, and cloud migration velocity. Forecast inputs incorporate camera density targets from Maharashtra and Karnataka safe city programs alongside RBI-mandated redundancy interpretation trends.
Practitioners should monitor BIS certification processing delays and PLI scheme revision announcements for early signals of domestic supply constraint. Forecasts reflect assumptions about regulatory enforcement continuity and component import pathway stability. Material shifts in export-control regime stringency or state-level safe city funding allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
France Surveillance Camera Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market