
 Smart Camera System Market | 2026-2036
Smart Camera System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Camera System Market Analytics
The capital-intensity divergence between in-house semiconductor fabrication and outsourced sensor assembly is unwinding competitive stability at the high end. Hangzhou Hikvision Digital Technology Co., Ltd. leverages captive chip design to dominate large-scale government tenders across Asia. Sony Corporation sustains premium positioning through proprietary CMOS image sensor architectures that anchor professional broadcast and cinematography segments. Robert Bosch GmbH competes on integrated automotive-to-security crossover technology, extending its industrial sensor expertise into smart city infrastructure.
A smart camera system integrates optical sensors, embedded processors, and network interfaces to capture, analyze, and transmit visual data without continuous human oversight. These systems typically incorporate edge-AI chipsets capable of real-time object detection at frame rates exceeding 30 fps, serving security, automation, and analytics applications across commercial and public environments. IP-Based and Cloud-Connected technologies command the fastest expansion as enterprises migrate from legacy analog DVR architectures to subscription-managed video platforms. Outdoor Cameras generate disproportionate margin pools due to weatherproofing requirements and extended warranty liabilities that filter out low-cost competitors.
The EU AI Act restricts biometric identification deployments in public spaces, forcing manufacturers to reengineer analytics pipelines for privacy-compliant edge processing. China's SAMR enforces GB/T cybersecurity standards on networked cameras, creating a dual-certification burden for products serving both European and Chinese buyers. India's BIS mandatory registration scheme for electronic surveillance equipment adds a third compliance layer. Stakeholders must monitor which regulatory jurisdiction achieves extraterritorial reach first, as that standard will effectively set the baseline for global product architecture decisions.
Market Dynamics
The migration from centralized cloud analytics to edge-AI processing is redistributing value capture across the smart camera value chain, forcing incumbents to rearchitect hardware-software integration strategies around on-device inference capabilities.
Growth Catalysts
- EU AI Act biometric restrictions:Privacy-compliant edge processing mandates are accelerating demand for anonymized analytics pipelines that process data locally without transmitting raw imagery to central servers.
- Smart city infrastructure modernization:Metropolitan traffic management programs in Germany and Singapore are procuring edge-computing camera networks capable of real-time vehicle flow optimization and incident detection.
- GB/T cybersecurity standards:China's SAMR enforcement creates a certification moat that advantages domestic manufacturers serving government and critical infrastructure tenders.
Market Restraints
- CMOS image sensor supply concentration:Premium sensor fabrication concentrates among a handful of Asian foundries, exposing procurement timelines to geopolitical friction and capacity allocation decisions.
- Edge-AI chipset cost structure:Advanced neural processing units carry 3-4x the unit cost of legacy video encoding silicon, compressing margins on mid-tier product lines.
- India BIS mandatory registration:Extended certification timelines for electronic surveillance equipment delay market entry for new suppliers and refresh cycles for established portfolios.
Strategic Opportunities
- Automotive-to-security technology convergence:ADAS-derived computer vision algorithms are migrating into perimeter security applications, enabling Tier-1 automotive suppliers to capture adjacent market share.
- Subscription-managed video platforms:Enterprise buyers are displacing capital-intensive DVR purchases with recurring-revenue cloud services, restructuring vendor cash flow profiles toward predictable SaaS economics.
- Outdoor camera weatherproofing specialization:Extended warranty liabilities and ingress protection requirements filter out low-cost competitors, creating margin pools for engineered solutions in harsh-environment deployments.
Industry Challenges
- Dual-certification architecture burden:Products serving both European and Chinese buyers must simultaneously satisfy GDPR-derived privacy constraints and GB/T cybersecurity mandates, multiplying firmware development and testing overhead.
- Legacy analog infrastructure integration:Enterprise security departments face complex migration paths from coaxial-based DVR systems to IP-connected edge-AI architectures, requiring staged capital deployment and staff retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Camera System Market |
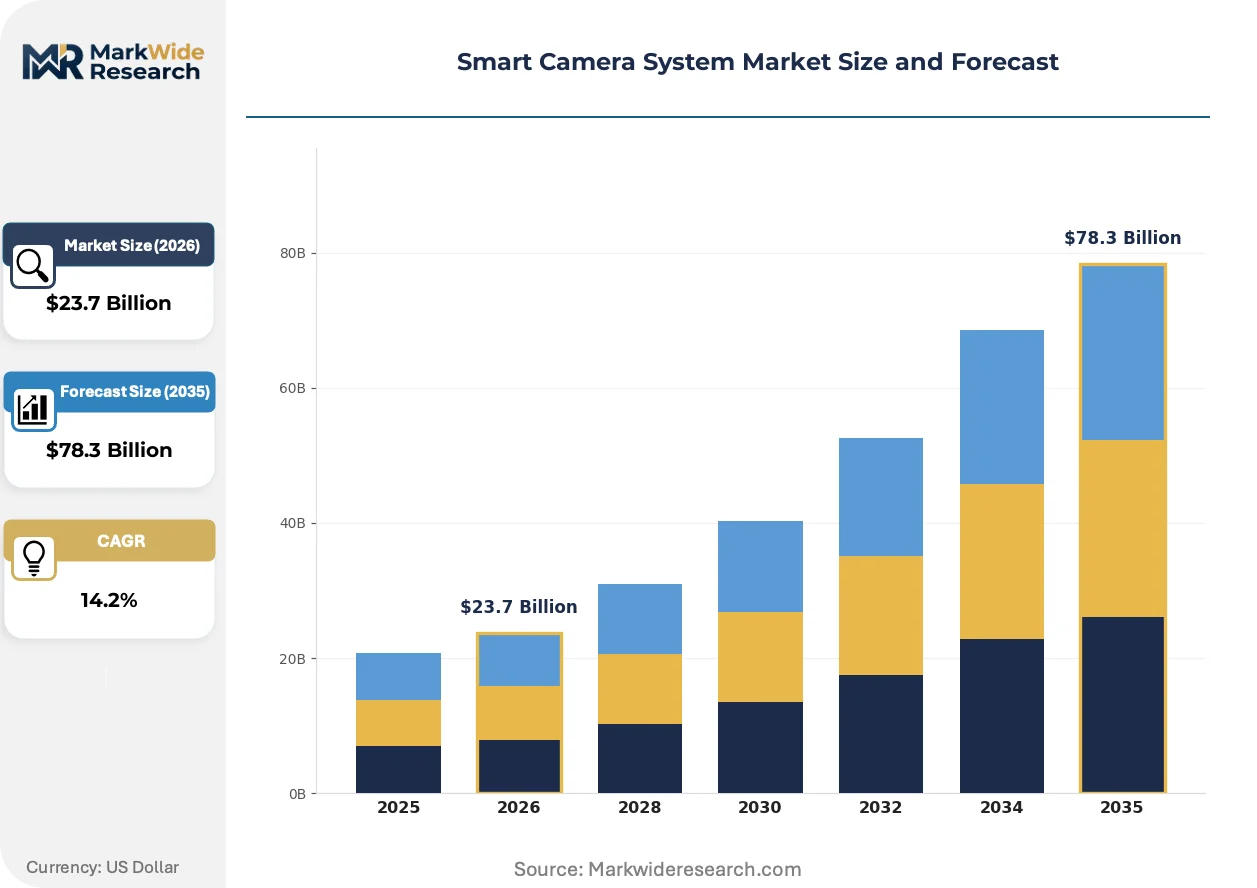
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cameras, Outdoor Cameras, PTZ Cameras, Bullet Cameras Technology: Analog, Digital, IP-Based, Cloud-Connected Application: Retail Security, Home Automation, Traffic Monitoring, Industrial Surveillance End User: Residential Users, Business Owners, Government Agencies, Event Organizers |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Sony Corporation, Samsung Electronics, Arlo Technologies, Inc., Canon Inc., Panasonic Corporation, Robert Bosch GmbH, ADT Inc., Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Camera System Market Evolving Landscape
Computational photography and on-device machine learning are converging to redefine performance benchmarks, while regulatory fragmentation across major economies forces divergent product roadmaps that complicate global scale economics.
Edge-AI inference engines are decomposing the traditional separation between camera hardware and backend analytics servers. Enterprise security buyers in financial services and critical infrastructure are deploying systems capable of 30+ fps object detection without network dependency. This architecture is decomposing value capture from centralized software vendors toward silicon-integrated system designers.
China's GB/T video surveillance standards and the EU AI Act are operating on divergent privacy-versus-security assumptions. The EU AI Act restricts biometric identification in public spaces, forcing reengineering of facial recognition pipelines for opt-in consent workflows. Professional broadcast and cinematography segments face the most complex compliance burden as their products cross multiple jurisdictional thresholds.
Buyers are unbundling after-sales service from hardware procurement, demanding API-accessible analytics platforms that integrate with existing security operations center workflows. Value-added resellers and systems integrators are capturing margin previously held by manufacturers through managed service overlays. This pattern is most pronounced in United States metropolitan public safety deployments where procurement authority has consolidated toward centralized IT departments.
Smart Camera System Market Segmentation
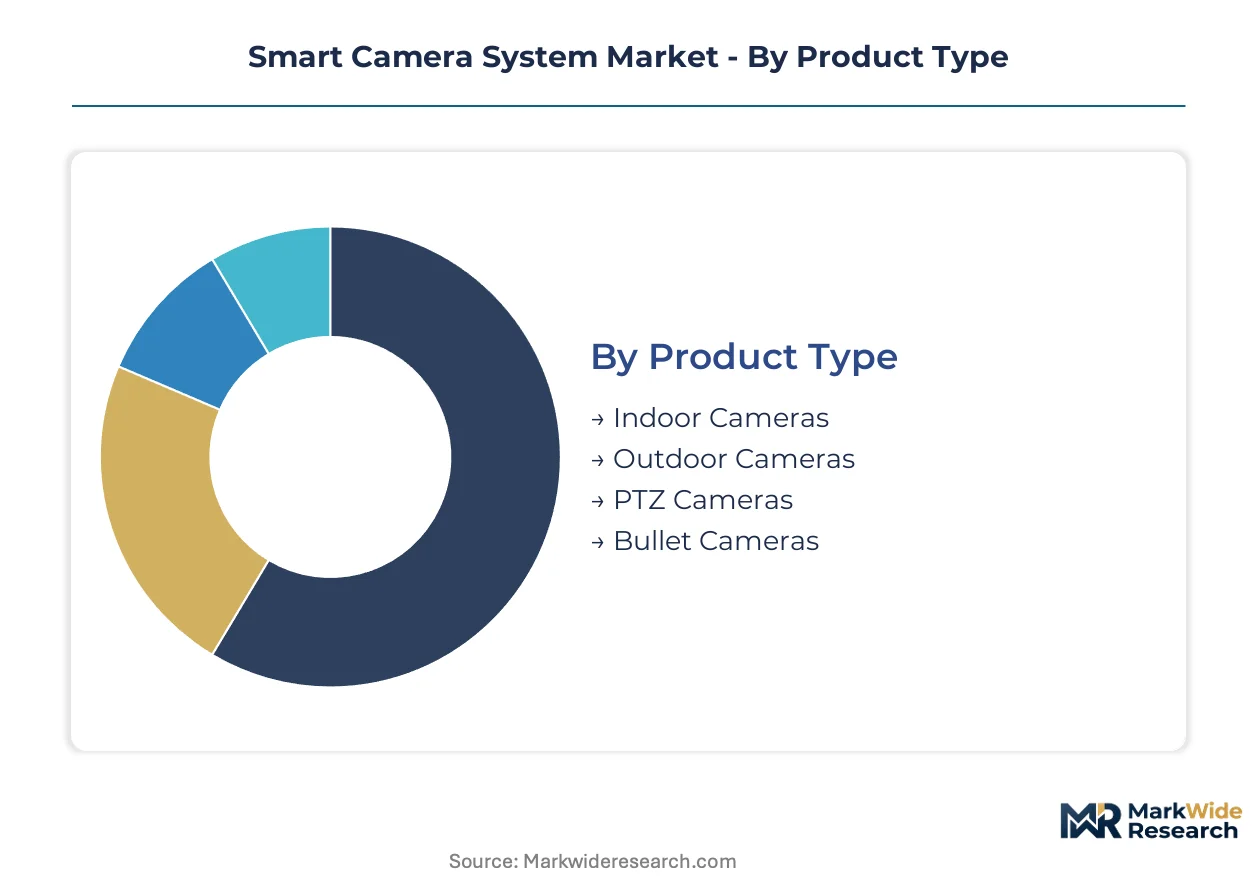
Segmentation in smart camera systems reveals how hardware specifications, connectivity architectures, and deployment contexts reshape procurement patterns. Buyers channel investments toward form factors and technologies that balance edge-AI capability against total cost of ownership across security, automation, and public infrastructure use cases.
Product Type:
Channel mix varies sharply by mounting environment and weather exposure, with outdoor specifications commanding premium distribution through systems integrators while indoor units flow through retail and e-commerce.
- Indoor Cameras:Compact dome and cube form factors integrate Wi-Fi connectivity and passive infrared motion detection for residential and small commercial deployments. Demand clusters in US metropolitan apartment complexes and Indian co-working spaces where cloud-managed multi-tenant access drives recurring subscription attach rates.
- Outdoor Cameras:Weatherproof housings with IP66+ ingress protection and integrated heaters sustain operation across temperature extremes from German industrial zones to Singapore's tropical humidity. Extended warranty liabilities and corrosion-resistant material specifications filter out low-cost competitors, creating margin concentration for engineered solutions.
- PTZ Cameras:Pan-tilt-zoom mechanisms with optical zoom ranges exceeding 30x serve perimeter monitoring and critical infrastructure applications.
- Bullet Cameras:Fixed-lens cylindrical housings dominate cost-sensitive corridor and entryway deployments in retail and logistics facilities.
Outdoor Cameras dominate installed base in government and industrial tenders. Indoor Cameras represent where expansion concentrates as residential smart home penetration deepens.
Technology:
Cost tier stratification separates legacy infrastructure refresh cycles from greenfield edge-AI deployments, with subscription economics favoring cloud-connected architectures over capital-intensive on-premise storage.
- Analog:Coaxial-based CVBS signal transmission persists in legacy retail and small commercial installations where DVR replacement cycles lag technology adoption curves. Demand concentrates in India's tier-2 cities and Southeast Asian manufacturing corridors where BIS certification delays and budget constraints extend equipment lifecycles.
- Digital:HD-TVI and HD-CVI bridge formats enable 1080p resolution over existing coaxial cabling, serving incremental upgrade paths for cost-constrained facility managers.
- IP-Based:Ethernet-powered cameras with ONVIF interoperability form the backbone of enterprise security networks, with Power-over-Ethernet simplifying installation in US financial services and German automotive facilities.
- Cloud-Connected:Direct-to-cloud architectures with edge preprocessing eliminate NVR hardware, restructuring vendor economics toward recurring SaaS revenue models.
Analog maintains residual installed base in emerging markets. Cloud-Connected architectures are climbing the fastest as enterprise buyers displace capital-intensive DVR purchases.
Application:
Volume concentration tracks urbanization patterns and regulatory enforcement intensity, with traffic management and critical infrastructure commanding multi-year procurement cycles distinct from consumer retail flows.
- Retail Security:Point-of-sale integration and shrinkage analytics drive deployment in US big-box chains and European grocery networks, with edge-AI enabling real-time theft pattern recognition without cloud latency.
- Home Automation:Video doorbells and interior monitoring devices integrate with voice assistants and smart locks, with demand surging in China's tier-1 cities and US suburban markets.
- Traffic Monitoring:Vehicle flow optimization and incident detection in Singapore's expressway network and Germany's autobahn corridors require 30+ fps edge inference and V2X integration.
- Industrial Surveillance:Hazard detection and process monitoring in oil and gas facilities and chemical plants demand explosion-proof housings and IECEx certification.
Retail Security dominates unit shipments. Traffic Monitoring is where steepest expansion trajectory materializes as smart city infrastructure modernization accelerates.
End User:
Customer type determines procurement authority concentration and service attach rates, with government tenders favoring integrated systems integrators while residential buyers route through retail and direct-to-consumer channels.
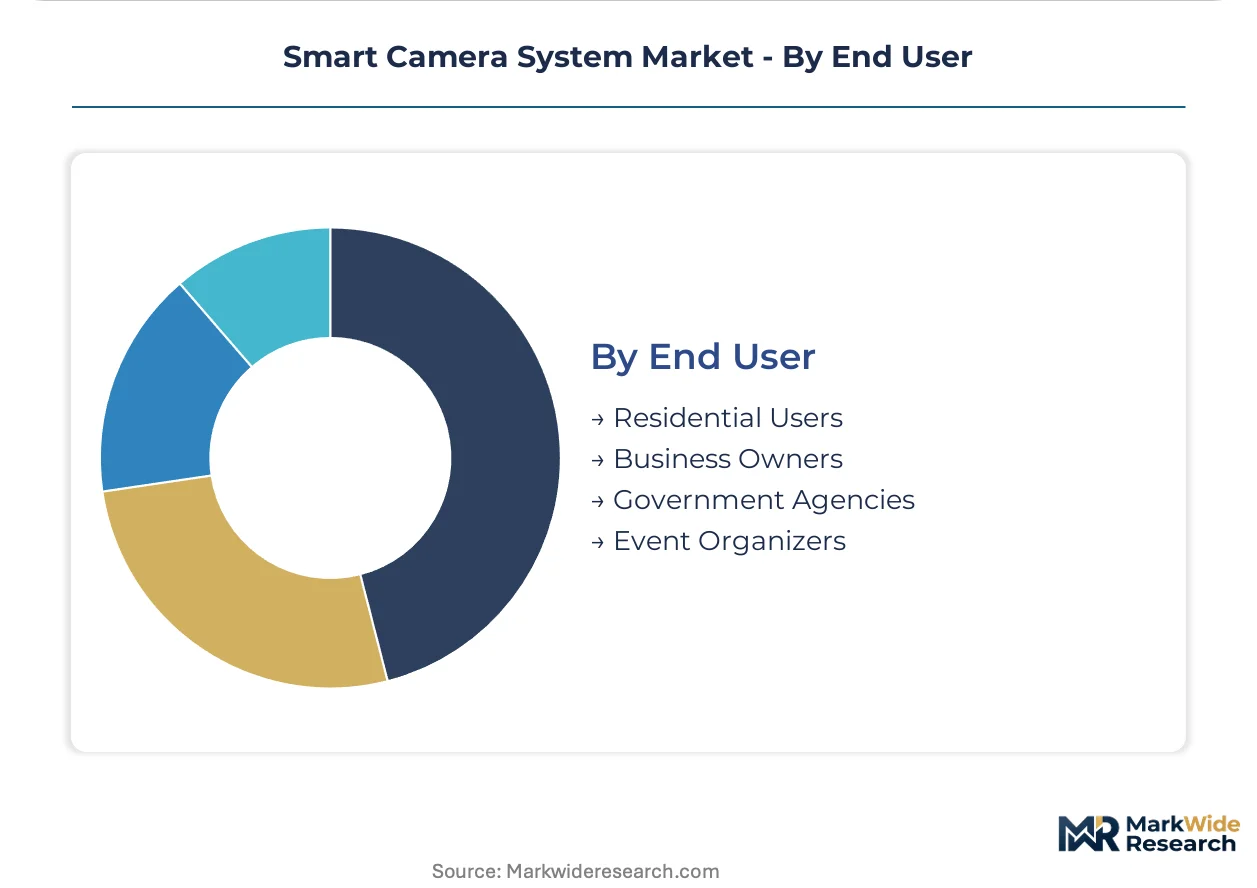
- Residential Users:DIY installation preferences and mobile-app-centric management drive demand for battery-powered wire-free cameras and subscription video storage in US and Chinese consumer markets.
- Business Owners:Multi-site franchise operators and logistics operators prioritize centralized dashboard management and API-accessible analytics integration with existing security operations workflows.
- Government Agencies:Metropolitan public safety departments in India, China, and the United States consolidate procurement authority toward centralized IT departments, demanding FedRAMP or equivalent certification and domestic data residency compliance.
- Event Organizers:Temporary deployment requirements for sports venues and music festivals favor rapid-install PTZ systems with cellular backhaul and cloud-based crowd analytics.
Government Agencies dominate project value. Residential Users are gaining share fastest as smart home ecosystem penetration deepens across price-sensitive demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in smart camera systems tilt toward net-importing Western markets and net-exporting Asian manufacturing bases. Germany and the United States absorb premium edge-AI equipment while China and South Korea dominate component fabrication. Regulatory divergence across these jurisdictions fragments product architectures and certification pathways.
United States
Federal procurement consolidation and metropolitan public safety modernization drive demand for FedRAMP-certified edge-AI networks. FCC spectrum allocations for private 5G backhaul reshape deployment economics for traffic management systems. Chicago and Los Angeles anchor the largest municipal tender pipelines, with both cities mandating domestic data residency for biometric analytics.
Germany
Autobahn infrastructure digitization and industrial facility perimeter hardening sustain demand for IP66+ outdoor systems. EU AI Act biometric restrictions force reengineering of facial recognition pipelines toward anonymized edge processing. Stuttgart and Munich cluster automotive-to-security technology crossover development, leveraging Tier-1 supplier computer vision expertise.
China
GB/T cybersecurity standards and SAMR enforcement create certification moats advantaging domestic manufacturers in government tenders. Dual carbon goals accelerate solar-powered edge camera deployment across western provinces. Shenzhen and Hangzhou concentrate captive semiconductor design and large-scale smart city integration, with Hangzhou's municipal network serving as reference architecture for Belt and Road exports.
Singapore
Expressway vehicle flow optimization and port automation sustain procurement of 30+ fps edge inference systems. TRAI-aligned spectrum management for V2X integration shapes technical specifications in adjacent ASEAN markets. The Jurong Lake District and Tuas Port anchor deployment clusters where camera networks merge with digital twin infrastructure.
India
BIS mandatory registration for electronic surveillance equipment delays refresh cycles while filtering out uncertified imports. Smart city mission funding concentrates procurement authority with state IT departments. Mumbai and Delhi-NCR dominate tender volumes, with Maharashtra's urban development authority pioneering API-accessible analytics integration for multi-agency coordination.
Smart Camera System Market Competitive Landscape
Concentration sits with diversified electronics conglomerates that control captive semiconductor supply and integrated software stacks. The vendor base stratifies across three tiers: vertically integrated sensor-to-system designers, specialized security pure-plays, and contract-assembled volume brands. Strategic moves center on backward integration into neural processing unit design and forward integration into subscription-managed video platforms.
Within the diversified conglomerate tier, Hangzhou Hikvision Digital Technology Co., Ltd., Sony Corporation, and Robert Bosch GmbH exemplify divergent paths to margin defense. Hangzhou Hikvision leverages in-house chip design to dominate government tenders across Asia. Sony sustains premium positioning through proprietary CMOS architectures that anchor professional broadcast and cinematography segments. Bosch extends industrial sensor expertise into smart city infrastructure, competing on automotive-derived computer vision algorithms.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Sony Corporation |
| Samsung Electronics |
| Arlo Technologies, Inc. |
| Canon Inc. |
| Panasonic Corporation |
| Robert Bosch GmbH |
| ADT Inc. |
| Xiaomi Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day sensor procurement lead times for premium CMOS image sensors concentrate pricing power with Taiwanese and South Korean foundries, while edge-AI chipset shortages compress margins for mid-tier system integrators competing on feature parity. This inventory tension feeds directly into buyer negotiation leverage across metropolitan public safety tenders.
Pricing Analysis
Configured-to-order pricing for explosion-proof industrial deployments commands spreads exceeding standard indoor Wi-Fi units by multiples reflecting IECEx certification costs and extended warranty liabilities. Three-tier pricing structure across premium, standard, and economy levels segments by edge-AI inference capability and ingress protection rating, with price erosion running through analog bridge formats as IP-based architectures displace legacy coaxial infrastructure. Government agencies exhibit lowest price sensitivity due to FedRAMP and domestic data residency mandates, while residential DIY buyers drive cost compression through subscription-managed platform economics.
Supply Chain Analysis
China and South Korea anchor CMOS image sensor wafer fabrication and neural processing unit packaging, with Taiwan concentrating advanced logic foundry capacity for edge-AI chipsets. Raw material dependencies span silicon wafers, rare-earth magnet components for PTZ motors, and specialized optical glass from German and Japanese suppliers. Single-source vulnerability concentrates in premium sensor fabrication, where geopolitical friction around semiconductor equipment export controls threatens allocation decisions. Distribution runs through systems integrators for government and industrial tenders, while cloud-connected architectures bypass traditional security distributors through direct-to-enterprise SaaS channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated metropolitan IT departments and centralized government procurement authorities, fragmenting vendor access as tender specifications harden around certification and data residency requirements.
For Market Incumbents: Consolidate backward integration into neural processing unit design to defend margin pools against automotive-to-security crossover entrants leveraging ADAS algorithm portfolios. Captive chip architecture investments create moats against Tier-1 automotive suppliers, while channel control through systems integrator exclusivity agreements protects government tender access from emerging cloud-native competitors. For New Entrants and Emerging Players: BIS certification fast-track programs for electronic surveillance equipment open procurement pipelines in Indian smart city missions where established portfolios face refresh delays. White-space concentrates in solar-powered edge deployments across China's western provinces and API-accessible analytics platforms for US multi-site franchise operators. Go-to-market positioning should emphasize rapid-install cellular backhaul systems for event organizers and temporary deployment contexts. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional fragmentation across EU AI Act biometric restrictions, GB/T cybersecurity mandates, and BIS registration schemes creates acquisition targets with dual-certification capabilities that command scarcity premia. The signal to watch is which regulatory jurisdiction achieves extraterritorial reach first, as that standard will reshape global product architecture economics and determine which certified-systems portfolios carry transferable value.| Strategic Initiative | Industry Significance |
|---|---|
| Neural Processing Unit Design Acquisition | Captive edge-AI silicon eliminates dependency on Qualcomm and Ambarella supply allocations. |
| Dual-Certification Architecture Development | Simultaneous EU AI Act and GB/T compliance opens concurrent access to German and Chinese government tenders. |
| Subscription Platform Migration | Recurring SaaS revenue restructuring displaces capital-intensive DVR procurement in US financial services. |
| Automotive Vision Algorithm Licensing | Bosch and Continental ADAS IP migration accelerates perimeter security product development cycles. |
| Domestic Data Residency Partnership | FedRAMP-authorized cloud regions satisfy Chicago and Los Angeles municipal biometric analytics mandates. |
Research Methodology
A spread of perspectives from smart city procurement officers, edge-AI chipset architects, security systems integrators, and regulatory compliance specialists converged on the working assumptions driving segmentation models. Primary fieldwork combined structured interviews with secondary validation against SAMR enforcement documentation, EU AI Act implementation guidance, BIS registration databases, and hyperscaler video platform capex disclosures. Bottom-up unit economics triangulated against top-down metropolitan infrastructure budget allocations.
Segmentation dimensions modeled span product type, connectivity architecture, deployment environment, end-user procurement authority, and regional regulatory cluster across the analysis window. CAGRs derived from installed base refresh cycles and greenfield smart city infrastructure commitments, with edge-AI capability adoption curves and cloud-connected platform migration rates serving as primary forecast inputs.
Underlying assumptions cover continued enforcement of GB/T cybersecurity standards and EU AI Act biometric restrictions, with deviation risk concentrated in semiconductor export control expansion and alternative neural processing unit architecture disruption. Recalibration cycles align with material shifts in regulatory jurisdiction extraterritorial reach and metropolitan procurement authority consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
Global Body Worn Cameras Market