
 Middle East and Africa Video Surveillance Storage Market | 2026-2036
Middle East and Africa Video Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Video Surveillance Storage Market Insights
Buyer concentration across Middle East and Africa video surveillance storage is broadening beyond traditional government security agencies toward retail chains, transit authorities, and educational campuses. Huawei Technologies Co Ltd anchors large-scale safe-city deployments with integrated storage-networking bundles across Saudi Arabia and the UAE. Dell Technologies Inc competes in enterprise on-premises installations through server-storage convergence for banking and critical infrastructure clients. Seagate Technology LLC specializes in surveillance-optimized hard disk drives engineered for 24/7 write-intensive workloads in desert climate data centers.
Video surveillance storage encompasses the hardware, software, and services that capture, retain, index, and retrieve video footage from security camera networks, typically requiring sustained write throughput of 180-250 MB/s per camera stream and retention periods spanning 30 to 90 days for forensic compliance. The primary industrial purpose centers on evidentiary preservation, real-time threat detection, and post-incident analytical reconstruction for law enforcement and private security operations. Network Attached Storage systems dominate mid-tier commercial deployments where cost per terabyte and rack-space efficiency determine procurement outcomes. Cloud storage segments expand fastest among retail and education end users seeking operational expenditure models and off-site redundancy against regional physical security risks. Solid State Drive adoption remains concentrated in edge-analytics nodes where low-latency retrieval supports artificial intelligence-based object recognition.
Saudi Arabia's National Data Management Office standards, South Africa's POPIA data-protection framework, and UAE cybersecurity council directives collectively mandate encryption-at-rest, access-audit trails, and sovereign data residency for surveillance footage. These compliance architectures elevate procurement complexity and favor vendors with certified local data center partnerships. Stakeholders must monitor evolving data-localization decrees across Gulf states and assess hybrid deployment models that balance regulatory custody requirements against cloud scalability economics.
Market Dynamics
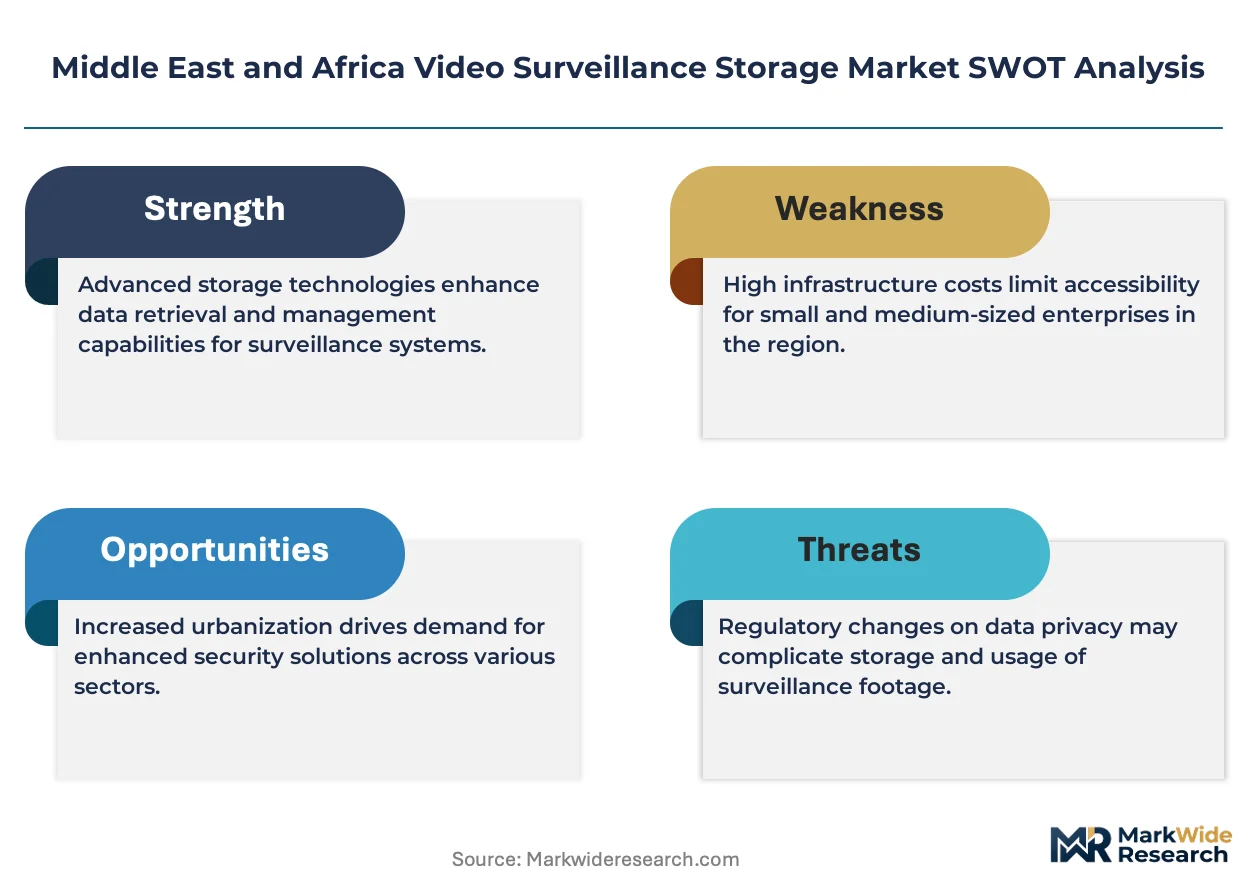
Smart city infrastructure mandates across Gulf Cooperation Council states are compressing procurement cycles for petabyte-scale video retention systems, while South Africa's POPIA compliance deadlines force architectural redesigns toward encrypted, sovereign-hosted storage arrays.
Growth Catalysts
- UAE Safe City mandates:Dubai Police and Abu Dhabi security initiatives sustain centralized storage tenders requiring 90-day forensic retention and real-time analytics integration.
- Edge-computing hardware diffusion:AI-enabled camera nodes across Saudi transit hubs generate localized processing demand, reducing backhaul bandwidth requirements while elevating SSD adoption at the network periphery.
- South Africa POPIA enforcement:The Protection of Personal Information Act mandates encryption-at-rest and access-audit trails, compelling surveillance operators to upgrade legacy unencrypted disk arrays.
Market Restraints
- NAND flash supply concentration:Solid-state drive production concentrates among Korean and Taiwanese foundries, exposing MEA integrators to currency volatility and extended lead times for edge-analytics deployments.
- Desert climate thermal degradation:Ambient temperatures exceeding 45°C in Gulf data centers accelerate hard disk drive failure rates, forcing redundant cooling capex that inflates total cost of ownership.
- Data localization decree fragmentation:Divergent sovereign hosting requirements across Saudi Arabia, UAE, and Egypt prevent standardized regional cloud architectures, multiplying vendor certification burdens.
Strategic Opportunities
- Kenya and Nigeria urban security modernization:Nairobi and Lagos municipal governments are tendering for district-level surveillance networks with localized storage nodes, creating first-mover advantages for tier-2 system integrators.
- Hybrid cloud orchestration services:Managed service providers can capture recurring revenue by bridging on-premises retention with burst-tier cloud archiving for retail and education end users.
- Surveillance-optimized HDD innovation:Vibration-resistant, helium-sealed drives engineered for 24/7 write-intensive workloads address the thermal-density constraints of Gulf climate data centers.
Industry Challenges
- Certified cybersecurity engineer scarcity:Shortfalls in personnel credentialed for UAE Cybersecurity Council and Saudi National Cybersecurity Authority compliance audits delay deployment timelines.
- Legacy analog-to-IP migration complexity:Banking and critical infrastructure clients face integration friction when grafting modern network-attached storage onto decades-old coaxial cable plant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Video Surveillance Storage Market |
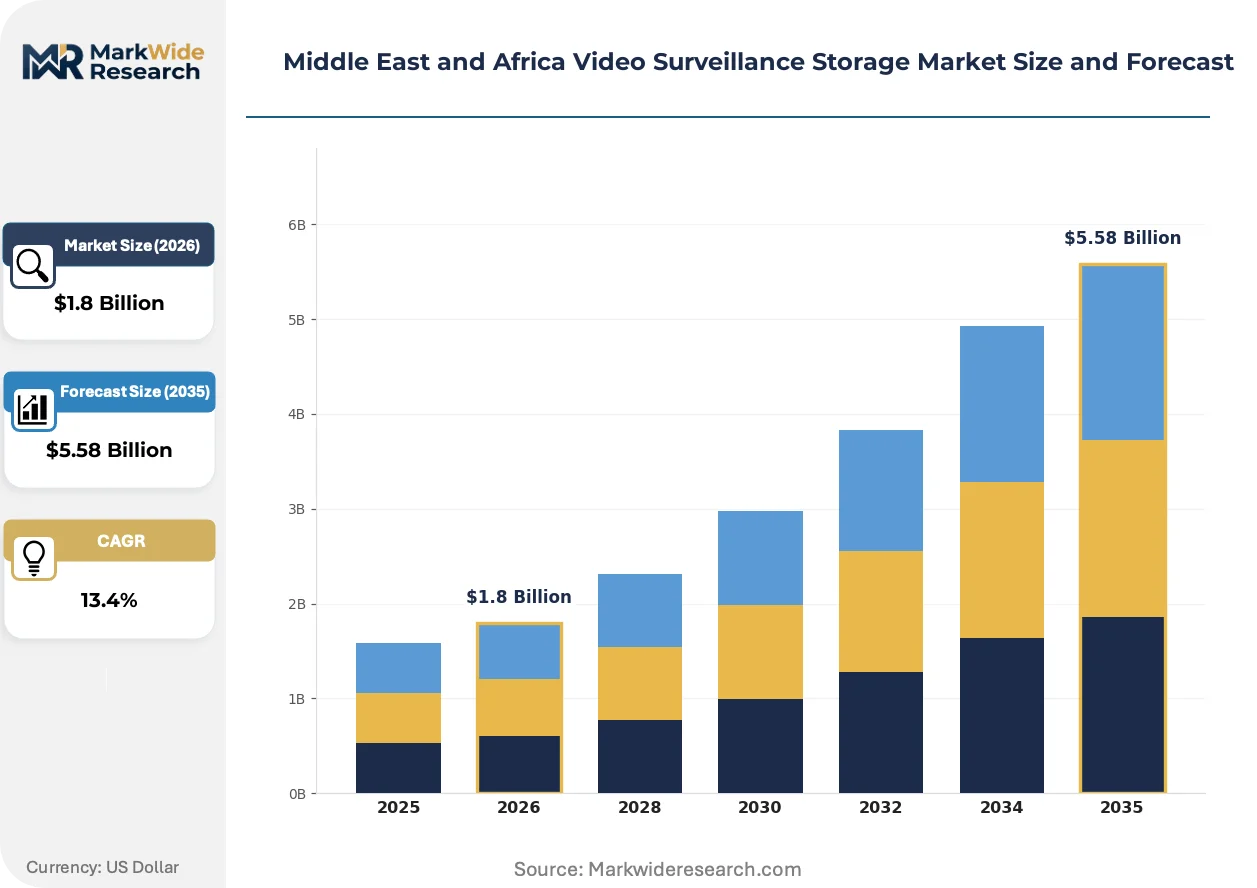
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.58 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Hard Disk Drive, Solid State Drive, Network Attached Storage, Cloud Storage Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote Storage End User: Retail, Transportation, Banking, Education Technology: IP Cameras, Analog Cameras, HD Cameras, 360-Degree Cameras |
| Companies Covered | Hangzhou Hikvision Digital Technology Co Ltd, Dell Technologies Inc, Huawei Technologies Co Ltd, Dahua Technology Co Ltd, Seagate Technology LLC, AXIS Communications, Western Digital, Rasilient Systems Inc, Vivotek, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Video Surveillance Storage Market Trends and Innovations
Artificial intelligence inference at the network edge is compressing storage latency requirements while regulatory mandates across the Middle East and Africa are mandating cryptographic and residency controls that reshape vendor qualification criteria.
AI-powered video analytics engines embedded within camera firmware are automating object classification and anomaly detection at the capture point. Saudi Aramco facilities and UAE airport authorities are deploying these nodes to filter redundant footage before it reaches central repositories. This compression of upstream data volumes is automating tiered storage economics, reducing expensive primary array utilization rates.
South Africa's POPIA enforcement timeline and UAE Cybersecurity Council directives now mandate AES-256 encryption-at-rest with hardware security module key management for all government surveillance footage. Banking and transit operators must demonstrate sovereign data residency through certified local data center partnerships. These compliance architectures favor vendors with pre-audited regional hosting infrastructure over global hyperscale alternatives.
Educational campuses and retail chains across the Gulf are abandoning capital-intensive on-premises procurement for operational expenditure-based managed storage subscriptions. Dubai-based system integrators now bundle five-year retention with remote monitoring and firmware patching. This preference shift concentrates buyer power among regional managed service providers with localized technical support capabilities.
Middle East and Africa Video Surveillance Storage Market Segmentation
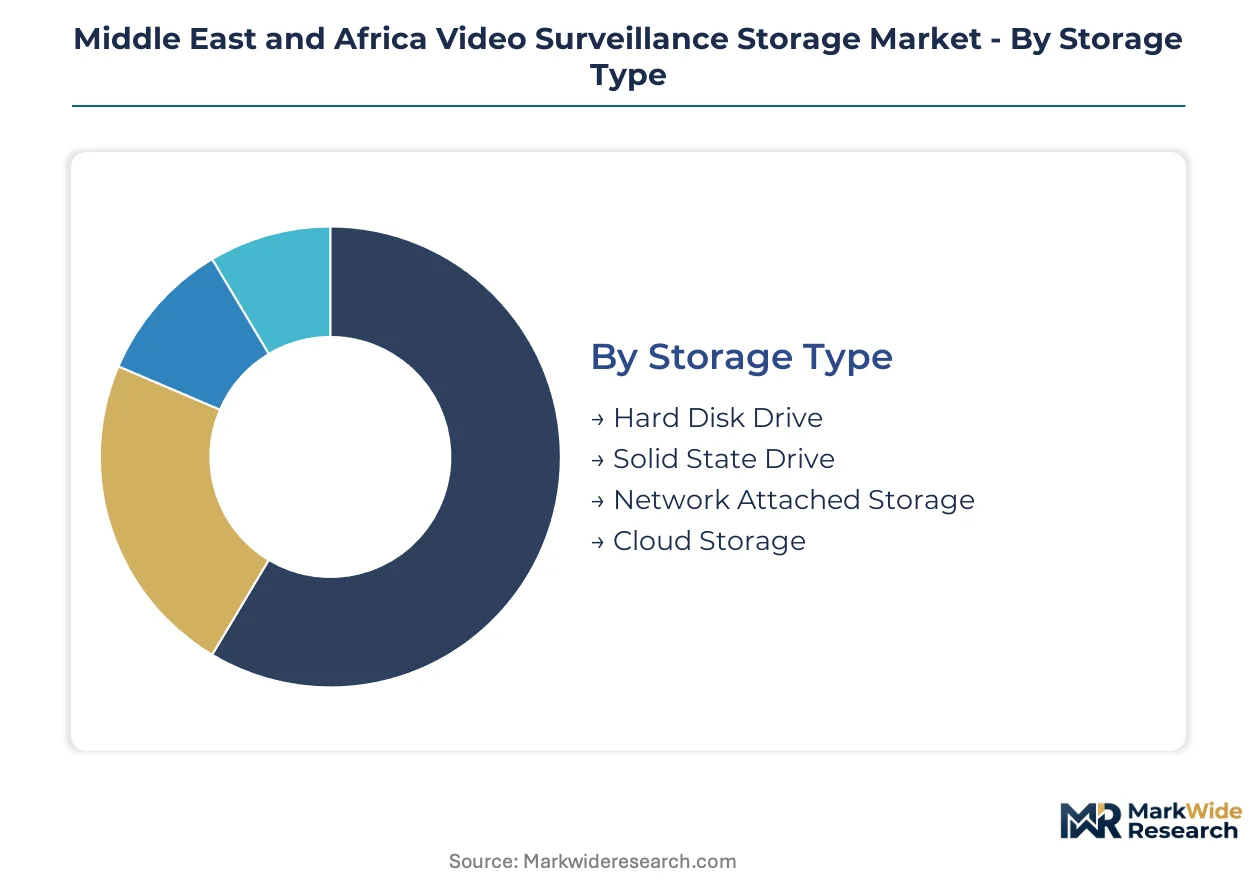
Storage procurement across the Middle East and Africa video surveillance market diverges sharply between legacy infrastructure refresh cycles and greenfield smart city deployments. Segment selection determines thermal resilience requirements, compliance architecture, and total cost of ownership in desert climate data centers.
Storage Type:
Volume deployments favor rotating media for cost efficiency, while premium workloads at the network edge command solid-state performance.
- Hard Disk Drive:Surveillance-optimized drives with helium-sealed enclosures and vibration-resistant firmware dominate 90-day retention archives. Saudi Aramco facilities and Dubai Police central repositories specify these units for petabyte-scale sequential write workloads in climate-controlled facilities.
- Solid State Drive:NVMe and SATA SSDs deliver sub-millisecond latency for AI inference nodes performing real-time object recognition. UAE airport authorities and Saudi transit hubs deploy these at the network periphery where thermal cycling and 24/7 write intensity would degrade mechanical media.
- Network Attached Storage:Mid-tier commercial integrators favor rack-mounted NAS appliances for retail chains and educational campuses seeking simplified management without enterprise SAN complexity.
- Cloud Storage:Managed service providers across the Gulf are bundling operational expenditure-based retention with sovereign data center guarantees for POPIA and UAE Cybersecurity Council compliance.
Mature deployment sits with Hard Disk Drive. Newer deployment is concentrated in Cloud Storage.
Deployment Model:
Procurement patterns track regulatory maturity, with data localization mandates fragmenting architecture choices across national boundaries.
- On-Premises:Banking and critical infrastructure operators in Saudi Arabia and South Africa retain sovereign custody of encryption keys and physical media to satisfy National Data Management Office and POPIA audit requirements.
- Cloud-Based:Retail chains and educational campuses across the UAE are abandoning capital-intensive ownership for managed subscriptions with five-year retention SLAs and remote firmware patching.
- Hybrid:Tiered architectures combining 30-day hot storage on-premises with burst-tier cloud archiving address bandwidth constraints in Nigerian and Kenyan municipal networks.
- Remote Storage:District-level surveillance nodes in Lagos and Nairobi utilize satellite-linked repositories where fiber backhaul remains economically unviable.
Established infrastructure favors On-Premises. Expansion is climbing fastest in Hybrid configurations.
End User:
Demand concentration varies by compliance exposure and footage analytical intensity.
- Retail:Loss prevention departments across Gulf Cooperation Council states are standardizing on 90-day retention with AI-powered dwell-time analytics, driving SSD adoption at store-level edge nodes.
- Transportation:Saudi railway operators and UAE aviation authorities generate the highest sustained write throughput requirements, specifying redundant storage arrays for continuous platform and perimeter monitoring.
- Banking:South African financial institutions face POPIA-mandated encryption upgrades for legacy coaxial-era archives, creating replacement demand for compliant network-attached systems.
- Education:Campus safety initiatives across Dubai and Abu Dhabi are tendering for district-wide networks with centralized retention and federated access controls.
Transportation commands the steepest expansion trajectory as Saudi and UAE transit modernization accelerates.
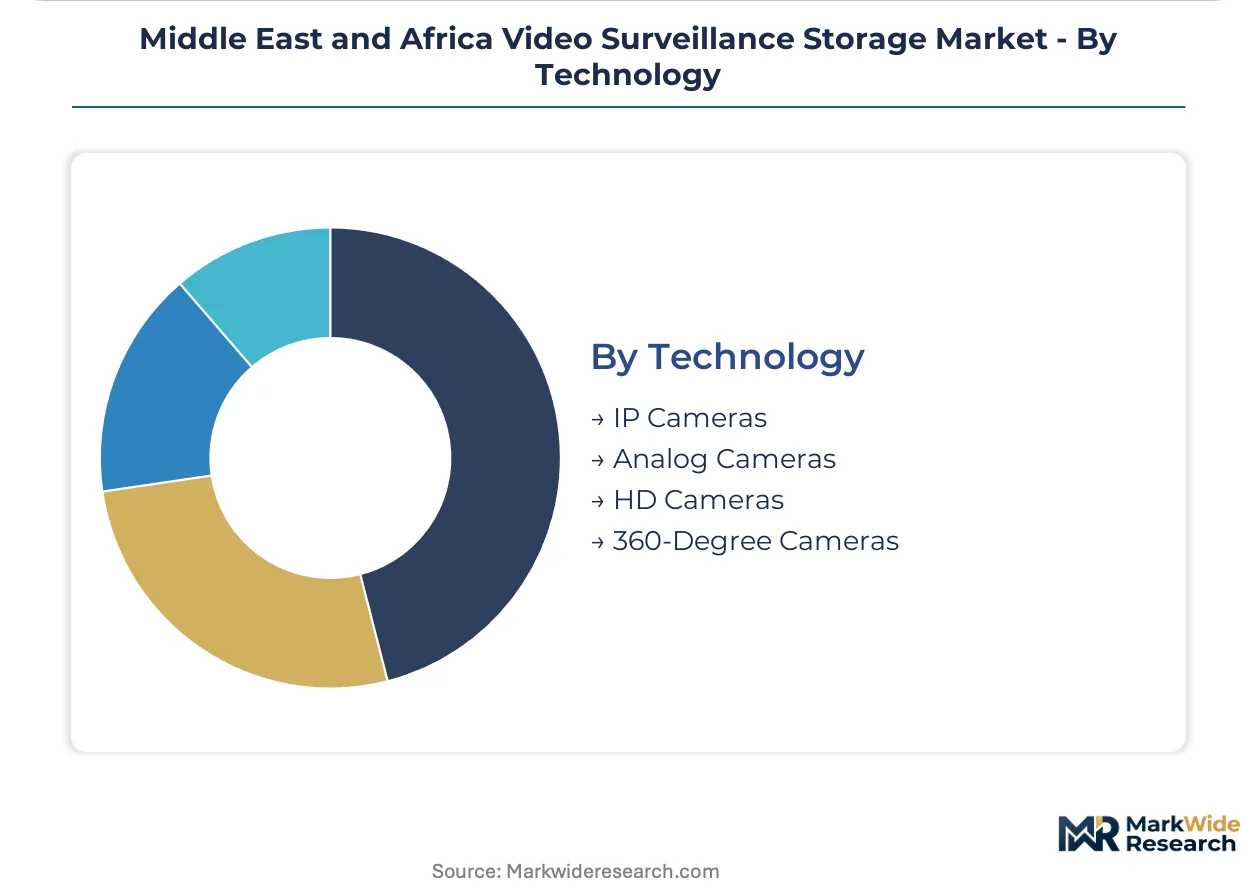
Technology:
Camera technology selection dictates storage bandwidth, compression efficiency, and edge-processing requirements.
- IP Cameras:H.265+ compression and Power over Ethernet simplify cabling for new installations across Saudi smart city corridors, reducing storage footprint per camera stream by 50% versus legacy codecs.
- Analog Cameras:Coaxial infrastructure persists in South African banking and industrial sites where full IP migration faces budget constraints, requiring hybrid encoders for modern storage integration.
- HD Cameras:1080p and 4K resolutions dominate retail and education deployments where facial recognition accuracy depends on capture fidelity.
- 360-Degree Cameras:Multi-sensor panoramic units in UAE airports and Saudi Aramco facilities generate multi-stream storage loads, favoring high-density HDD arrays with sequential write optimization.
IP Cameras anchor new procurement. Analog retention is concentrated in South African legacy infrastructure refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United Arab Emirates, where Dubai Police and Abu Dhabi Safe City initiatives sustain petabyte-scale storage tenders. Saudi Arabia and South Africa follow as secondary centers driven by smart city mandates and data protection enforcement. Fragmented data localization requirements across Gulf states prevent standardized regional architectures.
United Arab Emirates
Dubai Police and Abu Dhabi Safe City initiatives drive centralized storage procurement requiring 90-day forensic retention and real-time analytics integration. UAE Cybersecurity Council directives mandate AES-256 encryption-at-rest with hardware security module key management for government surveillance footage. Dubai-based system integrators bundle five-year retention with remote monitoring for retail and education clients.
Saudi Arabia
National Data Management Office standards and smart city infrastructure mandates compress procurement cycles for petabyte-scale video retention systems. Saudi Aramco facilities and transit hubs deploy AI-enabled camera nodes with localized processing to filter redundant footage before central repository transmission. Riyadh and Eastern Province data centers specify vibration-resistant, helium-sealed drives for 24/7 write-intensive workloads.
South Africa
Protection of Personal Information Act enforcement compels surveillance operators to upgrade legacy unencrypted disk arrays with encrypted, sovereign-hosted storage solutions. Banking and critical infrastructure clients retain sovereign custody of encryption keys to satisfy POPIA audit requirements. Johannesburg financial institutions face replacement demand for compliant network-attached systems.
Nigeria
Lagos municipal government tenders for district-level surveillance networks with localized storage nodes create first-mover advantages for tier-2 system integrators. Hybrid architectures combining 30-day hot storage on-premises with burst-tier cloud archiving address bandwidth constraints in municipal networks. District-level nodes utilize satellite-linked repositories where fiber backhaul remains economically unviable.
Kenya
Nairobi urban security modernization programs tender for district-level surveillance networks with localized storage nodes. Edge-computing hardware diffusion generates demand for SSD adoption at network peripheries where low-latency retrieval supports AI-based object recognition. Municipal procurement favors system integrators with certified local data center partnerships.
Middle East and Africa Video Surveillance Storage Market Competitive Landscape
Chinese producers anchor one tier; American and European specialists hold differentiated positions in enterprise and surveillance-optimized segments. Market structure fragments across integrated safe-city bundlers, server-storage convergence providers, and component-level drive manufacturers. Three archetypes dominate: full-stack infrastructure vendors, enterprise storage specialists, and surveillance-optimized component suppliers. Competitive moves center on certified local data center partnerships and surveillance-specific thermal resilience engineering.
Among Chinese full-stack providers, Huawei Technologies Co Ltd and Dahua Technology Co Ltd exemplify the integrated safe-city deployment archetype. Dell Technologies Inc represents the enterprise server-storage convergence position. Seagate Technology LLC and Western Digital occupy the surveillance-optimized drive manufacturing tier. Hangzhou Hikvision Digital Technology Co Ltd sits within the camera-to-storage integrated solution segment. These five entities collectively span the value chain from edge capture through central retention.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co Ltd |
| Dell Technologies Inc |
| Huawei Technologies Co Ltd |
| Dahua Technology Co Ltd |
| Seagate Technology LLC |
| AXIS Communications |
| Western Digital |
| Rasilient Systems Inc |
| Vivotek |
| Others |
Pricing and Supply Chain Analysis
Helium spot price volatility cascades through surveillance-optimized hard disk drive manufacturing into three-tier pricing structures across Gulf data center procurement, with thermal-resilient helium-sealed units commanding premium positioning against standard air-filled alternatives in desert climate deployments.
Pricing Analysis
Volume deployments of rotating media operate on thin margins while edge-computing SSD configurations retain pricing power through AI inference latency advantages. Three-tier pricing structure across premium, standard, and economy levels separates UAE government safe-city tenders with sovereign compliance requirements from Kenyan municipal district-level bids and South African banking refresh cycles. Cost compression in mid-tier NAS appliances is intensifying because NAND flash supply concentration exposes integrators to currency volatility. Retail chains and educational campuses across the Gulf exhibit highest price sensitivity, favoring operational expenditure subscriptions, while Saudi Aramco and Dubai Police demonstrate lowest sensitivity due to forensic retention mandates.
Supply Chain Analysis
UAE Cybersecurity Council and Saudi National Cybersecurity Authority certification requirements gate vendor qualification before procurement eligibility, forcing foreign manufacturers into local data center partnerships. Component manufacturing concentrates in China, Taiwan, and South Korea for NAND flash and drive controller silicon. Assembly draws from Malaysian and Thai facilities for final integration. Single-source vulnerability in Korean foundry capacity for enterprise-grade SSD controllers threatens edge-analytics deployment timelines across Saudi transit hubs. Distribution runs through Dubai-based system integrators who bundle five-year retention SLAs with remote firmware patching for retail and education end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as full-stack safe-city vendors capture procurement share by controlling camera-to-storage data flows, while component specialists risk disintermediation without edge-analytics software layers.
For Market Incumbents: Deepen sovereign data center partnerships in Riyadh and Johannesburg to preempt compliance-driven procurement shifts. Secure UAE Cybersecurity Council pre-audit certification to defend against Chinese full-stack bundlers. Invest in thermal-resilient firmware engineering for Gulf climate specifications. Control vibration-resistant drive controller IP to maintain margin position against commoditizing alternatives.
For New Entrants and Emerging Players: AI-powered video analytics compression algorithms offer entry into Saudi Aramco facility upgrades where upstream data filtering reduces central storage requirements. Target Lagos and Nairobi municipal tenders with satellite-linked hybrid architectures addressing fiber backhaul gaps. Lead with certified local data center partnerships rather than global hyperscale alternatives to satisfy POPIA and UAE data localization mandates.
For Investors and Strategic Acquirers: Distressed-cycle entries favor surveillance-optimized component manufacturers with captive thermal engineering IP in Southeast Asian assembly corridors. Long-term viability hinges on backward integration into edge-analytics software stacks over pure hardware exposure. Monitor Saudi National Data Management Office decree enforcement as inflection indicator for sovereign hosting demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Data Center Certification | UAE Cybersecurity Council pre-audit unlocks government petabyte-scale tender eligibility. |
| Helium-Sealed Drive Innovation | Thermal resilience engineering addresses 45°C ambient failure rates in Gulf facilities. |
| Edge-Analytics Software Acquisition | Upstream video filtering capability compresses central storage utilization rates for tiered economics. |
| Hybrid Cloud Orchestration Services | Managed subscriptions capture recurring revenue from retail and education operational expenditure shifts. |
| Regional System Integrator Partnership | Dubai-based bundlers control five-year retention SLA distribution across GCC states. |
Research Methodology
Independent corroboration across primary interviews with data center procurement officers, safe-city project managers, and surveillance system integrators, combined with secondary validation through UAE Cybersecurity Council directive filings, Saudi National Data Management Office standards documentation, and South Africa POPIA enforcement timelines, underwrites the qualitative findings. Bottom-up triangulation of storage capacity procurement data and top-down reconciliation against smart city infrastructure budget disclosures anchor volume estimates.
Comparable-period anchoring to 2026 baseline values extends across the projection horizon through segmented modeling of storage type, deployment model, end user vertical, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves adjusted for NAND flash supply elasticity and data localization decree implementation velocity. Industry-specific inputs include thermal degradation coefficients for Gulf climate HDD reliability and POPIA compliance-driven replacement cycle acceleration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden NAND flash supply disruption or accelerated data localization fragmentation across Egypt, Qatar, and Kuwait. Model refresh is warranted upon material change in Saudi National Cybersecurity Authority certification timelines or UAE sovereign hosting mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
CCTV Camera Market