
 India CCTV Market | 2026-2036
India CCTV Market Size, Share, and Industry Trends Forecast 2026-2036
India CCTV Market Outlook
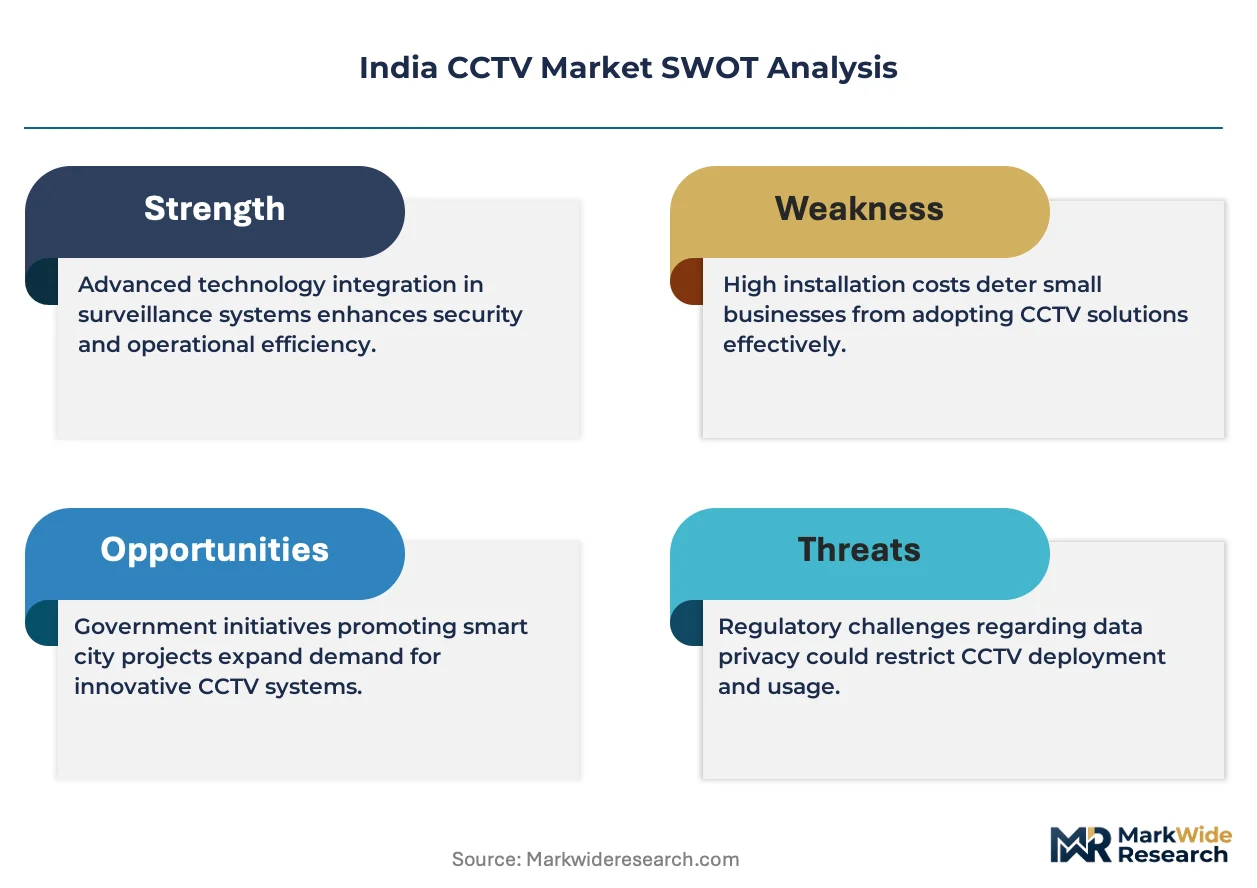
BIS IS 16046 certification for electronic security equipment is rotating the competitive landscape toward quality-compliant manufacturers. Hikvision Digital Technology leverages its extensive distribution network to sustain volume leadership across tier-1 and tier-2 cities. Godrej Security Solutions anchors its position through in-house manufacturing and deep integration with Indian institutional buyers. Dixon Technologies (India) differentiates by competing on cost-efficient domestic assembly and government contract eligibility.
Closed-circuit television encompasses video capture, transmission, and display systems employing coaxial cable, fiber optic, or IP-based networking architectures with resolutions spanning standard definition to 4K ultra-HD. These systems serve commercial and public safety functions through real-time monitoring, recorded evidence retrieval, and automated analytics integration. Dome cameras dominate indoor retail and banking deployments due to vandal-resistant housings and 360-degree coverage capabilities, while bullet configurations lead outdoor perimeter applications across transportation and residential sectors. IP technology is displacing analog infrastructure fastest in metro rail and smart city projects, though hybrid installations persist where legacy coaxial cabling remains economically entrenched.
BIS mandates IS 16046 compliance for all electronic security products sold in India, while the Ministry of Home Affairs guidelines under the Safe City Initiative direct procurement standards for urban surveillance networks. CDSCO oversight intersects where biometric-integrated CCTV systems process health-adjacent data in hospital and pharmaceutical facility deployments. Stakeholders must monitor evolving encryption requirements under proposed data protection frameworks and position procurement strategies around indigenous manufacturing incentives through the PLI scheme.
Market Dynamics
Networked IP surveillance infrastructure is systematically dismantling analog coaxial dominance across Indian urban centers, with metro rail authorities and smart city administrators mandating cloud-integrated video management platforms that render legacy DVR systems economically obsolete.
Growth Catalysts
- Safe City Initiative directives:Ministry of Home Affairs guidelines mandate surveillance network upgrades across urban centers, compelling municipal corporations to standardize on IP-based architectures with centralized command centers.
- Maharashtra infrastructure concentration:Mumbai Metro expansion and Pune commercial corridor development generate bulk procurement volumes for vandal-resistant dome and bullet camera configurations.
- PLI scheme incentives:Production Linked Incentive disbursements for electronics manufacturing attract domestic assembly investments, reducing landed costs for government-qualified bidders.
Market Restraints
- Image sensor supply concentration:CMOS sensor fabrication concentrates among East Asian foundries, exposing Indian integrators to shipping volatility and forex-driven component inflation.
- Coaxial infrastructure entrenchment:Legacy analog cabling in tier-3 municipal buildings and aging residential compounds delays full IP migration, perpetuating hybrid system complexity.
- BIS IS 16046 compliance timeline:Bureau of Indian Standards certification requirements extend product qualification cycles by four to six months for non-compliant imports.
Strategic Opportunities
- Tier-3 city penetration:Surveillance deployment in Indore, Lucknow, and Chandigarh remains below saturation thresholds, creating first-mover advantages for localized service networks.
- Edge analytics convergence:On-camera AI processing for facial recognition and behavioral analysis merges with 5G backhaul, enabling real-time threat response without centralized latency.
- Healthcare facility mandates:CDSCO-adjacent guidelines for pharmaceutical manufacturing security create specialized demand for biometric-integrated CCTV in cleanroom environments.
Industry Challenges
- Certification backlog congestion:BIS laboratory capacity constraints delay IS 16046 testing queues, compressing product launch windows for festival-season procurement cycles.
- Legacy DVR integration complexity:Hybrid deployments requiring analog-to-IP bridge equipment multiply installation labor costs and degrade video quality consistency across unified management platforms.
- Cloud security skill scarcity:Cybersecurity expertise for encrypted video transmission and zero-trust network architecture remains concentrated among Mumbai and Bengaluru talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India CCTV Market |
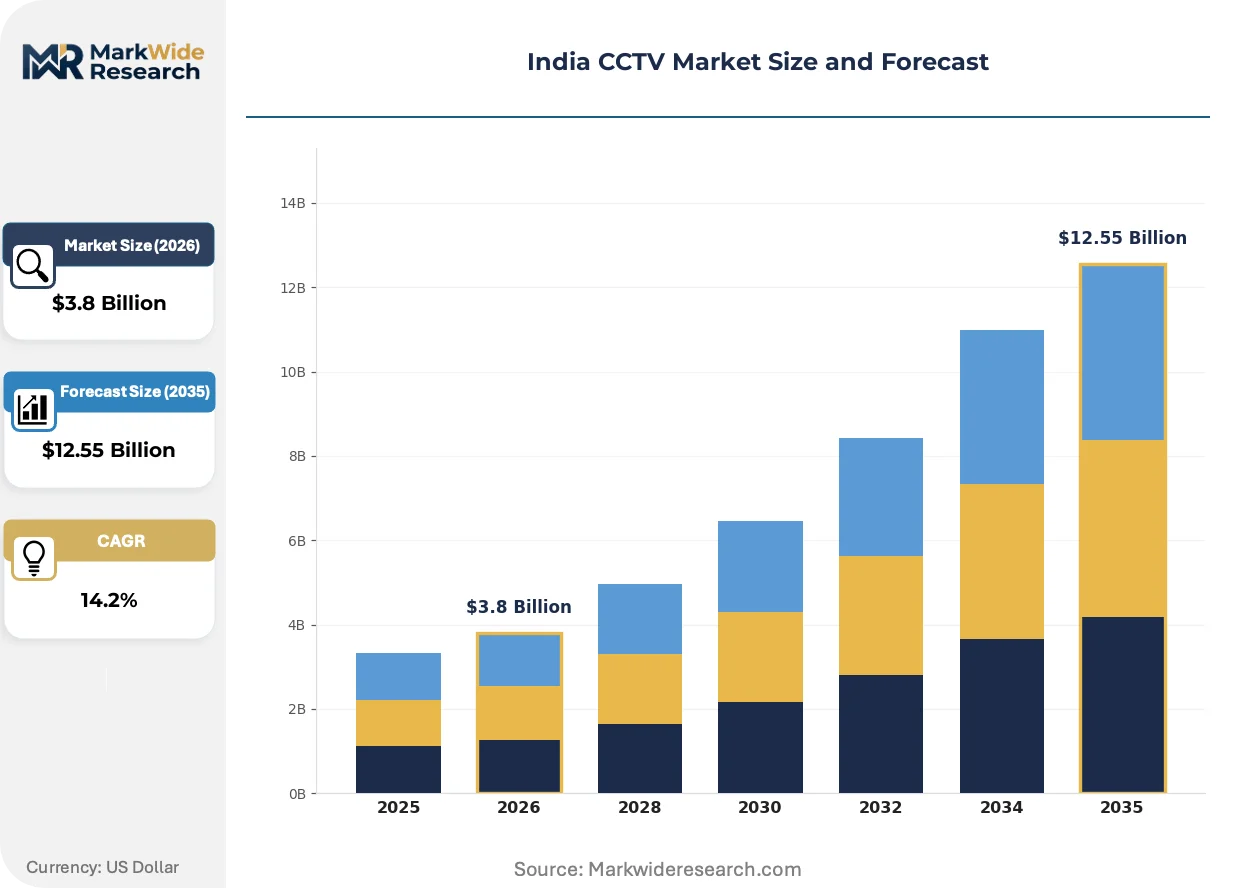
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
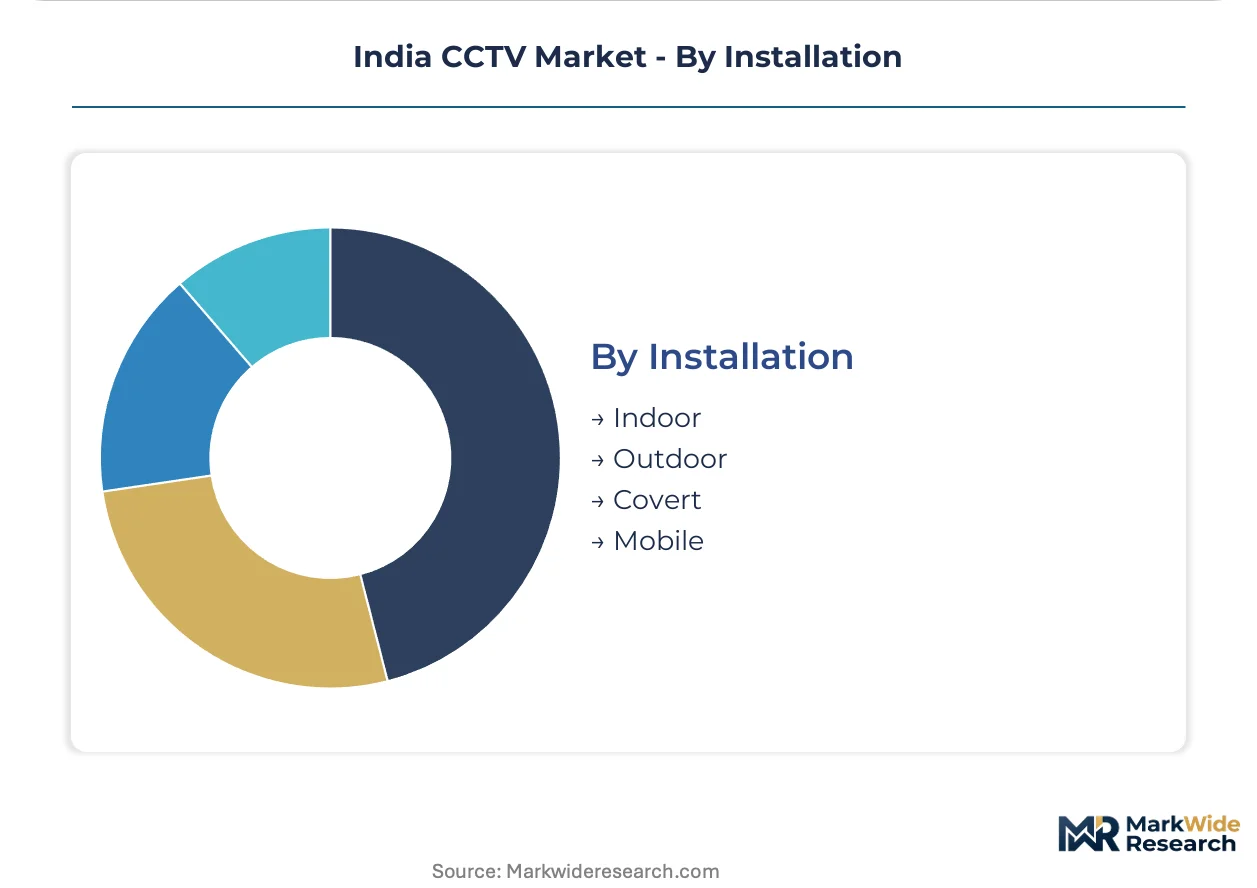
| Segmentation | Product Type: Dome, Bullet, PTZ, Box End User: Retail, Banking, Transportation, Residential Technology: Analog, IP, Wireless, Hybrid Installation: Indoor, Outdoor, Covert, Mobile |
| Companies Covered | Axis Video Systems India, Honeywell Commercial Security, Hikvision Digital Technology, Dixon Technologies (India), Vintron Informatics, Dahua Technology India, Godrej Security Solutions, Vantage Security, Aditya Infotech (CP Plus), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India CCTV Market Strategic Shifts
Edge computing architectures and on-device AI inference are compressing the traditional three-tier surveillance stack, eliminating latency bottlenecks while forcing storage and analytics vendors to reposition around distributed processing economics.
PoE++ (Power over Ethernet Plus Plus) infrastructure is supplanting separate electrical and data cabling runs in new commercial construction across Hyderabad and Chennai. Facility managers in IT parks and logistics warehouses are specifying IEEE 802.3bt-compliant switches to support pan-tilt-zoom cameras with integrated heaters and illuminators. This convergence collapses installation labor costs by eliminating conduit runs while enabling single-cable servicing that reduces mean-time-to-repair metrics.
BIS IS 16046 certification mandates for electronic security equipment are disqualifying uncertified imports from government and institutional tenders. The Bureau of Indian Standards enforcement through DGFT customs notifications has redirected procurement flows toward domestic assembly operations and pre-certified OEM partnerships. Maharashtra and Gujarat state police modernization programs now embed IS 16046 compliance as a mandatory technical bid criterion, accelerating supplier qualification rotations.
Buyers in banking and critical infrastructure verticals are unbundling hardware acquisition from multi-year managed service agreements. Large public sector banks are separating camera procurement from video analytics subscriptions, enabling competitive rebidding of software layers without forklift infrastructure replacement. This disaggregation is most pronounced in Delhi-NCR and Bengaluru, where CIOs demand API-open platforms that prevent vendor lock-in across five-year depreciation cycles.
India CCTV Market Segmentation
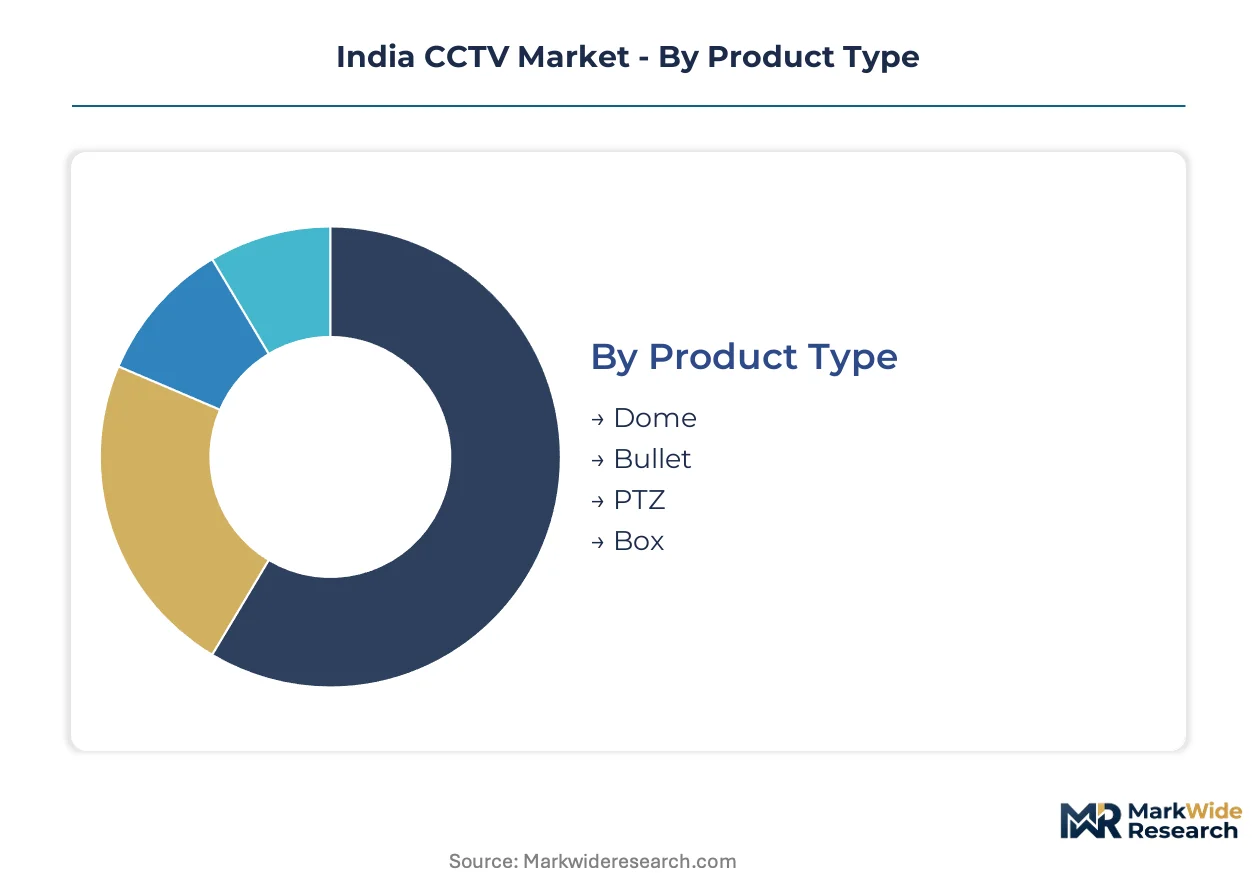
Segmentation in the India CCTV Market reveals how procurement patterns diverge across institutional buyers versus residential consumers, with BIS certification requirements and smart city mandates creating distinct qualification thresholds for each product and technology category.
Product Type:
Dome and bullet configurations anchor domestic manufacturing volumes, while PTZ and box cameras retain higher import dependency for specialized optical components.
- Dome:Vandal-resistant housings with 360-degree coverage capabilities serve indoor retail and banking deployments across Maharashtra and Gujarat. Mumbai Metro authorities specify these for station concourses where physical tampering risks concentrate.
- Bullet:Weather-sealed cylindrical housings with integrated infrared illuminators dominate outdoor perimeter applications across transportation corridors and residential compounds. Pune commercial real estate developers bulk-procure these for parking and loading bay surveillance.
- PTZ:Motorized pan-tilt-zoom mechanisms with optical zoom ranges up to 30x serve traffic monitoring and critical infrastructure command centers requiring operator-directed tracking.
- Box:Modular camera bodies with interchangeable lenses address specialized industrial inspection and casino/gaming surveillance requiring precise focal length matching.
Dome configurations command the established base across institutional deployments. The steepest expansion runs through bullet cameras driven by tier-2 city infrastructure buildouts.
End User:
Cost tiers separate enterprise-grade installations with multi-year managed service contracts from price-sensitive residential deployments.
- Retail:Multi-camera networked systems with POS integration and shopper analytics serve organized retail chains across Delhi-NCR and Bengaluru. Loss prevention teams mandate cloud-archived footage with 90-day retention for dispute resolution.
- Banking:RBI guidelines mandate branch surveillance with facial capture quality standards, driving replacement cycles for legacy analog systems in public sector banks. ATM vestibule deployments require anti-skimming camera positioning.
- Transportation:Metro rail authorities in Mumbai, Chennai, and Hyderabad specify IP-based platforms with centralized video management for platform and rolling stock coverage.
- Residential:Gated communities and individual homeowners in tier-2 cities drive wireless and DIY installation growth, with price sensitivity favoring domestic assembly over imported brands.
Banking verticals anchor replacement demand through regulatory compliance deadlines. Residential applications are gaining share fastest as apartment complex associations standardize on common-area surveillance.
Technology:
Volume concentration sits with IP architectures, though hybrid installations persist where legacy coaxial infrastructure delays full migration.
- Analog:Coaxial-based CVBS and HD-TVI systems persist in tier-3 municipal buildings and aging residential compounds where cabling replacement costs deter upgrade investments.
- IP:Ethernet-delivered H.265 video compression with Power over Ethernet infrastructure dominates new commercial construction and smart city tenders, enabling 4K resolution and edge analytics integration.
- Wireless:Wi-Fi and cellular backhaul configurations serve temporary deployments, construction sites, and rural locations lacking structured cabling, with battery-powered options for off-grid applications.
- Hybrid:Bridge-equipped installations combining analog camera retention with IP recording platforms address budget-constrained upgrade scenarios in government buildings and educational institutions.
Analog technology retains the installed base through infrastructure inertia. IP platforms are climbing the fastest as metro rail and safe city mandates eliminate legacy system eligibility.
Installation:
Application environment dictates housing specifications and mounting hardware requirements across the deployment spectrum.
- Indoor:Recessed ceiling and surface-mount configurations with discrete form factors serve corporate offices, healthcare facilities, and educational institutions where aesthetic integration matters.
- Outdoor:IP66/IP67 weatherproofing with integrated heaters and wiper mechanisms withstands monsoon conditions and temperature extremes across coastal Chennai and northern plains installations.
- Covert:Disguised housings embedded in smoke detectors, electrical fixtures, or environmental sensors address law enforcement sting operations and high-security facility penetration testing.
- Mobile:Vibration-resistant mounts with solid-state storage serve police vehicles, cash-in-transit fleets, and railway rolling stock requiring evidence-grade recording in motion.
Outdoor installations command the volume base through infrastructure expansion. Mobile configurations are expanding most quickly as fleet operators mandate driver behavior monitoring and incident documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme disbursements for electronics manufacturing are redistributing CCTV production capacity across Indian states, with state-level police modernization programs embedding BIS IS 16046 compliance as mandatory bid criteria.
Maharashtra
Mumbai Metro expansion and Pune commercial corridor development generate bulk procurement volumes for vandal-resistant dome and bullet configurations. The state police modernization program mandates IP-based surveillance with centralized command centers for urban precincts. Thane and Navi Mumbai industrial zones host domestic assembly operations supplying government-qualified tenders.
Gujarat
Smart city deployments in Ahmedabad and Surat drive networked camera installations across municipal jurisdictions. The state urban development department aligns procurement with Ministry of Home Affairs Safe City Initiative guidelines. GIFT City financial district specifications require biometric-integrated CCTV for critical infrastructure coverage.
Karnataka
Bengaluru IT park construction specifies PoE++ infrastructure for single-cable camera deployments with integrated analytics. The state electronics policy complements central PLI incentives for domestic manufacturing investments. Mysuru and Hubli-Dharwad municipal corporations are accelerating tier-2 surveillance network saturation.
Tamil Nadu
Chennai metro rail authorities specify IP-based platforms with edge computing capabilities for platform and rolling stock coverage. The state industrial policy supports electronics manufacturing clusters in Sriperumbudur and Oragadam. Coimbatore and Madurai commercial real estate developers are standardizing on outdoor weatherproof configurations.
Telangana
Hyderabad smart city administrators mandate cloud-integrated video management platforms rendering legacy DVR systems obsolete. The state police department's integrated command and control center drives centralized procurement specifications. Cyberabad technology corridor facilities require API-open platforms preventing vendor lock-in.
India CCTV Market Competitive Environment
Listed leaders compete with private specialists across certification compliance and distribution reach, producing a tiered structure where BIS IS 16046 qualification separates institutional-eligible suppliers from consumer-tier competitors. The vendor base clusters around three strategic archetypes: multinational technology licensors with extensive distribution networks, domestic assemblers leveraging PLI scheme eligibility, and security-focused conglomerates with in-house manufacturing. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through localized service networks.
Within the multinational technology tier, Hikvision Digital Technology and Dahua Technology India occupy positions anchored by volume distribution across tier-1 and tier-2 cities. Among domestic assemblers, Dixon Technologies (India) exemplifies cost-efficient manufacturing positioning for government contract eligibility. Godrej Security Solutions represents the integrated conglomerate archetype with deep institutional buyer relationships and captive production capabilities.
| Leading Market Players |
|---|
| Axis Video Systems India |
| Honeywell Commercial Security |
| Hikvision Digital Technology |
| Dixon Technologies (India) |
| Vintron Informatics |
| Dahua Technology India |
| Godrej Security Solutions |
| Vantage Security |
| Aditya Infotech (CP Plus) |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for CMOS image sensors concentrate procurement leverage among East Asian foundries, compressing margin buffers for Indian integrators while amplifying pricing power for certified domestic assemblers qualifying under PLI disbursement criteria.
Pricing Analysis
Certification tier creates the primary spread between institutional-eligible and consumer-tier suppliers. Three-tier pricing structure separates BIS IS 16046-compliant systems from pre-certified imports and uncertified gray-market equipment. Cost compression in the mid-tier is intensifying because Dixon Technologies and Vintron Informatics are expanding domestic assembly capacity. Municipal corporations and public sector banks exhibit the lowest price sensitivity due to mandate-driven replacement cycles, while residential buyers in tier-2 cities drive aggressive quoting for wireless DIY configurations.
Supply Chain Analysis
South China Sea transit lanes for semiconductor components expose Indian CCTV manufacturers to shipping volatility and forex-driven input inflation. CMOS sensors from Taiwan and South Korea, optical lenses from Japan, and PCB assemblies from China feed into domestic integration facilities in Maharashtra and Tamil Nadu. Single-source vulnerability concentrates in high-resolution image sensor fabrication, where foundry capacity allocation favors automotive and smartphone OEMs. Distribution runs through authorized dealer networks for institutional verticals and e-commerce marketplaces for residential endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among state police modernization programs and smart city administrators, fragmenting procurement authority previously dispersed across municipal departments and tilting vendor selection toward certification-compliant domestic assemblers.
For Market Incumbents: Shield market position by deepening captive production of vandal-resistant housings and PoE++ switches in Thane industrial zones, countering emerging competition from PLI-eligible contract manufacturers. Accelerate BIS laboratory partnerships to compress IS 16046 qualification cycles ahead of festival-season tender windows. For New Entrants and Emerging Players: Fast-track BIS certification through pre-certified OEM partnerships opens institutional procurement channels closed to direct imports. Target tier-3 municipal corporations in Indore and Lucknow where localized service networks remain underdeveloped. Lead with edge-analytics bundles that unbundle hardware from recurring software subscriptions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized security electronics divisions lacking standalone certification infrastructure. Long-term viability hinges on positioning for indigenous manufacturing incentives rather than import-dependent trading models. Watch for DGFT customs notification enforcement tightening as the signal for accelerated supplier qualification rotations.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Expansion | PLI scheme eligibility secures government tender access against import-dependent competitors. |
| BIS Certification Fast-Track | IS 16046 compliance opens Maharashtra and Gujarat police modernization program participation. |
| Edge Analytics Integration | On-camera AI processing differentiates offerings in Hyderabad smart city cloud-platform tenders. |
| Service Network Localization | Tier-3 city coverage captures first-mover advantage in Indore and Chandigarh surveillance deployment. |
| Hardware-Software Unbundling | API-open platforms prevent vendor lock-in and enable competitive rebidding of analytics layers. |
Study Parameters
Operator-level perspectives from metro rail project engineers, state police IT directors, smart city administrators, security systems integrators, and BIS certification laboratory managers anchored the qualitative base. These primary insights combined with secondary validation from DGFT customs notifications, Ministry of Home Affairs Safe City Initiative guidelines, PLI scheme disbursement records, and Bureau of Indian Standards enforcement circulars. Bottom-up installation volume estimates across Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Telangana triangulated against top-down electronics manufacturing capacity assessments.
Sensitivity analysis tested forecast robustness across varying PLI uptake rates and BIS enforcement intensity scenarios. Segmentation dimensions modeled include product type, end-user vertical, technology architecture, installation environment, and state-level procurement policy cluster. CAGRs were derived from installation run-rate projections and average system value trajectories, incorporating edge analytics penetration and IP displacement of analog infrastructure as industry-specific demand drivers.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme funding and BIS IS 16046 enforcement continuity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as CMOS sensor supply allocation priorities and data protection framework encryption requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Latin America Electronics Security Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
Europe Security Testing Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Mass Transit Security Market
Security and Surveillance
Integrated Security Services Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Specialized Threat Analysis and Protection Market