
 Europe Surveillance IP Camera Market | 2026-2036
Europe Surveillance IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Surveillance IP Camera Market Insights
Poland is reshaping regional manufacturing capacity as several component suppliers establish assembly operations near Wrocław and Kraków. Bosch Security Systems GmbH anchors its European production footprint through German engineering centers while extending distribution reach into Central and Eastern European markets. Dahua Technology competes aggressively on price-performance ratios for mid-tier municipal contracts. Axis Communications AB specializes in open-platform architectures that integrate with third-party video management software.
Europe surveillance IP cameras are digital networked imaging devices transmitting compressed video streams over Ethernet or Wi-Fi infrastructure, typically featuring resolutions from 2MP to 8MP with H.265 encoding and edge-based analytics processing. Their primary commercial purpose centers on real-time security monitoring, forensic evidence collection, and automated threat detection for property protection and public safety operations. Dome cameras dominate indoor retail and healthcare deployments where vandal resistance and discreet positioning matter. PTZ units capture the fastest-growing share in perimeter defense and large-area monitoring applications requiring operator-controlled pan-tilt-zoom functionality. Manufacturing end users generate concentrated margin pools due to stringent site-security requirements and integration with access-control systems.
GDPR and the EU AI Act constrain how biometric analytics and facial recognition capabilities deploy across member states, with national data protection authorities enforcing divergent interpretation standards. CE marking under the Radio Equipment Directive and cybersecurity resilience requirements under the EU Cybersecurity Act shape product certification pathways and market access timelines. Procurement teams must weigh compliance complexity against total cost of ownership when evaluating vendors with varying data governance architectures.
Market Dynamics
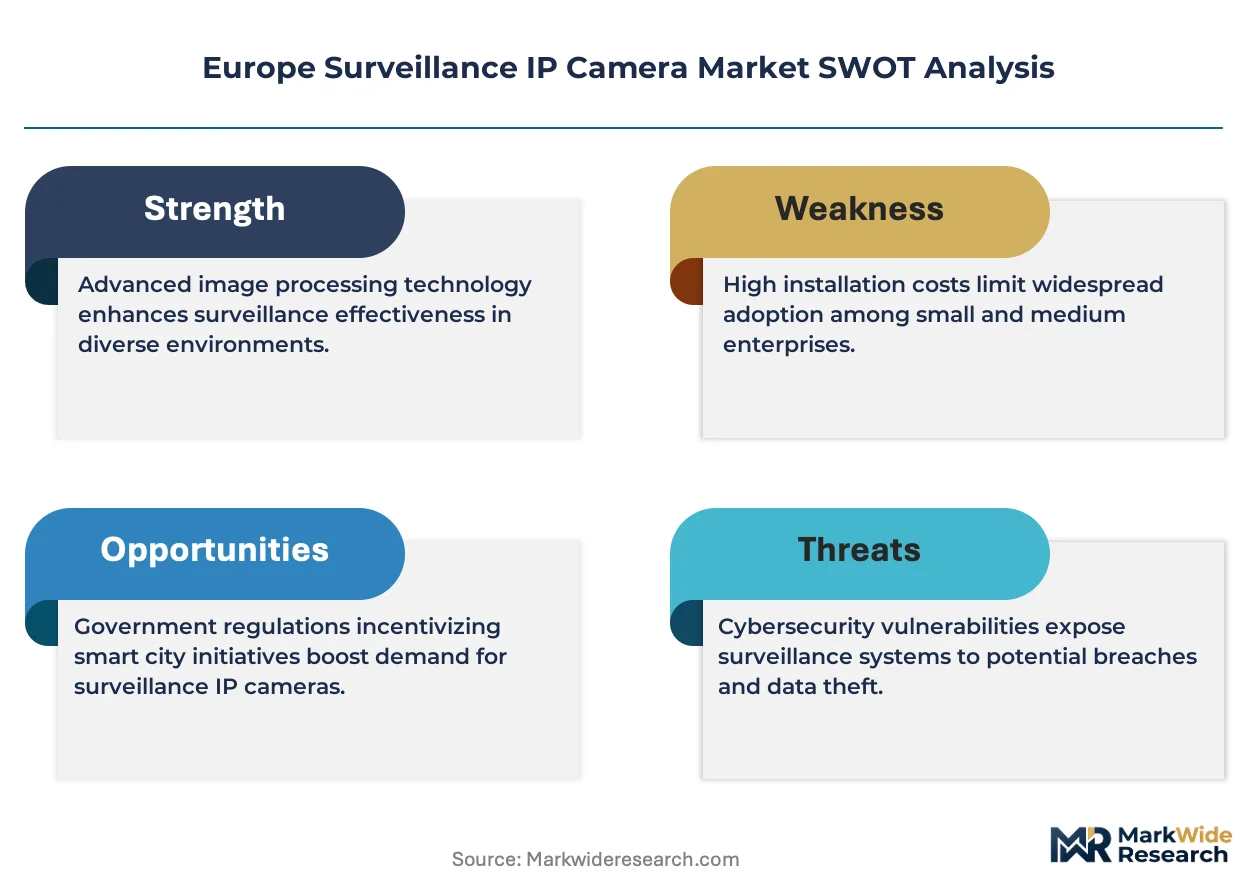
The EU AI Act and GDPR compliance deadlines are compressing firmware development cycles across the Europe Surveillance IP Camera Market, forcing manufacturers to redesign edge-computing architectures for privacy-by-design certification before 2026 enforcement windows.
Growth Catalysts
- Smart city infrastructure mandates:German municipal authorities are accelerating procurement of networked video systems for traffic management and public safety operations, with federal funding streams backing large-scale deployments.
- GDPR Article 32 security requirements:Critical infrastructure operators in France face mandatory security upgrade deadlines, driving replacement of legacy analog installations with IP-connected units featuring encrypted transmission protocols.
- Edge-based analytics processing:On-device AI inference capabilities are reducing bandwidth costs for manufacturing end users requiring real-time anomaly detection without cloud dependency.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends heavily on East Asian foundry capacity, exposing European integrators to lead-time volatility for 8MP and higher-resolution components.
- EU Cybersecurity Act certification timelines:The Common Criteria evaluation process for high-assurance security products extends market entry by 12-18 months for vendors without existing certified product lines.
- Biometric analytics restrictions:National data protection authorities in multiple member states are imposing divergent facial recognition moratoriums, fragmenting product roadmap requirements across borders.
Strategic Opportunities
- Polish manufacturing cluster development:Component suppliers establishing assembly operations near Wrocław and Kraków offer tariff-advantaged sourcing for Central and Eastern European distribution networks.
- Healthcare facility modernization:Hospital security directors are adopting vandal-resistant dome cameras with fall-detection analytics for patient safety monitoring, opening a specialized application vertical.
- CE marking convergence with Radio Equipment Directive:Harmonized cybersecurity resilience requirements are creating first-mover advantages for vendors achieving combined certification ahead of 2025 implementation deadlines.
Industry Challenges
- Firmware engineering talent scarcity:Embedded systems developers with H.265 encoding and edge-AI optimization skills command premium compensation, constraining R&D scaling for mid-tier vendors.
- Legacy analog migration complexity:Critical infrastructure operators face integration friction when connecting existing coaxial cable infrastructure to IP-based video management platforms without full site rewiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Surveillance IP Camera Market |
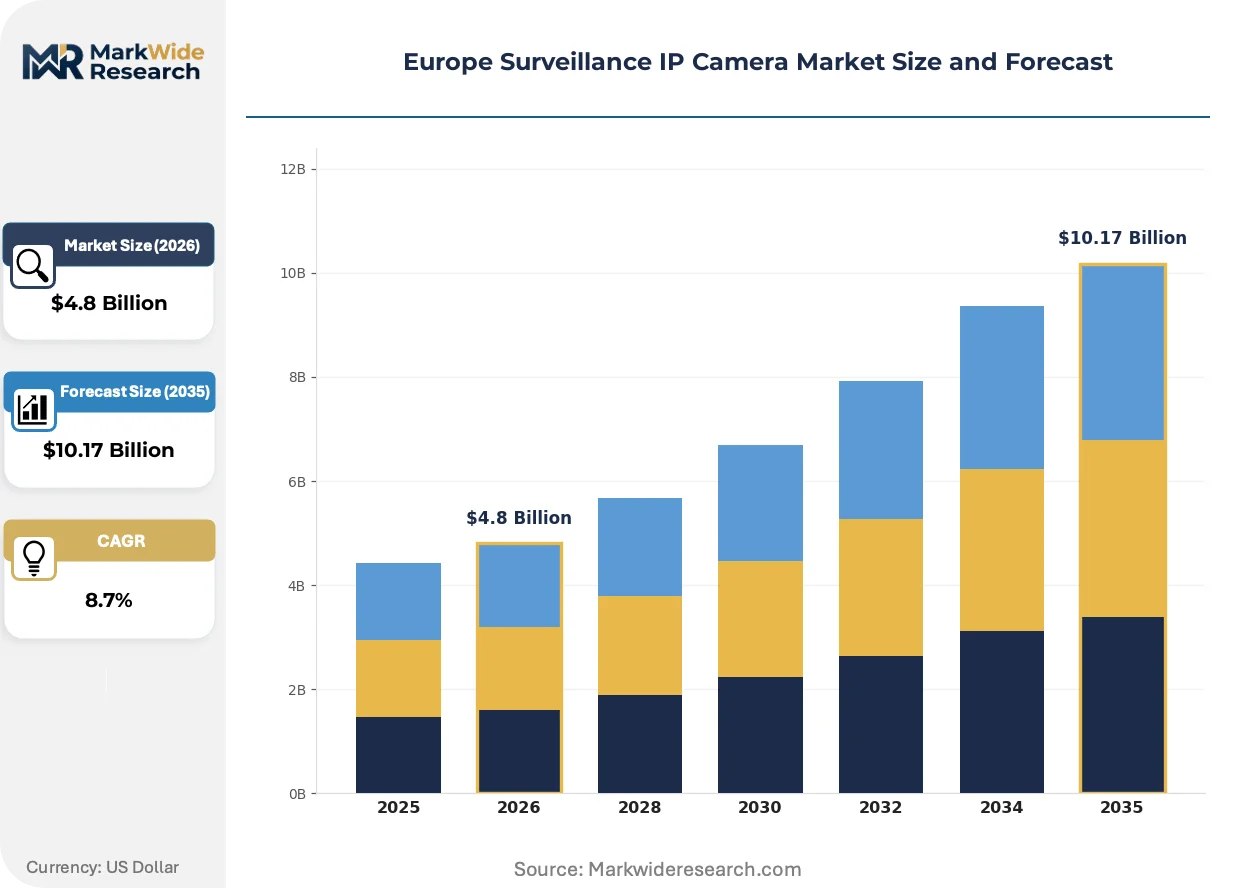
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Dome, Bullet, PTZ, Fisheye Technology: Analog, HD-TVI, AHD, IP End User: Retail, Education, Healthcare, Manufacturing Installation Type: Indoor, Outdoor, Wireless, Wired |
| Companies Covered | Hanwha Vision Co., Ltd., Dahua Technology, Bosch Security Systems GmbH, Vivotek Inc., Sony Corporation, Axis Communications AB, MOBOTIX AG, The Infinova Group, Hangzhou Hikvision Digital Technology Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Surveillance IP Camera Market Trends and Innovations
Three interconnected developments are reshaping product architecture and go-to-market approaches across European surveillance markets: edge-computing migration, regulatory compliance automation, and procurement centralization.
Multi-sensor panoramic cameras are migrating from centralized server-based analytics to on-device processing for object classification and perimeter intrusion detection. Airport security directors and logistics warehouse operators are adopting these units to reduce network bandwidth consumption by 60-70% while maintaining real-time alert capabilities. This technology shift is compressing margins for traditional video management software vendors as camera-native intelligence reduces dependency on third-party analytics licenses.
The EU AI Act's risk-based classification system for biometric identification systems is forcing product teams to segregate facial recognition capabilities into separately certifiable firmware modules. Industrial consequence includes mandatory human-in-the-loop requirements for real-time identification in public spaces, with most affected vendors targeting law enforcement and transportation hub segments for controlled pilot deployments rather than broad commercial rollout.
Consolidated procurement frameworks are displacing fragmented site-by-site purchasing across retail and healthcare chains. Security directors at multi-site operators now mandate centralized vendor accreditation with standardized API integration requirements, favoring open-platform architectures over proprietary ecosystems. France and Germany exhibit the most advanced procurement centralization, with national purchasing cooperatives negotiating three-year framework agreements covering hardware, installation, and maintenance services.
Europe Surveillance IP Camera Market Segmentation
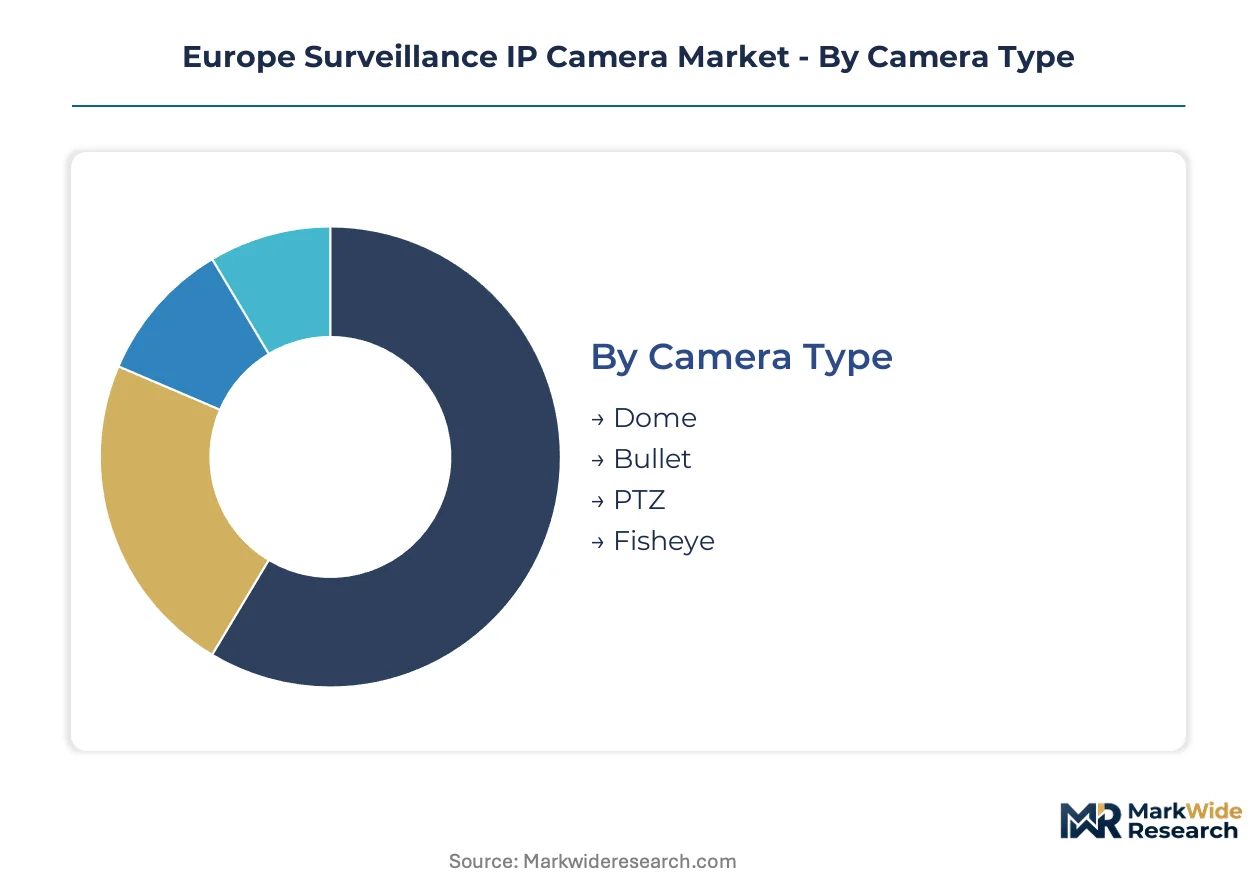
Segmentation in the Europe Surveillance IP Camera Market reveals how procurement priorities diverge across installation environments, compliance requirements, and analytics sophistication. Understanding these divisions enables vendors to align product roadmaps with the specific technical and regulatory demands of each buyer cohort.
Camera Type:
Mature form factors dominate established verticals while emerging designs capture specialized applications requiring expanded field-of-view or operator control.
- Dome:Vandal-resistant housings with discreet positioning capabilities serve indoor retail and healthcare deployments across France and Germany. Hospital security directors specify these units for patient safety monitoring with fall-detection analytics, while French retail chains prioritize aesthetic integration with store interiors.
- PTZ:Pan-tilt-zoom functionality enables operator-controlled surveillance across large perimeters and transportation hubs. German municipal authorities deploy these for traffic management and public safety operations, with federal funding streams accelerating procurement for smart city infrastructure.
- Bullet:Weather-resistant cylindrical housings target outdoor perimeter defense with fixed focal lengths. Polish manufacturing facilities specify these for site-security integration with access-control systems.
- Fisheye:Ultra-wide-angle lenses deliver 360-degree coverage from single mounting points. Logistics warehouse operators in the Netherlands adopt these for inventory monitoring with dewarping software.
Dome cameras handle the majority of throughput; PTZ is the fastest mover on share.
Technology:
Cost tiers separate legacy infrastructure from encrypted networked systems, with compliance deadlines forcing migration toward higher-assurance architectures.
- IP:Digital networked devices transmitting H.265 compressed streams over Ethernet or Wi-Fi infrastructure with edge-based analytics. Critical infrastructure operators in France face mandatory GDPR Article 32 security upgrade deadlines, driving replacement of legacy installations with encrypted transmission protocols.
- Analog:Coaxial-based video transmission systems approaching end-of-life across European member states. Migration friction persists where full site rewiring costs exceed incremental upgrade budgets.
- HD-TVI:High-definition transport video interface enabling 1080p resolution over existing coaxial cabling. Mid-tier municipal contractors in Spain specify these for budget-constrained retrofits.
- AHD:Analog high-definition technology competing on price-performance for small-scale commercial installations. Italian independent retailers deploy these for basic property protection without analytics requirements.
IP technology commands premium positioning; HD-TVI maintains residual volume in retrofit-heavy segments.
End User:
Application-specific requirements create divergent demand patterns across verticals with varying security postures and integration complexity.
- Manufacturing:Stringent site-security requirements and access-control integration generate concentrated margin pools. German automotive plants specify edge-computing capable units with real-time anomaly detection for production line monitoring.
- Healthcare:Vandal-resistant dome cameras with patient safety analytics address fall detection and wandering prevention. French hospital networks centralize procurement through national purchasing cooperatives.
- Retail:Multi-site chains mandate centralized vendor accreditation with standardized API integration. Open-platform architectures displace proprietary ecosystems across France and Germany.
- Education:Campus-wide deployments balance perimeter security with privacy-by-design constraints. GDPR compliance limits biometric analytics deployment in student-facing environments.
Manufacturing absorbs the highest equipment spend per site; Healthcare is expanding most quickly as facility modernization accelerates.
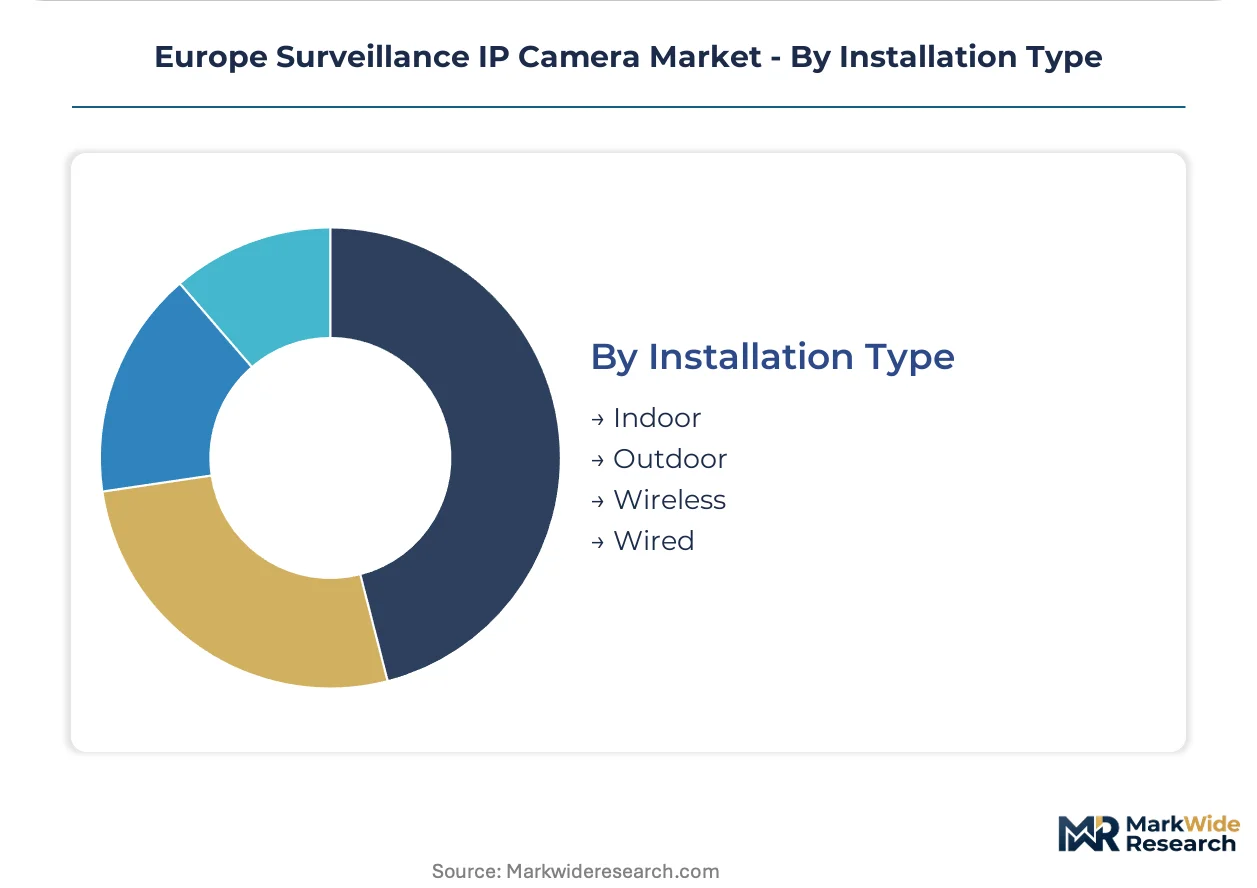
Installation Type:
Volume concentration reflects infrastructure maturity while wireless adoption climbs in heritage buildings and temporary deployments.
- Outdoor:Weatherproof housings with IP66+ ratings and infrared illumination for perimeter defense. Airport security directors across Northern Europe specify these for runway and cargo area coverage.
- Wired:Ethernet and fiber-optic backbone installations delivering guaranteed bandwidth for high-resolution streams. German smart city projects mandate wired infrastructure for traffic management systems.
- Indoor:Climate-controlled environments enabling compact form factors and lower power consumption. Polish healthcare facilities prioritize these for corridor and common area coverage.
- Wireless:Wi-Fi and cellular backhaul for heritage structures where cable routing is prohibited. Temporary construction site monitoring in Spain leverages these for rapid deployment.
Wired installations carry the bulk of current deployment; Wireless is gaining share fastest in constrained infrastructure segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement by the CNIL anchors France's regulatory gravity, while German smart city funding and Polish manufacturing clusters reshape procurement geography across the continent.
Germany
Federal smart city infrastructure mandates accelerate municipal procurement of networked video systems for traffic management and public safety operations. The KBA coordinates cybersecurity resilience requirements under the EU Cybersecurity Act with national transport security standards. Engineering centers in Stuttgart and Munich anchor Bosch Security Systems GmbH's European production footprint while extending distribution reach into Central and Eastern European markets.
France
Critical infrastructure operators face mandatory GDPR Article 32 security upgrade deadlines, driving replacement of legacy analog installations with IP-connected units. The CNIL enforces divergent biometric analytics restrictions that fragment facial recognition deployment across member states. National purchasing cooperatives in Île-de-France negotiate three-year framework agreements covering hardware, installation, and maintenance services for hospital networks.
Poland
Component suppliers establish assembly operations near Wrocław and Kraków to capture tariff-advantaged sourcing for Central and Eastern European distribution networks. The country's national data protection authority interprets EU AI Act risk classifications for biometric identification systems. Manufacturing facilities in the Silesian Voivodeship specify bullet cameras for site-security integration with access-control systems.
United Kingdom
Healthcare facility modernization drives adoption of vandal-resistant dome cameras with fall-detection analytics for patient safety monitoring. The Information Commissioner's Office enforces GDPR compliance timelines for encrypted transmission protocols in critical infrastructure. London-based security directors at multi-site retail chains mandate centralized vendor accreditation with standardized API integration requirements.
Netherlands
Logistics warehouse operators adopt fisheye cameras with dewarping software for inventory monitoring and perimeter intrusion detection. The country's national data protection authority coordinates with the EDPB on biometric analytics moratoriums affecting real-time identification deployments. Rotterdam port authorities deploy PTZ units for cargo area coverage with edge-based analytics processing.
Europe Surveillance IP Camera Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player tiers: German engineering-centric specialists, East Asian volume manufacturers, and Nordic open-platform architects. Strategic moves center on privacy-by-design firmware certification acceleration and Polish manufacturing cluster access for tariff-optimized distribution.
Within the engineering-specialist tier, Bosch Security Systems GmbH and MOBOTIX AG exemplify precision manufacturing archetypes with embedded systems expertise. Dahua Technology occupies a position among scale-driven fabricators competing aggressively on price-performance ratios for mid-tier municipal contracts. Axis Communications AB anchors the open-platform architecture segment, specializing in third-party video management software integration.
| Leading Market Players |
|---|
| Hanwha Vision Co., Ltd. |
| Dahua Technology |
| Bosch Security Systems GmbH |
| Vivotek Inc. |
| Sony Corporation |
| Axis Communications AB |
| MOBOTIX AG |
| The Infinova Group |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Wrocław and Kraków assembly clusters are expanding tariff-advantaged capacity for Central and Eastern European distribution, compressing landed costs for mid-tier municipal contractors while premium vendors anchored in German engineering centers maintain pricing power through firmware certification differentiation. This geographic bifurcation creates divergent margin structures across the Europe Surveillance IP Camera Market.
Pricing Analysis
Price spreads between German-engineered units and Polish-assembled alternatives reach three-to-one multiples across comparable resolution tiers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked cybersecurity-certified units from basic IP connectivity offerings. Cost compression in the standard tier is intensifying because Dahua Technology and Hangzhou Hikvision Digital Technology Co., Ltd. compete aggressively on price-performance ratios for mid-tier municipal contracts. Municipal procurement teams exhibit highest price sensitivity; critical infrastructure operators in France and Germany prioritize certification grade over unit cost.
Supply Chain Analysis
EU export-control regimes on advanced image sensors and AI accelerators constrain flows from East Asian foundries, extending lead-time volatility for 8MP and higher-resolution components. Image sensor fabrication draws heavily from Taiwan and South Korea; edge-AI chip packaging concentrates in China and Vietnam. Semiconductor supply concentration creates single-source vulnerability for European integrators requiring on-device inference capabilities. Distribution runs through German engineering centers for premium tiers and Polish assembly clusters for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization across French hospital networks and German retail chains is fragmenting vendor accreditation requirements, creating niche openings for specialized compliance architectures and regional assembly partnerships.
For Market Incumbents: Build firmware certification moats around EU AI Act and GDPR privacy-by-design architectures before enforcement windows compress development cycles. Bosch Security Systems GmbH and Axis Communications AB should accelerate Common Criteria evaluation timelines under the EU Cybersecurity Act to extend market entry barriers against East Asian volume manufacturers. Channel control through three-year framework agreements with national purchasing cooperatives in France and Germany locks out mid-tier competitors lacking balance-sheet depth for long-term service bundling. For New Entrants and Emerging Players: Establish a beachhead in Polish manufacturing cluster development by partnering with component suppliers near Wrocław and Kraków for tariff-optimized distribution into Central and Eastern European markets. Healthcare facility modernization in the United Kingdom and Netherlands offers the most penetrable vertical, with hospital security directors adopting vandal-resistant dome cameras with fall-detection analytics for patient safety monitoring. Go-to-market positioning should emphasize open-platform API integration to satisfy centralized procurement mandates from multi-site retail and healthcare chains. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with embedded systems expertise and existing CE marking convergence with the Radio Equipment Directive. Long-term viability over the next decade hinges on privacy-by-design firmware architectures that segregate biometric analytics into separately certifiable modules under EU AI Act risk classifications. Acquisition targets should display Polish manufacturing footprint combined with German engineering accreditation. The signal to watch is divergence in national data protection authority interpretations of facial recognition moratoriums, which will fragment product roadmap requirements and favor vendors with modular firmware architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Firmware Certification | EU AI Act compliance deadlines force edge-computing architecture redesigns before enforcement windows. |
| Polish Manufacturing Cluster Expansion | Tariff-advantaged assembly near Wrocław and Kraków optimizes Central and Eastern European distribution economics. |
| Open-Platform API Integration | Centralized procurement mandates from French hospital networks favor standardized third-party video management software compatibility. |
| Healthcare Vertical Specialization | Fall-detection analytics for patient safety monitoring opens specialized application vertical beyond traditional security. |
| Cybersecurity Resilience Certification | Common Criteria evaluation under the EU Cybersecurity Act extends market entry timelines for uncertified competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with security directors at multi-site retail chains, hospital procurement managers in French national purchasing cooperatives, municipal traffic management officials in Germany, and manufacturing facility engineers in Poland's Silesian Voivodeship. Secondary validation drew from CE marking databases under the Radio Equipment Directive, GDPR enforcement actions by the CNIL and national data protection authorities, EU Cybersecurity Act certification timelines, and customs records of image sensor imports. Bottom-up unit shipment estimates by camera type and technology tier were triangulated against top-down market value reconstruction.
Calibration against historical analog-to-IP migration patterns and smart city infrastructure procurement cycles anchored the projection framework across the analysis window. Segmentation dimensions modeled include camera type, technology tier, end-user vertical, installation environment, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and compliance-driven replacement cycles. Key inputs encompassed GDPR Article 32 security upgrade deadlines for critical infrastructure operators and federal funding stream allocations for German municipal networked video systems.
Stress conditions across semiconductor supply volatility, divergent biometric analytics moratoriums, and CE marking timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enforcement consistency for the EU AI Act and GDPR across member states. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Rugged Thermal Cameras Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Video Surveillance Market