
 Japan Video Surveillance Market | 2026-2036
Japan Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Video Surveillance Market Insights
Buyer concentration across Japan's transportation sector is decoupling from traditional municipal procurement patterns as private rail operators and logistics developers establish independent surveillance specifications. Panasonic Connect Co., Ltd. leverages its railway heritage to dominate platform monitoring contracts across JR East and JR West networks. Axis Communications AB anchors premium IP camera supply for Tokyo's commercial redevelopment zones through specialized channel partnerships. NEC Corporation differentiates on facial recognition integration with existing government identity databases.
Video surveillance encompasses networked camera systems, video management software, and analytics platforms designed for real-time monitoring, forensic review, and automated threat detection, typically operating at resolutions from 2MP to 8MP with H.265 compression and ONVIF protocol compatibility. IP Cameras lead product category value as rail operators replace analog infrastructure with Power-over-Ethernet deployments. Cloud-Based and Hybrid deployment models are expanding fastest among retail chains seeking centralized oversight of distributed storefronts. Edge Computing configurations concentrate margin pools where latency-sensitive applications demand local processing without backbone dependency.
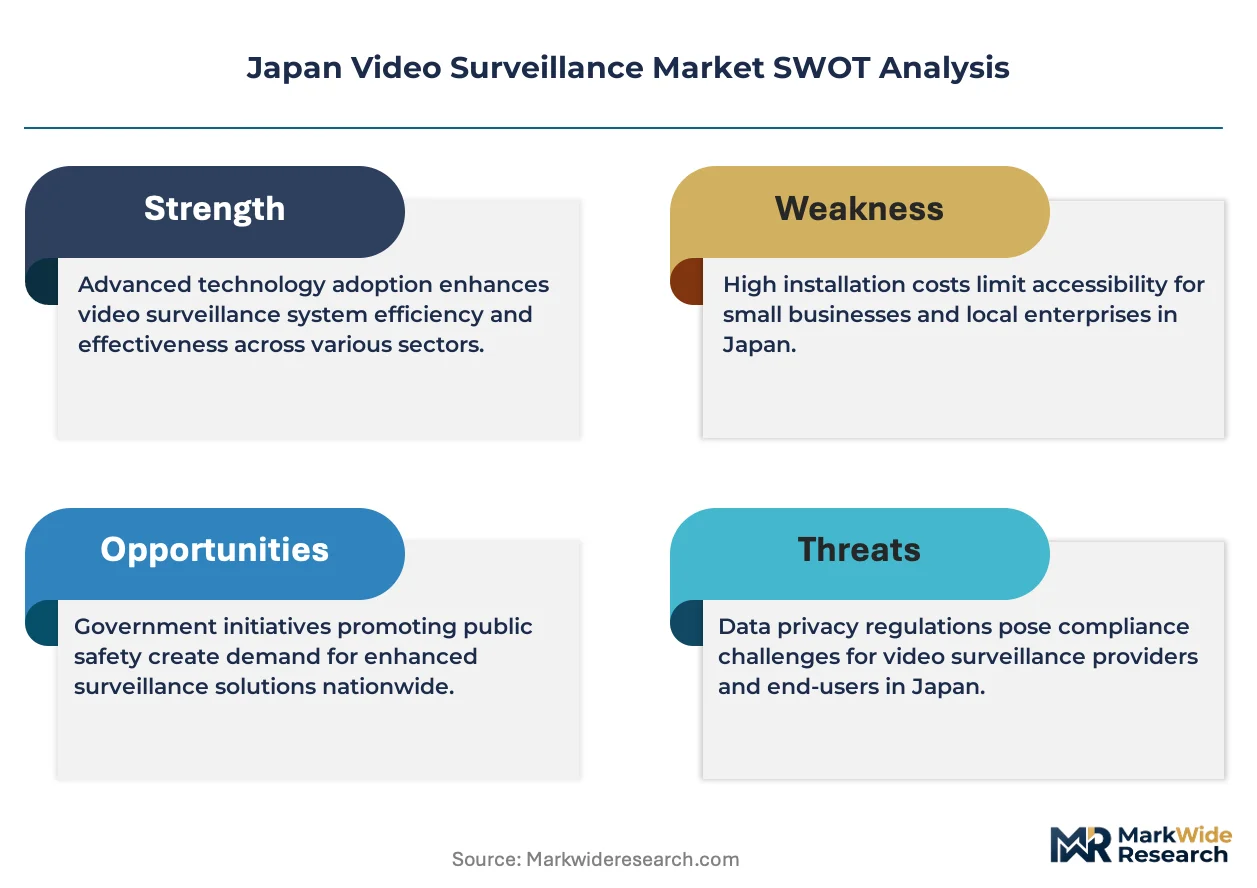
METI's cybersecurity guidelines for critical infrastructure and PMDA-adjacent data governance frameworks shape hardware certification requirements and cross-border data handling protocols for surveillance vendors. Japan's APPI enforcement by the Personal Information Protection Commission restricts biometric analytics deployment without explicit opt-in mechanisms, redirecting R&D toward privacy-preserving video analytics. Stakeholders must monitor evolving JIS standards for IoT device security and assess whether domestic manufacturing incentives alter component sourcing strategies for camera assemblies.
Market Dynamics
Japan's video surveillance sector is reconfiguring around edge-computing architectures as railway operators and municipal governments demand real-time analytics without cloud dependency. This infrastructure shift compresses hardware refresh cycles and elevates cybersecurity certification requirements under METI guidelines.
Growth Catalysts
- APPI Amendment Compliance:Municipal governments in Tokyo and Osaka are accelerating camera replacements to meet tightened consent frameworks for biometric data processing. Procurement specifications now mandate privacy-preserving analytics modules.
- Edge Computing at Transport Nodes:JR East and JR West networks are deploying Power-over-Ethernet camera systems with onboard GPU processing for platform crowd density monitoring. Latency requirements below 50 milliseconds prevent cloud-reliant architectures.
- Logistics Hub Modernization:Automated warehousing developments in Chiba and Kanagawa prefectures are specifying IP camera networks with integrated barcode scanning and worker safety detection.
Market Restraints
- APPI Consent Architecture:Facial recognition deployment requires explicit opt-in mechanisms that complicate public space installations. The Personal Information Protection Commission enforcement has stalled several smart city pilot programs.
- Semiconductor Supply Concentration:Image sensor and edge-AI chip sourcing remains concentrated among Taiwanese and South Korean foundries. Geopolitical friction elevates inventory carrying costs for domestic integrators.
- Legacy Analog Infrastructure:Municipal maintenance budgets prioritize incremental upgrades over full IP migrations. Hybrid coaxial-Ethernet cabling extends depreciation timelines and fragments vendor support obligations.
Strategic Opportunities
- Hokkaido and Tohoku Regional Expansion:Tourism infrastructure and agricultural logistics in northern prefectures remain underpenetrated relative to Kanto and Kansai corridors. Prefectural governments are issuing smart region bonds for surveillance backbone investments.
- Retail Chain Centralization:Convenience store and pharmacy operators are consolidating distributed storefront monitoring into hybrid cloud-edge architectures. This creates demand for standardized API-integrated video management platforms.
- JIS IoT Security Certification:Pending standards for connected device hardening will create first-mover advantages for vendors achieving early compliance. Certification timelines of 12-18 months will temporarily constrain competitive entry.
Industry Challenges
- Cybersecurity Engineering Talent:Embedded systems security expertise for camera firmware and edge node hardening remains scarce relative to enterprise IT security pools. METI's critical infrastructure guidelines intensify qualification requirements.
- Interoperability with Legacy VMS:Municipal procurement often specifies backward compatibility with decade-old video management software. API bridging and transcoding middleware add integration cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Video Surveillance Market |
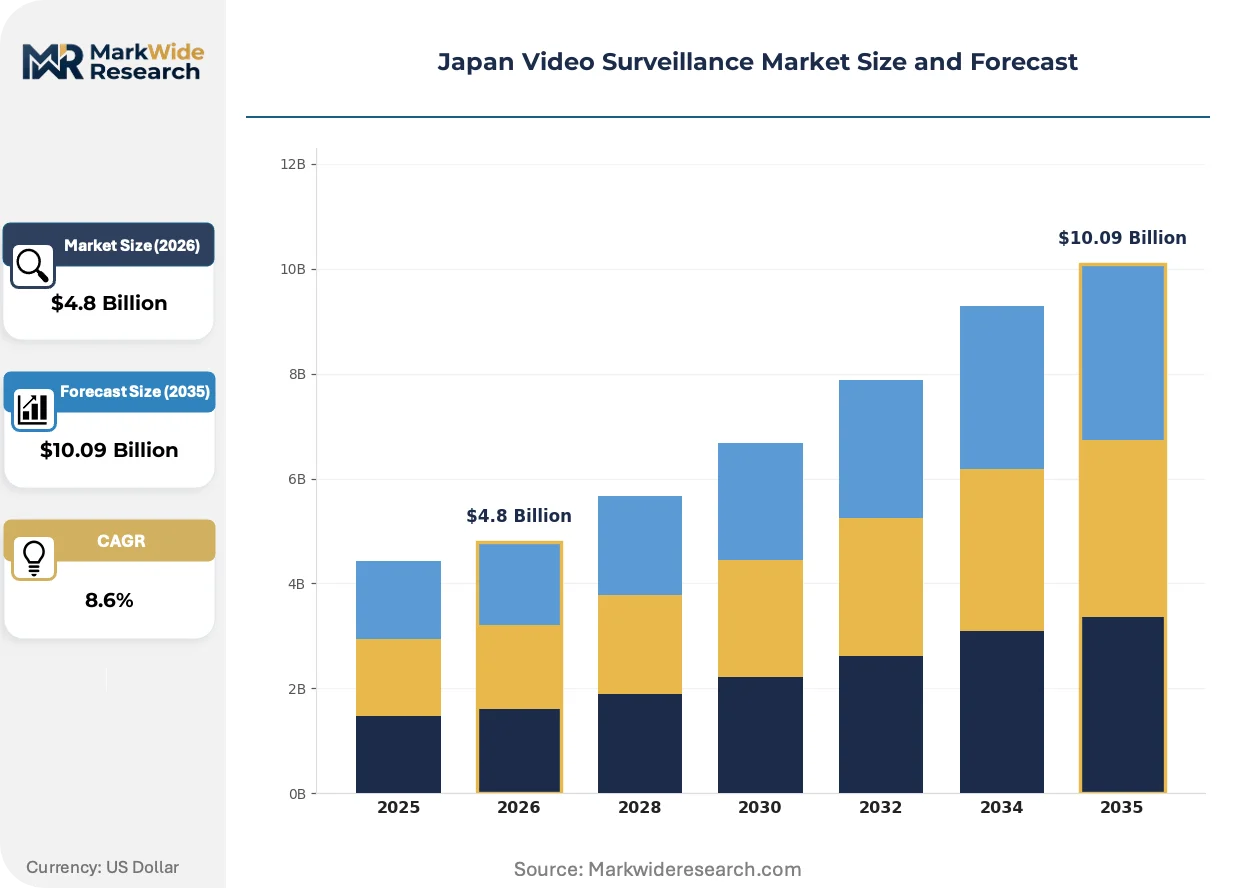
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, IP Cameras, Analog Cameras, Video Analytics Deployment Type: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Retail, Transportation, Banking, Government Technology: Motion Detection, Facial Recognition, Night Vision, Smart Analytics |
| Companies Covered | Zhejiang Dahua Technology Co., Ltd., Axis Communications AB, Panasonic Connect Co., Ltd., Canon Inc., NEC Corporation, Sony Corporation, Bosch Security Systems B.V., Hanwha Vision Co. Ltd, Hangzhou Hikvision Digital Technology Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Video Surveillance Market Trends and Innovations
Privacy-preserving video analytics and on-device processing are displacing centralized server architectures across Japanese surveillance deployments. Regulatory pressure and latency requirements are converging to reshape hardware specifications and procurement evaluation criteria.
Edge-based neural inference engines are automating real-time anomaly detection for railway platform safety and logistics perimeter monitoring. JR West has specified NVIDIA Jetson-powered cameras for Osaka station deployments, compressing response times from seconds to milliseconds. This capability is automating tier-1 alert triage that previously required human operator review, reducing control room staffing models.
METI's cybersecurity guidelines for critical infrastructure are mandating firmware signing and secure boot protocols for surveillance hardware deployed at energy and transport facilities. Vendors must submit to third-party penetration testing and maintain domestic incident response capabilities. Railway and nuclear facility operators are now excluding uncertified equipment from tender eligibility, accelerating compliance investments across the supplier base.
Consolidated service contracts are replacing discrete hardware-software-maintenance procurement at retail and logistics chains. Buyers are unbundling installation from ongoing platform management, favoring vendors with nationwide technician networks and API-accessible health monitoring. This restructuring is most visible among Tokyo-based convenience store operators with 500-plus location footprints seeking single-pane oversight.
Japan Video Surveillance Market Segmentation
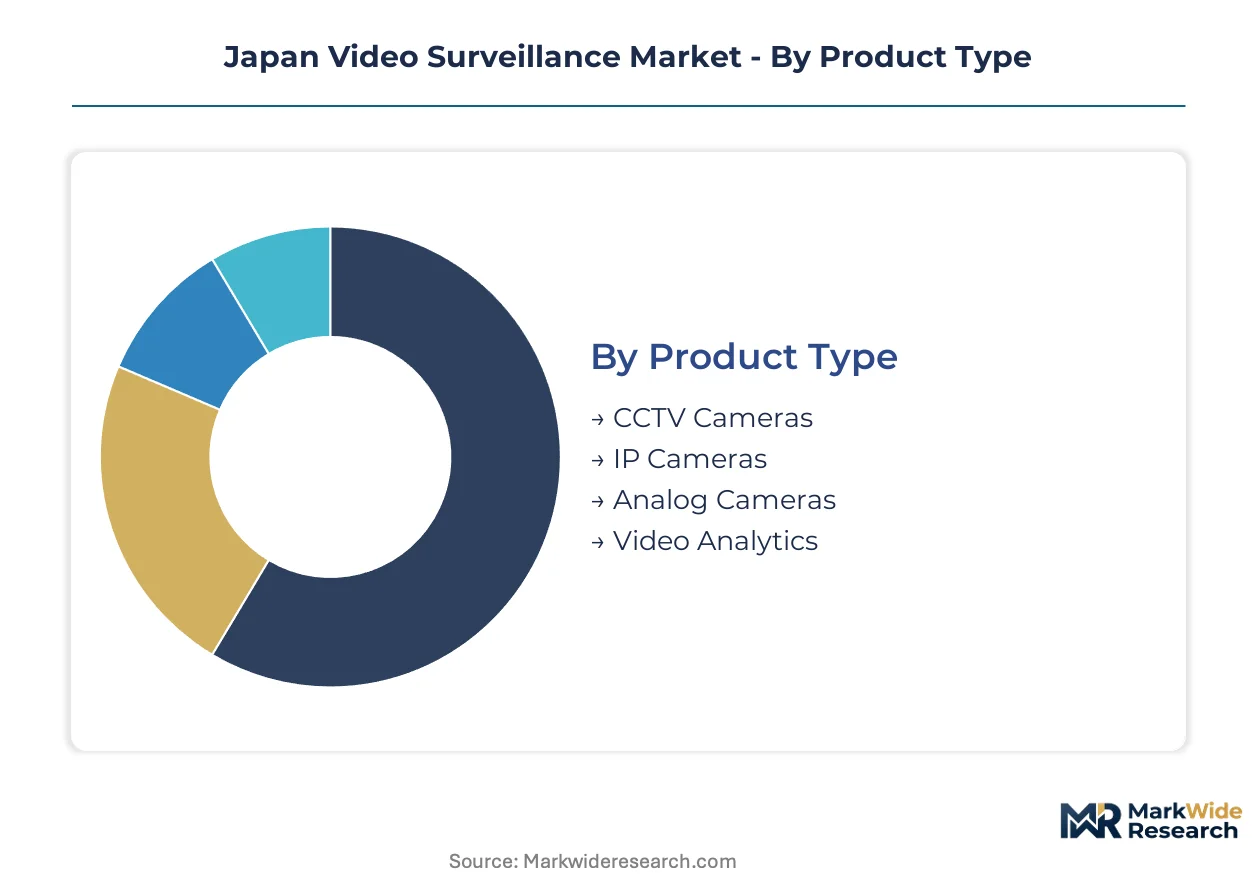
Procurement patterns across Japan's surveillance infrastructure reveal how upgrade cycles and regulatory compliance reshape category priorities. Municipal and private buyers segment investments by technical maturity, deployment risk, and long-term operational liability.
Product Type:
Camera replacement cycles dominate procurement planning as railway operators and municipal governments phase out aging analog infrastructure.
- IP Cameras:Power-over-Ethernet systems with H.265 compression and ONVIF protocol compatibility anchor new installations. JR East and JR West networks specify these for platform monitoring, driven by METI cybersecurity guidelines requiring firmware signing and secure boot protocols.
- Video Analytics:Privacy-preserving modules process biometric data at the edge without cloud transmission. Demand concentrates in Tokyo and Osaka municipal deployments where APPI amendments mandate explicit consent frameworks for facial recognition processing.
- CCTV Cameras:Legacy networked systems persist in budget-constrained municipal maintenance programs.
- Analog Cameras:Coaxial-cable infrastructure extends depreciation timelines in hybrid upgrade scenarios.
IP Cameras sits at the top of the volume ranking, with Video Analytics climbing the fastest.
Deployment Type:
Latency requirements and data sovereignty concerns fragment architecture preferences across critical infrastructure operators.
- Edge Computing:Onboard GPU processing enables sub-50-millisecond response times for platform crowd density monitoring. JR West's Osaka station deployment using NVIDIA Jetson-powered cameras automates tier-1 alert triage without backbone dependency.
- Hybrid:Split architectures balance local processing with centralized oversight for retail chains operating 500-plus location footprints. Tokyo convenience store operators favor this model for API-integrated health monitoring across distributed storefronts.
- On-Premises:Fully localized storage meets nuclear facility and energy sector cybersecurity requirements.
- Cloud-Based:Centralized video management expands among pharmacy and retail chains seeking single-pane oversight.
Edge Computing commands premium positioning, with Hybrid deployments expanding most quickly among multi-location operators.
End User:
Buyer sophistication varies sharply between regulated critical infrastructure and commercial applications.
- Transportation:Private rail operators establish independent specifications decoupled from municipal procurement. Panasonic Connect leverages railway heritage to dominate JR East and JR West platform monitoring contracts.
- Government:Tokyo, Osaka, and Fukuoka municipal governments accelerate camera deployments for public safety and crowd management. APPI compliance mandates redirect R&D toward privacy-preserving analytics modules.
- Retail:Convenience store operators consolidate distributed monitoring into standardized platforms.
- Banking:Branch networks specify integrated access control with surveillance analytics.
Transportation leads absolute spending, with Government procurement climbing fastest under tightened biometric consent frameworks.
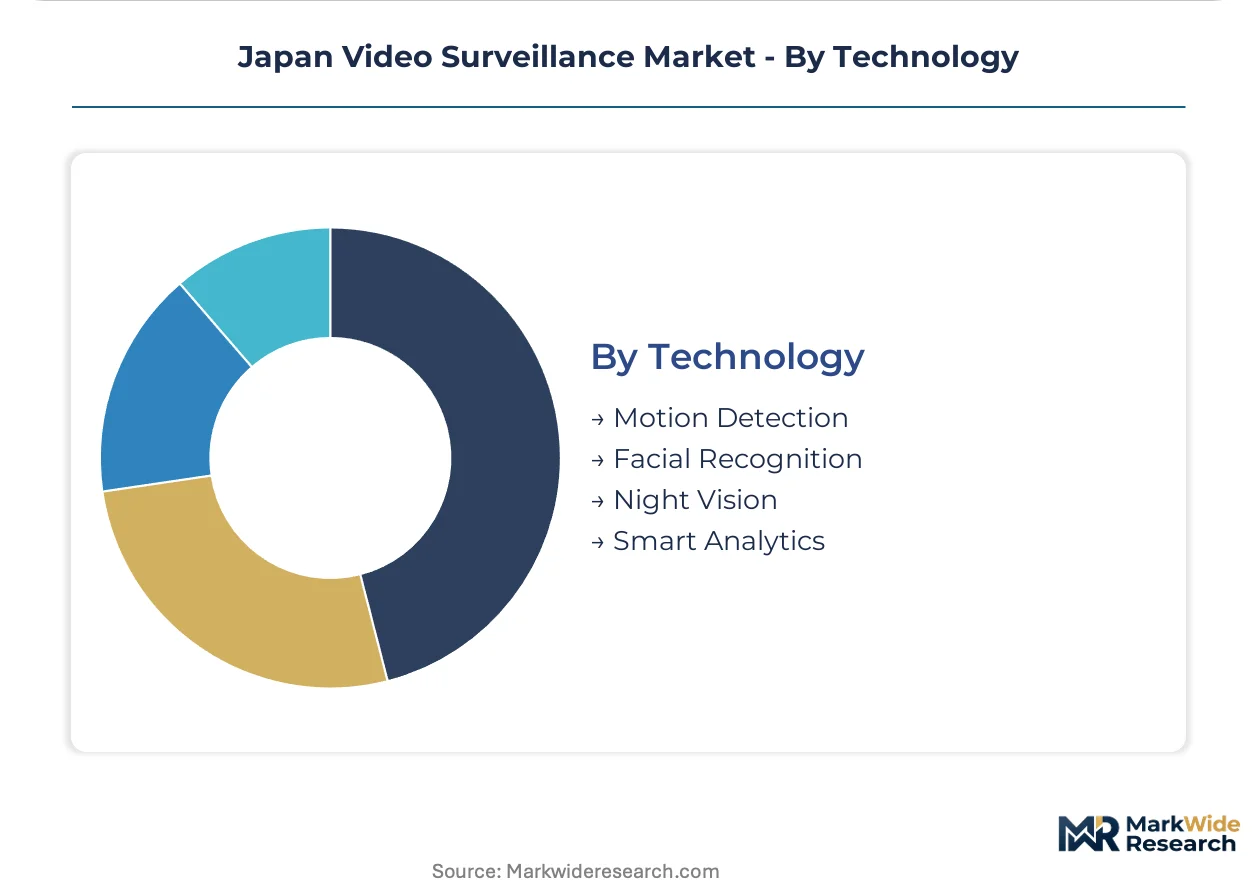
Technology:
Regulatory pressure and processing capability constraints reshape which analytics functions deploy at scale.
- Smart Analytics:Edge-based neural inference engines automate anomaly detection for logistics perimeter monitoring. Automated warehousing developments in Chiba and Kanagawa prefectures specify integrated barcode scanning and worker safety detection.
- Facial Recognition:Explicit opt-in requirements under Personal Information Protection Commission enforcement stall public space installations. NEC Corporation differentiates through integration with existing government identity databases where consent architectures permit deployment.
- Motion Detection:Baseline functionality saturates across legacy and new installations alike.
- Night Vision:Infrared-capable sensors standardize for 24-hour operational requirements at transport nodes.
Smart Analytics dominates R&D allocation, with Facial Recognition facing steepest regulatory headwinds despite technical maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Greater Tokyo, Osaka-Kobe, and Nagoya anchor Japan's video surveillance innovation clusters. Municipal procurement offices and railway operator headquarters cluster in these metros, shaping regional deployment patterns.
Kanto/Tokyo
Tokyo Metropolitan Government accelerates camera replacements for APPI-compliant biometric systems across Shinjuku and Shibuya wards. METI's cybersecurity guidelines mandate firmware signing for critical infrastructure deployments. The Yamanote Line corridor hosts concentrated demand from JR East for platform monitoring with sub-50-millisecond latency requirements.
Kansai/Osaka
Osaka City prioritizes crowd density analytics for Expo 2025 legacy infrastructure and ongoing commercial redevelopment zones. The Personal Information Protection Commission enforces explicit opt-in frameworks that redirect vendor R&D toward privacy-preserving modules. JR West's Osaka Station deployment anchors regional edge-computing specifications for railway safety.
Chubu/Nagoya
Logistics developers in Aichi and Mie prefectures specify IP camera networks with integrated barcode scanning for automated warehousing. Central Japan International Airport expansion drives perimeter security procurement with JIS IoT security certification requirements. Toyota Motor Corporation's supply chain influence extends to facility monitoring standards across the industrial corridor.
Kyushu
Fukuoka municipal government accelerates public safety camera deployments for tourism district management. Semiconductor packaging facilities in Kumamoto and Kagoshima elevate cybersecurity certification requirements under METI critical infrastructure guidelines. Regional smart city bonds finance surveillance backbone investments lagging Kanto deployment density.
Hokkaido and Tohoku
Agricultural logistics and cold-chain warehousing in Hokkaido generate underpenetrated demand relative to southern prefectures. Prefectural governments issue smart region bonds for surveillance infrastructure addressing tourism safety and rural security. Sapporo's winter tourism economy drives seasonal crowd management procurement distinct from year-round urban patterns.
Japan Video Surveillance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's procurement landscape. Railway operators and municipal governments segment vendor evaluation between full-stack integrators and component specialists. Three archetypes dominate: heritage electronics conglomerates with railway relationships, Nordic IP camera specialists with channel depth, and Chinese manufacturers with cost-optimized volume positioning. Competitive moves center on JIS certification pre-emption and consolidated service contract capture.
Among heritage conglomerates, Panasonic Connect Co., Ltd. exemplifies railway-anchored positioning through JR network relationships. Axis Communications AB represents Nordic specialist archetypes penetrating Tokyo commercial zones. NEC Corporation occupies government-identity integration positioning where biometric consent architectures permit deployment. Zhejiang Dahua Technology Co., Ltd. and Hangzhou Hikvision Digital Technology Co., Ltd. anchor volume-driven supply for cost-sensitive municipal segments. Canon Inc., Sony Corporation, and Hanwha Vision Co., Ltd. diversify across imaging sensor and camera assembly tiers.
| Leading Market Players |
|---|
| Zhejiang Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Panasonic Connect Co., Ltd. |
| Canon Inc. |
| NEC Corporation |
| Sony Corporation |
| Bosch Security Systems B.V. |
| Hanwha Vision Co. Ltd |
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Railway operators' sub-50-millisecond latency specifications for platform monitoring are compressing hardware refresh cycles and elevating cybersecurity certification requirements, forcing suppliers to absorb firmware signing and secure boot protocol costs while competing for JR East and JR West contracts.
Pricing Analysis
Capacity additions in Taiwanese and South Korean foundries are reshaping price floors for image sensors and edge-AI chips. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified systems with domestic incident response capabilities from uncertified alternatives. Cost compression in municipal procurement tiers is intensifying because hybrid coaxial-Ethernet cabling extends depreciation timelines. Government and critical infrastructure buyers demonstrate lowest price sensitivity due to cybersecurity mandates, while cost-optimized volume positioning dominates budget-constrained municipal maintenance programs.
Supply Chain Analysis
Dual-sourcing requirements from METI's critical infrastructure guidelines mandate multi-supplier qualification for surveillance hardware deployed at energy and transport facilities. Manufacturing concentrates in Taiwan, South Korea, and China for image sensors, edge-AI chips, and PoE camera assemblies. Component sourcing draws from semiconductor foundries, optical lens manufacturers, and cybersecurity firmware developers. Single-source vulnerability elevates inventory carrying costs for domestic integrators when geopolitical friction disrupts Taiwanese supply lines. Distribution runs through specialized channel partnerships for Tokyo commercial zones and direct railway procurement for JR network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's video surveillance market operates as a stable compounder, with APPI amendment compliance driving steady replacement demand across municipal and transportation infrastructure.
For Market Incumbents: Cement railway-anchored positioning through deeper JR East and JR West platform monitoring contracts before Nordic specialists expand channel depth. Prioritize JIS IoT security certification pre-emption to create 12-18 month competitive moats. Defend against Chinese manufacturers' cost-optimized volume positioning by bundling nationwide technician networks with API-accessible health monitoring.
For New Entrants and Emerging Players: METI's cybersecurity guidelines for critical infrastructure in Japan open a window for specialized embedded systems security firms to penetrate nuclear facility and energy sector procurement. Target Hokkaido and Tohoku smart region bonds for surveillance backbone investments where deployment density lags Kanto corridors. Enter through consolidated service contracts unbundling installation from ongoing platform management for retail chains with 500-plus location footprints.
For Investors and Strategic Acquirers: Asymmetric upside sits with privacy-preserving video analytics specialists possessing edge-computing IP and domestic incident response capabilities. Five-to-ten-year viability hinges on sustained APPI enforcement tightening biometric consent frameworks. Watch for Personal Information Protection Commission guidance clarifying opt-in architectures as the inflection signal indicating accelerated privacy-preserving module deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| JIS IoT Security Certification | First-mover compliance with pending standards creates 12-18 month competitive barriers for uncertified rivals. |
| Edge Computing Hardware Launch | NVIDIA Jetson-powered camera deployments at JR West's Osaka Station establish sub-50-millisecond latency benchmarks. |
| Privacy-Preserving Analytics Development | APPI-compliant modules redirect R&D investment away from stalled facial recognition public space installations. |
| Consolidated Service Contract Capture | Single-pane oversight platforms for Tokyo convenience store operators replace discrete hardware-software-maintenance procurement. |
| Hokkaido Regional Expansion | Smart region bonds finance surveillance infrastructure addressing agricultural logistics and winter tourism crowd management. |
Research Methodology
Multiple input streams — primary interviews with railway procurement officers, municipal technology directors, and logistics facility managers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Secondary sources included METI cybersecurity guideline documentation, Personal Information Protection Commission enforcement records, JR East and JR West technical specifications, and JIS standards drafts for IoT device security.
Data-stream reconciliation across product type, deployment architecture, end-user vertical, and regional prefecture dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, APPI compliance-driven upgrade timelines, and edge-computing adoption curves in railway and logistics applications. Forecast inputs incorporated semiconductor supply lead times and municipal bond issuance patterns for smart city infrastructure.
Revisions become necessary when METI cybersecurity guidelines expand certification requirements, Personal Information Protection Commission enforcement intensifies biometric consent scrutiny, or geopolitical friction disrupts Taiwanese and South Korean foundry supply. Deviation in semiconductor availability or JIS certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Coastal Surveillance Systems Market