
 Coastal Surveillance Systems Market | 2026-2036
Coastal Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Coastal Surveillance Systems Market Analysis
Multi-source procurement is recalibrating how defense ministries acquire coastal surveillance capabilities. Northrop Grumman Corporation leverages its integrated command-and-control heritage to anchor large-scale naval programs. Thales Group competes through electro-optical and radar fusion architectures across European and Asia-Pacific tenders. Leonardo S.p.A. specializes in portable coastal radar systems for littoral environments with limited infrastructure.
Coastal surveillance systems integrate radar, sonar, AIS, and electro-optical sensors into networked architectures for maritime domain awareness, typically operating at X-band or S-band frequencies with detection ranges from 20 to 200 nautical miles depending on antenna elevation and sea state conditions. Their primary purpose is to detect, track, and classify surface vessels for border control, maritime security, and search and rescue coordination. Radar and electro-optical technologies dominate installed base value due to their role in all-weather target acquisition, while AIS integration represents the fastest-growing layer as automatic identification becomes mandatory for vessel traffic management. Government and military end users command the largest budget pools, though fisheries enforcement agencies represent an emerging deployment channel for lower-cost mobile configurations.
The U.S. Coast Guard's acquisition framework and the EU's Integrated Maritime Policy shape certification requirements for cross-border interoperability, while India's Defence Acquisition Procedure mandates progressive indigenous content thresholds for coastal radar tenders. ISO 14001 environmental management and IEC 62388 maritime navigation standards increasingly influence sensor manufacturing specifications for export eligibility. Stakeholders must monitor how evolving encryption standards for AIS data exchange reshape system architecture roadmaps and supplier qualification criteria.
Market Dynamics
Naval modernization programs across Southeast Asian nations are compressing procurement cycles for integrated sensor platforms, while India's indigenous radar mandates force foreign suppliers to restructure local partnership models.
Growth Catalysts
- International Ship and Port Facility Security Code:Mandatory port security assessments under this UN framework require member states to deploy vessel tracking infrastructure, directly expanding coastal radar tender volumes.
- India's coastal command network expansion:The country's maritime security architecture is driving sequential procurement waves for indigenous coastal surveillance radar systems across 36 coastal districts.
- AIS integration:Automatic identification system mandates for commercial vessel traffic management are layering additional sensor requirements onto existing radar installations.
Market Restraints
- Gallium nitride supply concentration:Active electronically scanned array radar production depends on Chinese gallium nitride substrate suppliers, creating single-source vulnerability for Western defense contractors.
- Electromagnetic spectrum allocation friction:Civilian 5G deployment in C-band and X-band frequencies is compressing available bandwidth for maritime radar operations near major port cities.
- High-resolution electro-optical sensor costs:Thermal imaging and laser rangefinder modules require germanium and indium antimonide inputs subject to export control classifications.
Strategic Opportunities
- Fisheries enforcement mobile configurations:Southeast Asian maritime patrol agencies represent underpenetrated demand for trailer-mounted radar systems with 20-50 nautical mile detection envelopes.
- Sonar-radar fusion architectures:Convergence of underwater acoustic detection with surface radar tracking enables integrated seabed-to-surface monitoring for critical infrastructure protection.
- EU Integrated Maritime Policy certification alignment:Cross-border interoperability standards create qualification pathways for suppliers meeting IEC 62388 and ISO 14001 specifications simultaneously.
Industry Challenges
- Systems integration engineering talent scarcity:Defense contractors face competition from commercial autonomous vehicle and aerospace sectors for radar signal processing specialists.
- Legacy analog radar replacement complexity:Coast guard organizations operating 1980s-era magnetron systems require phased migration paths that preserve operational continuity during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coastal Surveillance Systems Market |
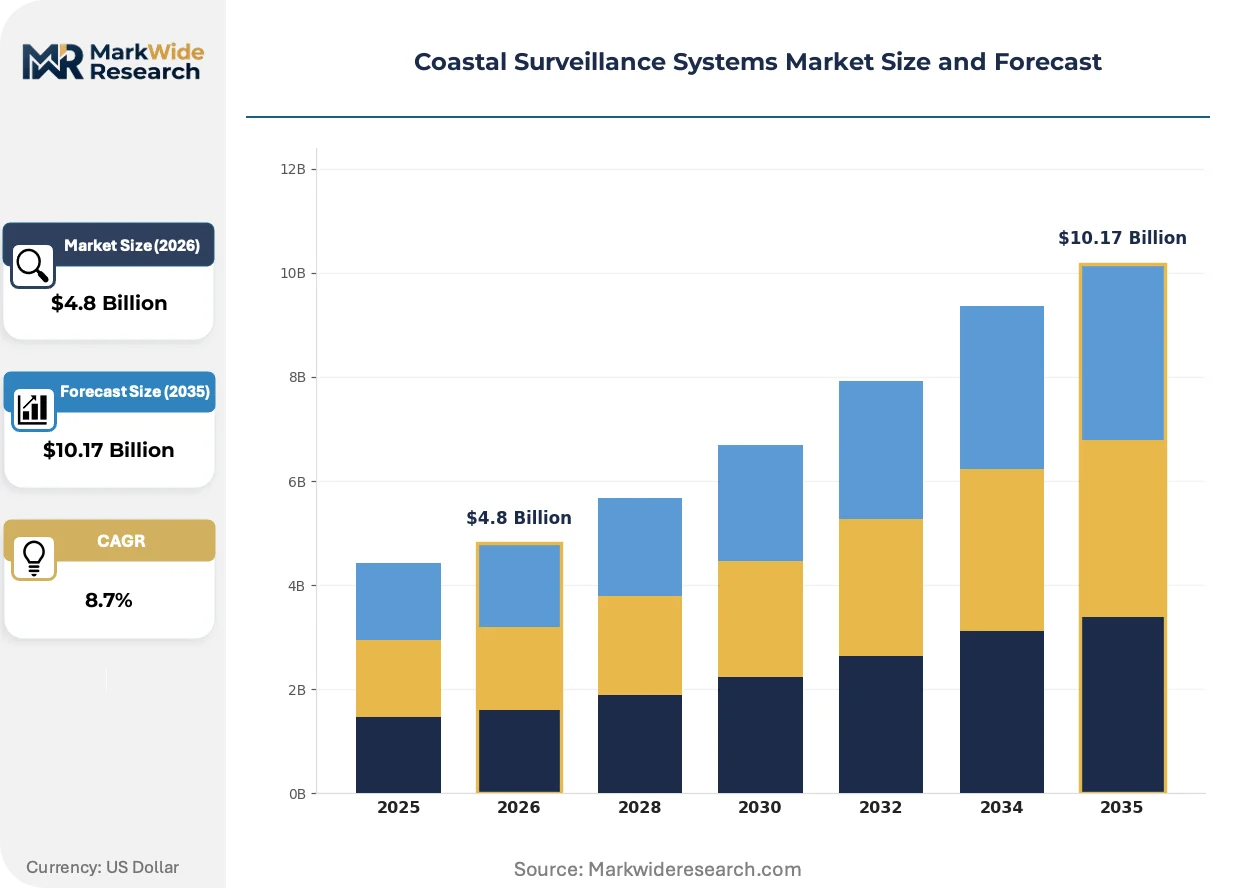
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Sonar, AIS, Electro-Optical Application: Border Control, Maritime Security, Environmental Monitoring, Search and Rescue End User: Government, Military, Coast Guard, Fisheries Deployment: Onshore, Offshore, Hybrid, Mobile |
| Companies Covered | Northrop Grumman Corporation, Indra Sistemas, Thales Group, Leonardo S.p.A., Kongsberg Gruppen ASA, RTX Corporation, L3Harris Technologies Inc., Elbit Systems Ltd., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coastal Surveillance Systems Market Emerging Trajectories
Synthetic aperture radar processing and machine-learning target classification are compressing the gap between raw sensor data and actionable maritime domain awareness for operator consoles.
Artificial intelligence-based automatic target recognition is integrating radar track histories with electro-optical imagery to reduce operator cognitive load during multi-vessel scenarios. Naval command centers in Australia and Japan are fielding these fusion systems for congested strait monitoring. The technology is integrating previously separate analyst workstations into unified threat-evaluation workflows.
REACH chemical substance restrictions are forcing sensor manufacturers to reformulate conformal coatings and printed circuit board laminates for export eligibility to European defense programs. Industrial consequences include extended qualification timelines for new material stacks. Radar suppliers serving NATO procurement channels are responding by dual-sourcing compliant substrate materials from Japanese and South Korean chemical firms.
Defense ministries are consolidating coastal surveillance procurement under national maritime security frameworks rather than fragmented agency budgets. The shift concentrates buying authority within naval headquarters and coast guard central commands, displacing port authority-led acquisitions. India's Defence Acquisition Procedure exemplifies this concentration, with coastal radar tenders now routing through integrated headquarters rather than individual state maritime boards.
Coastal Surveillance Systems Market Segmentation
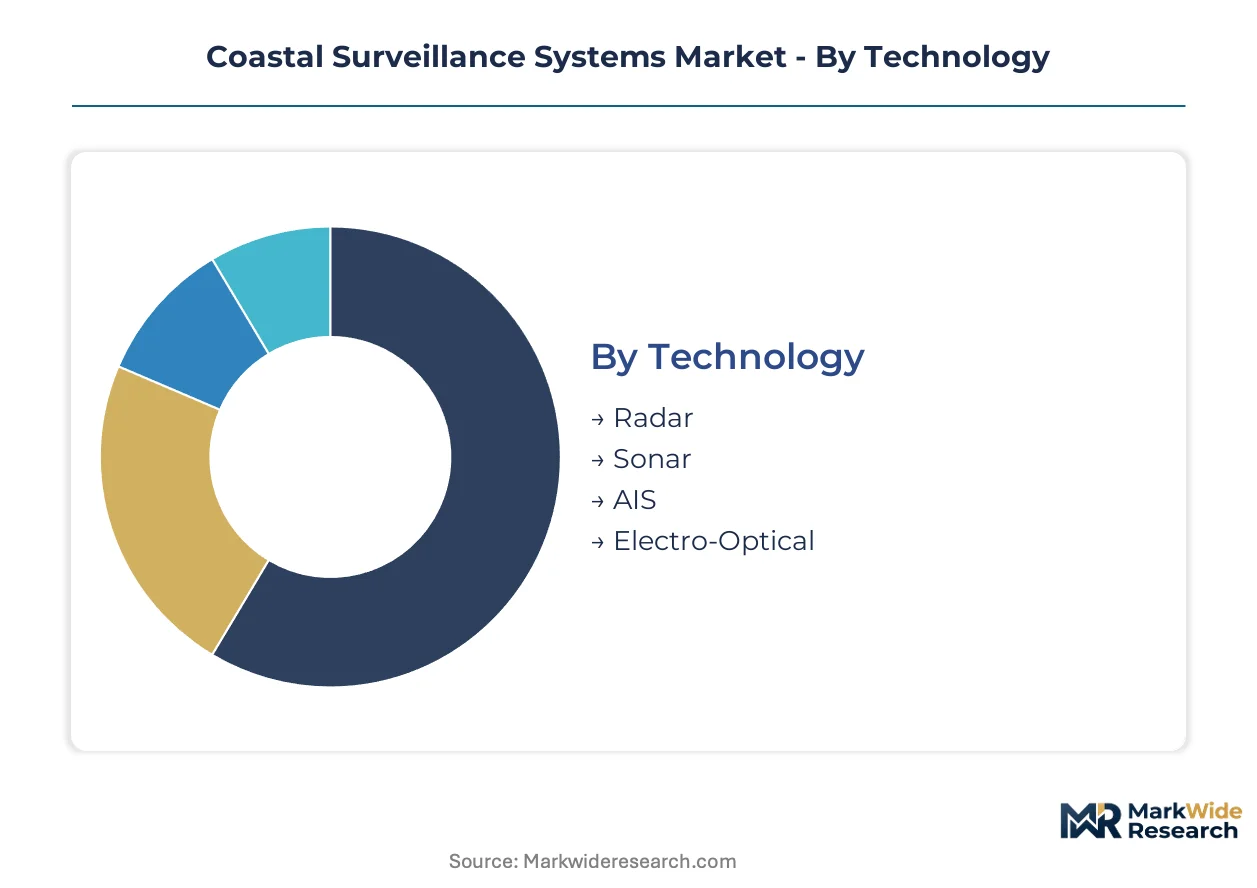
Coastal surveillance procurement splits across four critical dimensions that determine system architecture, sensor fusion requirements, and vendor qualification pathways. Upgrade cycles vary dramatically by deployment environment and end-user budget authority.
Technology:
Replacement timelines for legacy magnetron radars are compressing as active electronically scanned array platforms mature for maritime applications.
- Radar:X-band and S-band systems dominate installed base value through all-weather target acquisition capabilities. India's coastal command network expansion is driving sequential procurement waves for indigenous radar deployments across 36 coastal districts.
- Electro-Optical:Thermal imaging and laser rangefinder modules enable visual identification beyond radar classification limits. High-resolution sensor costs are constrained by germanium and indium antimonide export control classifications.
- AIS:Automatic identification system mandates for commercial vessel traffic management are layering additional sensor requirements onto existing installations.
- Sonar:Underwater acoustic detection converges with surface radar tracking for integrated seabed-to-surface monitoring of critical infrastructure.
Radar sits at the top of the volume ranking, with AIS climbing the fastest as mandatory carriage requirements expand vessel tracking coverage.
Application:
Cost tier differentiation separates sovereign-funded border protection from agency-level environmental monitoring programs with constrained capital cycles.
- Maritime Security:Integrated sensor platforms detect, track, and classify surface vessels for threat evaluation and interdiction coordination. Naval modernization programs across Southeast Asian nations are compressing procurement cycles for these systems.
- Border Control:Coastal radar networks with 20-200 nautical mile detection envelopes support territorial sovereignty enforcement and illegal immigration interdiction. Stringent port security mandates under the International Ship and Port Facility Security Code are reshaping system requirements.
- Search and Rescue:Vessel position data fusion with weather routing information accelerates emergency response coordination for distressed mariners.
- Environmental Monitoring:Oil spill detection and marine protected area enforcement utilize lower-cost electro-optical configurations with reduced range requirements.
Maritime Security commands the largest budget allocation, while Environmental Monitoring is gaining share fastest as marine conservation funding expands.
End User:
Customer type determines procurement authority concentration, with defense ministries consolidating buying power previously fragmented across port authorities.
- Military:Naval headquarters command integrated coastal surveillance architectures with command-and-control heritage requirements. India's Defence Acquisition Procedure exemplifies this concentration, routing coastal radar tenders through integrated headquarters.
- Government:National maritime security frameworks displace agency-led acquisitions through centralized budget authority and interoperability mandates.
- Coast Guard:Organizations operating 1980s-era magnetron systems require phased migration paths preserving operational continuity during technology transitions.
- Fisheries:Maritime patrol agencies in Southeast Asia represent underpenetrated demand for trailer-mounted radar systems with 20-50 nautical mile detection envelopes.
Military end users anchor procurement volume, with Fisheries expanding most quickly as enforcement agencies mobilize against illegal, unreported, and unregulated fishing.
Deployment:
Geography and infrastructure availability dictate platform selection, with remote littoral environments favoring portable configurations over fixed installations.
- Onshore:Fixed radar towers with elevated antenna positions maximize detection range for high-traffic coastal corridors. Civilian 5G deployment in C-band and X-band frequencies is compressing available bandwidth for maritime radar operations near major port cities.
- Mobile:Trailer-mounted systems enable rapid repositioning for fisheries enforcement and temporary security operations. Leonardo S.p.A. specializes in portable coastal radar systems for littoral environments with limited infrastructure.
- Hybrid:Networked architectures combine fixed coastal stations with deployable assets for surge capacity during elevated threat periods.
- Offshore:Platform-mounted sensors on buoys or artificial islands extend coverage beyond line-of-sight limitations of coastal terrain.
Onshore deployment retains the largest installed base, with Mobile configurations gaining share fastest as enforcement agencies prioritize operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's maritime technology cluster anchors procurement intensity for integrated coastal surveillance architectures across Southeast Asian littorals.
United States
The U.S. Coast Guard's acquisition framework drives vessel tracking infrastructure deployment along Atlantic and Pacific seaboards. FCC spectrum allocation proceedings shape radar frequency availability near major port cities. Defense contractors cluster around Washington DC-Northern Virginia corridor for command-and-control system integration.
India
Coastal command network expansion across 36 coastal districts generates sequential procurement waves for indigenous radar systems. The Defence Acquisition Procedure mandates progressive indigenous content thresholds for coastal radar tenders. Gujarat and Tamil Nadu host emerging domestic manufacturing partnerships for sensor platform assembly.
Japan
Naval command centers field AI-based target recognition systems for congested strait monitoring. METI industrial policy supports maritime domain awareness technology development. Yokohama-Kawasaki industrial zone concentrates electro-optical sensor fabrication for defense export programs.
Australia
Integrated seabed-to-surface monitoring requirements protect critical offshore infrastructure in Bass Strait and Northwest Shelf. The country's national maritime regulator enforces vessel traffic service standards for port approaches. Perth and Darwin anchor surveillance system maintenance hubs for northern coastline coverage.
South Korea
Active electronically scanned array radar production depends on gallium nitride substrate supply chains with Chinese concentration risk. The country's national defense procurement agency consolidates coastal surveillance under centralized naval headquarters authority. Busan-Ulsan shipbuilding corridor integrates sensor platforms into new naval construction programs.
Coastal Surveillance Systems Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue portable configurations for fisheries enforcement agencies. Tiered competition separates integrated command-and-control heritage suppliers from electro-optical fusion specialists and littoral radar fabricators. Two strategic archetypes dominate: aerospace-defense conglomerates leveraging naval program scale, and mid-cap specialists optimizing for limited-infrastructure deployments. Competitive moves concentrate on local partnership restructuring for indigenous content compliance and dual-sourcing material stacks for REACH chemical restrictions.
Within the integrated systems tier, Northrop Grumman Corporation and Thales Group represent contrasting geographic anchors for command-and-control heritage. Leonardo S.p.A. exemplifies the portable configuration specialist archetype for littoral environments with limited infrastructure. These three occupy positions across the technology spectrum from fixed coastal installations to trailer-mounted rapid deployment systems.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Indra Sistemas |
| Thales Group |
| Leonardo S.p.A. |
| Kongsberg Gruppen ASA |
| RTX Corporation |
| L3Harris Technologies Inc. |
| Elbit Systems Ltd. |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
Radar signal processing specialist concentration in the Washington DC-Northern Virginia corridor widens labor-cost differentials between integrated command-and-control systems and portable coastal radar configurations. REACH chemical compliance costs for conformal coatings and printed circuit board laminates compress margins at the standard tier while premium-tier suppliers pass through dual-sourced Japanese and South Korean substrate premiums.
Pricing Analysis
Input-cost pass-through from gallium nitride substrate scarcity and germanium export controls anchors pricing stratification across premium, standard, and economy tiers. Certification grade under EU Integrated Maritime Policy and ISO 14001 environmental management standards separates premium integrated architectures from lower-tier mobile configurations. Cost compression in the standard tier intensifies as fisheries enforcement agencies consolidate trailer-mounted procurement into volume tenders. Coast guard organizations with legacy magnetron replacement cycles demonstrate highest price sensitivity; naval headquarters with sovereign-funded modernization programs show lowest.
Supply Chain Analysis
Workforce availability constraints in South Korean and Japanese electro-optical fabrication hubs limit active electronically scanned array radar output expansion. Gallium nitride substrates draw from Chinese suppliers; germanium and indium antimonide hinge on export-controlled channels; conformal coating formulations source from Japanese and South Korean chemical firms. Single-source vulnerability in gallium nitride supply creates structural risk for Western defense contractors. Distribution runs through national defense procurement agencies with consolidated naval headquarters authority displacing fragmented port authority channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The International Ship and Port Facility Security Code functions as a regulatory compounder, mandating vessel tracking infrastructure that expands coastal radar tender volumes across member states.
For Market Incumbents: Hedge gallium nitride supply concentration by accelerating dual-sourcing partnerships with Japanese and South Korean substrate suppliers before Chinese export restrictions harden. Deepen backward integration into electro-optical sensor fabrication to capture margin from thermal imaging and laser rangefinder modules subject to germanium export controls. For New Entrants and Emerging Players: AI-based automatic target recognition systems offer a technology-first wedge into congested strait monitoring contracts in Australia and Japan where operator cognitive load reduction commands premium positioning. Fisheries enforcement mobile configurations in Southeast Asia represent the most penetrable white-space target; pursue trailer-mounted radar systems with 20-50 nautical mile detection envelopes through maritime patrol agency direct sales channels. For Investors and Strategic Acquirers: Defense conglomerates with naval program scale are the most active acquirer in this space, seeking electro-optical fusion specialists to complete integrated seabed-to-surface monitoring portfolios. Long-term viability centers on suppliers with demonstrated IEC 62388 and ISO 14001 simultaneous certification alignment for EU Integrated Maritime Policy compliance. Watch for AIS encryption standard revisions as the signal indicating system architecture roadmaps and supplier qualification criteria inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Local Partnership Restructuring | India's Defence Acquisition Procedure indigenous content thresholds force foreign suppliers to restructure Gujarat and Tamil Nadu manufacturing partnerships. |
| Dual-Sourcing Material Stacks | REACH chemical restrictions compel radar suppliers serving NATO procurement channels to dual-source compliant substrates from Japanese and South Korean chemical firms. |
| Sonar-Radar Fusion Development | Convergence of underwater acoustic detection with surface radar tracking enables integrated seabed-to-surface monitoring for Bass Strait critical infrastructure protection. |
| AI Target Recognition Integration | Machine-learning target classification compresses the gap between raw sensor data and actionable maritime domain awareness for congested strait operator consoles. |
| Mobile Configuration Scale-Up | Trailer-mounted radar systems address underpenetrated Southeast Asian maritime patrol agency demand for 20-50 nautical mile fisheries enforcement detection envelopes. |
Methodological Framework
Bottom-up fisheries enforcement and coast guard procurement modeling reconciled against top-down gallium nitride substrate supply tracking forms the analytical core. Primary interviews with naval program executives, defense procurement officers, radar signal processing engineers, and maritime patrol agency directors combined with secondary validation against customs trade data, SEC 10-K filings from aerospace-defense conglomerates, and national defense procurement agency tender databases. Triangulation between bottom-up segment builds and top-down supply-side capacity assessments ensures cross-verified output integrity.
Input-output matrix framing connects radar and electro-optical sensor production capacity to coastal command network expansion requirements across the projection horizon. Segmentation dimensions modeled include technology tier, application mission profile, end-user budget authority concentration, and deployment platform geography. CAGRs derive from sequential procurement wave timing for India's 36 coastal districts and Southeast Asian naval modernization program phasing. Industry-specific forecast inputs incorporate AIS mandate expansion trajectories and electromagnetic spectrum allocation friction near major port cities.
The model holds under stable gallium nitride supply continuity and progressive indigenous content threshold enforcement; deviation in Chinese export restriction severity or EU encryption standard revision timing would shift procurement cycle compression rates. Forecasts reflect documented assumptions regarding naval modernization program funding continuity and REACH chemical compliance timeline adherence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
France Surveillance Camera Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Global Body Worn Cameras Market