
 Asia-Pacific Surveillance Storage Market | 2026-2036
Asia-Pacific Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Surveillance Storage Market Insights
SSD density improvements are broadening cost-per-terabyte economics against traditional HDD arrays in high-write surveillance environments. Seagate Technology LLC leverages its platter manufacturing scale to sustain competitive positioning in bulk archival tiers across Chinese data centers. Huawei Technologies Co. Ltd anchors regional demand through integrated storage-networking bundles purpose-built for government security networks.
Asia-Pacific surveillance storage encompasses purpose-built data retention systems engineered for continuous write workloads, typically sustaining 180-540 terabytes per year per camera array at throughput rates exceeding 800 Mbps for 4K streams. These systems serve law enforcement, critical infrastructure operators, and commercial entities requiring forensic-grade chain-of-custody for video evidence. HDD configurations still dominate total petabytes shipped across the region, though SSD segments command premium margin pools in edge-analytics deployments where millisecond retrieval determines operational value. Cloud Solutions within the Technology dimension are expanding fastest as hybrid architectures allow tiered retention across on-premises buffers and regional hyperscale facilities.
China's MIIT enforces data localization through GB standards that mandate domestic storage nodes for government and critical infrastructure video, effectively conditioning market access for foreign vendors. India's RBI and TRAI frameworks impose retention mandates and cybersecurity audit requirements that directly expand storage capacity planning for financial institutions. Australia's TGA and state-level police certification standards create procurement specifications that favor vendors demonstrating tamper-evident storage architectures. Stakeholders must weigh sovereign data requirements against total cost of ownership when architecting multi-country surveillance infrastructure.
Market Dynamics
Smart city mandates across Southeast Asian metros are compressing procurement cycles for petabyte-scale municipal video analytics, forcing storage vendors to re-architect supply chains for 180-540 terabyte annual write loads per camera array.
Growth Catalysts
- RBI retention mandates:India's banking regulator extends video retention periods for ATM and branch surveillance, directly expanding capacity planning for financial institutions across Mumbai, Delhi, and Bangalore clusters.
- GB standard localization:China's MIIT data localization requirements compel foreign vendors to establish domestic cloud infrastructure, creating captive demand for regionally compliant storage nodes.
- 4K stream throughput:Edge-analytics deployments requiring 800 Mbps sustained write speeds pull SSD density improvements into high-write surveillance environments where millisecond retrieval determines operational value.
Market Restraints
- Platter supply concentration:HDD manufacturing scale concentrates in Chinese and Thai facilities, exposing procurement timelines to regional logistics constraints and customs processing variability.
- Dual-carbon compliance costs:China's MEE enforcement of energy efficiency standards for data centers elevates power-density requirements, compressing total cost of ownership calculations for archival tier deployments.
- Flash cost volatility:NAND wafer pricing fluctuations transmit directly to edge-analytics SSD quotations, complicating multi-year municipal contract budgeting.
Strategic Opportunities
- Vietnam smart city buildout:Ho Chi Minh City and Hanoi metro authorities issue RFPs for integrated video analytics platforms with 90-day minimum retention, opening procurement channels for hybrid cloud-on-premises architectures.
- Australia TGA certification:Federal and state-level police tamper-evident storage standards create specification barriers that favor vendors demonstrating forensic-grade chain-of-custody capabilities.
- AI-video convergence:Real-time object recognition at the edge fuses GPU inference with high-IOPS storage, enabling new service tiers where retrieval latency binds directly to alert response times.
Industry Challenges
- Forensic chain-of-custody certification:Australia's state police jurisdictions maintain non-harmonized evidence-handling standards, forcing vendors to maintain multiple firmware and audit-log configurations.
- Hybrid architecture integration:Financial institutions in India and Singapore struggle to synchronize on-premises buffer tiers with hyperscale cloud retention, creating data consistency failures during failover events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Surveillance Storage Market |
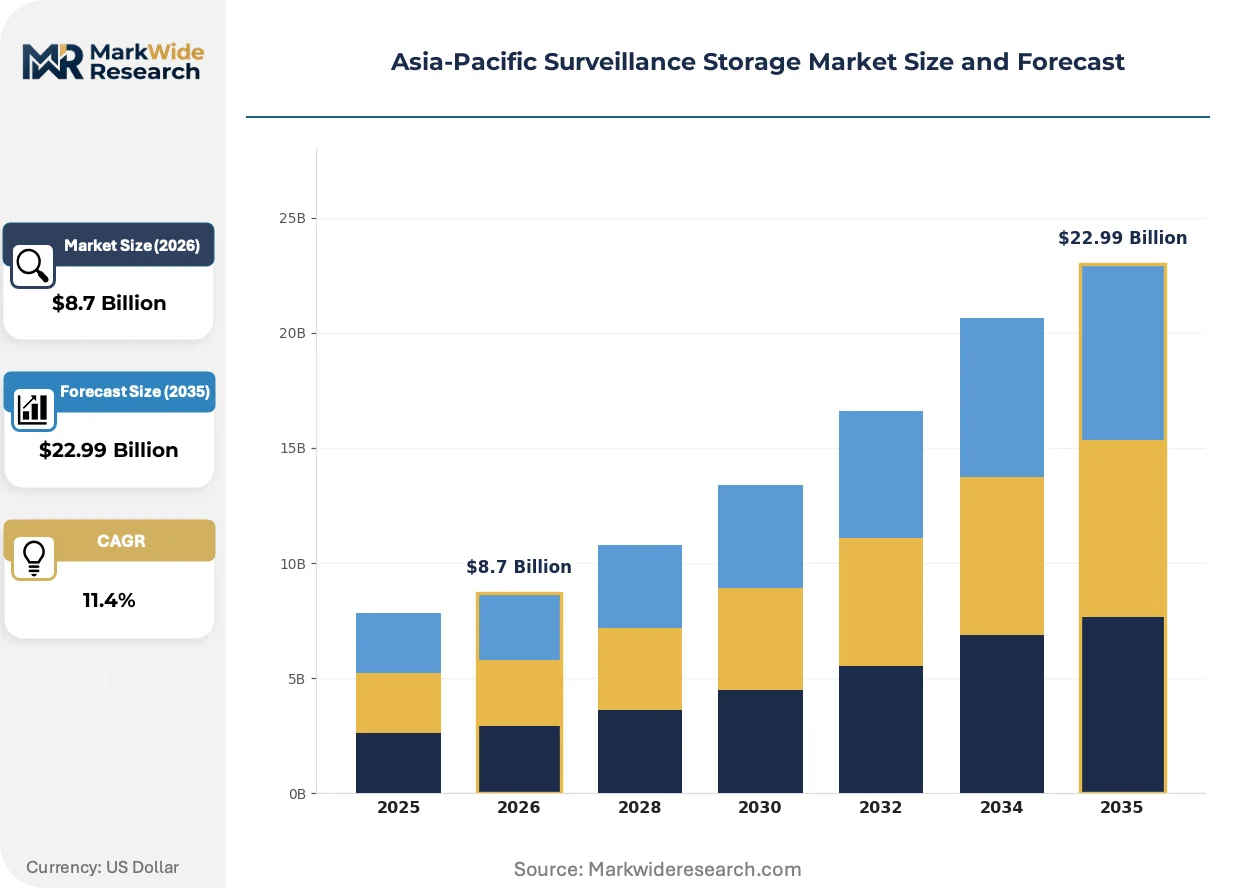
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NVR, DVR, SSD, HDD Technology: IP Cameras, Analog Cameras, Cloud Solutions, Hybrid Solutions End User: Retail, Transportation, Banking, Government Installation Type: On-premises, Cloud-based, Hybrid, Remote |
| Companies Covered | Hangzhou Hikvision Digital Technology Co. Ltd, Dahua Technology Co. Ltd, Huawei Technologies Co. Ltd, Seagate Technology LLC, Dell Technologies Inc, Hitachi Vantara, NetApp Inc, Western Digital, Quantum Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Surveillance Storage Market Trends and Innovations
Storage-class memory architectures and sovereign data frameworks are compressing the traditional separation between edge capture, on-premises buffering, and hyperscale archival, forcing vendors to re-bundle hardware, software, and compliance as unified offerings.
Computational storage drives with embedded inference engines are unifying video ingestion and real-time analytics within the same physical enclosure. Law enforcement agencies in South Korea and Singapore pilot these configurations for facial recognition at traffic intersections. This convergence is unifying what were previously separate server, storage, and analytics procurement decisions into single-vendor rack-scale contracts.
China's MIIT refinements to GB/T data security standards now mandate cryptographic module certification for all storage nodes processing government or critical infrastructure video. Foreign vendors must license domestic encryption cores or forfeit public sector eligibility. Financial institutions and transportation operators are responding by bifurcating procurement pools into certified-domestic and uncertified-international supply tracks.
Subscription-based capacity provisioning is displacing capital-heavy storage procurement in Australian and Japanese municipal deployments. City IT departments in Melbourne and Osaka now favor operational expenditure models where vendors retain hardware ownership and refresh obligations. This shift is most visible in mid-tier metros with constrained infrastructure budgets but escalating retention mandates.
Asia-Pacific Surveillance Storage Market Segmentation
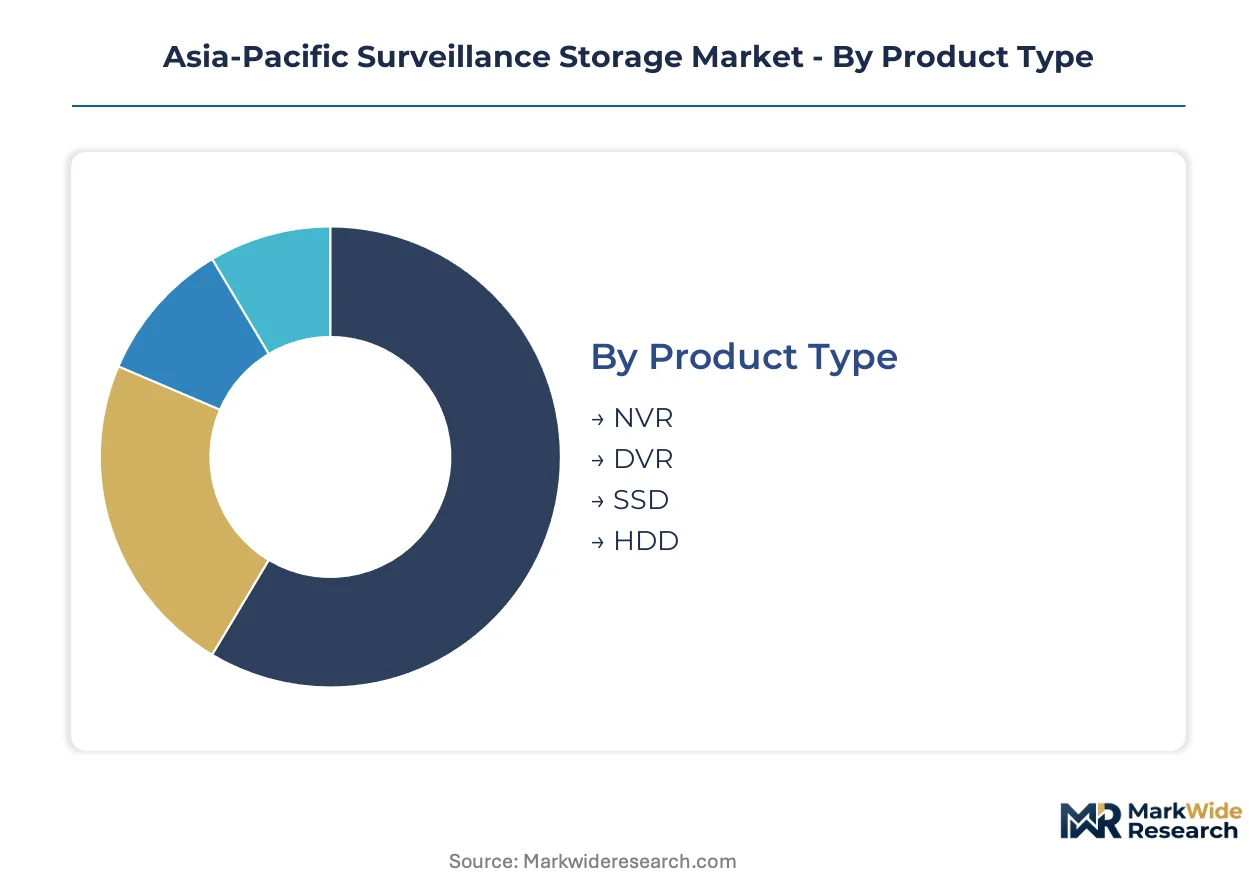
Segmentation in Asia-Pacific surveillance storage reflects divergent refresh cycles across infrastructure vintages. Legacy analog-to-IP transitions, HDD-to-SSD upgrades, and on-premises-to-cloud migrations each create distinct procurement rhythms that vendors must map against customer replacement timelines.
Product Type:
Upgrade cycles vary sharply by media technology, with mechanical and solid-state arrays following different depreciation schedules and performance obsolescence curves.
- HDD:Magnetic platter arrays sustain 180-540 terabyte annual write loads per camera cluster at the lowest cost-per-terabyte for archival tiers. Procurement concentrates in Chinese and Thai data centers where bulk retention mandates from MIIT and municipal governments prioritize petabyte-scale economics over retrieval speed.
- SSD:NAND-based storage delivers 800 Mbps sustained throughput for 4K streams with millisecond retrieval latency. Demand clusters in Singapore and South Korean edge-analytics deployments where real-time facial recognition at traffic intersections determines operational value.
- NVR:Network video recorders integrate encoding, storage, and network management in purpose-built appliances for mid-scale commercial installations.
- DVR:Digital video recorders serve legacy analog camera estates undergoing phased replacement across Southeast Asian retail and small-banking branches.
Volume placements concentrate in HDD configurations; the faster expansion belongs to SSD arrays.
Technology:
Cost tier differentiation separates premium IP and cloud architectures from economy analog and hybrid transitional systems.
- Cloud Solutions:Hyperscale retention nodes enable tiered storage across regional facilities with subscription-based capacity provisioning. Melbourne and Osaka municipal authorities favor this operational expenditure model for mid-tier deployments with constrained capital budgets.
- Hybrid Solutions:On-premises buffers synchronized with cloud archival balance latency-sensitive retrieval against long-term compliance retention. Financial institutions in Mumbai and Singapore deploy these configurations to meet RBI mandates while managing failover consistency.
- IP Cameras:Network-based capture systems generate compressed H.265 streams requiring compatible storage architectures.
- Analog Cameras:Coaxial-based video feeds persist in legacy infrastructure awaiting capital refresh cycles.
Hybrid architectures dominate current procurement volumes; cloud-native deployments are climbing the fastest.
End User:
Application-specific retention mandates and security certification requirements shape capacity planning across verticals.
- Banking:RBI-mandated video retention extensions for ATM and branch surveillance drive capacity expansion across Mumbai, Delhi, and Bangalore clusters. Cybersecurity audit requirements under TRAI frameworks impose additional encrypted storage specifications.
- Government:MIIT GB standards mandate domestic storage nodes and cryptographic module certification for public sector video, bifurcating procurement into certified-domestic and uncertified-international supply tracks.
- Transportation:Traffic management authorities in Ho Chi Minh City and Hanoi specify 90-day minimum retention for integrated video analytics platforms.
- Retail:Loss prevention and liability documentation drive distributed storage across franchise networks with varying centralization preferences.
Banking sector procurement represents the steepest expansion trajectory; government deployments command the largest absolute petabyte volumes.
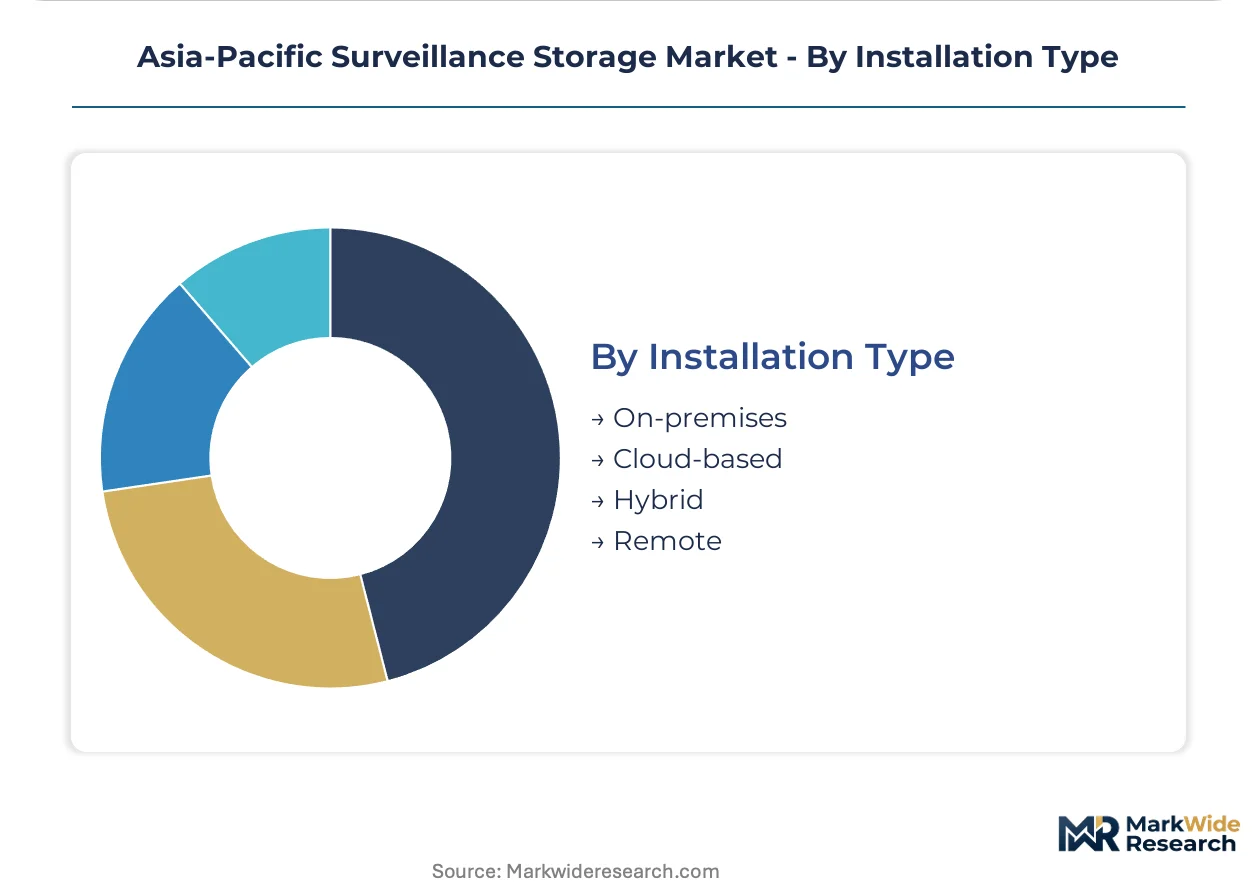
Installation Type:
Customer type and operational maturity determine architectural preferences between capital-intensive ownership and vendor-managed service models.
- On-premises:Customer-owned infrastructure maintains direct physical control over evidence chain-of-custody. Australian state police jurisdictions favor these configurations to satisfy TGA tamper-evident storage certification requirements.
- Hybrid:Tiered architectures buffer recent footage locally while archiving historical data to regional cloud nodes. This approach addresses India's RBI retention mandates while managing synchronization challenges during failover events.
- Cloud-based:Fully vendor-managed capacity eliminates refresh obligations for municipal IT departments with constrained infrastructure budgets.
- Remote:Distributed edge deployments serve geographically dispersed infrastructure with centralized management planes.
Hybrid installations hold the dominant share of new deployments; cloud-based configurations are gaining share fastest among budget-constrained metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across China's Yangtze River Delta and Pearl River Delta concentrate surveillance storage manufacturing and hyperscale deployment. These zones channel foreign direct investment toward domestic cloud infrastructure while MIIT localization mandates reshape vendor licensing requirements.
China
MIIT GB standards mandate cryptographic module certification for government and critical infrastructure video storage, bifurcating procurement into certified-domestic and uncertified-international supply tracks. Foreign vendors must license domestic encryption cores or forfeit public sector eligibility. Beijing-Tianjin-Hebei and Yangtze River Delta data centers absorb petabyte-scale HDD shipments for municipal video analytics.
India
RBI retention mandates extend video retention periods for ATM and branch surveillance, directly expanding capacity planning for financial institutions. TRAI cybersecurity audit requirements impose additional encrypted storage specifications on banking infrastructure. Mumbai, Delhi, and Bangalore clusters drive steepest procurement expansion across the region.
Australia
TGA and state-level police certification standards create procurement specifications favoring vendors demonstrating tamper-evident storage architectures. Victorian and New South Wales jurisdictions maintain non-harmonized evidence-handling standards, forcing firmware configuration multiplicity. Melbourne municipal authorities now favor subscription-based capacity provisioning over capital-heavy procurement.
South Korea
Real-time object recognition at traffic intersections fuses GPU inference with high-IOPS storage, enabling service tiers where retrieval latency binds directly to alert response times. Seoul Capital Area transportation authorities pilot computational storage drives with embedded inference engines. National police procurement favors single-vendor rack-scale contracts unifying server, storage, and analytics decisions.
Vietnam
Ho Chi Minh City and Hanoi metro authorities issue RFPs for integrated video analytics platforms with 90-day minimum retention requirements. Smart city buildouts compress procurement cycles for hybrid cloud-on-premises architectures. Municipal IT departments with constrained infrastructure budgets escalate storage procurement through operational expenditure models.
Asia-Pacific Surveillance Storage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers commanding government security networks while component suppliers dominate bulk archival tiers. The vendor base organizes around three strategic archetypes: platter-scale manufacturers sustaining cost-per-terabyte economics, integrated storage-networking bundlers serving sovereign compliance requirements, and cloud-native operators capturing subscription-based municipal procurement. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with localization mandates forcing joint venture formations and domestic encryption licensing arrangements.
Within the integrated solution tier, Huawei Technologies Co. Ltd and Hangzhou Hikvision Digital Technology Co. Ltd occupy positions aligned with government security network requirements. Seagate Technology LLC exemplifies the platter-scale archetype serving Chinese data center bulk retention demand. Dell Technologies Inc represents multinational infrastructure providers navigating bifurcated procurement pools between certified-domestic and uncertified-international supply tracks.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Dahua Technology Co. Ltd |
| Huawei Technologies Co. Ltd |
| Seagate Technology LLC |
| Dell Technologies Inc |
| Hitachi Vantara |
| NetApp Inc |
| Western Digital |
| Quantum Corporation |
| Others |
Pricing and Supply Chain Analysis
NAND wafer spot indices transmit volatility directly through SSD bill-of-materials into edge-analytics quotations, compressing municipal procurement timelines and forcing tiered contract structures that buffer buyers against flash cost swings.
Pricing Analysis
Short lead-time premiums of 15-25% apply to SSD arrays for South Korean traffic management deployments, while spot inventory of HDD platters from Thai facilities trades at discounts to contracted volumes. Three-tier pricing structure across certified-domestic, compliant-international, and uncertified-economy levels separates MIIT-authorized storage nodes from gray-market alternatives. Cost compression in archival HDD tiers is intensifying because Chinese data centers are consolidating petabyte orders under single-vendor frameworks. Banking procurement teams in Mumbai demonstrate highest price sensitivity due to RBI-mandated retention expansions, while Australian state police jurisdictions show lowest sensitivity where TGA certification requirements dominate vendor selection.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Beijing-Tianjin-Hebei data centers, while systems integrators serve mid-tier municipal deployments across Vietnam and Indonesia. Magnetic platter manufacturing concentrates in Chinese and Thai facilities; NAND fabrication anchors in South Korea and Japan. Raw material dependencies span rare earth substrates for platter coatings, DRAM modules for NVR buffer tiers, and controller ASICs for SSD firmware. Single-source vulnerability in Chinese encryption core licensing creates procurement bifurcation under MIIT GB standards. Distribution runs through authorized domestic partners for government-certified tiers and cross-border traders for international commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MIIT cryptographic module mandates construct a cost-of-compliance moat that rewards vendors with domestic encryption licensing while excluding foreign competitors from public sector procurement pools.
For Market Incumbents: Deploy domestic joint venture formations to secure GB/T certification eligibility for government security network contracts. Seagate Technology LLC and Dell Technologies Inc must license Chinese encryption cores or forfeit Beijing-Tianjin-Hebei municipal procurement channels. Capacity addition in Yangtze River Delta hyperscale facilities defends position against Huawei Technologies Co. Ltd integrated bundles. Firmware audit-log customization for Australian state police jurisdictions protects margin pools in forensic-grade segments against Hangzhou Hikvision Digital Technology Co. Ltd regional bundling. For New Entrants and Emerging Players: The 40-60% price-point gap between premium SSD edge-analytics tiers and economy HDD archival configurations opens white-space targeting for hybrid cloud-on-premises architectures in Vietnamese municipal deployments. Ho Chi Minh City and Hanoi smart city RFPs represent the most penetrable geography given 90-day retention mandates and constrained IT budgets. Subscription-based capacity provisioning models bypass capital-intensive procurement barriers for mid-tier metros. Computational storage drives with embedded inference engines offer differentiated entry into South Korean traffic management pilot programs. For Investors and Strategic Acquirers: The window for entry favors domestic-encryption-certified storage vendors with established MIIT compliance pathways. Long-term viability centers on sovereign data framework convergence across Asia-Pacific jurisdictions, with certified-domestic supply tracks capturing structural margin premiums. Acquisition target archetype: mid-scale hybrid cloud operators with existing municipal relationships in Australia and Japan. NAND wafer pricing stabilization signals demand normalization for edge-analytics SSD segments.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Encryption Core Licensing | MIIT GB/T compliance unlocks public sector procurement pools across Chinese government security networks. |
| Hybrid Cloud Architecture Deployment | Melbourne and Osaka municipal authorities favor operational expenditure models for retention mandates. |
| Computational Storage Drive Launch | Seoul Capital Area transportation pilots unify GPU inference with high-IOPS retrieval latency. |
| Forensic Chain-of-Custody Certification | TGA tamper-evident standards create specification barriers favoring certified vendors in Australian jurisdictions. |
| Platter Manufacturing Scale Expansion | Chinese and Thai facility output sustains cost-per-terabyte economics for petabyte-scale archival tiers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with data center procurement directors, municipal IT managers, storage vendor sales executives, and systems integration specialists. MIIT GB standard documentation, RBI circulars on video retention, and TGA certification requirements provided regulatory boundary conditions. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level projections.
Granularity-level modeling distinguished HDD archival tiers from SSD edge-analytics segments across the analysis window, with separate treatment of on-premises, hybrid, and cloud-native deployment architectures. Technology dimensions captured mechanical versus solid-state media transitions, while end-user segmentation isolated banking, government, transportation, and retail verticals. CAGRs derived from replacement cycle analysis, retention mandate expansion timelines, and smart city procurement pipeline visibility. NAND wafer pricing volatility and dual-carbon compliance cost trajectories fed sensitivity bands around base-case capacity forecasts.
Inputs from customs records and hyperscaler capex disclosures were available through the study window; gaps in real-time municipal procurement pipeline data introduce uncertainty bands around Vietnam and Indonesia smart city buildout timing. Forecasts reflect assumptions regarding MIIT enforcement consistency, RBI retention mandate adherence, and flash memory cost normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
US Video Surveillance Market