
 North America Surveillance IP Camera Market | 2026-2036
North America Surveillance IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surveillance IP Camera Market Insights
Multi-source component procurement is recalibrating supply chain economics for North American camera OEMs. Bosch Security Systems GmbH leverages in-house sensor fabrication to control image-processing quality from wafer to firmware. Motorola Solutions Inc anchors its position through deep integration with public-safety command platforms. Hikvision Digital Technology Co Ltd competes on manufacturing scale, though tariff exposure complicates its channel positioning in the region.
Surveillance IP cameras are network-connected digital imaging devices that encode video streams via H.265 or AV1 compression for transmission over Ethernet or Wi-Fi infrastructure, with power typically delivered through PoE+ to simplify cabling in ceiling and pole-mount installations. Their primary purpose is real-time situational monitoring, forensic evidence capture, and automated alert generation through onboard or cloud-based analytics. Dome form factors dominate commercial installations where vandal resistance and discreet positioning matter, while PTZ units command premium pricing in transportation and critical infrastructure for their operator-controllable coverage flexibility. Digital technology has overtaken analog and hybrid systems across new deployments, though wireless segments are gaining traction in retrofit residential and remote industrial settings where cabling proves cost-prohibitive.
FCC certification requirements govern radio-frequency emissions for wireless camera models, while NHTSA and TSA procurement standards shape product specifications for transportation-sector deployments. The Department of Homeland Security SAFETY Act influences liability frameworks and vendor qualification for government installations. State-level biometric privacy laws in Illinois, Texas, and Washington are forcing manufacturers to embed explicit consent-management features and facial-recognition disable switches. Stakeholders must weigh cloud-versus-edge analytics architectures against evolving data-localization mandates and municipal procurement transparency rules.
Market Dynamics
Edge AI inference engines are compressing latency windows for real-time threat detection, forcing camera OEMs to redesign thermal envelopes and power architectures around on-chip neural processing units rather than centralized server farms.
Growth Catalysts
- Biometric Privacy Mandates:Illinois BIPA and Texas CUBI statutes compel manufacturers to embed consent-management firmware and facial-recognition kill switches, creating upgrade cycles for compliant hardware.
- Smart City Infrastructure:Municipalities across Texas, California, and Ontario are bundling video analytics into transportation and critical infrastructure budgets, accelerating PoE+ network rollouts.
- Cloud-Native Analytics:Hybrid edge-cloud architectures are replacing DVR-centric systems, enabling subscription-based video management software revenue streams for integrators.
Market Restraints
- Image Sensor Supply Concentration:Sony and ON Semiconductor dominate CMOS wafer supply, exposing North American OEMs to allocation volatility and 26-week lead times during demand spikes.
- Section 301 Tariff Exposure:Finished camera assemblies and lens modules face residual duties from US-China trade actions, compressing gross margins for cost-optimized product lines.
- Legacy Analog Infrastructure:Hybrid coaxial cabling in aging commercial and government facilities slows IP migration, extending replacement cycles beyond typical technology refresh timelines.
Strategic Opportunities
- Remote Industrial Monitoring:Oil and gas facilities in Alberta and Permian Basin regions require explosion-rated wireless cameras where trenching fiber proves cost-prohibitive, opening retrofit demand.
- Outcome-Based Municipal Contracts:Performance-linked service agreements tie vendor payments to crime reduction metrics or traffic flow improvements, shifting procurement from capital expenditure to operational expenditure models.
- 5G Private Network Integration:Bandwidth-intensive 4K and multispectral streams are migrating to campus-scale 5G deployments, enabling camera density unconstrained by Ethernet cabling topology.
Industry Challenges
- Embedded Firmware Security:CVE disclosure rates for camera operating systems are accelerating, forcing OEMs to maintain decade-long patch lifecycles against state-sponsored intrusion attempts.
- Interoperability Certification Burden:ONVIF Profile T compliance, FCC Part 15 emissions testing, and DHS SAFETY Act qualification create multi-year approval timelines for government channel access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surveillance IP Camera Market |
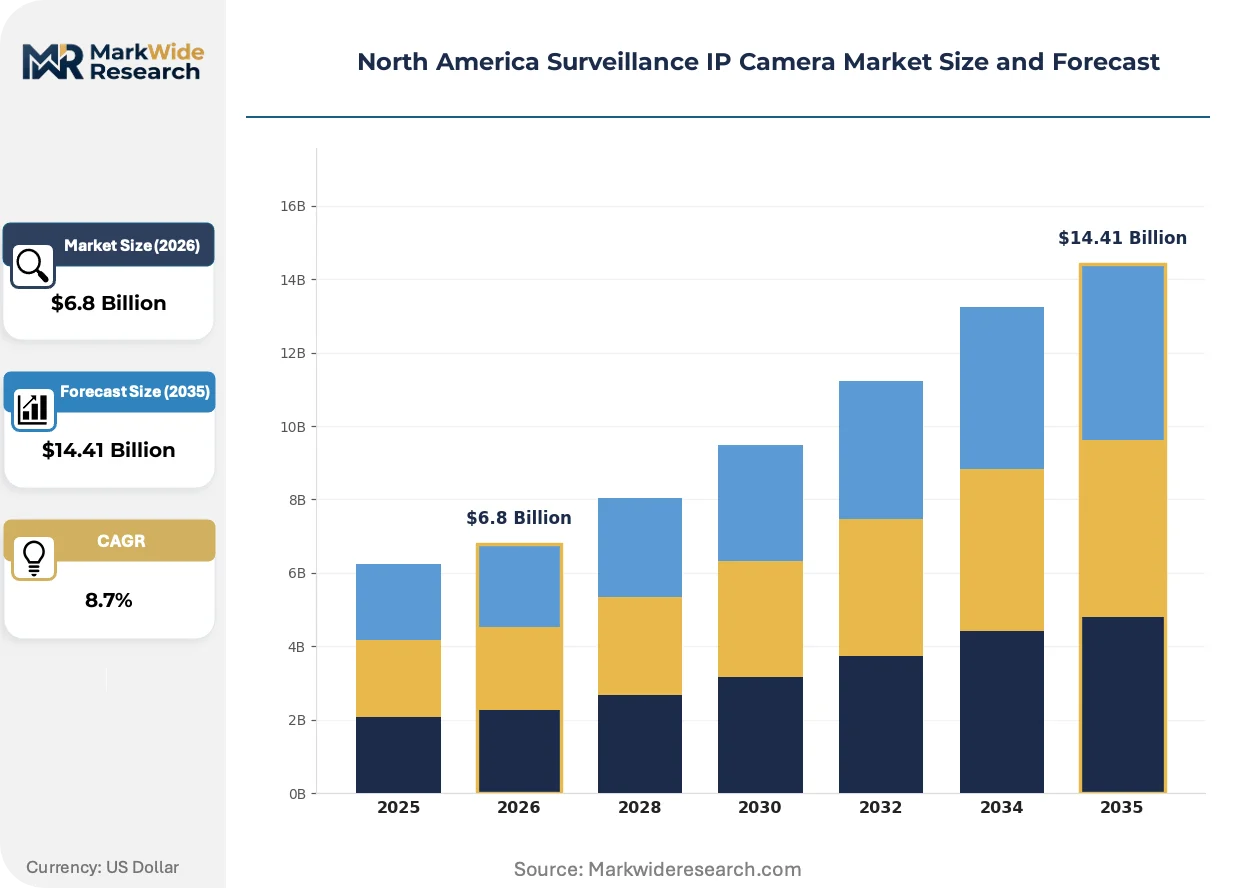
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Dome, Bullet, PTZ, Box Technology: Analog, Digital, Hybrid, Wireless Application: Retail, Transportation, Banking, Healthcare End User: Residential, Commercial, Government, Industrial |
| Companies Covered | Dahua Technology Co Ltd, Cisco Systems Inc, Motorola Solutions Inc, Bosch Security Systems GmbH, Panasonic Corporation, Honeywell International Inc, Johnson Controls International PLC, Sony Corporation, Hikvision Digital Technology Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surveillance IP Camera Market Trends and Innovations
Computational imaging and sovereign data requirements are converging to redefine hardware specifications and deployment architectures across municipal, commercial, and critical infrastructure verticals.
Multispectral sensor fusion is integrating thermal, visible-light, and near-infrared channels into unified video streams for perimeter detection in zero-illumination environments. Border protection agencies and nuclear facilities are piloting these units for automated intrusion classification. The technology is integrating spectral analytics directly into edge processors, eliminating backhaul bandwidth constraints for remote sites.
State-level biometric privacy frameworks in Illinois, Texas, and Washington are mandating audit trails for facial-recognition activation and data retention limits. Camera firmware must now support jurisdictional policy enforcement through geofenced configuration profiles. Manufacturers serving multi-state integrators face SKU proliferation to maintain compliance across incompatible statutory regimes.
Municipal procurement departments are consolidating vendor relationships through master service agreements that bundle hardware, installation, and analytics subscriptions into unified performance contracts. Value-added resellers and systems integrators are displacing traditional distribution channels for large-scale deployments. California transit authorities and Ontario municipal governments have pioneered these consolidated sourcing vehicles, compressing supplier rosters to pre-qualified technology partners.
North America Surveillance IP Camera Market Segmentation
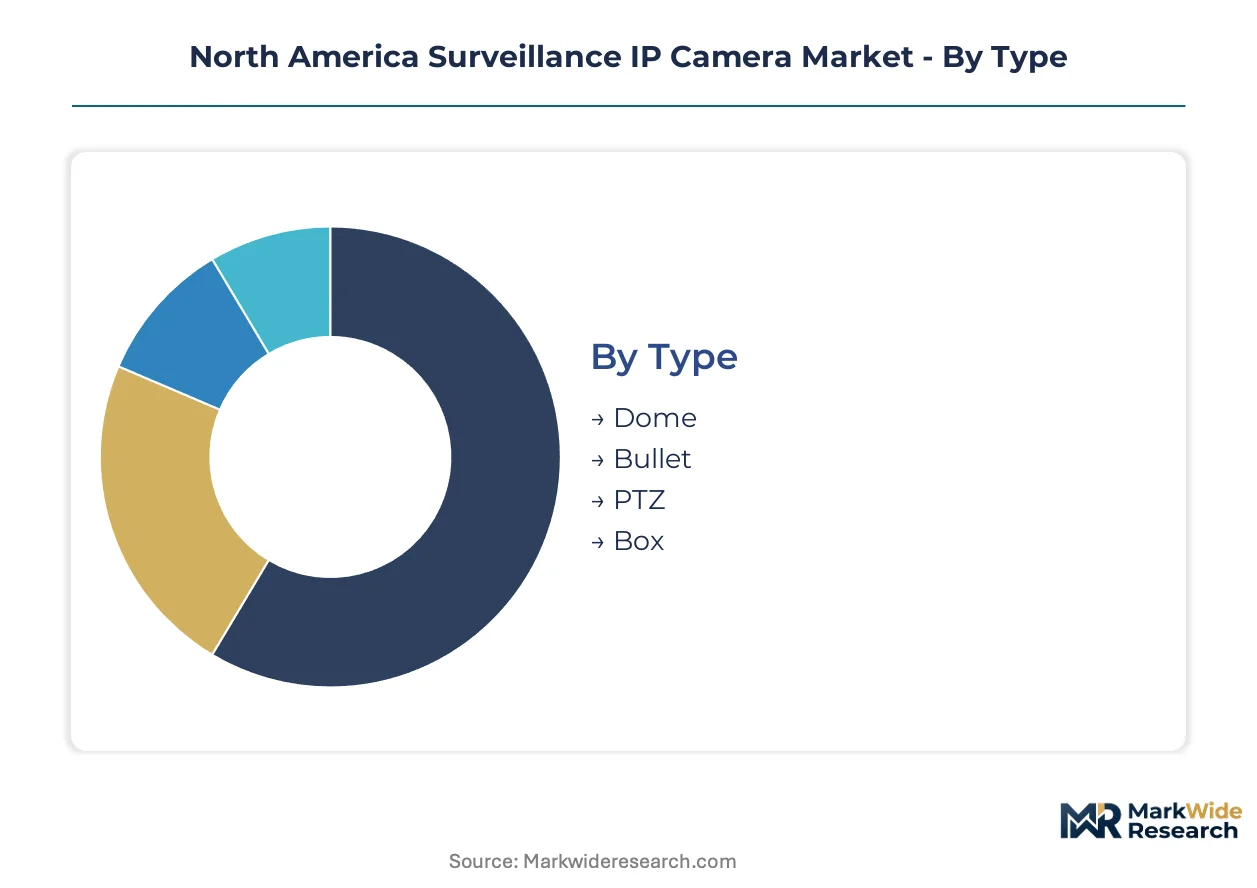
Surveillance IP camera procurement decisions across North America diverge sharply by deployment environment, with form factor selection driven by vandalism exposure, cabling constraints, and analytics integration requirements. Understanding these segment boundaries clarifies where manufacturers must differentiate on hardware durability versus software capabilities.
Type:
Physical mounting constraints and operator control requirements dominate buyer evaluation for camera housings.
- Dome:Hemispherical enclosures with tamper-resistant polycarbonate domes suit ceiling-mounted commercial installations where discreet positioning matters. Retail chains across California and Texas specify these for indoor loss-prevention deployments, prioritizing aesthetic integration over maximum resolution.
- PTZ:Pan-tilt-zoom mechanisms enable operator-controllable coverage of wide perimeters through motorized lens positioning. Transportation authorities in Ontario and critical infrastructure operators in the Permian Basin pay premiums for these units, driven by the need to track moving targets across expansive facilities without camera density multiplication.
- Bullet:Cylindrical weatherproof housings mount externally on walls and poles for directional surveillance. These units dominate parking structure and perimeter applications where infrared illumination range determines nighttime effectiveness.
- Box:Modular designs with interchangeable C/CS-mount lenses serve specialized applications requiring telephoto or wide-angle optics. Industrial facilities and casino surveillance rooms favor these for custom focal length matching.
Dome cameras lead on scale across commercial retrofit projects; PTZ units lead on momentum within smart city transportation budgets.
Technology:
Migration economics and infrastructure legacy determine whether buyers adopt full digital architectures or bridge transitional solutions.
- Digital:Native IP cameras encode H.265 or AV1 streams for direct network transmission without analog conversion. Municipalities in Texas and California mandate these for new construction, eliminating coaxial cabling costs and enabling cloud-native video management platforms.
- Wireless:Wi-Fi or cellular-connected units eliminate trenching requirements in retrofit environments. Oil and gas operators in Alberta and remote industrial sites across the US Southwest deploy these where fiber installation proves cost-prohibitive, though FCC Part 15 certification adds procurement lead time.
- Analog:Coaxial-based systems persist in aging government facilities and budget-constrained school districts where full infrastructure replacement remains unfunded. Replacement cycles here extend well beyond typical technology refresh timelines.
- Hybrid:Dual-mode cameras support both analog and IP output to ease transition paths. These units appeal to multi-site retailers phasing upgrades location-by-location without simultaneous network overhauls.
Digital technology commands the dominant installed base; wireless architectures are climbing the fastest as 5G private networks mature.
Application:
Regulatory exposure and incident liability shape vertical-specific feature requirements and procurement approval processes.
- Transportation:NHTSA and TSA procurement standards govern camera specifications for transit authorities and aviation facilities. Edge AI inference for real-time crowd density and abandoned-object detection is becoming mandatory in these deployments.
- Banking:Federal regulatory examination priorities and insurance underwriter requirements drive demand for forensic-grade image capture with synchronized audio. Facial recognition disable switches are proliferating here in response to Illinois BIPA compliance pressure.
- Retail:Loss-prevention departments prioritize integration with point-of-sale systems and heat-mapping analytics. Cloud-native architectures are displacing on-premise DVRs as chains consolidate security operations centers.
- Healthcare:HIPAA constraints and patient privacy protocols limit camera placement and retention policies. These installations emphasize corridor coverage over patient room monitoring, with strict access logging for forensic retrieval.
Transportation applications lead on scale through federal infrastructure spending; banking verticals lead on momentum from biometric privacy compliance cycles.
End User:
Budget authority and procurement sophistication separate consumer-grade from enterprise-grade buying patterns.
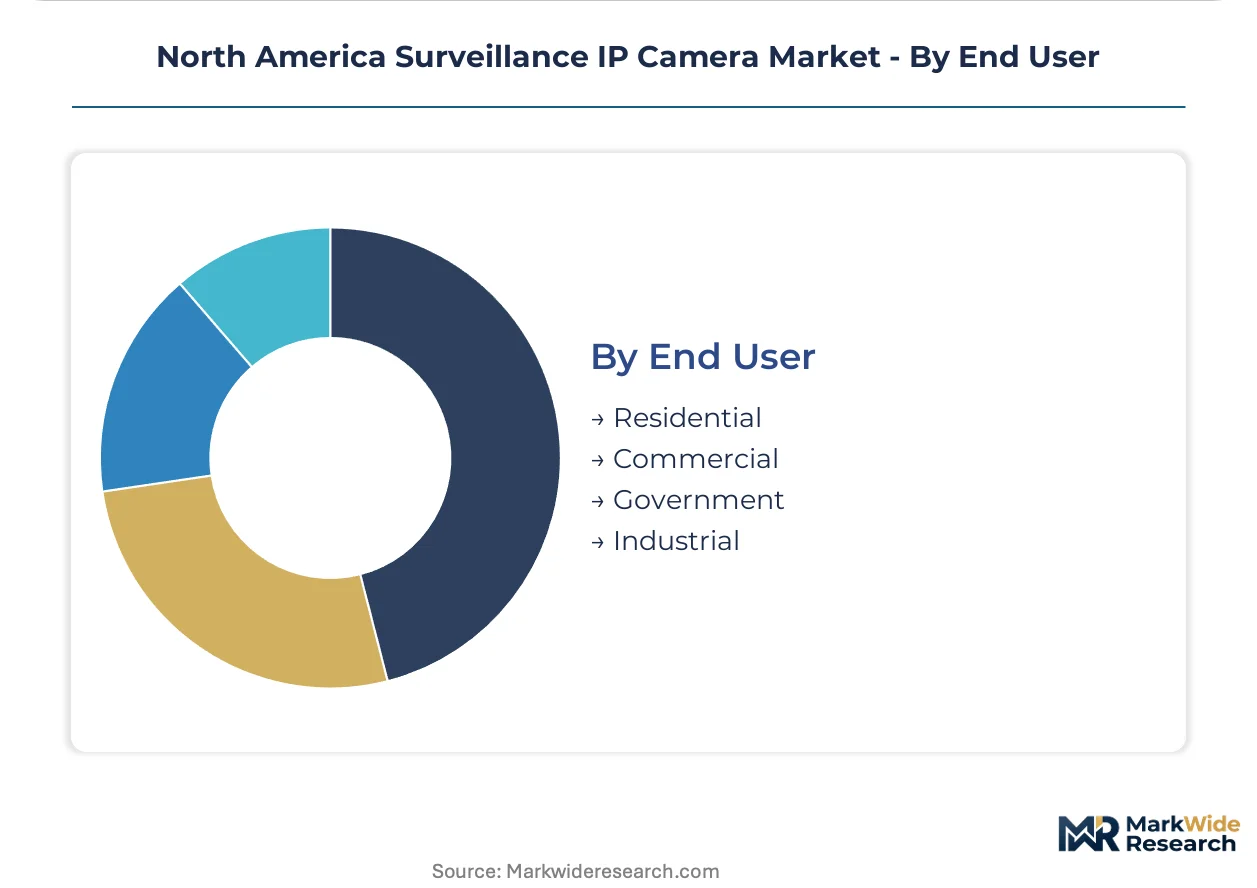
- Government:DHS SAFETY Act qualification and state-level procurement transparency rules create multi-year vendor approval timelines. These buyers prioritize cybersecurity certifications and domestic assembly content for critical infrastructure deployments.
- Commercial:Property management firms and corporate security departments balance upfront hardware costs against subscription-based video analytics recurring revenue. Master service agreements are consolidating vendor relationships across multi-site portfolios.
- Industrial:Explosion-rated housings and extreme temperature specifications differentiate this segment. Alberta oil sands and Texas petrochemical facilities require IECEx-certified equipment with 10-year operational lifespans.
- Residential:DIY installation and smartphone app integration dominate consumer preferences. These buyers drive wireless segment growth but exert severe price pressure on hardware margins.
Commercial end users lead on scale across North America; government procurement leads on momentum through smart city infrastructure acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration across North America follows regulatory-arbitrage logic, with assembly gravitating toward jurisdictions offering streamlined FCC certification pathways and favorable tariff treatment for finished electronics. Mexico's manufacturing zones attract OEMs seeking proximity to US demand without Section 301 duty exposure, while Canadian facilities leverage CUSMA rules of origin for cross-border supply security.
United States
Texas and California municipal governments are accelerating smart city video infrastructure procurement through federal infrastructure grants. FCC Part 15 certification requirements govern wireless camera deployments, creating compliance lead times that favor established domestic integrators. The Permian Basin energy corridor demands explosion-rated cameras for petrochemical facility monitoring, driving specialized hardware specifications.
Canada
Ontario transit authorities are bundling IP camera networks into provincial transportation modernization budgets. Health Canada and PMRA procurement standards influence specifications for federal facility security installations. The Alberta oil sands region requires IECEx-certified equipment with extreme temperature tolerance, concentrating demand among industrial-grade suppliers.
Mexico
Manufacturing zones in Nuevo León and Baja California are attracting camera assembly operations seeking CUSMA tariff advantages and proximity to US distribution channels. Mexico's federal telecommunications regulator imposes equipment certification requirements that parallel FCC frameworks, reducing technical barriers for cross-border product flows. Mexico City metro authorities are piloting edge-AI camera networks for crowd management.
North America Surveillance IP Camera Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native analytics partnerships and edge-AI firmware differentiation. The vendor base spans three structural tiers: diversified technology conglomerates with security divisions, pure-play surveillance specialists with manufacturing scale, and software-centric challengers betting on subscription revenue models. Strategic moves concentrate on vertical integration into sensor supply and master service agreement consolidation with municipal procurement departments.
Within the diversified technology tier, Cisco Systems Inc and Honeywell International Inc exemplify enterprise IT incumbents leveraging existing network infrastructure relationships to displace standalone camera vendors. Motorola Solutions Inc occupies a position bridging public-safety command platforms with video hardware, representing the deep-integration archetype. Bosch Security Systems GmbH anchors the European-origin specialist segment, while Hikvision Digital Technology Co Ltd and Dahua Technology Co Ltd exemplify scale-driven manufacturing from Chinese origins, though tariff exposure complicates their North American channel positioning.
| Leading Market Players |
|---|
| Dahua Technology Co Ltd |
| Cisco Systems Inc |
| Motorola Solutions Inc |
| Bosch Security Systems GmbH |
| Panasonic Corporation |
| Honeywell International Inc |
| Johnson Controls International PLC |
| Sony Corporation |
| Hikvision Digital Technology Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Federal smart city infrastructure grants across Texas and California are mandating edge-AI capable cameras with embedded biometric privacy controls, forcing OEMs to absorb NPU chip premiums and multi-SKU firmware development costs that compress margins on standard-tier units.
Pricing Analysis
Input-cost pass-through from Sony and ON Semiconductor CMOS allocation volatility feeds directly into camera bill-of-materials, with 26-week lead time spikes forcing tiered pricing adjustments across premium, standard, and economy levels. Price differentiation hinges on ONVIF Profile T certification grade and DHS SAFETY Act qualification status, with government-channel hardware commanding substantial premiums over commercial equivalents. Cost compression in the residential wireless segment intensifies because DIY buyers prioritize smartphone app integration over image-processing specifications. Commercial property management firms exhibit lowest price sensitivity due to master service agreement bundling that obscures per-unit hardware costs within long-term analytics subscriptions.
Supply Chain Analysis
Dual-sourcing requirements from Ontario transit authorities and Texas municipal procurement departments mandate qualified secondary suppliers for image sensors and lens modules, preventing single-source lock-in despite Sony's market dominance. Manufacturing concentrates in Mexico's Nuevo León and Baja California zones, China's Yangtze River Delta, and Taiwan's semiconductor foundries. Raw material dependencies span silicon wafers, optical glass, and rare-earth magnet components for PTZ motors. Tariff exposure from residual Section 301 duties on finished assemblies creates structural risk for cost-optimized product lines. Distribution runs through value-added resellers and systems integrators who displace traditional wholesale channels for large-scale government and commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software-defined camera architectures that shift value capture from commoditized hardware to recurring analytics subscriptions, offsetting sensor cost inflation through SaaS-tiered pricing power.
For Market Incumbents: Deepen upstream control over edge-AI processor supply through exclusive foundry partnerships or captive semiconductor design capabilities, insulating against allocation volatility that threatens fulfillment commitments to Texas and California municipal buyers. Fortify channel position by acquiring regional systems integrators with DHS SAFETY Act qualification and established master service agreement relationships, neutralizing emerging software-centric challengers before they achieve critical mass in transportation verticals. For New Entrants and Emerging Players: Launch via outcome-based municipal contracts in mid-tier Ontario cities and Alberta industrial corridors where incumbent coverage remains thin and performance-linked pricing models face less procurement scrutiny. Target explosion-rated wireless camera demand from Permian Basin oil operators and Alberta oil sands facilities, where trenching costs create natural white-space for cellular-connected retrofit solutions absent from established vendor portfolios. For Investors and Strategic Acquirers: Asymmetric upside sits with edge-AI firmware specialists possessing ONVIF Profile T certification and existing integration with public-safety command platforms, as these capabilities command scarcity premiums in government channel access. Five-to-ten-year viability favors vendors with demonstrated patch lifecycle management against accelerating CVE disclosure rates. Watch for inflection signals in 5G private network deployment velocity across campus-scale industrial facilities, which would unlock bandwidth-intensive multispectral camera density unconstrained by Ethernet topology.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Firmware Development | On-chip neural processing units differentiate real-time threat detection latency against centralized server architectures. |
| Master Service Agreement Consolidation | California transit authorities and Ontario municipalities compress supplier rosters to pre-qualified technology partners. |
| Biometric Privacy Compliance Integration | Illinois BIPA and Texas CUBI mandates force consent-management firmware and facial-recognition kill switches as standard features. |
| 5G Private Network Certification | Campus-scale deployments enable camera density unconstrained by PoE+ cabling topology in industrial settings. |
| Explosion-Rated Product Line Expansion | Alberta oil sands and Permian Basin petrochemical facilities require IECEx-certified equipment with extreme temperature tolerance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal procurement officers, security systems integrators, OEM product managers, and edge-AI chipset engineers alongside secondary validation through FCC equipment authorization databases, DHS SAFETY Act qualified vendor listings, and municipal budget disclosure filings. Bottom-up camera shipment estimates triangulated against top-down infrastructure spending allocations from federal grant programs.
Comparable-period anchoring established baseline reference points from historical smart city procurement cycles and analog-to-IP migration trajectories, with projection horizons extending across the analysis window. Segmentation dimensions modeled include form factor type, technology architecture, vertical application, and end-user procurement sophistication, with CAGRs derived from unit economics of edge-AI chip adoption curves and municipal subscription revenue maturation. Forecast inputs incorporated PoE+ network rollout velocity and 5G private network deployment pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Section 301 tariff escalation or semiconductor export restriction scenarios. Deviation in federal infrastructure grant allocation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
North America Video Surveillance Systems Market