
 ASEAN Inland Waterway Freight Transport Market | 2026-2036
ASEAN Inland Waterway Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Inland Waterway Freight Transport Market Insights
The ASEAN Green Freight Programme is realigning vessel procurement criteria across Southeast Asian river networks. PT Pelindo leverages its intermodal port network to dominate transhipment between Java's northern coast and interior waterways. Vinafreight sustains competitive positioning through specialized liquid cargo handling on the Mekong River system.
ASEAN inland waterway freight transport encompasses the movement of goods via navigable rivers, canals, and delta systems using powered vessels with draft capacities typically ranging from 1.5 to 4.5 meters, serving as a cost-competitive alternative to road and rail for bulk and containerized cargo over distances of 50 to 800 kilometers. Barge operations command the largest volume share given their flexibility across shallow-draft routes, while container ships represent the fastest-expanding transport type as shippers convert road freight to river corridors for cost and emissions savings. Bulk commodities generate the most tonnage moved, though hazardous materials transport commands premium pricing due to specialized certification requirements and limited carrier availability.
Indonesia's Ministry of Transportation and Vietnam's Maritime Administration enforce vessel safety and environmental compliance standards that dictate fleet modernization timelines and market access eligibility. Thailand's Department of Marine Administration implements cargo handling protocols that influence terminal infrastructure investment along the Chao Phraya basin. Stakeholders must monitor regulatory harmonization progress across ASEAN member states, as divergent certification requirements between national waterway authorities continue to fragment cross-border operational efficiency and capital deployment decisions.
Market Dynamics
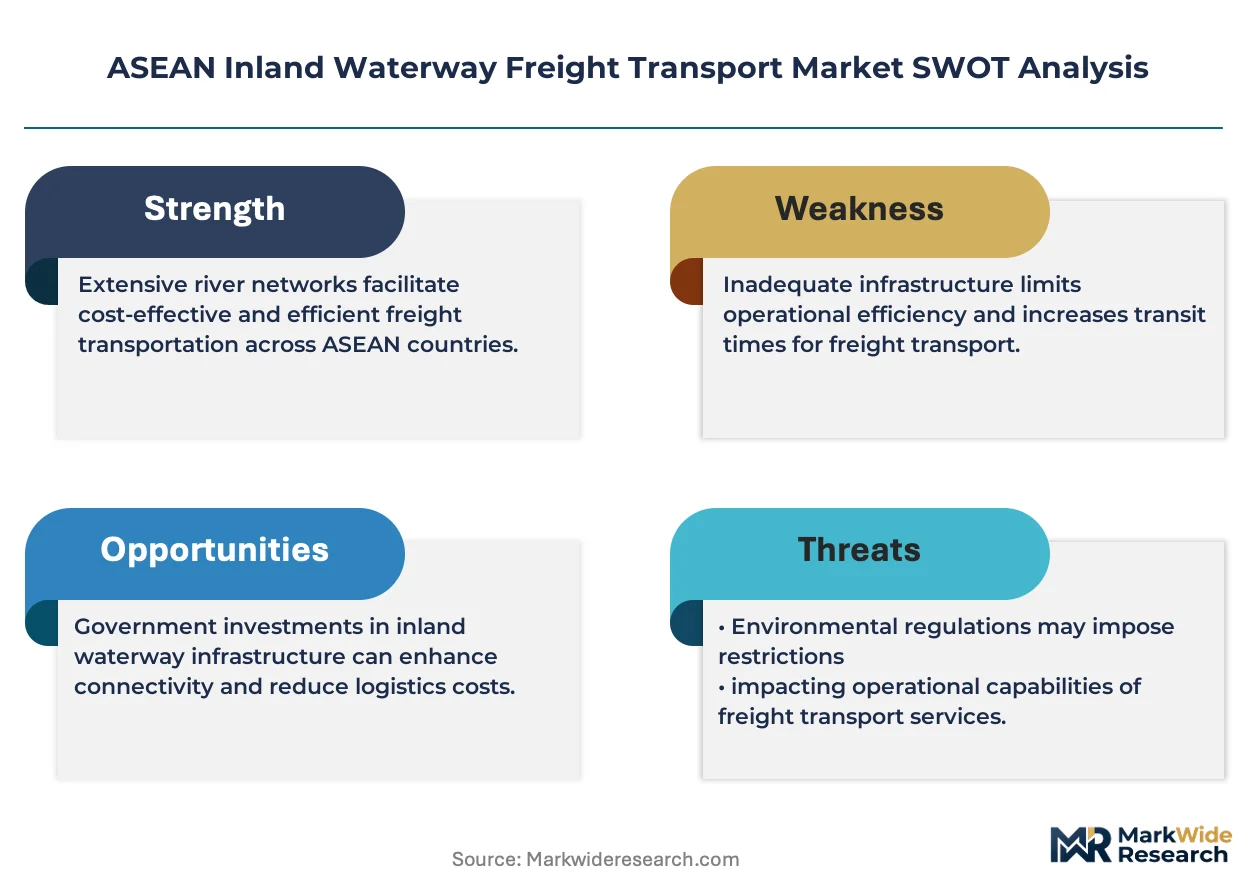
The ASEAN Inland Waterway Freight Transport Market faces intensifying pressure from the ASEAN Green Freight Programme, which is recalibrating vessel procurement standards and accelerating fleet obsolescence timelines across Southeast Asian river corridors. This regulatory pivot is compressing investment cycles and forcing operators toward cleaner propulsion technologies.
Growth Catalysts
- Maritime Axis Policy:Indonesia's maritime axis policy is channeling state capital into port-to-river connectivity upgrades, unlocking barge traffic between Java's northern terminals and interior manufacturing zones.
- Containerized Agricultural Exports:Rising Mekong Delta agricultural exports are converting road freight to river corridors, with shippers prioritizing cost and emissions savings on Vietnam-Cambodia routes.
- Chao Phraya Manufacturing Hinterland:Bangkok's industrial belt is generating concentrated demand for bulk and containerized cargo movement along Thailand's primary river artery.
Market Restraints
- Divergent Certification Requirements:Indonesia's Ministry of Transportation and Vietnam's Maritime Administration maintain incompatible vessel safety standards, fragmenting cross-border operational efficiency.
- Draft Limitations:Shallow-draft constraints on secondary Mekong tributaries restrict vessel capacity to 1.5-2.5 meters, limiting economies of scale on feeder routes.
- Road Freight Substitution:Flexible trucking networks continue capturing time-sensitive cargo despite higher per-ton-kilometer costs on shorter corridors.
Strategic Opportunities
- Liquid Cargo Specialization:Hazardous materials transport commands premium pricing due to limited certified carrier availability on the Mekong River system.
- Intermodal Transhipment:Java's northern coast-to-interior waterway links offer underdeveloped potential for port operators integrating coastal and river networks.
- Green Vessel Incentives:The ASEAN Green Freight Programme is creating preferential market access for operators deploying alternative propulsion technologies.
Industry Challenges
- Skilled Crew Scarcity:Specialized certification for hazardous cargo handling and advanced navigation systems is outpacing training pipeline capacity across national maritime academies.
- Fleet Modernization Capex:Compliance with Indonesia's Ministry of Transportation emission standards requires capital-intensive engine retrofits or newbuilds with compressed payback periods.
- Legacy Terminal Integration:Thailand's Department of Marine Administration cargo handling protocols are misaligned with automated container tracking systems, complicating digitalization investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Inland Waterway Freight Transport Market |
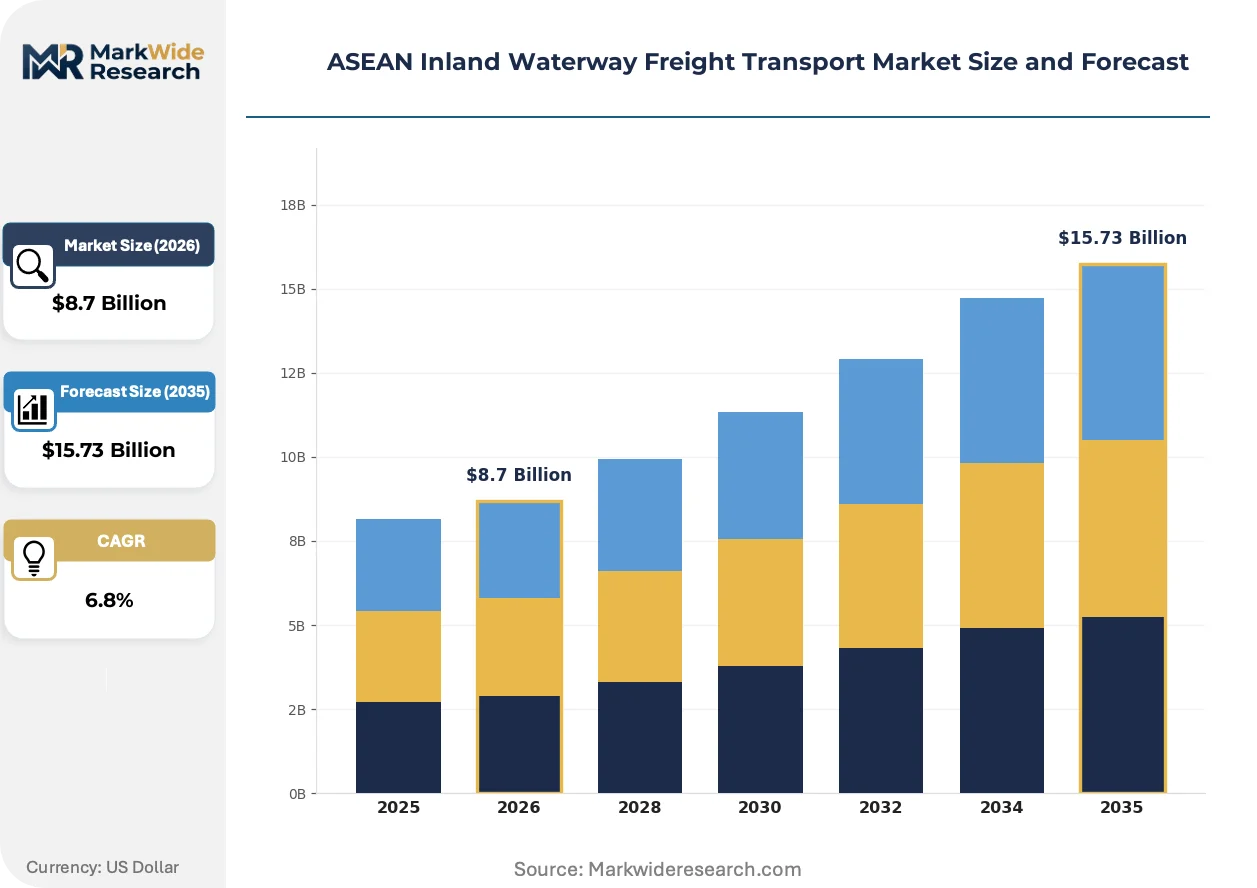
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Type: Barges, Container Ships, Tankers, Bulk Carriers Freight Category: General Cargo, Liquid Cargo, Hazardous Materials, Bulk Commodities End User: Agriculture, Manufacturing, Retail, Construction Operational Model: Charter Services, Scheduled Services, Contract Logistics, Ad Hoc Transport |
| Companies Covered | Siam Shipping, PT Pelindo, Vinafreight, Inland Water Transport Corporation (IWTC), Vietnam National Shipping Lines, Gemadept Corporation, Vinafco Logistics, ASDP Indonesia Ferry, Indonesia Port Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Inland Waterway Freight Transport Market Trends and Innovations
Digital navigation and propulsion technologies are restructuring competitive capabilities across ASEAN river networks. Operators are racing to deploy systems that compress transit times while satisfying tightening environmental mandates.
LNG-battery hybrid propulsion is converging with automated river traffic management systems to enable continuous operations on shallow-draft routes previously limited by fuel range and pilot availability. Vietnamese and Indonesian fleet operators are retrofitting existing hulls with dual-fuel capabilities at accelerating pace. This technology convergence is compressing the cost gap between green vessels and conventional diesel barges on high-frequency corridors.
Thailand's Department of Marine Administration has implemented mandatory electronic logging devices for all cargo vessels transiting the Chao Phraya basin, creating real-time visibility requirements that favor operators with integrated fleet management platforms. The regulation is forcing smaller carriers toward third-party logistics partnerships or exit. Containerized cargo segments are responding fastest, with Bangkok-based manufacturers now requiring ELD-compliant carriers in procurement contracts.
Shippers are unbundling long-term dedicated fleet contracts in favor of spot-market platform booking for non-core routes. Digital freight matching platforms are displacing traditional broker networks on the Vietnam-Cambodia corridor, with agricultural exporters leading adoption. This procurement evolution is most visible in the Mekong Delta, where seasonal volume spikes make fixed-cost fleet commitments economically unattractive for mid-sized commodity traders.
ASEAN Inland Waterway Freight Transport Market Segmentation
Segmentation reveals how vessel specifications, cargo characteristics, and contracting structures determine competitive positioning across Southeast Asia's river networks. Procurement patterns diverge sharply between bulk commodity traders and containerized manufacturers, with regulatory compliance thresholds acting as market filters.
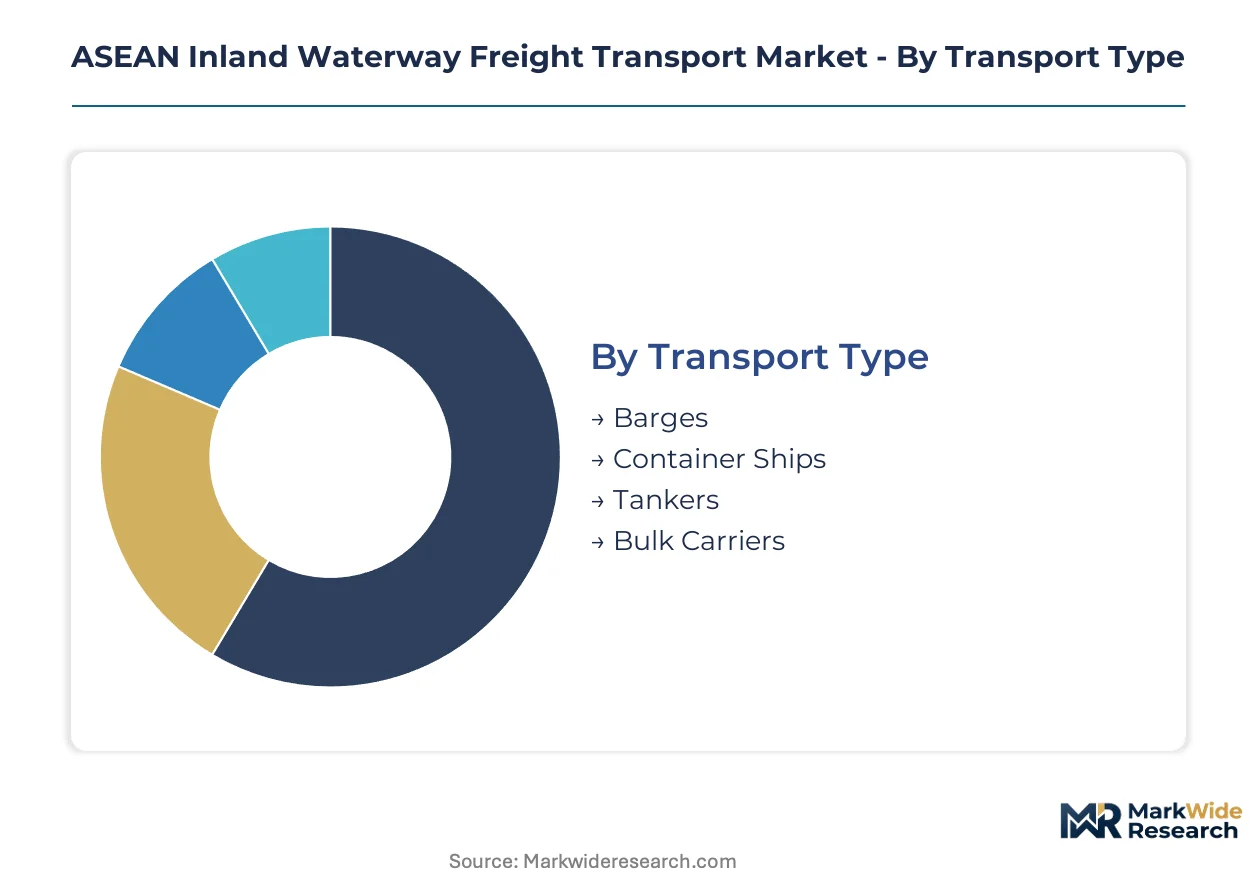
Transport Type:
Propulsion configurations and hull geometries define operational envelopes across varying draft constraints and cargo density requirements.
- Barges:Flat-bottomed hulls with 1.5-4.5 meter draft flexibility dominate shallow Mekong tributaries and Java's interior channels. Thai manufacturing clusters along the Chao Phraya generate concentrated demand for 500-2,000 DWT units moving construction materials and containerized components.
- Container Ships:Cellular vessel designs with standardized slot configurations enable direct transshipment with coastal feeders at Ho Chi Minh City and Bangkok terminals. Vietnamese agricultural exporters are converting road freight to river corridors for cost and emissions savings on Vietnam-Cambodia routes.
- Tankers:Double-hull configurations with segregated cargo compartments serve refined petroleum distribution along Indonesia's maritime axis corridors.
- Bulk Carriers:Open-hatch designs optimized for coal, aggregates, and agricultural commodities operate on Indonesia's port-to-river connectivity routes.
Barges lead on scale; container ships lead on momentum.
Freight Category:
Cargo density and handling protocols create divergent margin profiles and capital intensity requirements.
- Bulk Commodities:Coal, aggregates, and agricultural products generate the highest tonnage volumes with standardized loading equipment. Indonesia's northern Java coast-to-interior waterway links concentrate demand for grab crane-compatible vessels.
- Liquid Cargo:Refined petroleum, palm oil, and chemical feedstocks require tank cleaning certification and vapor recovery systems. Hazardous materials transport commands premium pricing due to limited certified carrier availability on the Mekong River system.
- General Cargo:Breakbulk manufactured goods and project cargo utilize multi-purpose vessels with adjustable tween decks.
- Hazardous Materials:Specialized certification requirements and limited carrier availability create supply-constrained pricing premiums.
Bulk commodities lead on scale; liquid cargo leads on margin.
End User:
Industry-specific logistics requirements shape vessel allocation patterns and contract structures.
- Manufacturing:Just-in-time component delivery demands reliable scheduled services with electronic logging device compliance. Bangkok-based manufacturers now require ELD-compliant carriers in procurement contracts.
- Agriculture:Seasonal volume spikes and perishability constraints favor flexible charter arrangements over fixed fleet commitments. Mekong Delta exporters are unbundling long-term contracts in favor of spot-market platform booking.
- Retail:Containerized consumer goods prioritize intermodal connectivity with coastal shipping networks.
- Construction:Heavy-lift requirements for steel and cement favor barges with reinforced decks and distributed loading capabilities.
Manufacturing leads on contract value; agriculture leads on volume volatility.
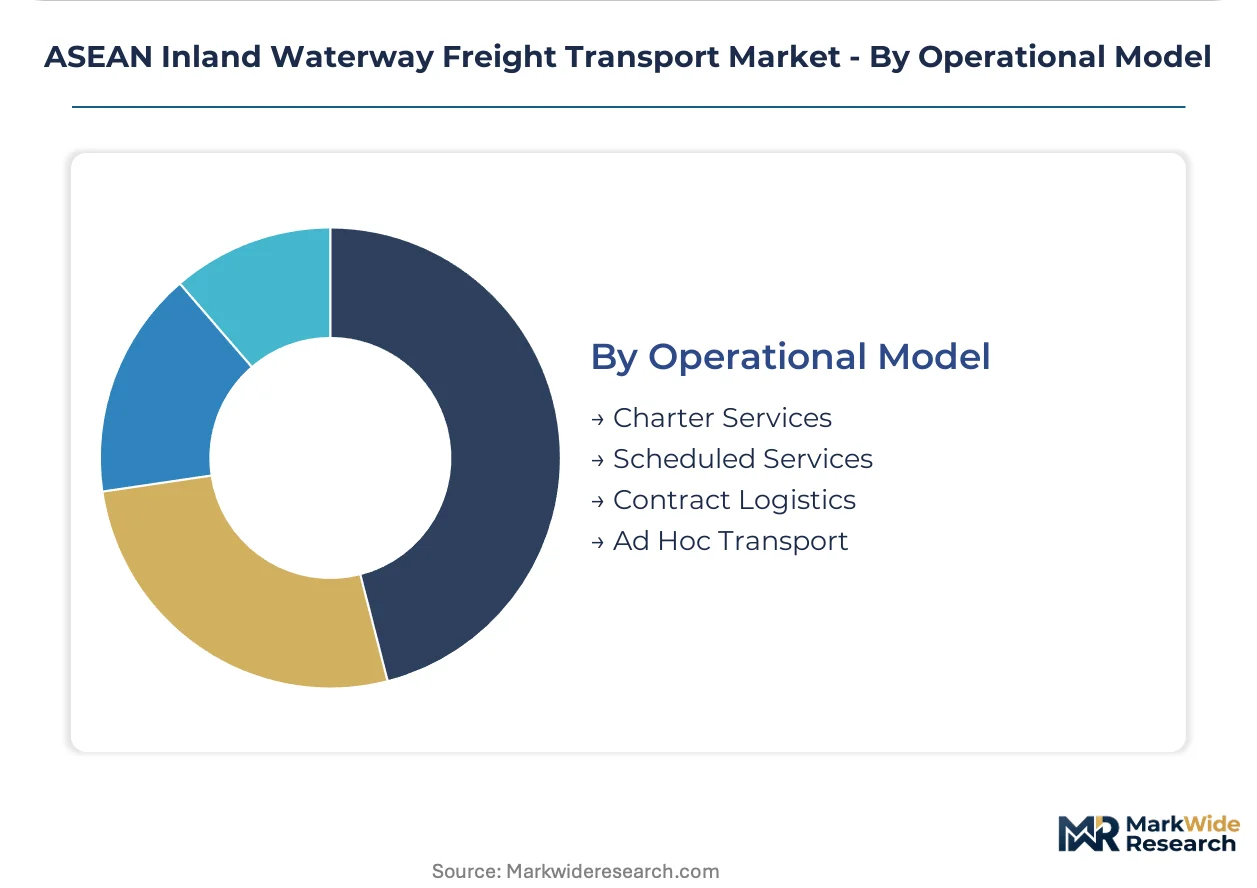
Operational Model:
Asset utilization strategies and risk allocation mechanisms determine fleet investment cycles and working capital intensity.
- Contract Logistics:Multi-year dedicated fleet agreements with integrated warehousing and customs clearance services. PT Pelindo leverages its intermodal port network to dominate transhipment between Java's northern coast and interior waterways.
- Scheduled Services:Fixed-route, fixed-departure operations with published tariffs and guaranteed capacity allocation. Thailand's Department of Marine Administration electronic logging mandates favor operators with integrated fleet management platforms.
- Charter Services:Voyage-specific or time-charter arrangements for project cargo and seasonal agricultural peaks.
- Ad Hoc Transport:Spot-market transactions through digital freight matching platforms displacing traditional broker networks on the Vietnam-Cambodia corridor.
Contract logistics leads on revenue stability; ad hoc transport leads on digital adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASEAN inland waterway freight transport traces its modern lineage to post-colonial riverine trade networks established along the Mekong and Chao Phraya basins during the 1960s, when barges first displaced rail for bulk agricultural movement between delta regions and coastal ports.
Vietnam
Mekong Delta containerized agricultural exports are converting road freight to river corridors between Ho Chi Minh City and Phnom Penh. Vietnam's Maritime Administration enforces vessel safety standards that dictate fleet modernization timelines for cross-border operators. Can Tho and An Giang provinces concentrate barge loading activity for rice and seafood exports moving through Cai Mep deep-water terminals.
Thailand
Bangkok's manufacturing hinterland generates concentrated demand for construction materials and electronics components moving along the Chao Phraya River corridor. Thailand's Department of Marine Administration mandates electronic logging devices for all cargo vessels transiting the basin, favoring operators with integrated fleet management platforms. Ayutthaya and Pathum Thani industrial zones anchor scheduled barge services feeding Laem Chabang port.
Indonesia
Java's northern coast-to-interior waterway links concentrate bulk coal and palm oil movements between Tanjung Priok and Cilacap. Indonesia's Ministry of Transportation channels state capital into port-to-river connectivity upgrades under its maritime axis policy. Surabaya and Semarang manufacturing clusters drive fleet renewal investments for shallow-draft routes serving interior distribution centers.
Cambodia
Phnom Penh river port traffic is expanding as Vietnamese agricultural exporters seek alternative routing to avoid road congestion at border crossings. Cambodia's Ministry of Public Works and Transport coordinates vessel certification harmonization with Vietnamese counterparts for Mekong transits. Kandal province terminals handle transshipment growth between Vietnam-sourced containers and Cambodian manufacturing inputs.
Myanmar
Ayeyarwady River bulk commodity movements face infrastructure constraints limiting vessel draft to 2.5 meters during dry season operations. Myanmar's Department of Marine Administration maintains vessel registration standards divergent from ASEAN neighbors, fragmenting cross-border efficiency. Yangon and Mandalay industrial corridors concentrate limited containerized cargo activity serving domestic manufacturing distribution.
ASEAN Inland Waterway Freight Transport Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specialized cargo handling and integrated port-network control. The market structures around three tiers: state-linked port operators with captive hinterland access, specialized liquid cargo handlers with hazardous materials certification, and fragmented ad hoc charter operators competing on spot rates. Strategic archetypes include intermodal integrators leveraging coastal-river connectivity, hazardous cargo specialists commanding scarcity premiums, and digital platform operators displacing traditional brokerage. Dominant competitive moves encompass fleet modernization for green compliance and strategic partnerships with agricultural exporters for dedicated contract logistics.
Among Vietnam-based operators, Vinafreight and Vietnam National Shipping Lines exemplify specialized liquid cargo and integrated coastal-river positioning respectively. PT Pelindo represents the state-linked intermodal archetype dominating Java's northern coast-to-interior corridors. These three anchors illustrate how geographic concentration and regulatory relationships determine competitive tier placement across ASEAN river networks.
| Leading Market Players |
|---|
| Siam Shipping |
| PT Pelindo |
| Vinafreight |
| Inland Water Transport Corporation (IWTC) |
| Vietnam National Shipping Lines |
| Gemadept Corporation |
| Vinafco Logistics |
| ASDP Indonesia Ferry |
| Indonesia Port Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between hazardous cargo specialists and general freight operators splits both pricing power and supplier networks across Mekong and Chao Phraya corridors. Vietnam's Maritime Administration safety mandates and Indonesia's Ministry of Transportation emission standards create tiered compliance ladders that concentrate premium pricing with certified carriers while commodity barge rates erode from fleet oversupply.
Pricing Analysis
Contract-based long-term offtake agreements dominate scheduled services along Thailand's Chao Phraya basin, with spot-market platforms capturing seasonal agricultural peaks on Vietnam-Cambodia routes. Price differentiation rests on hazardous materials certification and electronic logging device compliance, with Bangkok manufacturers paying premiums for ELD-integrated fleets. Cost compression in general cargo tiers intensifies as digital freight matching platforms disintermediate traditional brokers. Agriculture exporters exhibit highest price sensitivity, while manufacturing procurement teams prioritize reliability over rate minimization.
Supply Chain Analysis
Marine engine and hull construction inputs rest on South Korean and Chinese shipyard capacity, with specialized navigation electronics drawing from Japanese and Singaporean suppliers. Steel plate and diesel propulsion systems anchor vessel build costs, while LNG-battery hybrid retrofit kits remain concentrated among European and South Korean technology licensors. Single-source vulnerability runs through advanced emissions control system suppliers serving Indonesia's maritime axis fleet renewal. Distribution runs through state-linked port operators with captive hinterland access, fragmenting independent carrier procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN inland waterway freight transport market compounds steadily as containerized agricultural export growth and manufacturing hinterland expansion generate predictable tonnage demand across river corridors.
For Market Incumbents: Deploy fleet modernization as the primary lever to capture green vessel incentives under the ASEAN Green Freight Programme. Retrofit existing hulls with dual-fuel capabilities before regulatory deadlines compress asset values. Secure backward integration into terminal operations at Cai Mep and Laem Chabang to lock in transshipment volumes against emerging digital platform competitors. For New Entrants and Emerging Players: Digital freight matching platforms offer the most penetrable entry vector for spot-market agricultural segments in the Mekong Delta. Target liquid cargo specialization where hazardous materials certification scarcity supports premium rate capture. Pursue partnership-based go-to-market approaches with Vietnamese agricultural cooperatives seeking alternatives to road freight congestion at Cambodia border crossings. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented ad hoc charter operators lack capital for Indonesia's Ministry of Transportation emission compliance investments. The market supports 5-10 year holding periods for intermodal integrators controlling Java's northern coast-to-interior corridors. Watch ASEAN regulatory harmonization progress as the signal indicating cross-border operational efficiency inflection and scalable platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization for Green Compliance | Indonesia's maritime axis policy channels state capital toward LNG-battery hybrid retrofits, accelerating payback compression for conventional diesel assets. |
| Terminal Infrastructure Integration | PT Pelindo's intermodal port network dominance creates captive hinterland access that independent barge operators cannot replicate without capital partnerships. |
| Liquid Cargo Specialization | Vinafreight's hazardous materials certification scarcity on the Mekong River system supports premium pricing that general freight operators cannot match. |
| Digital Platform Development | Electronic logging device mandates from Thailand's Department of Marine Administration favor integrated fleet management platforms that displace smaller carriers. |
| Cross-Border Regulatory Harmonization | Vietnam's Maritime Administration coordination with Cambodian counterparts on vessel certification standards unlocks operational efficiency gains for early movers. |
Research Methodology
Coverage spans Vietnam, Thailand, Indonesia, Cambodia, and Myanmar, with primary inputs from each national waterway administration. The analysis combines interviews with fleet operations managers, terminal infrastructure directors, agricultural export logistics coordinators, and maritime regulatory compliance officers with secondary validation from customs trade databases, national transport ministry filings, and ASEAN secretariat policy documents. Bottom-up vessel capacity assessments and top-down trade flow estimates provide triangulation checks across the analysis window.
Segment-level granularity models transport type, freight category, end user industry, and operational model dimensions across the projection horizon. CAGRs derive from tonnage growth assumptions tied to Mekong Delta agricultural export expansion and Chao Phraya manufacturing hinterland development. Industry-specific forecast inputs incorporate Indonesia's maritime axis infrastructure spend trajectories and Vietnam-Cambodia cross-border vessel certification harmonization timelines.
The model assumes a particular technology adoption path for LNG-battery hybrid propulsion; alternative pathways for methanol or ammonia fuel systems would alter the fleet renewal capex outlook and carrier competitive positioning. Forecasts reflect assumptions about regulatory enforcement consistency and agricultural commodity price stability that Vietnam's Maritime Administration policy shifts or climate-induced Mekong flow variation could revise. A small set of triggers—ASEAN Green Freight Programme mandate acceleration, Indonesia-Philippines regulatory alignment breakthroughs, and Bangkok manufacturing relocation patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Freight Transport Market