
 Automatic Vehicle Location System (AVL) Market | 2026-2036
Automatic Vehicle Location System (AVL) Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Vehicle Location System (AVL) Market Insights
The capability gap between hardware-centric and software-native AVL providers is collapsing as cloud platforms commoditize GPS processing. Continental AG leverages its Tier-1 automotive relationships to sustain embedded module contracts across European OEMs. Geotab competes through open API architecture that anchors third-party fleet analytics ecosystems. Samsara differentiates by verticalizing from device to dashboard, controlling subscription revenue in North American logistics.
Automatic Vehicle Location Systems comprise GPS receivers, cellular modems, and onboard computing units that transmit latitude, longitude, and telemetry data to centralized servers at sub-minute intervals for real-time coordination. The primary commercial purpose spans route optimization, asset security, and regulatory compliance logging for mobile fleets. Hardware still occupies the largest revenue pool though margin accretion is shifting toward software subscriptions, while integrated GPS-cellular systems represent the fastest-expanding technology pairing as dual-mode redundancy becomes standard in emergency services and cold-chain logistics. Fleet management end users dominate procurement volume, but public transport authorities are driving specification rigor through open-data mandates.
The US DOT ELD mandate and FCC Part 90 private land mobile radio standards shape device certification requirements, while EU GDPR and the proposed EU Data Act constrain cross-border telematics storage architectures. Japan's METI connected vehicle guidelines and ISO 15638 framework for cooperative intelligent transport systems further complicate multi-jurisdictional platform design. Stakeholders must decide whether to architect for regulatory fragmentation or pursue modular compliance layers that adapt to diverging data sovereignty regimes.

Market Dynamics
ELD mandates from the US DOT and GDPR constraints from the EU are forcing AVL providers to architect modular compliance layers rather than unified global platforms, collapsing the traditional hardware-software boundary as cloud-native processing commoditizes GPS telemetry.
Growth Catalysts
- ELD Mandate Compliance:The US DOT's electronic logging device requirements for commercial carriers accelerate replacement cycles across North American trucking fleets, embedding cellular-GPS modules as standard equipment.
- Cooperative Intelligent Transport Systems:Japan's METI connected vehicle guidelines and the ISO 15638 framework drive OEM integration of AVL architectures into factory-installed telematics stacks.
- Cold-Chain Logistics Expansion:Pharmaceutical and perishable food distributors in Germany's automotive corridor demand sub-minute location telemetry with temperature correlation, pulling dual-redundancy GPS-cellular systems into fleet specifications.
Market Restraints
- Semiconductor Supply Concentration:GPS receiver and cellular modem fabrication concentrates in East Asian foundries, exposing module assemblers to input volatility and extended lead times for automotive-grade components.
- Data Sovereignty Fragmentation:The EU Data Act and GDPR's cross-border storage constraints force redundant server infrastructure across jurisdictions, inflating platform operating costs for multi-national fleet operators.
- Legacy Radio Substitution:Private land mobile radio systems under FCC Part 90 standards retain cost advantages for rural municipal fleets, slowing cellular migration in budget-constrained public safety segments.
Strategic Opportunities
- Indian Fleet Formalization:The country's PLI scheme for automotive electronics and expanding organized logistics sector create first-mover potential for cloud-native AVL providers targeting unpenetrated commercial vehicle populations.
- Predictive Maintenance Convergence:Integration of AVL telemetry with engine diagnostic APIs and tire pressure monitoring creates bundled subscription value for long-haul operators seeking unified fleet intelligence.
- Open-Data Transit Mandates:European public transport authorities specifying real-time vehicle position publication under mobility-as-a-service frameworks generate specification-grade demand for API-first platform architectures.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for low-power GPS-cellular modules requires specialized expertise in automotive functional safety standards, constraining product development velocity at mid-tier providers.
- Multi-Jurisdictional Certification Timelines:Simultaneous FCC, CE marking, and METI type approval processes extend time-to-market by 8-14 months for integrated hardware platforms targeting cross-border fleet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Vehicle Location System (AVL) Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $57.6 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Integrated Systems, Standalone Solutions Technology: GPS, RFID, Cellular, Wi-Fi End User: Logistics, Public Transport, Emergency Services, Fleet Management Application: Real-Time Tracking, Route Optimization, Fleet Monitoring, Vehicle Recovery |
| Companies Covered | Continental AG, Motorola Solutions, Garmin, Motive, Samsara, CalAmp, Geotab, Descartes, Teletrac Navman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Vehicle Location System (AVL) Market Trends and Innovations
Cloud-based telemetry processing is decomposing the traditional AVL value chain, compressing margins for hardware-centric vendors while enabling software-native entrants to capture recurring revenue through platform subscriptions.
Edge computing architectures with onboard inference capabilities are decomposing the historical dependency on centralized servers for route optimization. Cold-chain operators in Germany and the Netherlands deploy these systems to enable real-time rerouting during refrigeration failures without cellular latency. The shift compresses differentiation for legacy hardware vendors lacking embedded AI silicon partnerships.
The EU Data Act's proposed restrictions on cross-border telematics storage are forcing platform architects to regionalize server infrastructure by member state. Fleet operators with pan-European coverage face compliance complexity that favors modular providers over monolithic global platforms. German automotive OEMs respond by embedding localized data residency into connected vehicle contracts.
Third-party fleet analytics ecosystems anchored through open APIs are displacing vertically integrated software stacks among North American logistics buyers. Large carriers now procure AVL hardware as a commodity input while subscribing to route optimization and driver scoring from specialized SaaS vendors. This unbundling concentrates procurement leverage with buyers capable of integrating multi-vendor toolchains.
Automatic Vehicle Location System (AVL) Market Segmentation
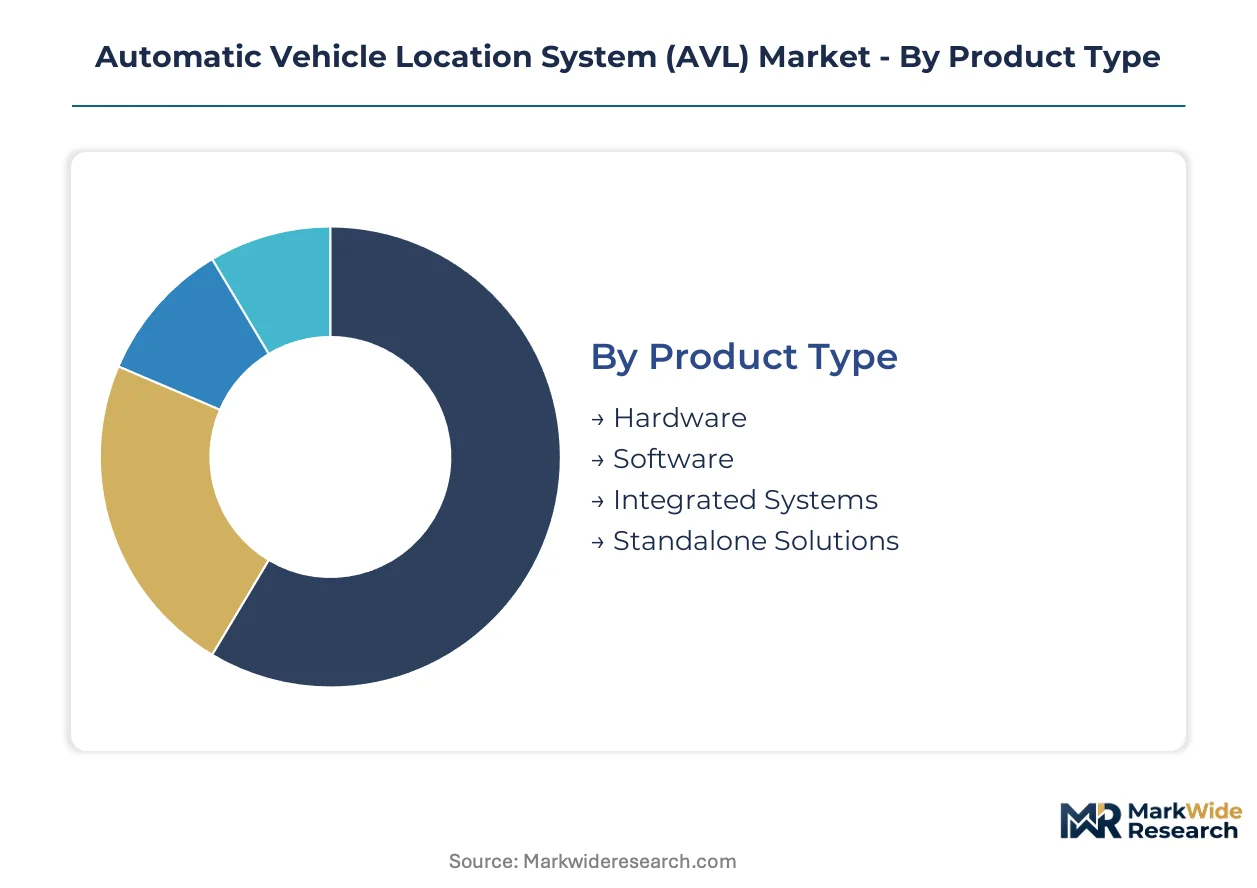
AVL procurement patterns diverge sharply across product architectures and technology pairings, with hardware-centric buyers prioritizing embedded durability while software-native adopters favor API extensibility. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Hardware and integrated systems command domestic procurement volumes in North America and Germany, while software subscriptions and standalone solutions travel cross-border through cloud delivery models.
- Hardware:GPS receivers, cellular modems, and onboard computing units fabricated to automotive-grade specifications. Fleet operators in the United States anchor replacement demand through ELD mandate compliance, though semiconductor lead times from East Asian foundries constrain fulfillment velocity.
- Integrated Systems:Factory-installed telematics stacks combining GPS-cellular modules with OEM vehicle buses. German automotive corridors embed these architectures into connected vehicle contracts, pulling specification-grade requirements from Tier-1 suppliers.
- Software:Cloud-native platforms processing telemetry through subscription APIs. Delivery spans jurisdictions without physical manufacturing constraints.
- Standalone Solutions:Modular units for retrofit installation across heterogeneous fleet ages. Municipal buyers in budget-constrained segments favor these for incremental deployment.
Hardware holds the largest share; momentum sits with integrated systems.
Technology:
Cellular and GPS pairings dominate volume procurement, while RFID and Wi-Fi carve defensive positions in cost-sensitive or latency-critical niches.
- GPS:Satellite-based positioning providing latitude, longitude, and velocity vectors at sub-minute intervals. Cold-chain operators in Germany demand dual-redundancy configurations to safeguard temperature-correlated telemetry.
- Cellular:4G LTE and emerging 5G modems transmitting encrypted data packets to centralized servers. The FCC's Part 90 standards and EU GDPR constraints shape certification complexity for cross-border fleet deployments.
- RFID:Passive and active radio-frequency identification for yard management and depot tracking. Lower infrastructure costs retain relevance for last-mile operators with fixed facility networks.
- Wi-Fi:Short-range connectivity leveraging depot and urban hotspot density. Urban public transport authorities in European open-data mandates deploy these for real-time passenger information systems.
Cellular-GPS combinations anchor revenue concentration; Wi-Fi is climbing the fastest as smart city infrastructure densifies.
End User:
Fleet management and logistics buyers drive export-led procurement through multinational carrier networks, while public transport and emergency services concentrate domestically around municipal contracting regimes.
- Fleet Management:Commercial operators optimizing asset utilization across distributed vehicle populations. North American logistics carriers unbundle hardware from software, procuring GPS-cellular modules as commodity inputs while subscribing to specialized route analytics.
- Logistics:Long-haul trucking and last-mile delivery networks requiring regulatory compliance logging. The US DOT ELD mandate accelerates replacement cycles for commercial carriers operating across state lines.
- Public Transport:Municipal and regional authorities specifying real-time vehicle position publication. European mobility-as-a-service frameworks generate API-first demand for open-data compliance.
- Emergency Services:Police, fire, and ambulance fleets requiring mission-critical location redundancy. FCC Part 90 private land mobile radio standards retain cost advantages in rural coverage gaps.
Fleet management holds the largest share; public transport is gaining share fastest through open-data mandate proliferation.
Application:
Real-time tracking and fleet monitoring concentrate in high-frequency logistics corridors, while route optimization and vehicle recovery spread across fragmented municipal and insurance-led demand pools.
- Real-Time Tracking:Continuous position transmission enabling dispatch coordination and asset security. Pharmaceutical distributors in the Netherlands deploy edge-computing architectures to reroute during refrigeration failures without cellular latency.
- Fleet Monitoring:Aggregated telemetry dashboards unifying vehicle health, driver behavior, and compliance status. Large North American carriers integrate multi-vendor toolchains through open API ecosystems.
- Route Optimization:Algorithmic pathfinding reducing fuel consumption and transit time. Cloud-native processing commoditizes this capability, compressing differentiation for legacy software vendors.
- Vehicle Recovery:Theft detection and stolen asset retrieval services. Insurance underwriters in Germany bundle these subscriptions with connected vehicle policies.
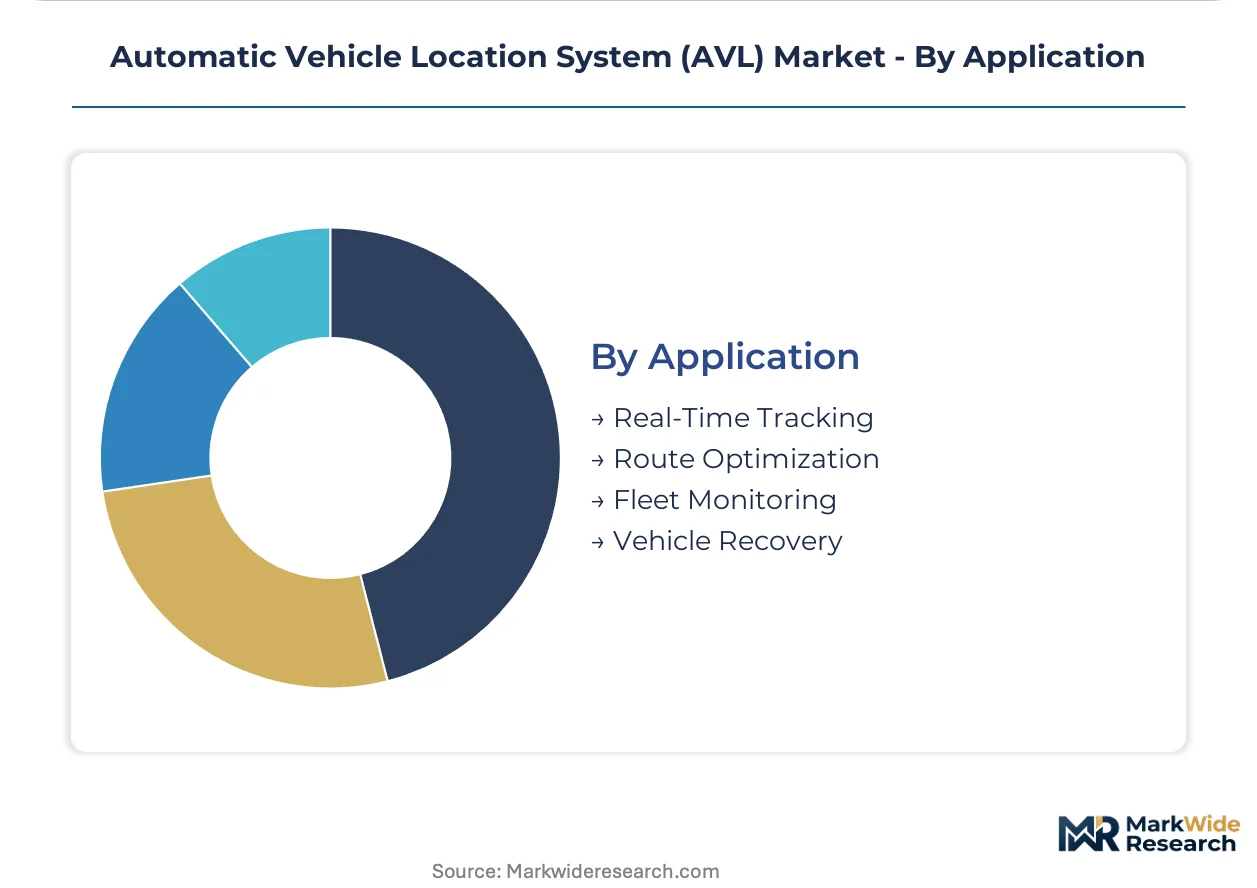
Real-time tracking holds the largest share; route optimization shows the steepest expansion trajectory as AI inference migrates to edge silicon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major AVL markets. The United States prioritizes ELD mandate compliance for commercial trucking, Germany embeds modules into OEM connected vehicle architectures, and India represents greenfield penetration opportunity as organized logistics formalizes.
United States
Fleet operators anchor replacement demand through US DOT electronic logging device mandates for interstate commercial carriers. FCC Part 90 private land mobile radio standards shape certification requirements for cross-border deployments. California-based logistics carriers unbundle hardware procurement from software subscriptions, procuring GPS-cellular modules as commodity inputs while integrating multi-vendor analytics toolchains.
Germany
Automotive OEMs embed AVL architectures into factory-installed telematics stacks under EU Data Act data residency constraints. KBA type approval processes and GDPR cross-border storage rules force redundant server infrastructure across member states. Baden-Württemberg's automotive corridor concentrates Tier-1 supplier relationships where Continental AG sustains embedded module contracts.
Japan
METI connected vehicle guidelines and ISO 15638 cooperative intelligent transport systems frameworks drive OEM integration of AVL modules. Domestic manufacturers prioritize dual-redundancy GPS-cellular configurations for mission-critical applications. Nagoya's Chubu region anchors automotive electronics production where embedded systems talent scarcity constrains firmware development velocity.
India
Organized logistics sector expansion and PLI scheme incentives for automotive electronics create first-mover potential for cloud-native AVL providers. Unpenetrated commercial vehicle populations across fragmented owner-operator fleets offer volume upside. Maharashtra's Mumbai-Pune industrial corridor concentrates organized trucking operations where formal fleet management adoption accelerates.
Netherlands
Pharmaceutical distributors deploy edge-computing AVL architectures for cold-chain rerouting during refrigeration failures without cellular latency. EU open-data transit mandates under mobility-as-a-service frameworks generate specification-grade demand for API-first platforms. Rotterdam's port logistics cluster drives sub-minute location telemetry requirements for temperature-correlated asset tracking.
Automatic Vehicle Location System (AVL) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the boundary collapsing as cloud platforms commoditize GPS processing. Tier-1 automotive suppliers leverage OEM relationships for embedded module contracts, while software-native entrants capture recurring revenue through platform subscriptions. Two strategic archetypes dominate: hardware-centric vendors with automotive-grade fabrication capabilities, and API-first providers anchoring third-party analytics ecosystems. Competitive moves concentrate on M&A for embedded AI silicon partnerships and geographic expansion targeting Indian fleet formalization.
Within the integrated automotive tier, Continental AG exemplifies Tier-1 positioning through embedded module relationships. Among software-native specialists, Geotab and Samsara occupy positions at opposite ends of the vertical integration spectrum—Geotab through open API ecosystems, Samsara through device-to-dashboard control. Motorola Solutions represents the mission-critical communications archetype, serving emergency services segments where FCC Part 90 radio standards retain cost advantages. Garmin anchors consumer and commercial crossover positioning, spanning fleet and recreational applications.
| Leading Market Players |
|---|
| Continental AG |
| Motorola Solutions |
| Garmin |
| Motive |
| Samsara |
| CalAmp |
| Geotab |
| Descartes |
| Teletrac Navman |
| Others |
Pricing and Supply Chain Analysis
FCC Part 90 certification requirements for private land mobile radio systems simultaneously gate supplier qualification and stratify price tiers across the AVL hardware landscape, compressing margins for uncertified assemblers while embedding premium capture for dual-mode cellular-radio module vendors serving mission-critical emergency fleets.
Pricing Analysis
Long-term offtake contracts dominate procurement for North American logistics carriers bundling ELD-compliant hardware with multi-year SaaS subscriptions, while municipal buyers in constrained budgets favor spot purchasing of standalone retrofit units. Price differentiation separates automotive-grade modules with ISO 26262 functional safety certification from commercial-grade alternatives lacking temperature resilience. Cost compression in the standalone retrofit tier intensifies as cloud-native platforms commoditize GPS processing, eroding hardware premiums. Fleet management operators exhibit highest price sensitivity, while emergency services segments absorb certification-driven premiums for mission-critical redundancy.
Supply Chain Analysis
Strategic stockpiling of automotive-grade GPS receivers and cellular modems has displaced just-in-time preferences among Tier-1 module assemblers confronting extended lead times from East Asian foundries. GPS receiver fabrication concentrates in Taiwan, South Korea, and Japan, while cellular modem production anchors in China and Vietnam. Raw material dependencies span semiconductor-grade silicon substrates, rare-earth magnet components for antenna assemblies, and lithium-ion cells for backup power systems. Single-source vulnerability in automotive-grade GPS chipset supply exposes module vendors to allocation rationing during capacity constraints. Distribution runs through OEM direct contracts for integrated systems and specialized fleet technology distributors for aftermarket retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-native location services and embedded OEM telematics stacks pose accelerating substitution threats to standalone AVL hardware providers, forcing incumbents to defend recurring revenue through platform stickiness rather than device attachment.
For Market Incumbents: Fortify subscription retention by deepening API ecosystem partnerships with specialized fleet analytics vendors, insulating against unbundling pressure from buyers procuring hardware as commodity inputs. Prioritize backward integration into edge-computing silicon partnerships to preserve differentiation as cloud processing commoditizes GPS telemetry. The priority lever rests on controlling data-layer subscriptions even as device margins erode. For New Entrants and Emerging Players: Differentiate on cloud-native architectures targeting India's unpenetrated owner-operator fleet segments, where PLI scheme incentives and organized logistics formalization create first-mover white space. Penetrate the municipal public transport vertical through API-first platforms compliant with European open-data mandates, bypassing hardware-centric incumbents locked in legacy radio substitution battles. Anchor go-to-market through mobility-as-a-service consortium bids specifying real-time position publication requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-native platform segments as cloud infrastructure displaces captive hardware fabrication, improving return profiles for SaaS-heavy targets versus integrated device vendors. Long-term viability favors acquisition of modular compliance-layer architects capable of adapting to diverging data sovereignty regimes across jurisdictions. The signal to watch is OEM telematics stack standardization velocity, which would compress standalone hardware addressable market if factory-installed penetration accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded AI Silicon Partnership | Edge inference capabilities enable real-time cold-chain rerouting without cellular latency for pharmaceutical distributors. |
| Modular Compliance Layer Architecture | Regional data residency adaptation addresses EU Data Act constraints without redundant global platform replication. |
| Open API Ecosystem Expansion | Third-party analytics anchoring prevents unbundling as North American carriers procure hardware as commodity inputs. |
| Indian Market Geographic Entry | PLI scheme incentives and organized logistics formalization create first-mover advantage in unpenetrated commercial vehicle populations. |
| Predictive Maintenance Integration | Engine diagnostic API bundling generates subscription stickiness for long-haul operators seeking unified fleet intelligence. |
Research Methodology
Operator-level perspectives from fleet management directors, OEM telematics procurement leads, Tier-1 automotive supplier executives, and municipal transit authority technology officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through FCC ELD mandate documentation, EU Data Act regulatory filings, METI connected vehicle guideline publications, and automotive production database tracking. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis framed the quantitative architecture, with volume and value outputs reflecting cross-verification between supply-side capacity assessments and demand-side procurement surveys across product type, technology pairing, end-user vertical, and application segmentation. CAGRs were derived from fitted growth curves calibrated to replacement cycle dynamics under regulatory mandate pressure and technology diffusion patterns in cold-chain logistics. Forecast inputs incorporated semiconductor lead time volatility indices and fleet formalization rates in emerging markets.
The analysis sits within stated boundaries; outcomes outside sustained ELD enforcement intensity, GDPR data residency stability, or East Asian foundry capacity normalization would require recalibration. Forecasts reflect documented assumptions regarding regulatory mandate adherence rates and cloud platform substitution velocity. Revision becomes warranted when OEM embedded telematics penetration crosses critical thresholds or when data sovereignty fragmentation accelerates beyond modular adaptation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Malaysia Domestic CEP Market