
 Germany Road Freight Transport Market | 2026-2036
Germany Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Road Freight Transport Market Foresight
Telematics integration with predictive routing algorithms is rewriting fleet economics across German road freight. DACHSER leverages its European network density to sustain cross-border consolidation advantages. Deutsche Bahn AG anchors intermodal offerings that compete with pure trucking on long-haul lanes. DHL Group differentiates through pharmaceutical and automotive logistics specialization.
Road freight transport in Germany encompasses the movement of goods via motor vehicles on federal highways, autobahns, and municipal roads, utilizing vehicles ranging from 3.5-tonne light commercial units to 40-tonne heavy goods vehicles with standardized EU dimensions. The sector serves as the backbone of industrial supply chains, handling approximately three-quarters of domestic freight tonnage while interfacing with rail, inland waterway, and air cargo systems. Heavy goods vehicles dominate tonnage-moved metrics, though refrigerated trucks command premium rate structures due to temperature-controlled infrastructure requirements. Electric powertrains within the fuel type category attract fleet investment despite higher capital costs, driven by urban access restrictions and total-cost-of-ownership improvements.
The Kraftfahrt-Bundesamt enforces driver hour regulations and vehicle inspection standards that directly shape fleet sizing and route planning decisions. EU Green Deal emissions targets and Germany's national climate protection framework mandate progressive CO2 reductions for new heavy-duty vehicles, forcing carrier investment cycles toward alternative drivetrains. The Bundesamt für Güterverkehr monitors cabotage compliance and market access conditions for international operators. Stakeholders must weigh electrification capex against regulatory compliance timelines while monitoring charging infrastructure buildout along priority corridors.
Market Dynamics
The EU Green Deal's CO2 emissions standards for heavy-duty vehicles are forcing German carriers into compressed fleet renewal cycles, while e-commerce fulfillment density in the Rhine-Ruhr corridor is reshaping asset utilization economics.
Growth Catalysts
- E-commerce fulfillment networks:Online retail distribution centers in North Rhine-Westphalia are generating sustained tonnage demand for regional carriers.
- EU Green Deal mandates:Progressive CO2 reduction targets for new heavy-duty vehicles are accelerating investment in alternative drivetrains.
- Telematics integration:Predictive routing algorithms are compressing empty-mile ratios and improving fleet economics across German road freight operations.
Market Restraints
- Charging infrastructure gaps:Insufficient high-power charging corridors along priority freight routes is delaying full fleet electrification timelines.
- Driver availability constraints:Kraftfahrt-Bundesamt hour regulations are limiting operational flexibility and expanding wage pressure.
- Capital intensity of zero-emission vehicles:Battery-electric and hydrogen fuel cell trucks require substantially higher upfront investment versus diesel equivalents.
Strategic Opportunities
- Intermodal integration:Deutsche Bahn AG's rail-road terminals offer carriers access to long-haul lanes with reduced driver hour exposure.
- Pharmaceutical cold chain specialization:Temperature-controlled logistics for biologics commands premium rate structures with higher margin stability.
- Urban access restrictions:Zero-emission zones in German city centers are creating first-mover advantages for electrified last-mile fleets.
Industry Challenges
- Skill gaps in electric powertrain maintenance:Technician certification for high-voltage systems is lagging fleet deployment schedules.
- Legacy fleet depreciation cycles:Compressed regulatory timelines are stranding diesel assets before full economic life realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Road Freight Transport Market |
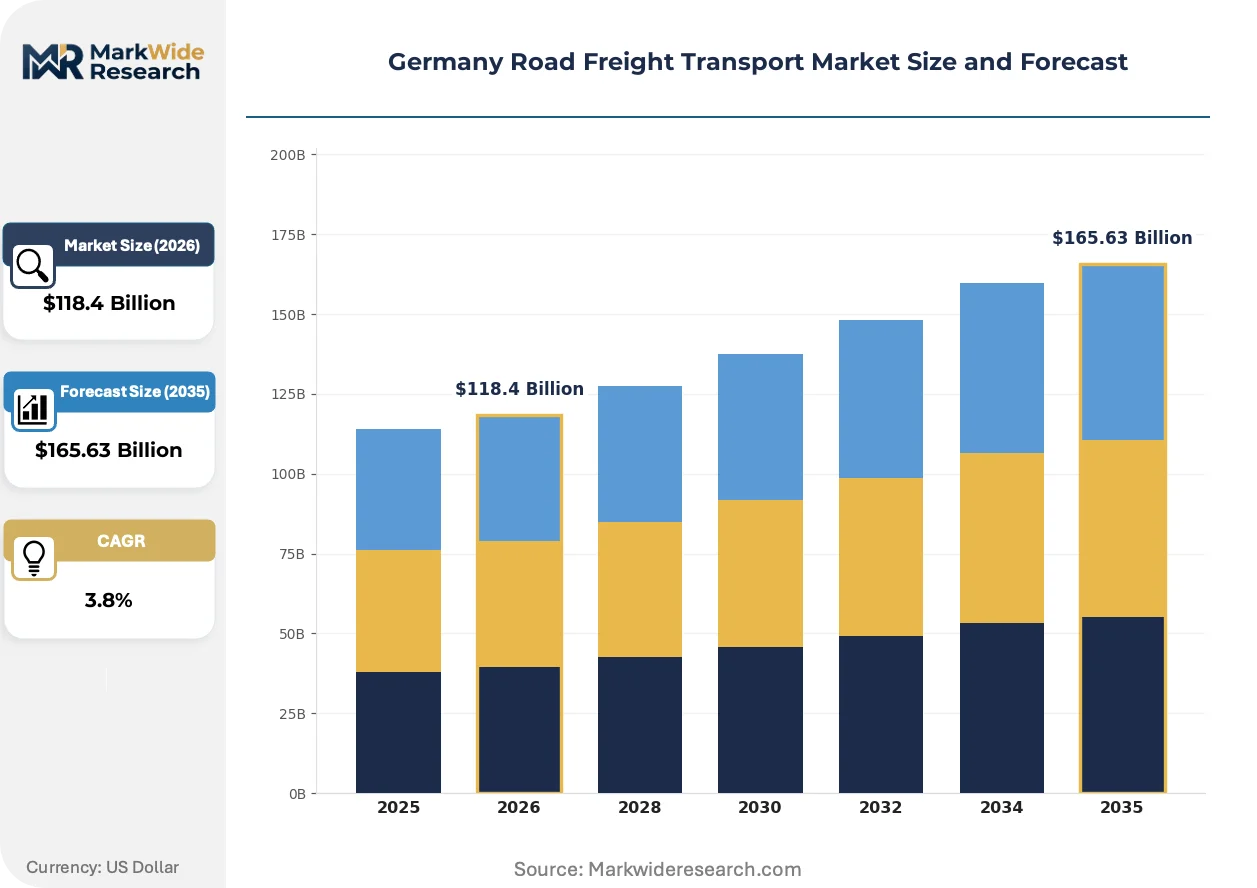
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $165.63 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Commercial Vehicles, Heavy Goods Vehicles, Trailers, Tankers, Refrigerated Trucks Service Type: Full Truckload, Less Than Truckload, Expedited Shipping, Courier Services, Door-to-Door Delivery Customer Type: Manufacturing Firms, Wholesale Distributors, E-commerce Businesses, Construction Companies, Agricultural Producers Fuel Type: Diesel, Compressed Natural Gas, Electric, Hybrid, Biodiesel |
| Companies Covered | Kuehne+Nagel, Pabst Transport GmbH & Co. KG, DACHSER, DSV A/S (De Sammensluttede Vognmænd af Air and Sea), Raben Group, Deutsche Bahn AG (including DB Schenker), United Parcel Service of America, Inc. (UPS), A.P. Moller - Maersk, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Road Freight Transport Market Shifts & Advancements
Digital freight matching platforms and autonomous dispatch systems are restructuring how German carriers source loads and optimize asset deployment across fragmented shipper demand.
Autonomous platooning technology is rendering obsolete traditional convoy coordination between human drivers. Major automotive manufacturers are piloting vehicle-to-vehicle communication systems on autobahn corridors. Fleet operators adopting these systems are compressing fuel consumption and labor costs on high-volume lanes.
The EU Green Deal's progressive CO2 standards for heavy-duty vehicles are mandating alternative drivetrain adoption timelines. German carriers must phase out internal combustion engines according to binding reduction curves. Heavy goods vehicle segments serving long-haul routes face the most compressed transition schedules.
Shippers are consolidating procurement onto digital freight exchanges that disintermediate traditional broker relationships. Small and mid-sized carriers are gaining direct access to contract freight through platform-based tendering. This pattern concentrates in automotive and consumer goods verticals with predictable lane density.
Germany Road Freight Transport Market Segmentation
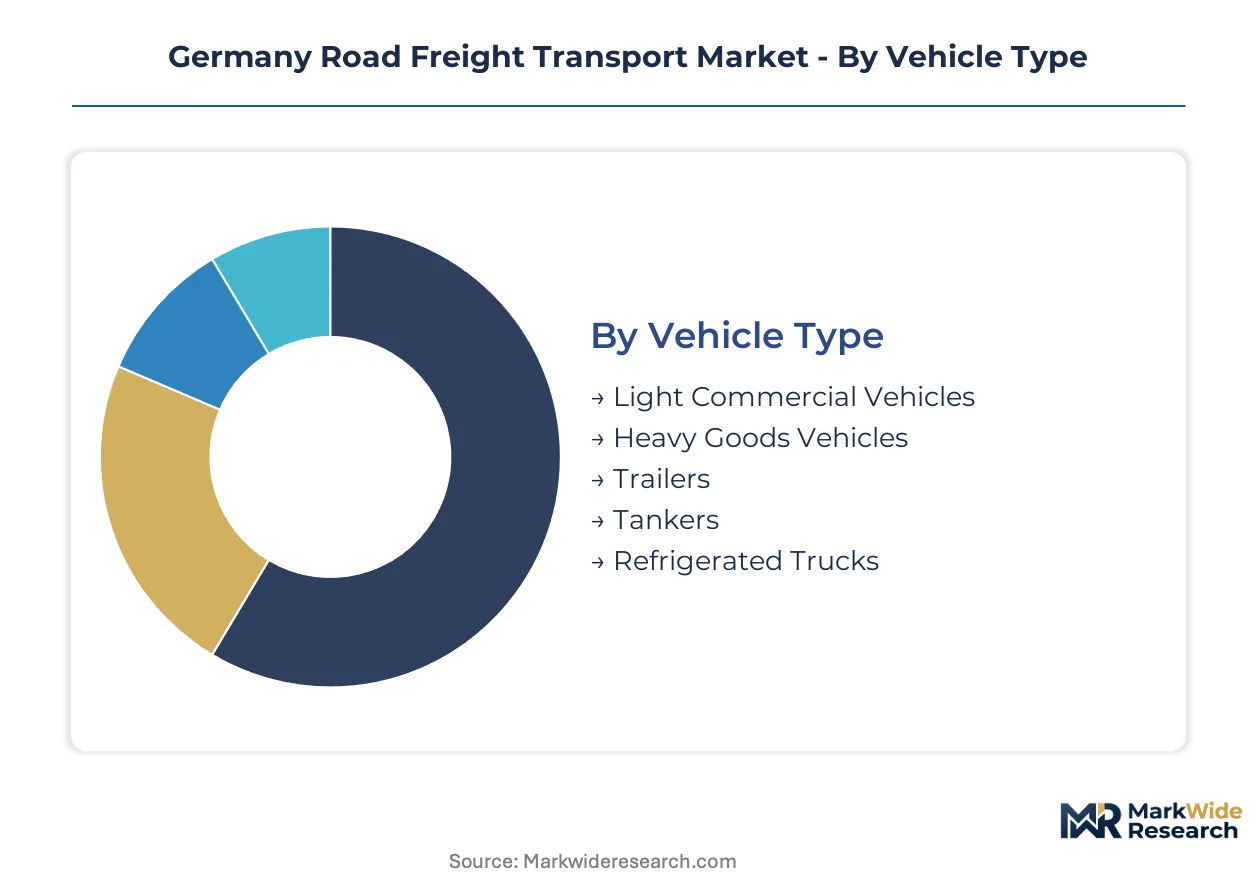
Segmentation in German road freight reveals how carrier economics diverge across asset classes and service configurations. Fleet composition and fuel technology choices now carry direct regulatory consequences under EU Green Deal mandates.
Vehicle Type:
After-sales service intensity varies dramatically across vehicle categories, with refrigerated units requiring continuous temperature system maintenance and heavy goods vehicles demanding specialized drivetrain expertise.
- Heavy Goods Vehicles:These 40-tonne articulated units dominate tonnage-moved metrics on autobahn corridors and Rhine-Ruhr industrial lanes. Manufacturing supply chains in Baden-Württemberg and Bavaria sustain the highest asset utilization rates for this segment.
- Refrigerated Trucks:Temperature-controlled chassis with integrated cooling systems command premium rate structures due to pharmaceutical and fresh food chain requirements. Biologics distribution from Frankfurt's pharmaceutical cluster drives specialized fleet investment here.
- Light Commercial Vehicles:3.5-tonne units serve urban last-mile delivery with lower capital barriers.
- Trailers:Interchangeable units enable flexible load matching across German carrier networks.
- Tankers:Specialized liquid and bulk cargo transport with chemical safety certification requirements.
By volume, Heavy Goods Vehicles leads. By growth pace, Refrigerated Trucks is expanding most quickly.
Service Type:
Cost tier differentiation separates premium expedited offerings from standardized scheduled services, with full truckload commanding rate premiums over consolidated less-than-truckload alternatives.
- Full Truckload:Dedicated vehicle allocation for single-shipper cargo maximizes route efficiency on high-density lanes. Automotive just-in-time supply chains between Stuttgart and Wolfsburg anchor demand concentration here.
- Less Than Truckload:Consolidated multi-shipper loads optimize asset utilization through terminal-based sorting networks. E-commerce fulfillment density in North Rhine-Westphalia sustains hub-and-spoke economics for this segment.
- Expedited Shipping:Time-definite delivery with guaranteed transit windows.
- Courier Services:Small parcel collection and delivery with high stop frequency.
- Door-to-Door Delivery:End-to-end shipment handling without intermediary terminals.
Full Truckload captures the largest revenue share. Less Than Truckload shows the steepest expansion trajectory from e-commerce procurement shifts.
Customer Type:
Application concentration determines lane predictability, with manufacturing firms offering contracted regularity while agricultural producers impose seasonal volatility on fleet planning.
- E-commerce Businesses:Online retail distribution centers generate sustained regional tonnage with high frequency, low weight characteristics. Fulfillment networks around Düsseldorf and Cologne reshape last-mile capacity requirements.
- Manufacturing Firms:Industrial supply chains demand synchronized inbound logistics with production schedules. Automotive OEMs in Lower Saxony and Bavaria anchor the most valuable contract freight relationships.
- Wholesale Distributors:Intermediate goods movement between production and retail tiers.
- Construction Companies:Project-based demand with heavy and oversized cargo requirements.
- Agricultural Producers:Seasonal harvest-driven transport with temperature-sensitive product flows.
Manufacturing Firms contributes the highest contract stability. E-commerce Businesses is gaining share fastest from fulfillment network expansion.
Fuel Type:
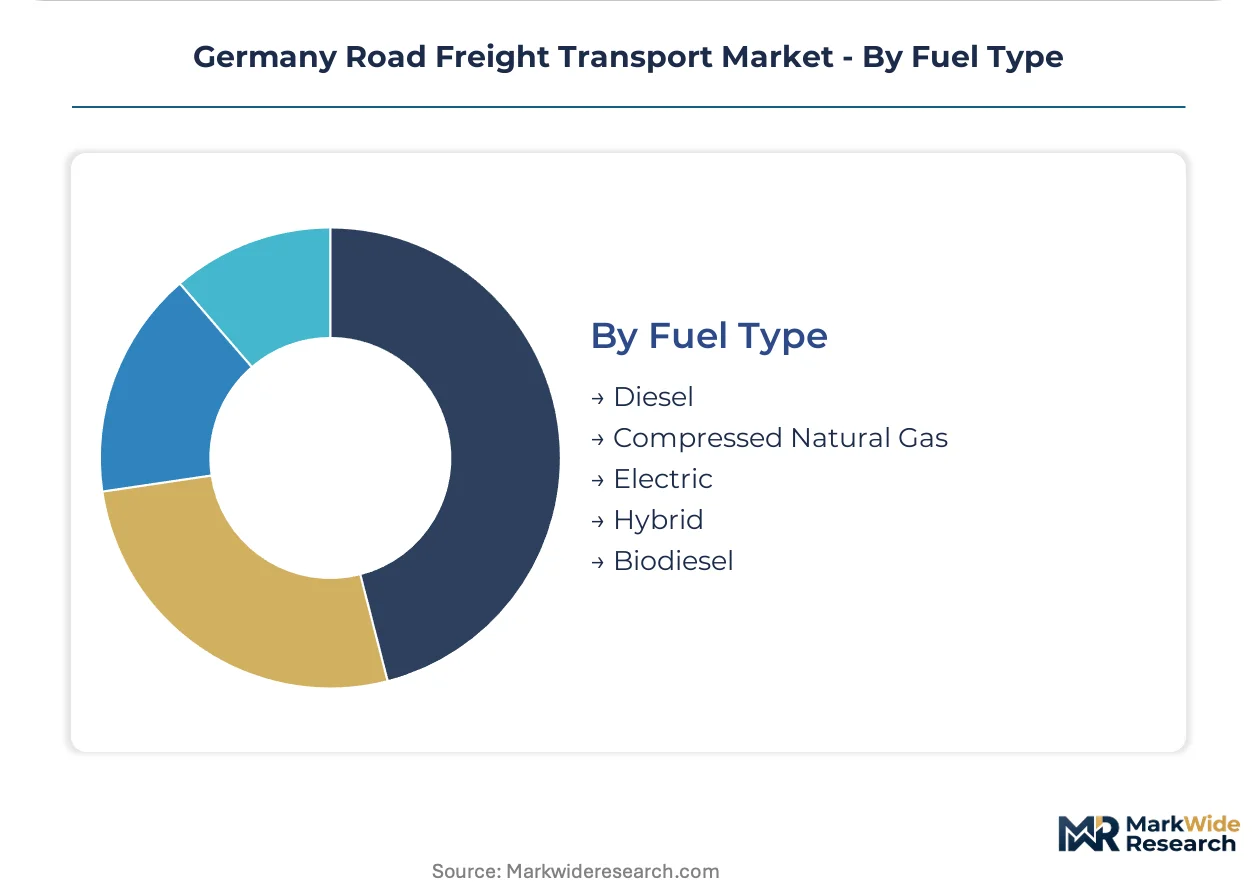
Technology maturity stages separate established diesel infrastructure from emerging electric powertrains, with total-cost-of-ownership calculations shifting as charging networks extend along priority corridors.
- Diesel:Conventional compression-ignition engines dominate existing fleet composition with mature refueling infrastructure. Legacy asset depreciation cycles now compress under EU Green Deal CO2 reduction mandates.
- Electric:Battery-electric powertrains attract fleet investment despite higher capital costs, driven by urban access restrictions in Berlin, Hamburg, and Munich zero-emission zones.
- Compressed Natural Gas:Lower-carbon fossil alternative with established European refueling corridors.
- Hybrid:Dual powertrain configurations bridging range and emissions requirements.
- Biodiesel:Renewable fuel drop-in compatible with existing diesel infrastructure.
Diesel retains the largest installed base. Electric climbs the fastest from regulatory compliance timelines and urban access incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's export-import balance drives disproportionate road freight intensity, with manufacturing supply chains generating sustained tonnage flows across federal borders and into neighboring European markets.
North Rhine-Westphalia
E-commerce fulfillment networks around Düsseldorf and Cologne generate sustained regional tonnage with high-frequency, low-weight characteristics. The EU Green Deal's CO2 standards for heavy-duty vehicles are accelerating fleet renewal decisions among Rhine-Ruhr corridor operators. Logistics density in the Cologne-Bonn-Düsseldorf triangle supports higher asset utilization rates than national averages.
Bavaria
Automotive OEM supply chains between Munich and Ingolstadt anchor contract freight relationships with synchronized inbound logistics requirements. Germany's national climate protection framework mandates progressive CO2 reductions that compress diesel fleet depreciation cycles. The Munich metropolitan area concentrates pharmaceutical distribution activity with temperature-controlled infrastructure investment.
Baden-Württemberg
Industrial machinery and automotive component manufacturing in Stuttgart and Mannheim sustain heavy goods vehicle demand on autobahn corridors. Kraftfahrt-Bundesamt driver hour regulations limit operational flexibility for just-in-time supply chains serving the region. The Stuttgart logistics cluster specializes in precision manufacturing freight with time-definite delivery requirements.
Lower Saxony
Volkswagen's Wolfsburg operations anchor automotive supply chain freight volumes with predictable lane density. The Bundesamt für Güterverkehr monitors cabotage compliance for international operators accessing northern ports. The Hanover-Braunschweig corridor concentrates intermodal terminals connecting road freight to Deutsche Bahn AG rail networks.
Hamburg
Port hinterland logistics generate container drayage demand with specialized chassis requirements for maritime cargo. Urban access restrictions in Hamburg's zero-emission zone are creating first-mover advantages for electrified last-mile fleets. The Hamburg metropolitan area serves as a northern gateway for Scandinavian trade flows.
Germany Road Freight Transport Market Competitive Landscape
On the supply side, the industry is consolidating around integrated logistics providers with cross-border network density, while specialized regional carriers defend niche positions through service differentiation. Three archetypes dominate: pan-European network operators with intermodal capabilities, pharmaceutical and automotive logistics specialists with temperature-controlled infrastructure, and last-mile delivery platforms serving e-commerce fulfillment density. Competitive intensity centers on fleet electrification timelines and digital freight matching capabilities.
Within the integrated logistics tier, DACHSER and DHL Group represent network density advantages across European road corridors. Deutsche Bahn AG occupies a distinctive position through rail-road intermodal offerings that compete with pure trucking on long-haul lanes. Among specialized operators, Kuehne+Nagel exemplifies the maritime-forwarding-integrated model serving German export-import flows.
| Leading Market Players |
|---|
| Kuehne+Nagel |
| Pabst Transport GmbH & Co. KG |
| DACHSER |
| DSV A/S (De Sammensluttede Vognmænd af Air and Sea) |
| Raben Group |
| Deutsche Bahn AG (including DB Schenker) |
| United Parcel Service of America, Inc. (UPS) |
| A.P. Moller - Maersk |
| DHL Group |
| Others |
Supply & Pricing Matrix
EU Green Deal CO2 compliance timelines compress fleet renewal cycles and simultaneously widen pricing spreads between electrified and diesel-heavy operators while forcing supply chain reconfiguration toward battery and hydrogen fuel cell sourcing corridors. Carrier balance sheets absorb stranded diesel asset risk as regulatory deadlines advance, concentrating pricing power among early electrification adopters with secured charging infrastructure access.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled rate tiers and just-in-time delivery premiums. Three-tier pricing structure across premium, standard, and economy levels separates dedicated fleet allocation from shared consolidation services and spot-market brokerage. Cost compression in standard-tier full truckload segments is intensifying because e-commerce fulfillment density attracts asset-heavy entrants. Small and mid-sized carriers serving spot markets exhibit highest price sensitivity, while pharmaceutical cold chain specialists command rate inelasticity through temperature-controlled certification.
Supply Chain Analysis
Dual-use battery technology export controls limiting flows from China, South Korea, and Japan constrain German carrier access to high-density energy storage systems for heavy-duty electrification. Powertrain manufacturing draws from lithium-ion cell production, rare earth magnet processing, and high-voltage inverter assembly. Single-source vulnerability concentrates in Chinese cathode material refining. Distribution runs through Tier 1 automotive supplier networks and specialized commercial vehicle dealerships with certified high-voltage service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
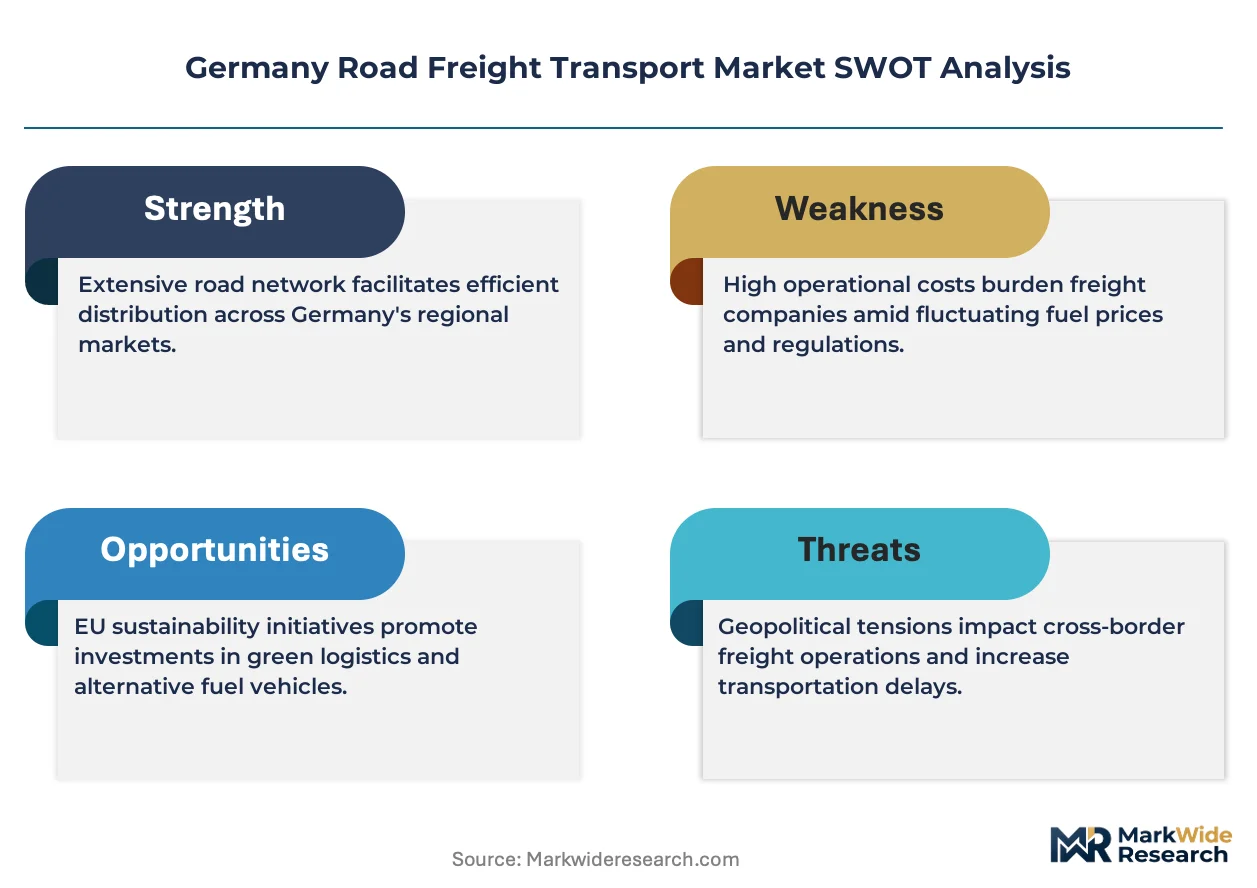
German road freight sits at a forced-technology inflection where EU Green Deal mandates are compressing diesel fleet economic life while electrification infrastructure buildout lags deployment requirements.
For Market Incumbents: Pre-empt regulatory stranding by accelerating electrified fleet deployment along Rhine-Ruhr charging corridors before competitor density erodes first-mover urban access privileges. Secure long-term power purchase agreements with renewable generators to lock in total-cost-of-ownership advantages against diesel price volatility. Deepen backward integration into charging infrastructure through partnerships with grid operators and energy retailers.
For New Entrants and Emerging Players: Pursue specialized last-mile electrification contracts in Hamburg, Berlin, and Munich zero-emission zones where incumbent diesel fleets face immediate access restrictions. Target pharmaceutical cold chain verticals with temperature-controlled electric vehicle offerings that command premium rate structures. Deploy direct shipper platform relationships to bypass traditional freight broker intermediaries in automotive and consumer goods lanes.
For Investors and Strategic Acquirers: EU Green Deal 2040 CO2 targets reshape the acquisition landscape by elevating carriers with secured charging infrastructure and certified electric fleet deployment over asset-heavy diesel operators. Long-term viability favors integrated logistics providers with intermodal rail access and pharmaceutical specialization capabilities. Monitor charging corridor buildout pace along A3, A5, and A7 autobahn routes as the critical inflection signal for electrification economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures high-power corridor access along A3 and A5 autobahn freight routes for electric fleet expansion. |
| Pharmaceutical Cold Chain Certification | Unlocks Frankfurt biologics distribution contracts with temperature-controlled infrastructure investment. |
| Rail-Road Intermodal Integration | Reduces driver hour exposure through Deutsche Bahn AG terminal access on long-haul lanes. |
| Digital Freight Platform Integration | Disintermediates traditional brokers through direct shipper matching in automotive verticals. |
| Renewable Power Purchase Agreement | Locks in electricity cost advantages against diesel price volatility for electric fleet operations. |
Research Methodology
The analysis maps heavy goods vehicle, refrigerated truck, and light commercial vehicle segments, each validated through fleet operations directors, logistics procurement managers at manufacturing OEMs, and charging infrastructure developers. Primary interviews with Kraftfahrt-Bundesamt compliance officers and Bundesamt für Güterverkehr market access specialists combined with secondary validation against EU Green Deal regulatory filings, autobahn freight traffic monitoring data, and carrier SEC disclosures. Bottom-up fleet deployment tracking and top-down tonnage-movement estimates triangulate market sizing.
Assumptions held EU Green Deal CO2 reduction curves and charging infrastructure buildout schedules fixed while varying e-commerce fulfillment density and driver availability scenarios across the projection horizon. Segmentation dimensions modeled include vehicle type, service configuration, fuel technology maturity, and regional logistics density. CAGRs derived from fleet replacement cycle analysis and tonnage growth correlation with industrial production indices. Forecast inputs incorporated battery-electric vehicle total-cost-of-ownership trajectories and urban access restriction implementation timelines.
Sensitivities concentrate around charging infrastructure deployment pace, battery cell supply availability, and driver hour regulation enforcement intensity. Forecasts reflect these assumptions with acknowledged revision triggers from regulatory deadline acceleration or technology cost breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market