
 Europe Road Feeder Services Market | 2026-2036
Europe Road Feeder Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Road Feeder Services Market Insights
Aftermarket fleet optimization revenue is tilting toward predictive maintenance and telematics subscriptions as operators seek to reduce empty-running penalties. DHL Group leverages its pan-European hub network to sustain high asset utilization across airport transfer lanes. Girteka anchors its position through dedicated trailer pools serving Central European air freight corridors. Rhenus differentiates via integrated customs brokerage bundled with cross-border feeder movements.
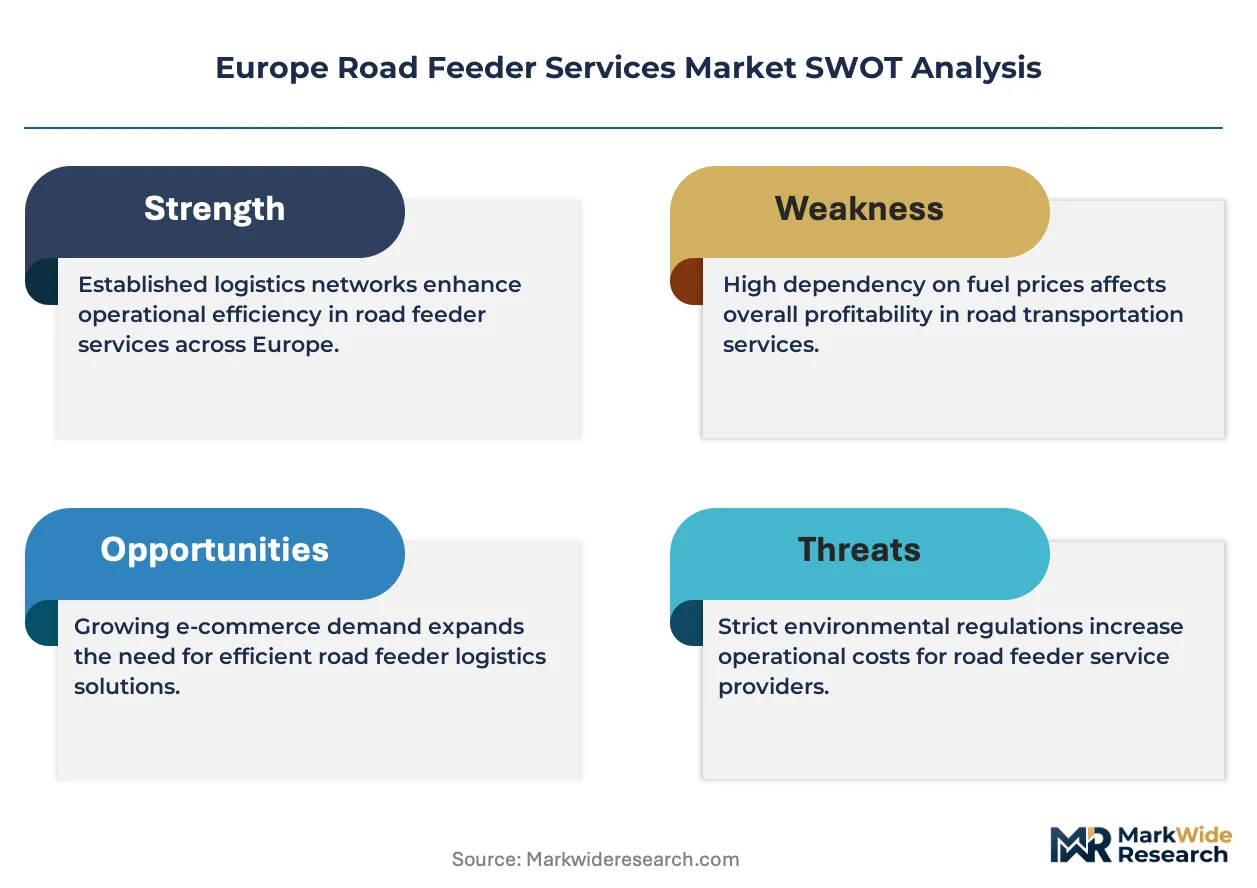
Europe road feeder services denote scheduled trucking operations that connect air cargo terminals with shippers, consignees, and intermodal transfer points, typically operating within fixed time windows synchronized to flight schedules and using vehicles ranging from 3.5-tonne vans to 40-tonne articulated combinations with roller-bed or wide-body container compatibility. These services function as the surface extension of air freight networks, enabling door-to-airport and airport-to-door cargo flows without direct airline involvement in ground distribution. Airport transfers command the largest volume share among service types, reflecting their role as the backbone connection between gateway hubs and regional spoke airports. E-commerce end users represent the fastest-expanding demand pool, driven by next-day delivery promises that require precise feeder timing. Medium-distance segments generate disproportionate margin contribution, as these lanes balance fuel efficiency against premium pricing for time-definite service.
The EU Green Deal and its delegated acts on heavy-duty vehicle CO2 standards, enforced by the European Commission in coordination with national transport authorities, mandate progressive emissions reductions that reshape fleet procurement timelines and total-cost-of-ownership calculations for feeder operators. Germany's KBA type-approval processes and France's ANSM-linked environmental certification requirements for commercial vehicles create compliance layers that favor operators with capital reserves for early fleet transition. Stakeholders must monitor the divergence between national subsidy schemes for zero-emission trucks and the actual charging infrastructure deployment pace along major feeder corridors to calibrate investment sequencing.
Market Dynamics
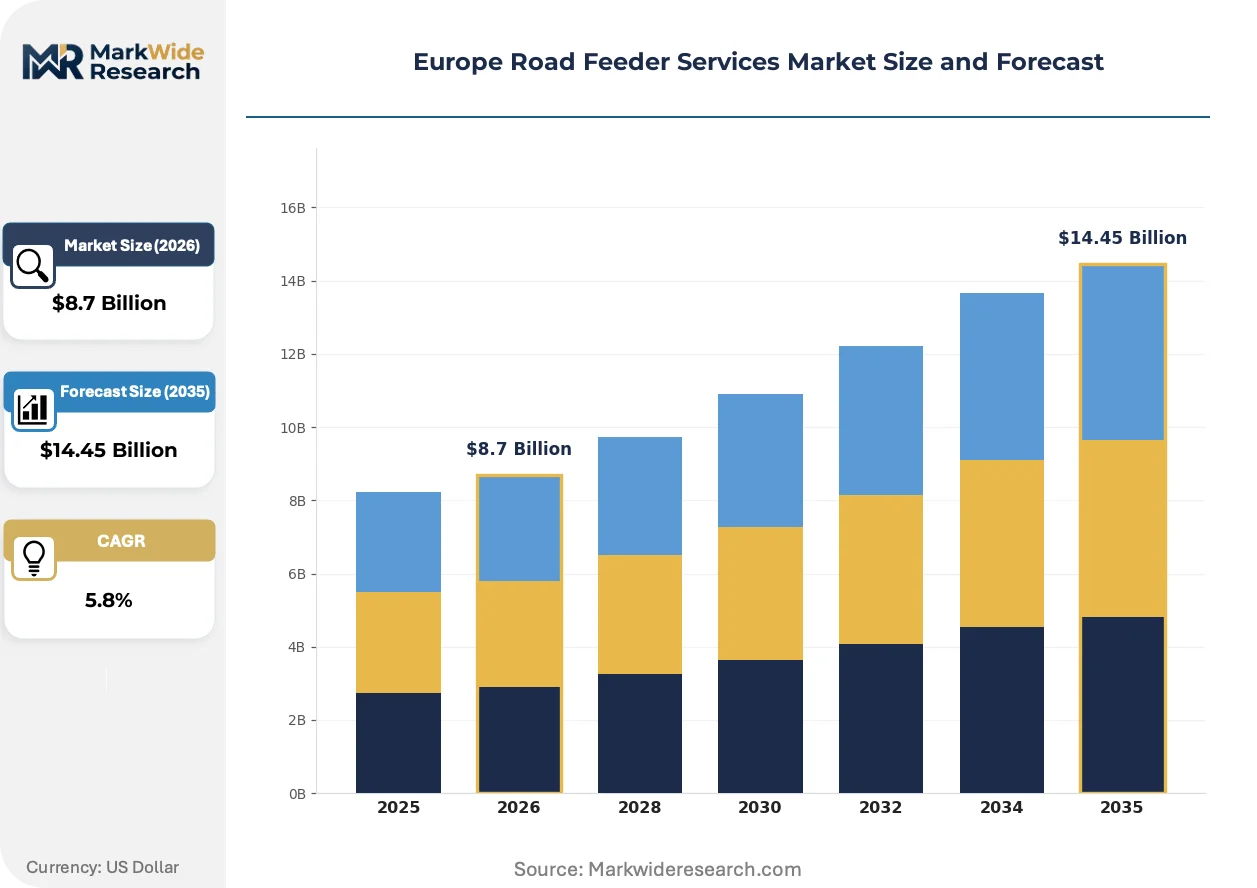
The EU Green Deal's heavy-duty vehicle CO2 standards are compressing fleet renewal cycles across European road feeder operators, forcing capital reallocation toward alternative drivetrains before charging infrastructure maturity.
Growth Catalysts
- E-commerce fulfillment density:Next-day delivery promises from online retailers are tightening synchronization requirements between air cargo hubs and regional distribution centers, expanding scheduled feeder volumes.
- EU Green Deal delegated acts:Progressive emissions mandates for commercial transport fleets are accelerating replacement demand for zero-emission vehicles among contracted logistics providers.
- Rhine-Ruhr corridor concentration:Multimodal connectivity density in Germany's logistics heartland supports high-frequency feeder operations that attract pharmaceutical and electronics shippers.
Market Restraints
- Battery electric vehicle total-cost-of-ownership uncertainty:Residual value risk and charging infrastructure gaps along cross-border corridors inflate depreciation assumptions for fleet managers.
- Driver availability constraints:Professional license acquisition bottlenecks in Germany and France limit operational scaling regardless of equipment investment.
- Airport slot coordination rigidity:Fixed flight schedules compress ground handling windows, reducing flexibility for road feeder operators to optimize load consolidation.
Strategic Opportunities
- Poland-Czech Republic manufacturing corridors:Underdeveloped scheduled feeder links between Central European production zones and Frankfurt, Amsterdam, and Paris air hubs represent whitespace for frequency-based service launches.
- Predictive maintenance telematics:Sensor-enabled fleet optimization creates recurring revenue streams through subscription models that reduce empty-running penalties for operators.
- EU Alternative Fuels Infrastructure Regulation:Mandated charging and hydrogen refueling deployment along core transport corridors will de-risk electric truck procurement for early-mover feeder fleets.
Industry Challenges
- Cross-border customs brokerage integration:Post-Brexit documentation complexity and varying national enforcement interpretations of EU customs code create operational friction for UK-EU feeder movements.
- Legacy trailer pool incompatibility:Roller-bed and wide-body container handling systems require coordinated capital replacement across shipper and operator fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Road Feeder Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airport Transfers, Inter-terminal Transport, Last Mile Delivery, Cargo Handling End User: Airlines, Freight Forwarders, Logistics Providers, E-commerce Distance: Short Distance, Medium Distance, Long Distance, Express Vehicle Type: Vans, Trucks, Trailers, Buses |
| Companies Covered | DHL Group, DSV A/S, Kuehne + Nagel, Dachser, DB Schenker, XPO, Girteka, Rhenus, Ninatrans, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Road Feeder Services Market Trends and Innovations
Digital freight matching platforms and electrification hardware are converging to reshape asset utilization models across European airport transfer corridors, compressing the traditional boundaries between scheduled and on-demand road feeder operations.
Telematics-enabled predictive maintenance is collapsing the information lag between vehicle health monitoring and maintenance scheduling. Pharmaceutical and electronics shippers with temperature-sensitive cargo are adopting these systems fastest, demanding real-time visibility that compresses service-level agreement negotiations toward outcome-based uptime guarantees rather than equipment-age specifications.
The EU Green Deal's delegated acts on heavy-duty vehicle CO2 standards are mandating 15% emissions reductions by 2025 and 30% by 2030 against 2019 baselines. Fleet procurement timelines are compressing as operators front-load electric and hydrogen truck orders to secure limited production slots from manufacturers. Germany's KBA type-approval processes and France's ANSM-linked environmental certification requirements are creating compliance layering that favors capital-reserved operators.
Shipper procurement patterns are rotating toward integrated door-to-door liability structures that bundle air and surface movements under single-carrier accountability. Electronics manufacturers with just-in-time supply chains are displacing fragmented multi-vendor arrangements with contracted feeder networks that absorb inventory risk. This consolidation is most visible in the Netherlands and Belgium, where Schiphol and Brussels Airport cargo communities have institutionalized integrated service tenders.
Europe Road Feeder Services Market Segmentation
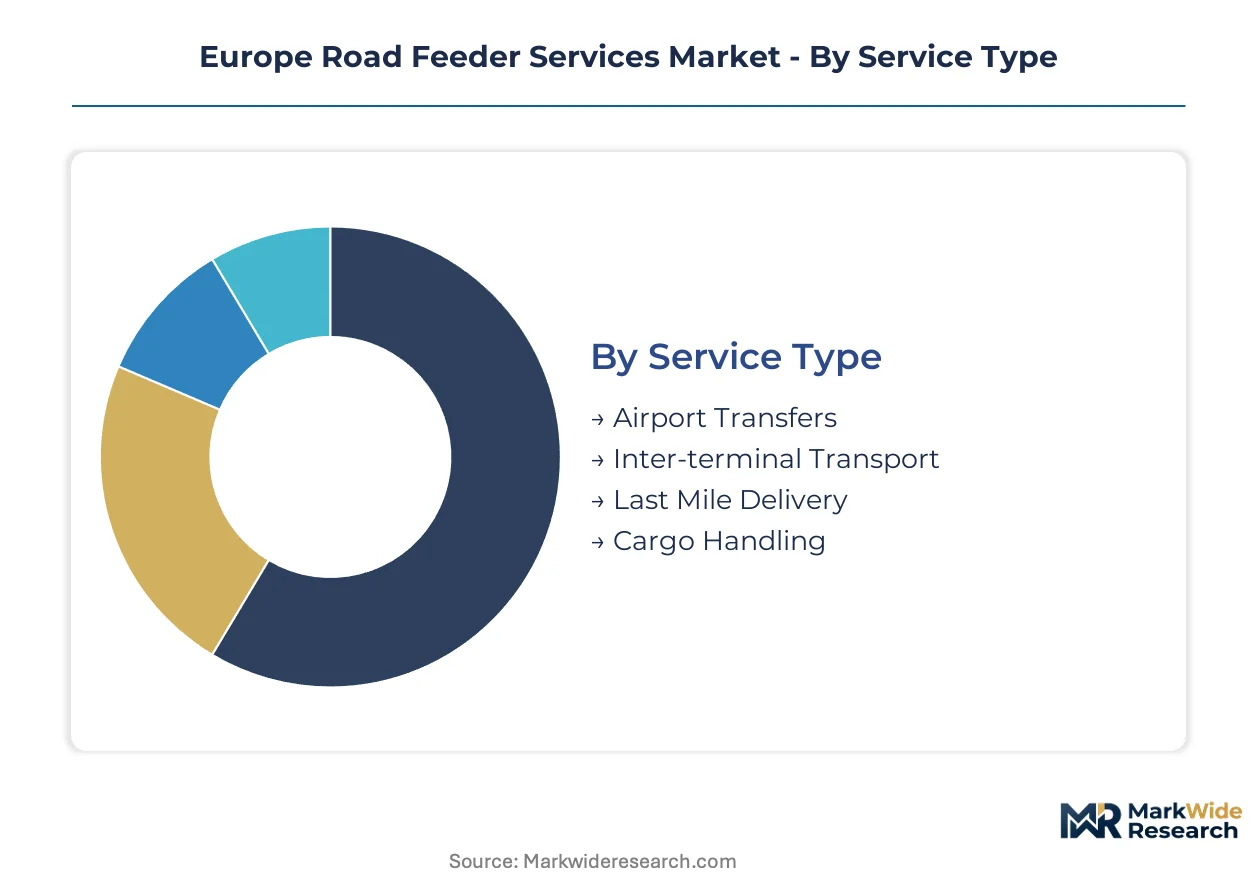
Segmentation in Europe road feeder services reveals how operational specialization aligns with divergent shipper requirements across time-definite logistics. Each dimension—service type, end user, distance, and vehicle—carries distinct margin profiles and capital intensity that shape competitive positioning.
Service Type:
Mature scheduled operations dominate revenue concentration while emerging digital-enabled services are gaining frequency share.
- Airport Transfers:Scheduled trucking between gateway hubs and regional spoke airports using roller-bed trailers synchronized to flight schedules. Germany's Rhine-Ruhr corridor generates the densest demand for these time-critical connections, driven by pharmaceutical and electronics shippers requiring precise handoffs.
- Inter-terminal Transport:Cross-dock movements between co-located cargo terminals at major hubs like Frankfurt and Amsterdam. Belgium and the Netherlands concentrate procurement here as integrated air-ground contracts displace fragmented vendor arrangements.
- Last Mile Delivery:Final-leg distribution from regional airports to consignee facilities, typically using smaller vans for urban access constraints.
- Cargo Handling:Ancillary services including container drayage, pallet build-up, and temporary storage within airport perimeters.
Airport transfers handle the majority of throughput; last mile delivery is expanding most quickly on share.
End User:
Customer type determines contract structure, with asset-heavy operators preferring long-term airline agreements while forwarders seek flexible spot capacity.
- Freight Forwarders:Non-asset-based intermediaries purchasing scheduled capacity to extend their door-to-door service portfolios. Forwarders in the Netherlands and Belgium are consolidating procurement toward fewer, larger feeder contractors to reduce coordination overhead.
- E-commerce:Online retailers and their fulfillment operators demanding next-day delivery synchronization between air hubs and regional distribution centers. Poland and Czech Republic manufacturing zones are emerging as the steepest expansion trajectory for this segment.
- Airlines:Carriers outsourcing surface distribution to maintain flight schedule integrity without direct truck fleet investment.
- Logistics Providers:Integrated operators bundling feeder services with warehousing, customs brokerage, and value-added processing.
Freight forwarders anchor volume commitment; e-commerce is climbing the fastest on share.
Distance:
Lane length directly correlates with fuel efficiency optimization and pricing power, creating distinct competitive arenas.
- Medium Distance:Corridors between 150-400 kilometers balancing fuel economy against premium time-definite pricing. France's ANSM-linked certification requirements favor established operators with capital reserves for compliant fleet renewal on these high-margin lanes.
- Express:Premium-priced movements with sub-four-hour delivery windows, often operating outside standard traffic restrictions. Germany's KBA type-approval processes for specialized equipment concentrate supply among early movers with zero-emission vehicle commitments.
- Short Distance:Urban and peri-urban connections under 150 kilometers where congestion and access restrictions dominate operational design.
- Long Distance:Cross-border corridors exceeding 400 kilometers where driver hour regulations and overnight staging complexity inflate cost structures.
Medium distance generates disproportionate margin contribution; express is gaining share fastest.
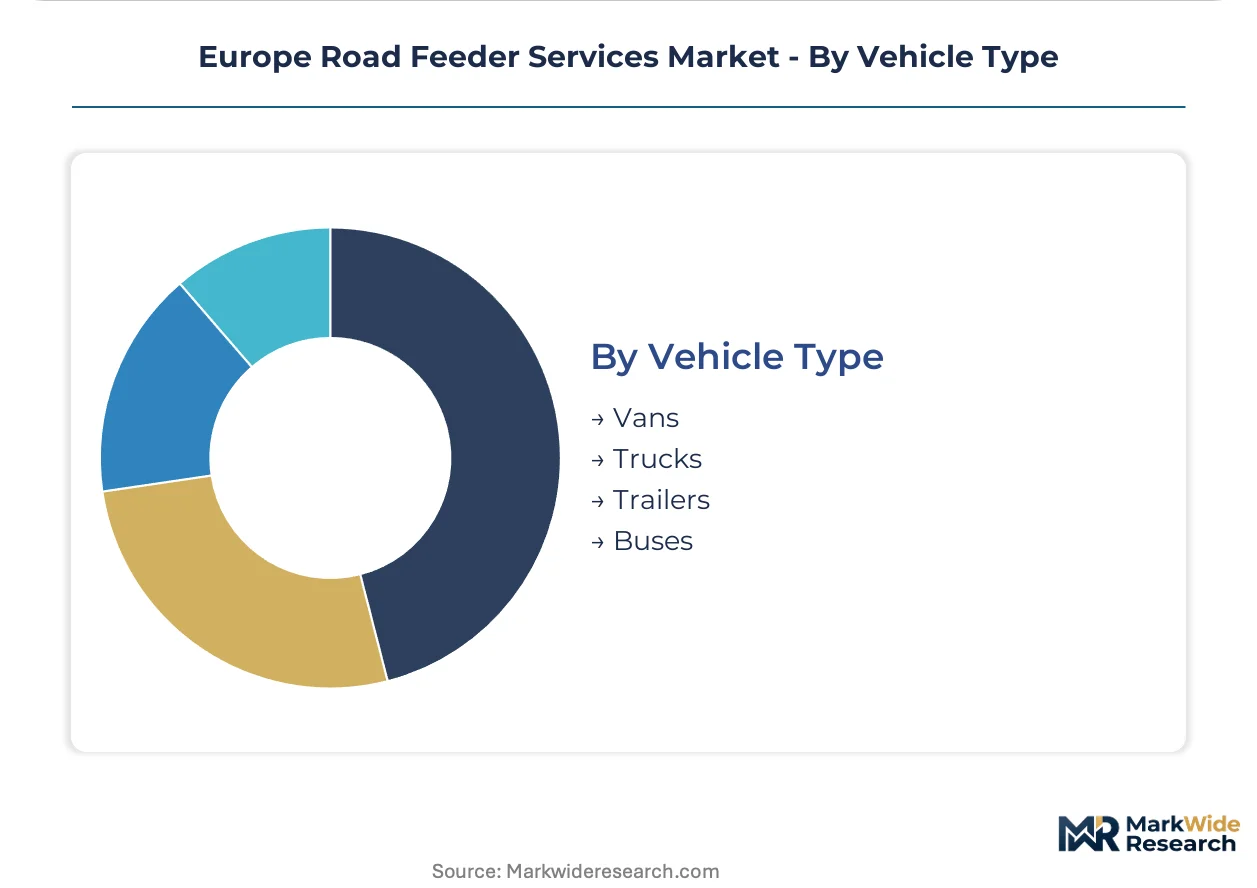
Vehicle Type:
Equipment specification follows cargo compatibility requirements and EU Green Deal compliance timelines.
- Trailers:Roller-bed and wide-body container-compatible units enabling rapid transfer of air cargo ULDs. Germany's fleet renewal mandates under EU heavy-duty CO2 standards are compressing procurement timelines for these high-asset items.
- Trucks:Articulated combinations from 18-40 tonnes forming the backbone of scheduled feeder networks. Battery electric variants face residual value uncertainty until charging infrastructure deployment along core corridors matures.
- Vans:3.5-tonne vehicles for last-mile access and restricted airport zones where larger equipment faces operational limits.
- Buses:Converted or purpose-built units for crew transport and limited document/courier movements, a marginal category in pure cargo terms.
Trailers represent the fixed asset base; trucks face the steepest technology transition pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the region. German and Dutch buyers prioritize schedule reliability over rate competition, while operators in Poland and Czech Republic face acute margin pressure from fragmented forwarder procurement.
Germany
The Rhine-Ruhr corridor generates Europe's densest scheduled feeder volumes, driven by pharmaceutical and electronics shippers demanding precise airport synchronization. The KBA enforces type-approval processes for zero-emission commercial vehicles that compress fleet procurement timelines. Frankfurt Airport's cargo community anchors high-frequency connections to regional spoke airports across North Rhine-Westphalia.
Netherlands
Schiphol's integrated air-ground contracts displace fragmented vendor arrangements as electronics manufacturers consolidate procurement. The EU Green Deal's delegated acts on heavy-duty CO2 standards accelerate replacement demand for battery electric trucks serving Amsterdam-rotterdam corridors. The Randstad logistics cluster concentrates multimodal investments linking port and airport feeder networks.
France
Paris Charles de Gaulle's cargo terminals drive express feeder demand from luxury goods and aerospace suppliers with sub-four-hour delivery windows. ANSM-linked environmental certification requirements for commercial vehicles create compliance layering favoring capital-reserved operators. The Île-de-France region hosts the steepest consolidation of integrated customs brokerage with cross-border feeder movements.
Poland
Manufacturing zones around Warsaw and Łódź generate underdeveloped scheduled feeder links to Frankfurt and Amsterdam air hubs. National subsidy schemes for zero-emission trucks diverge from actual charging infrastructure deployment pace along major corridors. The Central European production belt represents whitespace for frequency-based service launches targeting e-commerce fulfillment networks.
Belgium
Brussels Airport's cargo community institutionalizes integrated service tenders bundling air and surface movements. REACH compliance documentation requirements for chemical shipments filter feeder operator selection toward established customs brokerage specialists. The Antwerp-Brussels logistics axis supports high-asset utilization through dedicated trailer pools serving pharmaceutical temperature-controlled corridors.
Europe Road Feeder Services Market Competitive Landscape
Capability concentration sits with integrated logistics providers possessing customs brokerage depth; scale advantage sits with pan-European network operators with dense hub coverage. The market structure tilts toward consolidation as shipper procurement rotates toward single-carrier accountability structures. Three archetypes dominate: integrated door-to-door liability bundlers, frequency-based scheduled network operators, and digital-enabled freight matching platforms. Competitive moves concentrate on fleet electrification sequencing and predictive maintenance telematics deployment.
Among Germany-based integrated operators, DHL Group and DB Schenker exemplify the scale-driven archetype through pan-European hub networks sustaining high asset utilization. Rhenus occupies a position within the customs-bundled tier, differentiated by cross-border brokerage integration. These three represent how capital reserves and compliance layering favor early fleet transition under EU Green Deal mandates.
| Leading Market Players |
|---|
| DHL Group |
| DSV A/S |
| Kuehne + Nagel |
| Dachser |
| DB Schenker |
| XPO |
| Girteka |
| Rhenus |
| Ninatrans |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal compliance layering as a regulatory chokepoint determines both pricing tier spreads and supply chain shape, compressing fleet procurement timelines for capital-reserved operators while fragmenting procurement access for undercapitalized carriers across Rhine-Ruhr and Poland-Czech corridors.
Pricing Analysis
Long-term contracted offtake agreements dominate pricing structures for scheduled airport transfers, with pharmaceutical and electronics shippers absorbing premium rates for time-definite service guarantees. Price differentiation hinges on fleet emissions certification tier under EU heavy-duty CO2 standards and after-sales predictive maintenance bundling. Cost compression in medium-distance lanes is intensifying because forwarder procurement consolidation demands volume discounts. E-commerce fulfillment operators exhibit the highest price sensitivity, while pharmaceutical shippers prioritize schedule reliability over rate competition.
Supply Chain Analysis
Extended payment terms from integrated logistics providers to trailer manufacturers are compressing working capital cycles across Germany, Netherlands, and Poland production zones. Equipment supply concentrates in German and Czech manufacturing clusters, with roller-bed trailer fabrication drawing from steel coil suppliers and hydraulic component specialists. Single-source vulnerability sits with battery electric drivetrain suppliers facing production slot constraints. Distribution runs through pan-European hub networks anchored by Frankfurt, Amsterdam, and Paris air cargo terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's progressive emissions mandates constitute a high-growth disruption, compressing fleet renewal cycles and reconstituting competitive advantage around zero-emission vehicle procurement timelines.
For Market Incumbents: Entrench market position through accelerated backward integration into charging infrastructure partnerships along core feeder corridors and captive trailer pool expansion in Germany's Rhine-Ruhr logistics belt. DHL Group and DB Schenker exemplify this trajectory through pan-European hub density that absorbs inventory risk from pharmaceutical shippers. The threat of digital freight matching platforms demands predictive maintenance telematics deployment to lock in recurring revenue streams. For New Entrants and Emerging Players: Poland-Czech Republic manufacturing corridors represent the steepest underpenetration for frequency-based scheduled feeder links to Frankfurt and Amsterdam air hubs. White-space targets include e-commerce fulfillment networks demanding next-day delivery synchronization and temperature-controlled pharmaceutical movements from Warsaw and Łódź production zones. A digital-native go-to-market angle bundling real-time visibility with customs brokerage integration bypasses incumbent asset-heavy positioning. For Investors and Strategic Acquirers: The EU Alternative Fuels Infrastructure Regulation reshapes the acquisition landscape by de-risking electric truck procurement for early-mover feeder fleets with corridor-specific charging deployment commitments. Long-term viability over a multi-year window favors integrated operators possessing customs brokerage depth and pan-European network density. The signal to watch is divergence between national zero-emission truck subsidy schemes and actual charging infrastructure deployment pace along major feeder corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Sequencing | Front-loaded battery electric truck orders secure limited manufacturer production slots ahead of EU CO2 mandate deadlines. |
| Predictive Maintenance Telematics Deployment | Sensor-enabled uptime guarantees reduce empty-running penalties and create recurring subscription revenue from pharmaceutical shippers. |
| Customs Brokerage Integration | Post-Brexit documentation complexity filters procurement toward operators bundling cross-border clearance with feeder movements. |
| Corridor-Specific Charging Infrastructure Partnership | EU Alternative Fuels Infrastructure Regulation mandates de-risk electric truck total-cost-of-ownership for early movers. |
| Trailer Pool Expansion | Dedicated roller-bed and wide-body container-compatible units enable rapid ULD transfer synchronized to flight schedules. |
Research Methodology
The analysis maps airport transfers, inter-terminal transport, last-mile delivery, and cargo handling segments, each validated through fleet operations directors, airline cargo procurement managers, freight forwarder contracting leads, and customs brokerage specialists. Primary interviews with these stakeholders combined with secondary validation from EU transport authority emissions filings, KBA type-approval databases, airport cargo throughput statistics, and logistics operator sustainability disclosures. Bottom-up service volume estimates and top-down market sizing triangulate across the projection horizon.
Assumptions held fixed include EU Green Deal CO2 reduction trajectories and charging infrastructure deployment schedules per the Alternative Fuels Infrastructure Regulation, while fuel price volatility and battery technology cost curves were varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, end-user vertical, distance band, and vehicle specification. CAGRs derive from trend extrapolation calibrated against fleet renewal cycle compression and e-commerce fulfillment density expansion. Industry-specific inputs include pharmaceutical temperature-control compliance rates and electronics just-in-time supply chain synchronization requirements.
The forecast holds incumbent behavior within observed patterns; aggressive fleet electrification moves by capital-resourced integrated logistics providers would shift competitive outcomes. Macroeconomic deviation, regulatory enforcement variance across member states, or breakthrough battery technology adoption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Transportation Aggregators Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market