
 Thailand Road Freight Transport Market | 2026-2036
Thailand Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Road Freight Transport Market Analytics
Last-mile delivery revenue is fragmenting between dedicated fleet operators and platform-based intermediaries. SCG Logistics leverages its cement-and-building-materials heritage to anchor heavy-freight corridors across Thailand's eastern seaboard. Kerry Logistics competes through cross-border connectivity into Cambodia, Laos, Myanmar, and Vietnam. DHL Group extends its pharmaceutical cold-chain certification to capture temperature-controlled road freight from Bangkok's growing biomedical zone.
Road freight transport encompasses the movement of goods via motor vehicles over paved highway networks, typically involving payloads from one ton in light commercial vans to forty tons in heavy-duty tractor-trailers with diesel or compressed-natural-gas powertrains. The activity serves as the dominant domestic logistics mode for manufacturers, retailers, and agricultural exporters requiring point-to-point flexibility that rail or water cannot match. Full Truck Load services dominate volume on the Bangkok-Laem Chabang corridor where automotive parts and electronics move in scheduled loops. Less Than Truck Load operations are gaining share among small and medium enterprises in provincial retail networks. Third-Party Logistics providers now control the largest margin pool by bundling warehousing, customs brokerage, and fleet management under single contracts.
Thailand's Department of Land Transport enforces axle-load limits and commercial-driver certification that shape fleet renewal cycles and insurance costs. The Excise Department's differential taxation on Euro 4 versus Euro 5 engines is accelerating diesel-truck replacement. The country's national environmental regulator pushes emission testing at provincial checkpoints, tightening market access for older vehicles. Stakeholders must monitor whether carbon-border adjustment mechanisms in European export destinations will force Thai road carriers to adopt verified emissions tracking.
Market Dynamics
The Thai road freight sector is reorienting around the Eastern Economic Corridor's tax-incentive zones, which redirect cargo corridors from Bangkok's congested industrial ring toward Chonburi and Rayong provinces. Fleet operators face simultaneous pressure from Euro 5 emission mandates and the automotive sector's just-in-time delivery requirements.
Growth Catalysts
- Eastern Economic Corridor incentives:Board of Investment privileges for logistics operators establishing hubs in Rayong and Chonburi attract third-party logistics investment and expand bonded warehouse networks.
- Electronics manufacturing outsourcing:Thai contract manufacturers building regional supply hubs generate scheduled full-truckload demand between industrial estates and Laem Chabang port.
- Compressed natural gas infrastructure:PTT's expanding CNG station network along Highway 7 enables dual-fuel fleet conversions that reduce fuel cost exposure for heavy-freight operators.
Market Restraints
- Driver certification bottlenecks:Department of Land Transport commercial licensing requirements create recruitment friction and wage inflation for qualified heavy-vehicle operators.
- Axle-load enforcement variance:Inconsistent provincial checkpoint implementation of weight limits distorts competitive positioning between compliant and non-compliant fleet operators.
- Cross-border documentation complexity:ASEAN single-window implementation gaps at Thai-Lao and Thai-Myanmar checkpoints delay transit times for Mekong corridor freight.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Bangkok's biomedical zone growth creates demand for temperature-validated road freight with GDP compliance certification.
- Last-mile platform integration:E-commerce fulfillment networks in provincial retail centers offer white space for dedicated fleet operators to disintermediate traditional distributor channels.
- Carbon-border adjustment preparation:European export destination requirements for verified emissions tracking position early-adopter Thai carriers for preferential shipper contracts.
Industry Challenges
- Telematics integration with legacy fleet:Older diesel tractors lack OBD-II compatibility for real-time fuel and emissions monitoring required by corporate shipper sustainability programs.
- Multi-temperature cargo handling:Food processing exporters demand simultaneous frozen, chilled, and ambient compartments that strain refrigerated trailer availability and driver training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Road Freight Transport Market |
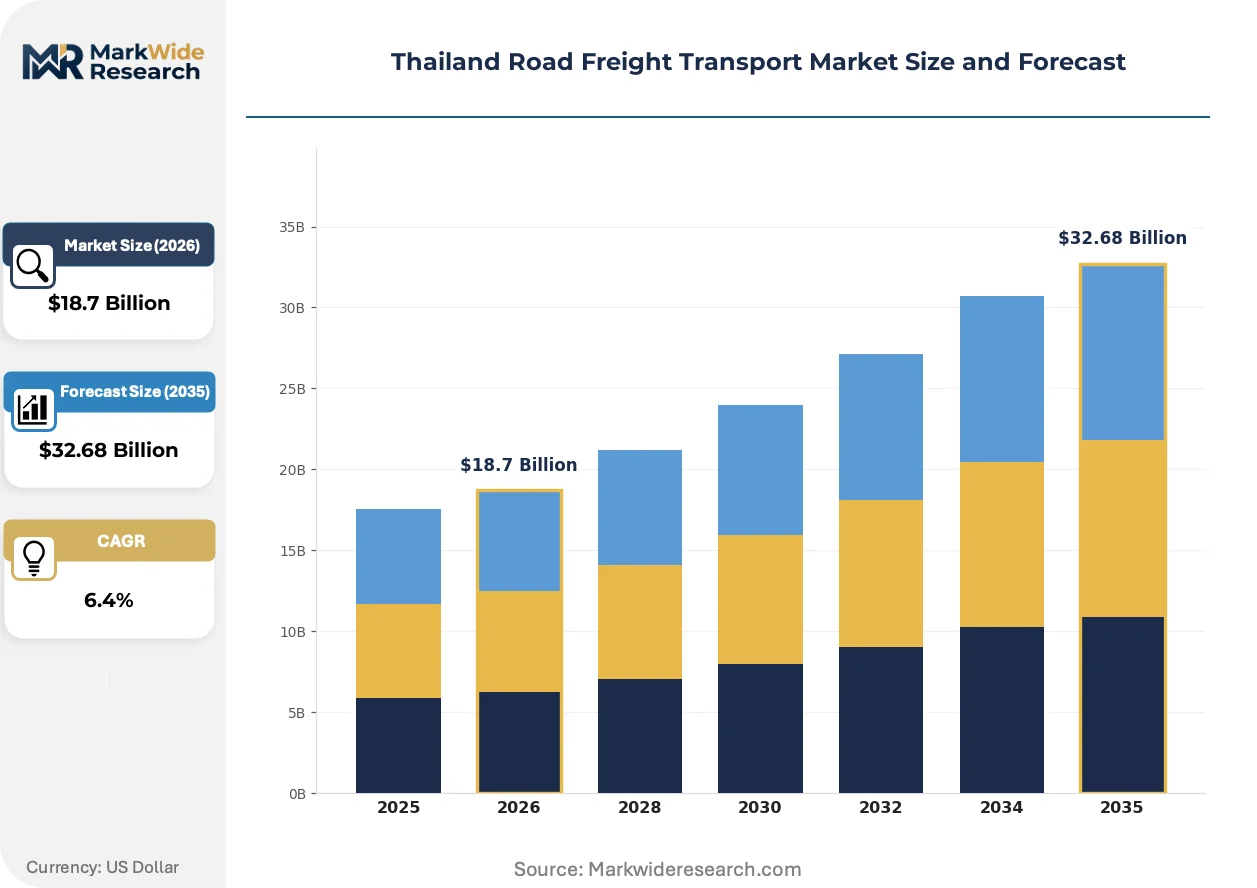
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Dedicated Transportation, Freight Brokerage Vehicle Type: Trucks, Vans, Trailers, Flatbeds End User: Retail, Manufacturing, Agriculture, Construction Distribution Channel: Direct Sales, Third-Party Logistics, Online Platforms, Freight Brokers |
| Companies Covered | DHL Group, SCG Logistics, JWD Group, Kerry Logistics, DB Schenker, Kuehne + Nagel, XPO Logistics, Yusen Logistics, Linfox Pty Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Road Freight Transport Market Evolving Landscape
Telematics and alternative powertrains are restructuring fleet economics while regulatory pressure on emissions intensifies compliance requirements. These shifts favor operators with capital discipline and technical integration capabilities.
Telematics platforms integrating GPS, fuel sensors, and driver behavior analytics are hybridizing fleet management from reactive dispatch into predictive asset deployment. Large automotive parts shippers now mandate real-time visibility as a contract condition. This convergence compresses margins for operators lacking digital infrastructure while creating data monetization opportunities for platform-integrated carriers.
The Excise Department's differential taxation between Euro 4 and Euro 5 diesel engines accelerates tractor replacement cycles. Heavy-freight operators serving Laem Chabang automotive corridors face compressed payback calculations on new equipment purchases. Provincial emission testing checkpoints operated by the national environmental regulator increasingly bar older vehicles from industrial estate access.
Shippers in Bangkok's industrial ring are consolidating vendor relationships toward integrated logistics providers bundling warehousing, customs brokerage, and dedicated fleet capacity. Small and medium enterprises in provincial retail networks respond by aggregating less-than-truckload volumes through digital freight matching platforms. This behavioral shift is most visible in Chiang Mai and Khon Kaen distribution corridors where traditional distributor networks face disintermediation pressure.
Thailand Road Freight Transport Market Segmentation
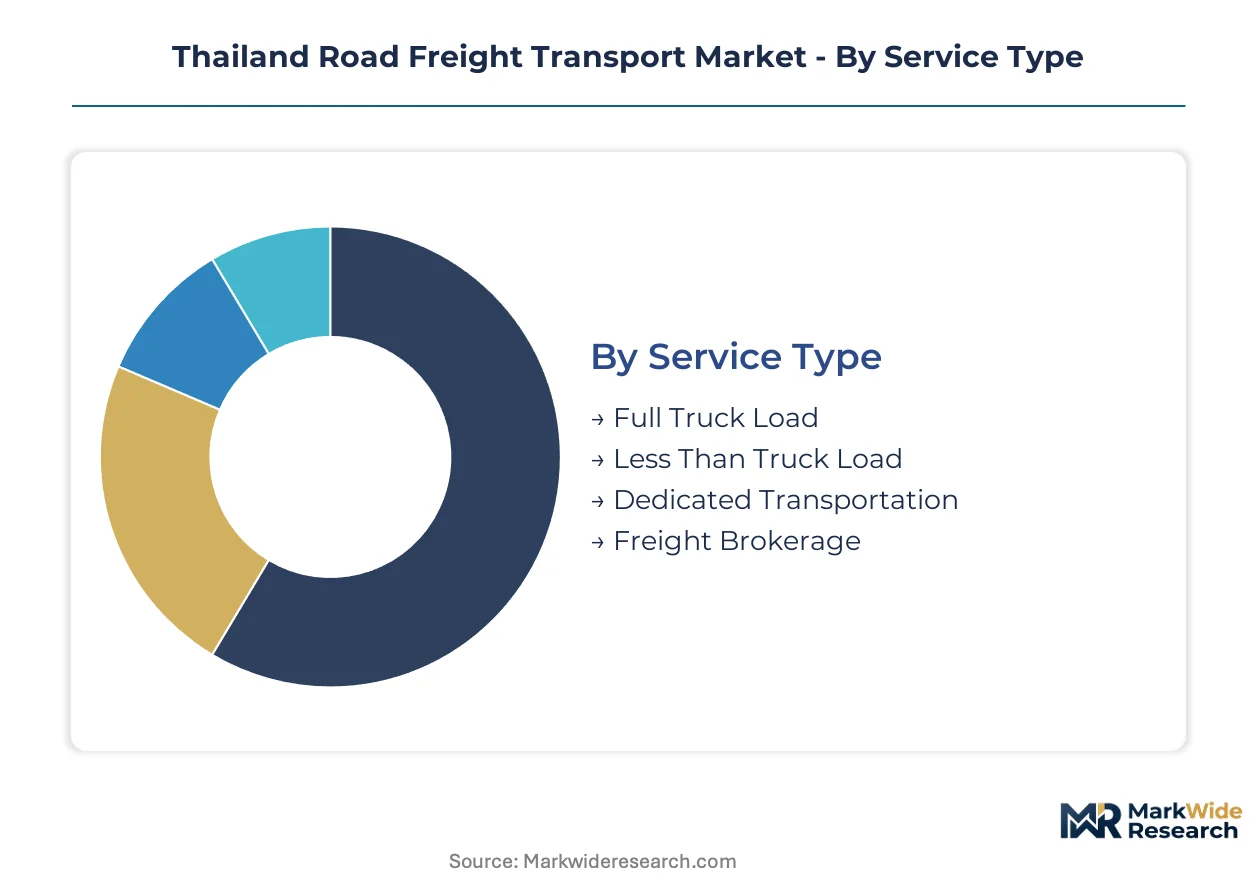
Road freight segmentation in Thailand reveals distinct operational economics across service models and asset types. Fleet operators prioritize segments based on cargo density, route predictability, and regulatory compliance burdens.
Service Type:
Full Truck Load contracts turn over fastest with daily or multi-day cycles, while Dedicated Transportation agreements lock capacity for months or years. Less Than Truck Load and Freight Brokerage occupy intermediate positions with weekly to monthly booking patterns.
- Full Truck Load:Scheduled point-to-point movement utilizing entire vehicle capacity for single-shipper cargo. Demand concentrates along the Bangkok-Laem Chabang corridor where automotive parts and electronics move in synchronized loops tied to manufacturing schedules.
- Less Than Truck Load:Consolidated shipments from multiple shippers sharing trailer space, typically under palletized configurations. Provincial retail networks in Chiang Mai and Khon Kaen drive expansion as small and medium enterprises aggregate volumes through digital freight matching platforms.
- Dedicated Transportation:Captive fleet allocation for single-shipper exclusive use under multi-year contracts.
- Freight Brokerage:Intermediary matching of shipper demand with available carrier capacity without asset ownership.
Full Truck Load dominates installed base. Less Than Truck Load is where expansion concentrates.
Vehicle Type:
Cost tier separation runs from premium refrigerated trailers through standard dry vans to economy flatbed configurations. Euro 5 emission mandates compress payback calculations most severely for heavy tractor-trailer combinations.
- Trucks:Heavy-duty diesel or compressed-natural-gas tractors pulling various trailer types, typically 6x4 or 6x2 axle configurations rated for forty-ton gross combinations. The Eastern Economic Corridor's bonded warehouse networks and Laem Chabang port linkages anchor demand for heavy-freight tractors.
- Trailers:Detachable cargo units including dry vans, refrigerated units, and specialized tank configurations. Food processing exporters in Bangkok's industrial ring drive multi-temperature specifications requiring simultaneous frozen, chilled, and ambient compartments.
- Vans:Light commercial vehicles under three-and-a-half tons gross vehicle weight for last-mile distribution.
- Flatbeds:Open-deck trailers for oversized or non-containerized cargo including construction materials and machinery.
Trucks command the highest asset values per unit. Trailers are where fleet expansion concentrates.
End User:
Application-based segmentation separates time-critical manufacturing flows from seasonal agricultural movements and project-based construction logistics. Each vertical imposes distinct equipment specifications and driver certification requirements.
- Manufacturing:Just-in-time component delivery and finished goods distribution for automotive, electronics, and food processing sectors. Rayong and Chonburi industrial estates generate the densest demand corridors as contract manufacturers build regional supply hubs.
- Retail:Inventory replenishment for hypermarkets, convenience chains, and e-commerce fulfillment centers. Provincial distribution centers face disintermediation pressure from platform-based last-mile operators.
- Agriculture:Seasonal movement of fresh produce, rubber, and palm oil from plantation to processing or export.
- Construction:Project-logistics for cement, steel, and building materials with irregular scheduling and site-access constraints.
Manufacturing dominates contract value concentration. Retail is where platform disruption concentrates.
Distribution Channel:
Customer-type segmentation separates direct shipper-carrier relationships from intermediated arrangements through asset-light platforms. Margin capture varies sharply across these channel structures.
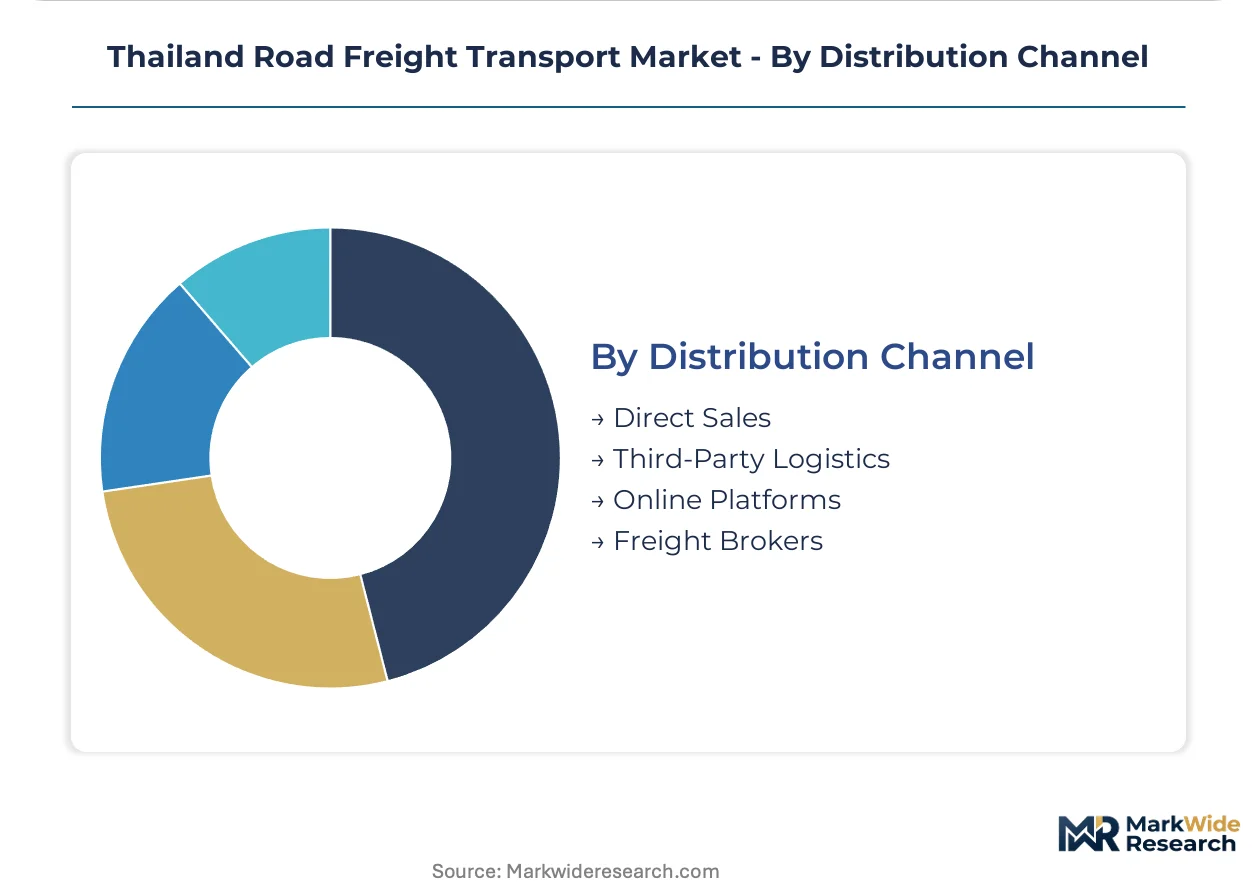
- Third-Party Logistics:Integrated providers bundling warehousing, customs brokerage, and fleet management under single contracts. Bangkok's industrial ring shippers consolidate vendor relationships toward these bundled providers.
- Direct Sales:Shipper contracts placed directly with asset-owning carriers without intermediary markup. Large automotive parts manufacturers mandate this structure for core lanes requiring real-time visibility compliance.
- Freight Brokers:Traditional intermediary networks matching spot-market demand with available capacity.
- Online Platforms:Digital freight matching enabling price discovery and load-board transactions.
Third-Party Logistics dominates margin pool capture. Online Platforms are where venture investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shippers in Bangkok's industrial ring exhibit the highest price elasticity, squeezing margins on standard dry-freight lanes, while pharmaceutical and cold-chain buyers absorb premium pricing for GDP-certified capacity. Provincial retail networks fall between these extremes.
Bangkok Metropolitan Region
Automotive parts manufacturers and electronics assemblers dominate freight demand, generating synchronized full-truckload loops to Laem Chabang port. The Department of Land Transport enforces commercial-driver certification and axle-load limits that shape fleet renewal cycles. Bang Na-Trat Road and Bang Phli industrial estates anchor heavy-freight corridors where just-in-time delivery requirements compress scheduling flexibility.
Eastern Economic Corridor
Rayong and Chonburi provinces redirect cargo flows from Bangkok's congested ring through Board of Investment tax incentives for logistics operators. Euro 5 emission mandates from the Excise Department accelerate diesel-truck replacement in bonded warehouse networks. Map Ta Phut and Laem Chabang port linkages serve contract manufacturers building regional electronics supply hubs.
Central Plains
Food processing exporters and agricultural distributors generate seasonal demand spikes for refrigerated and dry-van capacity. Provincial emission testing checkpoints operated by the national environmental regulator increasingly bar older vehicles from industrial estate access. Ayutthaya and Pathum Thani provinces concentrate cold-storage facilities serving Bangkok's biomedical zone expansion.
Northern Region
Chiang Mai and Lamphun distribution corridors face disintermediation pressure as small and medium enterprises aggregate less-than-truckload volumes through digital freight matching platforms. Cross-border documentation complexity at the Thai-Lao border delays Mekong corridor transit times. Industrial estates around Chiang Mai city generate scheduled demand for automotive components and electronics assembly.
Northeastern Region
Khon Kaen anchors retail distribution networks where e-commerce fulfillment centers drive last-mile platform integration. PTT's compressed natural gas station expansion along Highway 2 enables dual-fuel fleet conversions that reduce fuel cost exposure. Nakhon Ratchasima province's manufacturing estates generate full-truckload demand linking to Bangkok and Eastern Economic Corridor corridors.
Thailand Road Freight Transport Market Competitive Landscape
Capability concentration sits with integrated third-party logistics providers bundling warehousing, customs brokerage, and fleet management; scale advantage sits with global freight networks with cross-border connectivity. The market structures around three tiers: asset-heavy domestic operators, international forwarders with Thai subsidiaries, and platform-based intermediaries. Strategic moves concentrate on fleet telematics integration and cold-chain certification acquisition.
Within the integrated logistics tier, SCG Logistics anchors heavy-freight corridors across Thailand's eastern seaboard through its cement-and-building-materials heritage. Kerry Logistics exemplifies cross-border connectivity into Cambodia, Laos, Myanmar, and Vietnam. DHL Group occupies a position in pharmaceutical cold-chain certification, capturing temperature-controlled road freight from Bangkok's growing biomedical zone.
| Leading Market Players |
|---|
| DHL Group |
| SCG Logistics |
| JWD Group |
| Kerry Logistics |
| DB Schenker |
| Kuehne + Nagel |
| XPO Logistics |
| Yusen Logistics |
| Linfox Pty Ltd. |
| Others |
Value Network & Pricing Analysis
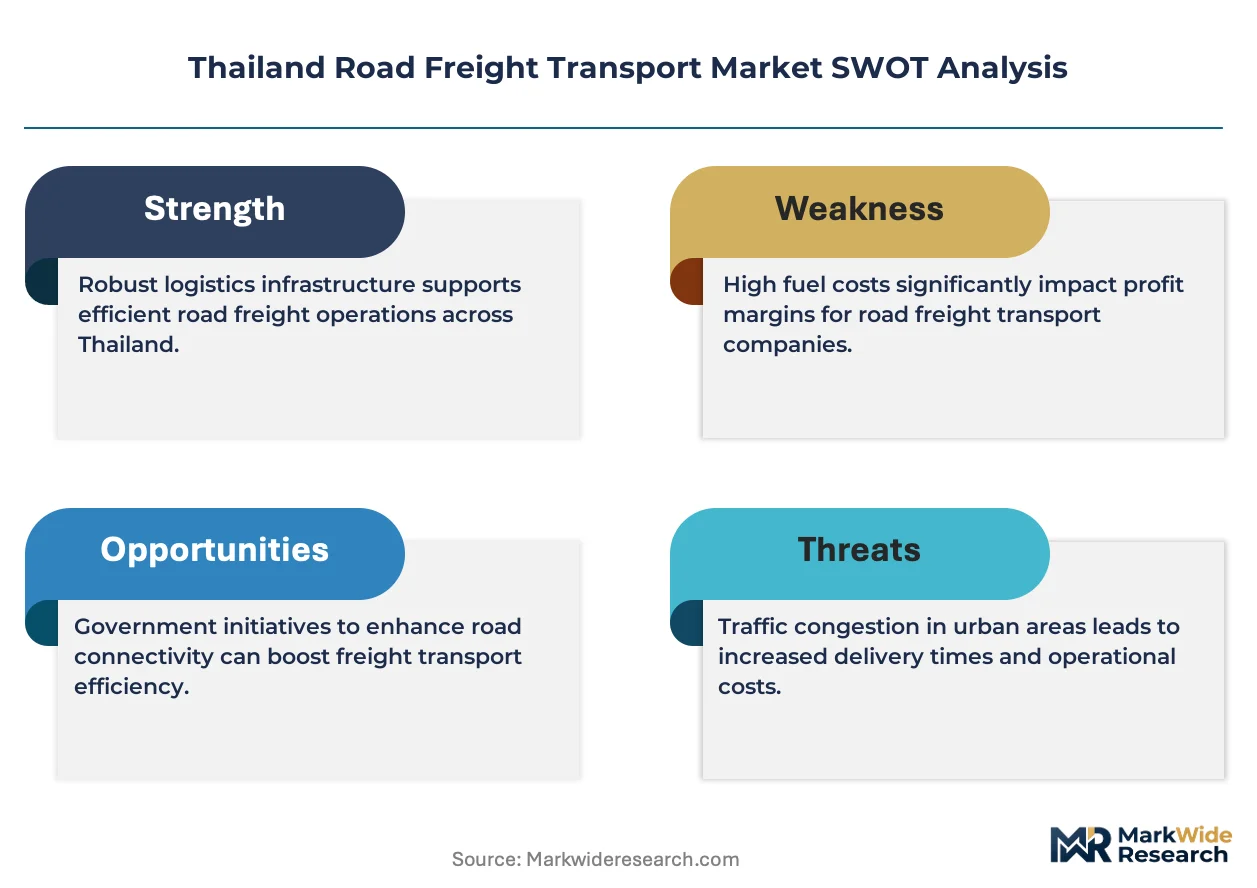
The Bangkok-Laem Chabang corridor anchors Thailand's freight pricing hierarchy, where heavy-freight operators serving automotive just-in-time loops command rate premiums while provincial LTL aggregators face compression from digital freight platforms. Supply concentration in the Eastern Economic Corridor's bonded warehouse networks enables integrated 3PLs to bundle warehousing and fleet capacity at margins that asset-light brokers cannot match.
Pricing Analysis
After-sales service revenue from maintenance contracts and extended fleet availability agreements drives lifetime value capture for heavy-freight operators. Contract pricing stratifies across GDP-certified pharmaceutical cold-chain, standard automotive FTL loops, and economy-grade construction materials haulage. Cost compression in the standard dry-freight tier intensifies as Bangkok industrial ring shippers consolidate vendor relationships toward bundled providers. Small and medium enterprises in provincial retail networks exhibit the highest price elasticity, while pharmaceutical buyers absorb premium rates for temperature-validated capacity.
Supply Chain Analysis
ASEAN single-window implementation gaps function as de facto export-control friction, limiting cross-border flow velocity at Thai-Lao and Thai-Myanmar checkpoints. Manufacturing supply draws from China, Japan, and South Korea for automotive electronics and precision components. Diesel and compressed natural gas feedstock dependencies, refrigerated trailer chassis, and telematics hardware constitute critical input categories. Single-source vulnerability concentrates in Euro 5 engine supply from Japanese OEMs. Distribution runs through 3PL-integrated warehouse networks, direct shipper-carrier contracts, and emerging digital freight matching platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's road freight sector sits at a high-growth inflection as Euro 5 emission mandates and telematics integration requirements simultaneously reshape fleet economics and competitive barriers.
For Market Incumbents: Entrench cross-border connectivity advantages by deepening bonded warehouse networks in Rayong and Chonburi provinces before ASEAN single-window harmonization erodes documentation friction. Acquire GDP cold-chain certification capabilities to capture pharmaceutical freight from Bangkok's biomedical zone expansion. Prioritize telematics infrastructure that satisfies automotive shipper real-time visibility mandates. For New Entrants and Emerging Players: Build out digital freight matching platforms targeting Chiang Mai and Khon Kaen provincial retail corridors where traditional distributor networks face disintermediation pressure. Focus on LTL aggregation for small and medium enterprises underserved by integrated 3PLs. Pursue partnership-based entry with e-commerce fulfillment centers rather than asset-heavy fleet acquisition. For Investors and Strategic Acquirers: Euro 5 enforcement reshapes the acquisition landscape toward fleet operators with compliant tractor inventories and technical integration capabilities. Position for consolidation plays across the 5-to-10-year horizon as emission testing checkpoints progressively bar older vehicles from industrial estate access. Target mid-scale carriers with captive pharmaceutical or automotive shipper relationships. Monitor PTT's CNG station rollout pace as a signal for dual-fuel fleet conversion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Telematics Integration | Automotive parts shippers now mandate real-time visibility as a contract condition for FTL loops. |
| Cold-Chain Certification Acquisition | GDP compliance positions carriers for Bangkok biomedical zone pharmaceutical freight expansion. |
| Cross-Border Corridor Development | Mekong corridor connectivity into Cambodia, Laos, Myanmar, and Vietnam differentiates integrated operators. |
| Alternative Powertrain Conversion | PTT's CNG infrastructure expansion along Highway 7 enables fuel cost reduction for heavy-freight operators. |
| Digital Platform Integration | Freight matching platforms disintermediate traditional distributors in Chiang Mai and Khon Kaen retail networks. |
Research Methodology
Desk research of customs trade databases, Department of Land Transport regulatory filings, and Board of Investment incentive disclosures preceded structured interviews with fleet operations directors, 3PL contract managers, automotive procurement leads, and cold-chain compliance officers. Primary fieldwork combined with secondary validation from PTT infrastructure announcements and Eastern Economic Corridor development authority planning documents. Bottom-up segment sizing and top-down macroeconomic cross-checks were triangulated to ensure consistency.
Assumptions regarding Euro 5 enforcement trajectory, ASEAN single-window implementation pace, and CNG station network expansion were held fixed across the projection horizon while fuel price volatility and cross-border documentation harmonization were treated as sensitivity variables. Segmentation modeling incorporated service type, vehicle configuration, end-use vertical, and distribution channel dimensions. CAGRs were derived from installed fleet turnover analysis, industrial estate absorption rates, and shipper contract renewal patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-based intermediaries or state-backed infrastructure investors would shift outcomes. Material shifts in emission enforcement rigor, carbon-border adjustment implementation, or regional trade agreement renegotiation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
India Intra-City Logistics Market