
 Traction Equipment Market | 2026-2036
Traction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Equipment Market Analysis
Chinese manufacturers is shifting capacity toward electric traction systems for metro and freight applications. SANY Group leverages domestic rail electrification programs to extend its product portfolio across Asia. Hitachi Construction Machinery anchors its position through advanced AC traction technology for heavy-haul segments. Caterpillar competes in road traction equipment with specialized drivetrain configurations for mining and earthmoving operations.
Traction equipment encompasses electromechanical systems that convert electrical or mechanical power into controlled tractive force for rail vehicles, heavy road machinery, and industrial conveyance, typically operating at voltage ranges from 750V DC to 25kV AC depending on application. These systems govern acceleration, braking, and adhesion management to ensure reliable movement across variable load and gradient conditions. Rail traction dominates current revenue pools given established infrastructure replacement cycles, while electric traction technology leads growth trajectory as municipalities phase out diesel fleets. Hybrid traction occupies a transitional niche where construction firms require dual-power flexibility for sites lacking full electrification.
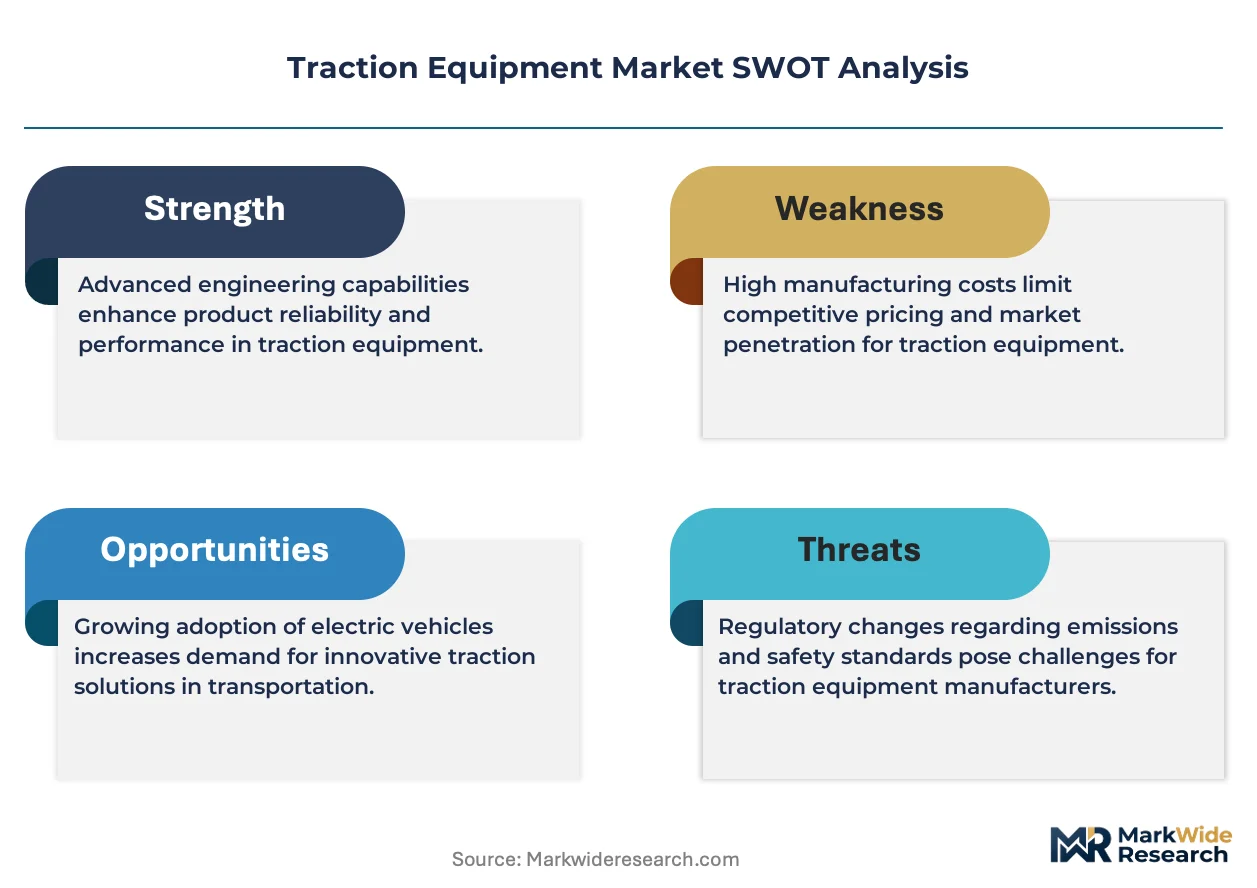
The Federal Railroad Administration enforces crashworthiness and electromagnetic compatibility standards that shape traction system design for US freight and passenger operators. EPA locomotive emission tiers and EU F-Gas Regulation constrain diesel-hybrid architectures while accelerating pure-electric platform development. China's NMPA and GB standards govern rail equipment certification, creating distinct compliance pathways for domestic versus export-bound manufacturers. Stakeholders must monitor how divergent electrification timelines across regulatory jurisdictions affect platform standardization decisions and supply chain configuration.
Market Dynamics
Electrification mandates across multiple jurisdictions are forcing simultaneous platform transitions in rail and heavy machinery, compressing supplier development cycles while fragmenting certification requirements.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates pure-electric traction system deployment across European freight corridors.
- Metro fleet renewals:Urban transit agencies in Germany and Japan are replacing aging DC motor systems with AC traction packages.
- Silicon carbide inverters:Wide-bandgap semiconductor adoption reduces switching losses and enables higher power density in compact traction drives.
Market Restraints
- Copper and rare-earth magnet costs:NdFeB permanent magnet price volatility constrains cost predictability for high-performance traction motors.
- Foundry concentration:Specialized castings for traction motor housings concentrate in Chinese and German supplier bases.
- Grid interconnection delays:Utility-side infrastructure timelines lag fleet electrification schedules by 18-36 months in multiple jurisdictions.
Strategic Opportunities
- India's dedicated freight corridors:3,800 route-kilometers of new electrified track create demand for heavy-haul traction systems.
- Battery-electric mining trucks:Open-pit operations lacking overhead catenary infrastructure drive demand for onboard energy storage traction.
- Japan's METI green innovation fund:Subsidies for next-generation rail technology lower R&D risk for hydrogen fuel cell traction prototypes.
Industry Challenges
- Embedded software certification:EN 50128 compliance for safety-critical traction control systems extends development timelines by 12-18 months.
- Multi-voltage platform complexity:Manufacturers must engineer traction packages spanning 750V DC to 25kV AC without common component architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Equipment Market |
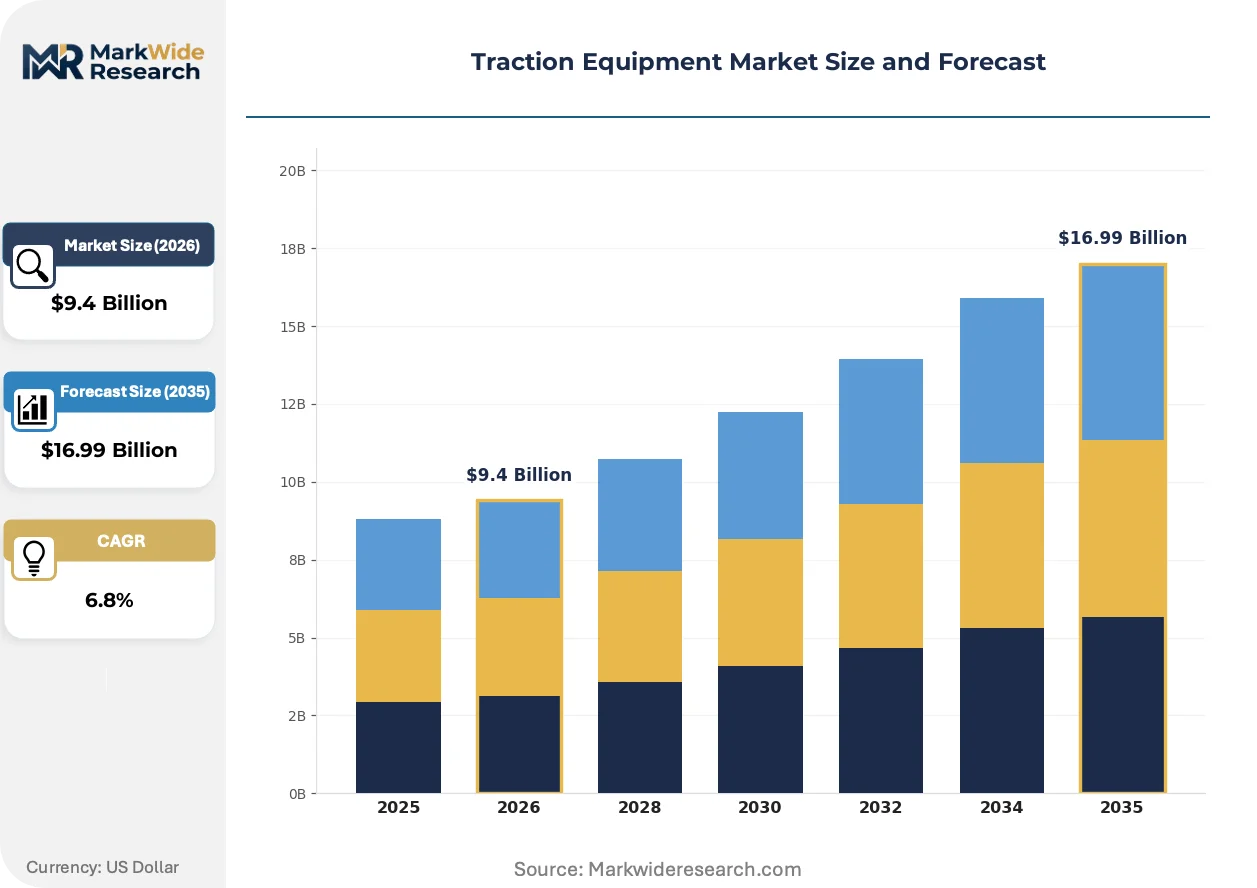
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rail Traction, Road Traction, Electric Traction, Hybrid Traction Application: Freight Transport, Passenger Transport, Urban Transit, Construction End User: Transport Agencies, Logistics Companies, Construction Firms, Municipalities Technology: AC Traction, DC Traction, Regenerative Braking, Automation |
| Companies Covered | SANY Group, Hitachi Construction Machinery, Caterpillar, John Deere, Liebherr Group, Komatsu, Volvo Construction Equipment, American Traction Systems, XCMG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Equipment Market Emerging Trajectories
Digital twin integration and wide-bandgap electronics are compressing product development cycles while enabling predictive maintenance models that alter aftermarket revenue structures.
Silicon carbide traction inverters are decentralizing thermal management requirements in high-power rail applications. Japanese and Korean rail operators are retrofitting existing fleets with SiC-based converter modules. This semiconductor transition is decentralizing the traditional dominance of water-glycol cooling systems in favor of air-cooled architectures.
EPA locomotive emission tiers and the EU F-Gas Regulation are forcing parallel compliance pathways for manufacturers serving transatlantic markets. Dual-certification requirements increase engineering overhead by 15-25 percent for platform development. North American freight operators are responding with selective route electrification rather than fleet-wide diesel replacement.
Aftermarket service unbundling is fragmenting traditional OEM captive maintenance arrangements. Mining and construction firms are negotiating component-level service contracts with third-party specialists. This procurement evolution is most advanced in Australian iron ore operations and Chilean copper mining districts.
Traction Equipment Market Segmentation
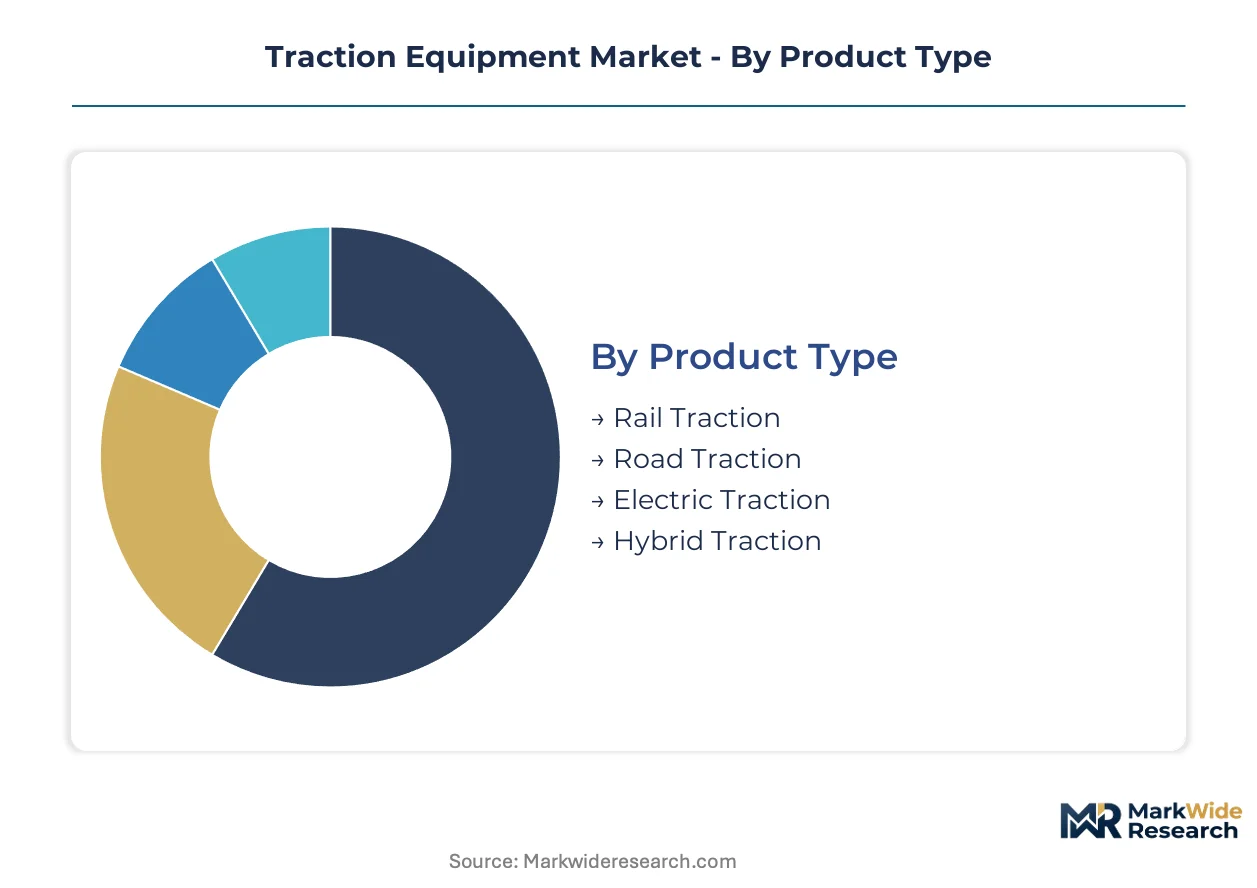
Traction equipment segmentation reveals how electrification mandates and infrastructure replacement cycles create divergent demand patterns across product architectures and end-use environments. Understanding these divisions helps suppliers align platform investments with actual procurement triggers rather than assumed technology transitions.
Product Type:
Rail fleet modernization programs in Germany and Japan are driving replacement decisions across all traction architectures, with voltage standardization and emission compliance shaping procurement specifications.
- Rail Traction:Electromechanical systems for locomotives and multiple units operating across 750V DC to 25kV AC infrastructure. Metro authorities in Tokyo and Berlin prioritize AC motor replacements to reduce maintenance intervals and improve energy recovery.
- Electric Traction:Pure-electric drivetrains eliminating onboard combustion for catenary-connected or battery-supplied operation. China's NMPA certification pathways and EU F-Gas Regulation compliance requirements dominate engineering priorities for export-bound manufacturers.
- Road Traction:Heavy-duty drivetrains for mining trucks and earthmoving equipment requiring high-torque low-speed performance. Australian iron ore operators and Chilean copper mines specify these systems for pit haulage where overhead lines remain impractical.
- Hybrid Traction:Dual-power architectures combining diesel or hydrogen generation with electric drive motors. Construction firms in jurisdictions with incomplete grid coverage deploy these for site flexibility while maintaining electrification optionality.
Volume placements concentrate in Rail Traction; the faster expansion belongs to Electric Traction.
Application:
Cost tier differentiation separates high-infrastructure applications from mobile equipment where onboard energy storage dominates capital allocation decisions.
- Freight Transport:Heavy-haul locomotive systems for bulk commodity and intermodal corridors. India's dedicated freight networks and China's coal-haul routes specify high-adhesion AC traction with regenerative braking for gradient-heavy terrain.
- Urban Transit:Metro and light rail systems with frequent stop-start cycles demanding rapid acceleration control. Operators in Osaka and Munich are retrofitting existing fleets with silicon carbide inverters to reduce cooling system complexity.
- Passenger Transport:Intercity and high-speed rail requiring sustained high-speed operation with minimal vibration. Japan's METI green innovation fund supports hydrogen fuel cell prototypes for non-electrified regional lines.
- Construction:Mobile equipment for earthmoving and material handling with severe duty cycles. Mining contractors in Western Australia negotiate component-level service contracts rather than traditional OEM captive maintenance.
Revenue concentration favors Freight Transport; Urban Transit climbs the fastest as municipal electrification schedules accelerate.
End User:
Customer procurement maturity determines whether traction system purchases bundle with long-term service agreements or fragment into component-level contracts.
- Transport Agencies:State and municipal rail operators with standardized specification frameworks and extended replacement cycles. German urban transit agencies bundle AC traction upgrades with digital twin integration for predictive maintenance.
- Construction Firms:Mining and earthmoving contractors prioritizing equipment availability over capital efficiency. Chilean copper districts lead aftermarket unbundling trends with third-party specialist contracts for drive system components.
- Logistics Companies:Intermodal operators and private freight carriers balancing fuel cost exposure against electrification infrastructure requirements. North American freight operators pursue selective route electrification rather than fleet-wide diesel replacement.
- Municipalities:City governments coordinating transit fleet transitions with utility grid interconnection timelines. Utility-side infrastructure delays of 18-36 months compress actual deployment schedules against announced electrification targets.
Procurement scale concentrates with Transport Agencies; Construction Firms are gaining share fastest through aftermarket restructuring.
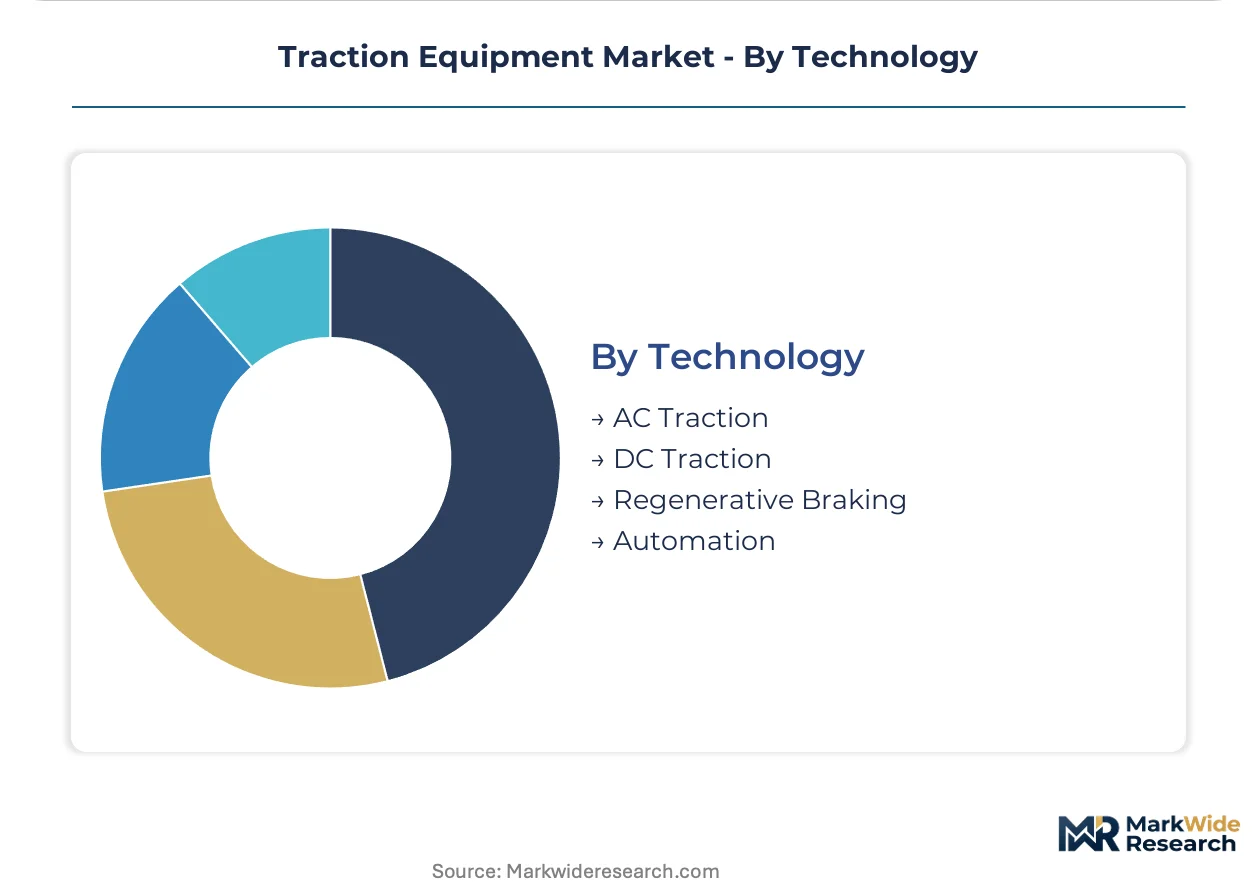
Technology:
Semiconductor transitions and software certification burdens are fragmenting supplier development cycles across competing technical architectures.
- AC Traction:Alternating current motor control systems with variable frequency drives enabling precise torque management. Hitachi Construction Machinery anchors market position through advanced AC packages for heavy-haul segments.
- Regenerative Braking:Energy recovery systems returning kinetic energy to catenary or onboard storage. Japanese and Korean retrofit programs favor SiC-based converter modules for improved efficiency in existing fleet upgrades.
- DC Traction:Direct current motor systems with simpler control electronics but higher maintenance requirements. Aging metro fleets in legacy jurisdictions still specify DC traction for compatibility with existing substation infrastructure.
- Automation:Driverless operation platforms integrating traction control with signaling and obstacle detection. EN 50128 safety certification extends development timelines by 12-18 months for software-intensive architectures.
Installed base dominance sits with AC Traction; Regenerative Braking shows steepest expansion trajectory as energy efficiency mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing capacity in China's Jiangxi and Inner Mongolia provinces supplies critical NdFeB materials for high-performance traction motors worldwide. Foundry networks in Germany's Ruhr region and Japan's Chubu industrial belt cast specialized motor housings for rail and heavy machinery applications. These material and component localities anchor regional production clusters.
Germany
KBA vehicle certification standards and EU F-Gas Regulation compliance shape traction system specifications for European freight corridors. Urban transit agencies in Berlin and Munich bundle AC traction upgrades with digital twin integration for predictive maintenance. The Ruhr industrial belt concentrates foundry capacity for traction motor housings serving export markets.
China
NMPA rail equipment certification and GB standards create distinct compliance pathways for domestic versus export-bound manufacturers. High-speed rail corridor expansions across the Yangtze River Delta and Pearl River Delta drive demand for 25kV AC traction packages. Jiangxi province's rare-earth processing clusters supply NdFeB permanent magnets for motor assemblies.
Japan
METI's green innovation fund subsidizes next-generation rail technology development including hydrogen fuel cell traction prototypes. Osaka Metro and Tokyo Metro retrofit existing fleets with silicon carbide inverters to reduce cooling system complexity. The Chubu region around Nagoya anchors advanced AC traction manufacturing for heavy-haul segments.
India
CEA grid interconnection standards and railway electrification mandates compress deployment schedules against announced fleet transition targets. Dedicated freight corridors spanning 3,800 route-kilometers create demand for heavy-haul traction systems with regenerative braking. Manufacturing clusters in Maharashtra and Gujarat assemble traction packages for domestic metro and freight applications.
United States
FRA crashworthiness and electromagnetic compatibility standards govern traction system design for freight and passenger operators. EPA locomotive emission tiers push North American freight operators toward selective route electrification rather than fleet-wide diesel replacement. Chicago and Los Angeles metropolitan rail agencies coordinate procurement with utility-side infrastructure timelines.
Traction Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-electric mining applications and hydrogen fuel cell prototypes. The market exhibits tiered concentration with integrated industrial conglomerates holding rail and construction positions alongside specialized traction component suppliers. Three archetypes dominate: diversified heavy machinery manufacturers with captive traction divisions, pure-play rail equipment specialists, and semiconductor-integrated power electronics firms. Competitive moves center on silicon carbide inverter partnerships and backward integration into rare-earth magnet supply chains.
Within the diversified machinery tier, SANY Group and Caterpillar exemplify scale-driven positions spanning rail electrification and mining equipment. Hitachi Construction Machinery anchors the precision-engineering archetype through its Chubu-region manufacturing base. These three entities represent contrasting geographic and capability configurations: Chinese state-linked expansion, American mining-sector dominance, and Japanese AC traction specialization.
| Leading Market Players |
|---|
| SANY Group |
| Hitachi Construction Machinery |
| Caterpillar |
| John Deere |
| Liebherr Group |
| Komatsu |
| Volvo Construction Equipment |
| American Traction Systems |
| XCMG Group |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange copper futures and NdFeB magnet price indices cascade through traction equipment supply chains, compressing margins for AC motor assemblies while widening spreads between bundled aftermarket service contracts and unbundled component procurement.
Pricing Analysis
Service-bundling arrangements separate OEM captive maintenance packages from component-level contracts negotiated by mining operators in Western Australia and Chile. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EN 50128-compliant safety software commanding substantial premiums over non-certified alternatives. Pricing pressure stems from rare-earth magnet cost volatility constraining cost predictability for high-performance motors. Transport agencies exhibit lowest price sensitivity given standardized specification frameworks, while construction firms prioritize equipment availability over capital efficiency.
Supply Chain Analysis
Regional distribution centers in Germany's Ruhr region and Japan's Chubu industrial belt coordinate hub-and-spoke patterns for specialized traction motor castings. Foundry networks in China, Germany, and Japan concentrate production of traction motor housings and NdFeB permanent magnets. Raw material flows draw from Jiangxi province rare-earth processing clusters and Chilean copper mining districts. Single-source vulnerability around silicon carbide wafer supply creates chokepoint exposure for wide-bandgap inverter production. Distribution runs through OEM-direct channels for rail operators and third-party specialist networks for mining contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints in Germany and Japan prop pricing premiums for certified traction castings, creating supply-constrained conditions favoring incumbents with captive manufacturing assets.
For Market Incumbents: Anticipate aftermarket unbundling threats from Australian iron ore operators and Chilean copper contractors by deepening digital twin integration for predictive maintenance offerings. Secure backward integration into rare-earth magnet supply chains through partnerships with Jiangxi province processors. Capacity addition in India's Maharashtra and Gujarat clusters addresses dedicated freight corridor demand while hedging against Chinese supply concentration. For New Entrants and Emerging Players: Mining contractors represent the most penetrable buyer archetype given their component-level service contract preferences and dissatisfaction with OEM captive maintenance. Battery-electric mining truck applications offer white-space entry where overhead catenary infrastructure remains impractical. Component-level service specialization provides the clearest go-to-market angle against integrated machinery conglomerates. For Investors and Strategic Acquirers: Distressed-cycle entries favor semiconductor-integrated power electronics firms with silicon carbide inverter capabilities in South Korea and Taiwan. Long-term viability centers on wide-bandgap semiconductor transitions displacing traditional water-glycol cooling architectures. Watch Japanese METI green innovation fund disbursement patterns as inflection indicators for hydrogen fuel cell traction prototype commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Partnership | Reduces cooling system complexity for Osaka Metro and Tokyo Metro retrofit programs. |
| Backward Integration into Rare-Earth Magnets | Secures NdFeB supply from Jiangxi province against price volatility for high-performance motors. |
| Digital Twin Integration | Enables predictive maintenance contracts with German urban transit agencies bundling AC traction upgrades. |
| India Manufacturing Footprint Expansion | Positions for 3,800 route-kilometers of dedicated freight corridor electrification demand. |
| Hydrogen Fuel Cell Prototype Development | Accesses METI green innovation fund subsidies for non-electrified regional line applications. |
Methodological Framework
Multi-period observation of fleet electrification procurement schedules and utility grid interconnection timelines anchored the trend analysis, supplemented by interviews with rail operator engineering directors, mining contractor maintenance heads, OEM procurement teams, and traction component suppliers. Secondary validation drew from Federal Railroad Administration certification filings, EU F-Gas Regulation implementation reports, China NMPA rail equipment registrations, and India CEA grid standards documentation. Bottom-up and top-down triangulation reconciled equipment shipment data with infrastructure investment disclosures.
Input-output matrices mapped traction system demand across product architecture, application environment, end-user procurement maturity, and technology generation dimensions over the projection horizon. CAGRs were derived from segment-level unit economics and replacement cycle analysis. Silicon carbide adoption curves and EN 50128 software certification timelines provided industry-specific forecast inputs alongside rare-earth magnet price elasticity assumptions.
Caveats apply where utility-side infrastructure delays beyond 18-36 months or NdFeB supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
North America Long-Haul Transport Market