
 Freight Transport Management Market | 2026-2036
Freight Transport Management Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Transport Management Market Foresight
E-commerce retailers is bifurcating demand away from traditional freight brokers toward integrated digital platforms. Oracle leverages its cloud infrastructure to dominate enterprise-scale transport management systems. SAP sustains competitive positioning through deep ERP integration with logistics modules. C.H. Robinson anchors North American truckload brokerage through proprietary carrier-matching algorithms.
Freight transport management encompasses the planning, execution, and optimization of cargo movement across multimodal networks, typically integrating real-time GPS tracking, electronic logging devices, and automated dispatch engines with sub-100-millisecond latency requirements. Its primary commercial purpose is to minimize empty miles, consolidate loads, and synchronize inventory flows between shippers and carriers. Cloud-based deployment leads adoption among mid-market logistics providers seeking scalable infrastructure without capital expenditure, while edge computing solutions represent the fastest-growing segment for last-mile operations requiring localized data processing. SaaS platforms now capture the deepest margin pools through recurring subscription revenue and API-based ecosystem integrations.
The US EPA mandates greenhouse gas emissions standards for medium- and heavy-duty trucks under Phase 2 regulations, while the EU Green Deal's Fit for 55 package imposes carbon border adjustments on freight imports. Germany's KBA enforces periodic technical inspections that accelerate fleet renewal toward telematics-enabled vehicles. Stakeholders must decide whether to build proprietary routing algorithms or embed third-party AI engines as regulatory compliance costs reshape software procurement criteria.
Market Dynamics
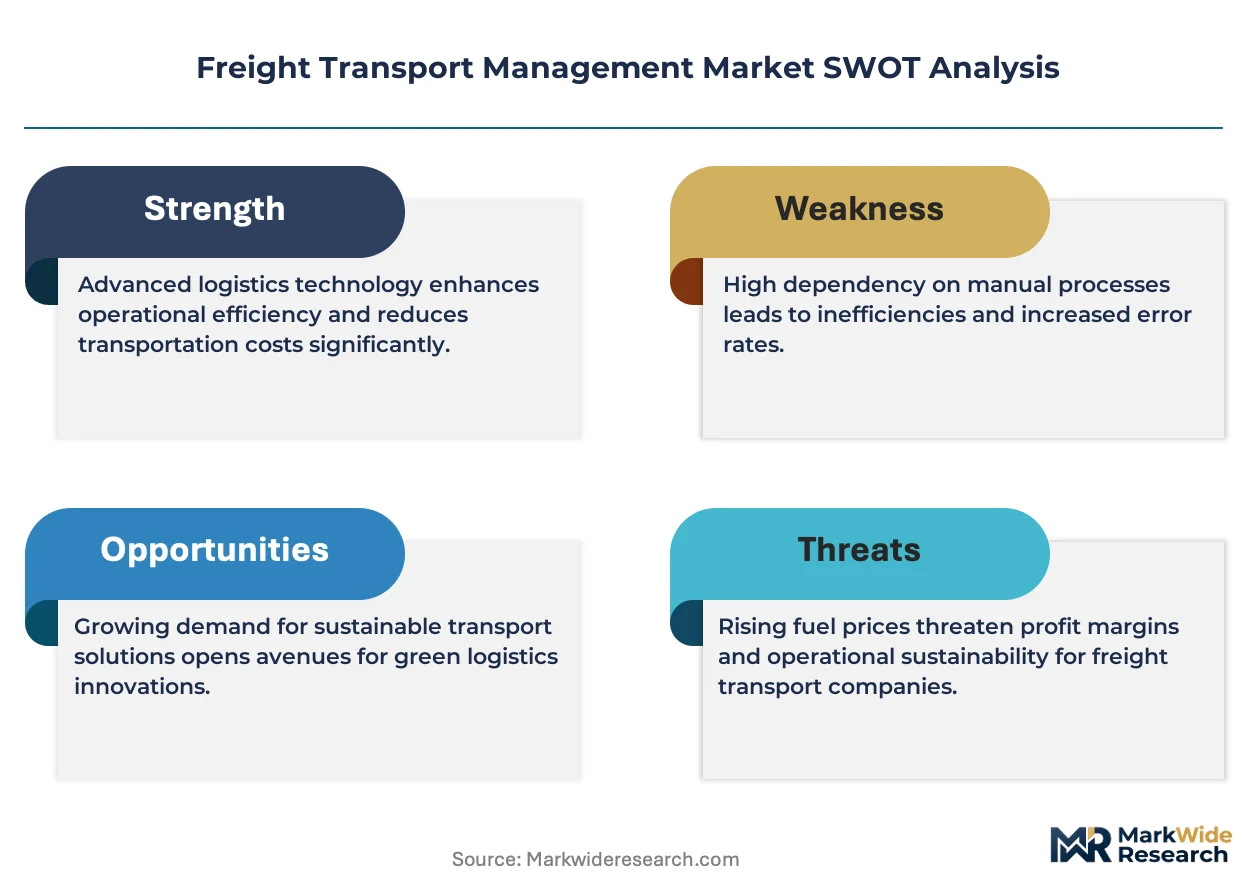
Cloud-based freight platforms are compressing margins for traditional freight brokers while simultaneously expanding total addressable market for integrated logistics software. E-commerce fulfillment networks demand sub-hour delivery windows, forcing transport operators to abandon legacy dispatch systems.
Growth Catalysts
- EU Green Deal Fit for 55:Carbon border adjustments on freight imports accelerate fleet electrification and telematics adoption across European logistics corridors.
- Electronic logging devices:Mandated hours-of-service compliance drives replacement of paper logbooks with automated compliance engines in North American trucking.
- Rhine-Ruhr logistics concentration:Germany's dense industrial cluster generates continuous demand for multimodal optimization platforms serving chemical and automotive shippers.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate telematics chip fabrication, exposing fleet operators to input cost volatility and delivery delays.
- API standardization gaps:Proprietary data formats between competing transport management systems create integration friction and duplicate development costs.
- Diesel price exposure:Fuel represents 25-30% of operating costs for asset-based carriers, compressing margins when hedging instruments are unavailable.
Strategic Opportunities
- Last-mile edge computing:Localized data processing at distribution hubs enables real-time route reoptimization without cloud latency.
- India's logistics modernization:National highway corridor development and GST harmonization create white space for cloud-native freight platforms.
- ISO 14064 carbon accounting:Standardized emissions verification protocols open subscription revenue streams for compliance-as-a-service modules.
Industry Challenges
- Embedded systems engineering talent:Shortage of developers with combined logistics domain knowledge and real-time optimization expertise constrains product velocity.
- Legacy ERP integration complexity:On-premise warehouse management systems require custom middleware development, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Transport Management Market |
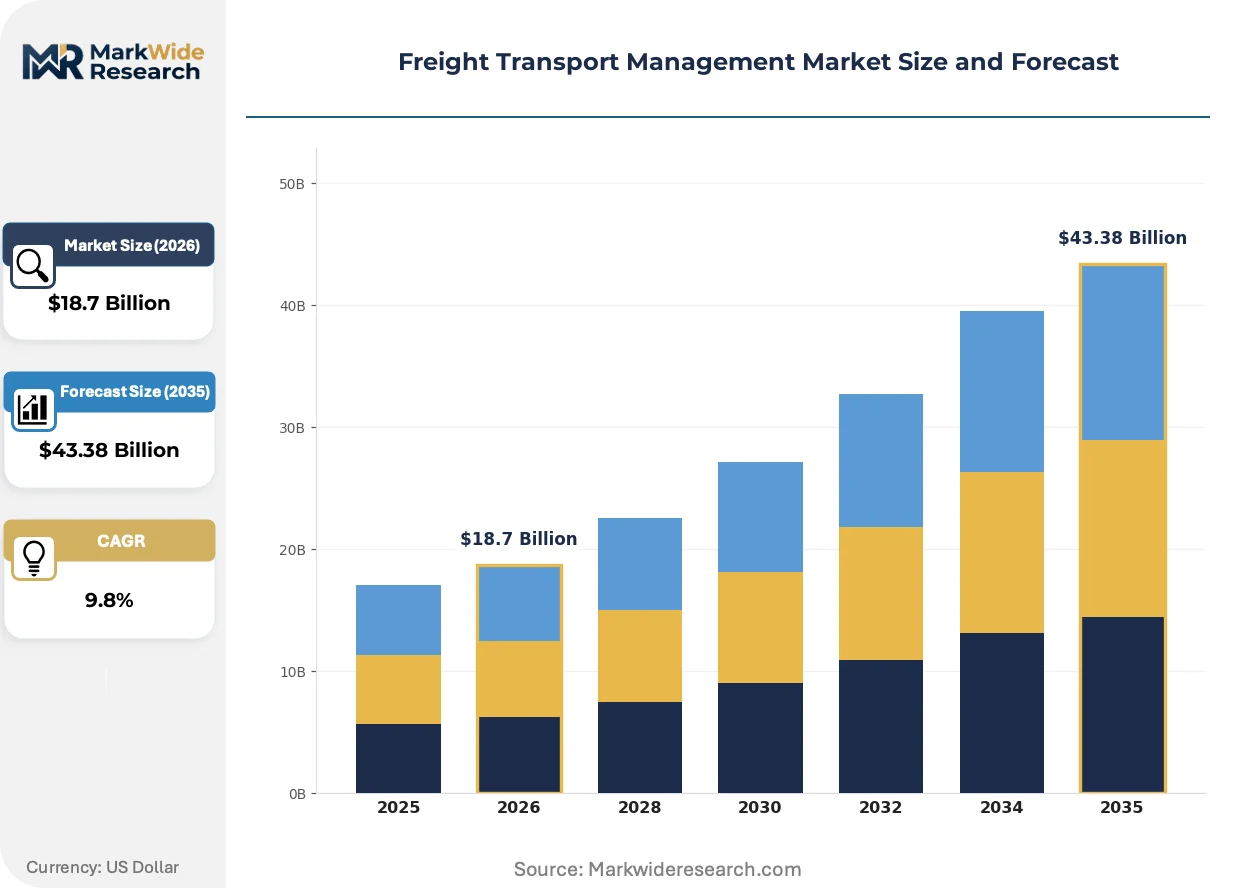
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Customs Brokerage, Cargo Handling, Inventory Management, Order Fulfillment Application: Intermodal Transport, Last-Mile Delivery, Cross-Docking, Route Optimization, Fleet Management, Load Consolidation Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Edge Computing, SaaS Platforms, Mobile Applications End User: Logistics Providers, Freight Brokers, Shipping Companies, E-commerce Retailers, Third-Party Logistics, Supply Chain Consultants |
| Companies Covered | Oracle, SAP, Manhattan Associates, C.H. Robinson, Blue Yonder Group, Descartes Systems Group, Accenture, Kuehne + Nagel, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Transport Management Market Shifts & Advancements
Freight transport software is converging with warehouse execution systems and customs platforms into unified supply chain operating systems. Real-time visibility is becoming table stakes rather than a premium feature.
Edge computing hardware is miniaturizing to gateway devices installable in standard vehicle diagnostic ports. Mid-market less-than-truckload carriers are adopting these units fastest, bypassing expensive telematics retrofits. This compression of hardware footprint is miniaturizing the capital barrier to real-time fleet intelligence.
The US EPA Phase 2 greenhouse gas standards for medium- and heavy-duty trucks tighten through 2027 model years. Engine manufacturers must integrate predictive cruise control and automated manual transmissions. Long-haul truckload segments face the steepest compliance costs, accelerating consolidation toward larger fleet operators with dedicated sustainability teams.
Shippers are unbundling freight procurement from contracted capacity, maintaining spot market relationships alongside annual bids. Food and beverage manufacturers lead this behavior shift, responding to demand volatility from quick-commerce channels. Germany's chemical sector shows similar patterns, with BASF and Bayer subsidiaries piloting dynamic freight marketplaces.
Freight Transport Management Market Segmentation
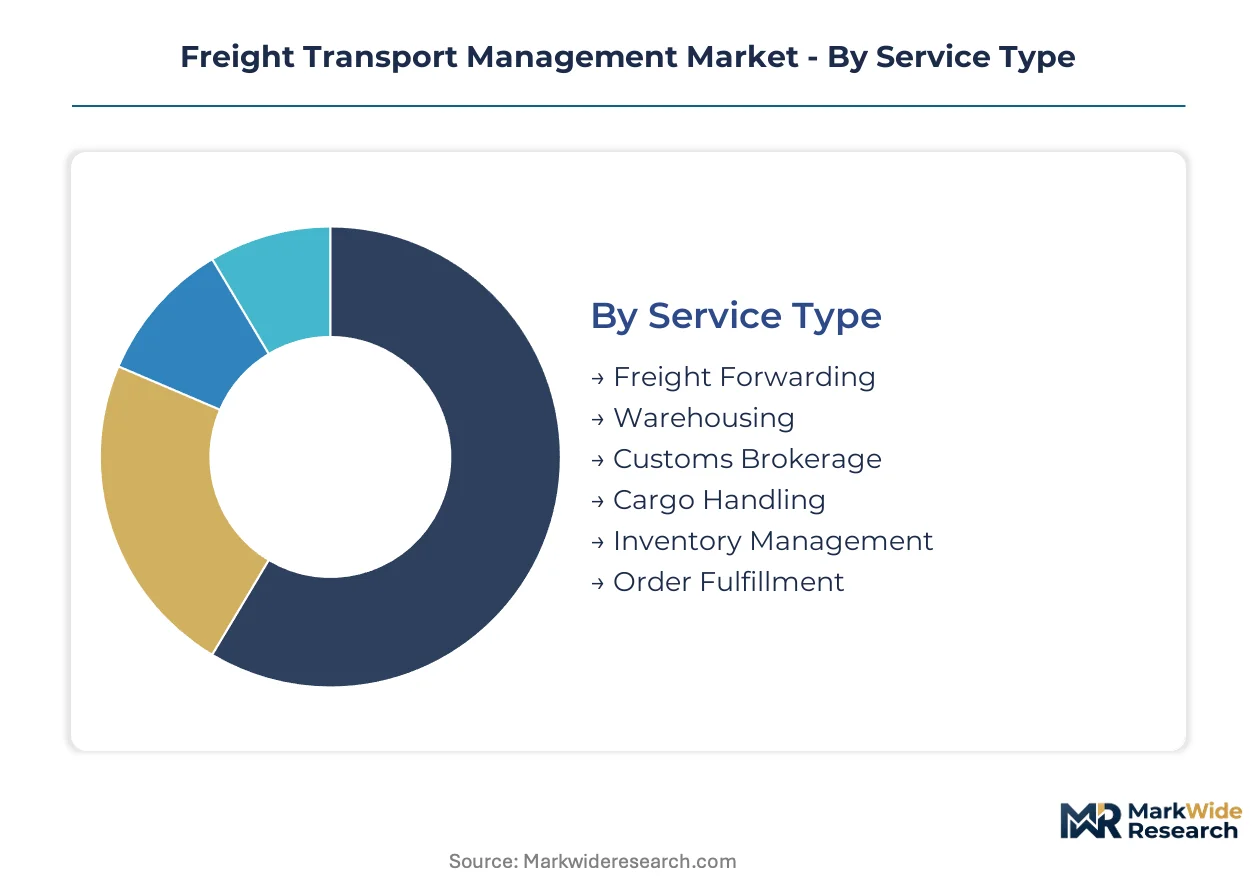
Freight transport management vendors configure product portfolios around service delivery models, operational applications, infrastructure deployment modes, and buyer organizational types. Margin capture varies sharply across these dimensions, with SaaS platforms and cloud-native architectures commanding recurring revenue premiums while on-premises implementations face compression from capital expenditure avoidance trends.
Service Type:
Margin pools concentrate in value-added services that embed proprietary technology rather than commodity labor arbitrage.
- Freight Forwarding:Multimodal coordination across ocean, air, and surface networks requires customs documentation expertise and carrier contract leverage. E-commerce retailers in Germany's Rhine-Ruhr corridor drive demand for integrated forwarding platforms that synchronize with warehouse management systems.
- Warehousing:Inventory positioning and fulfillment center operations generate recurring revenue through long-term facility contracts. Third-party logistics providers in North American markets prioritize warehouse management modules with real-time labor tracking and automated slotting optimization.
- Customs Brokerage:Regulatory compliance services for cross-border movements.
- Cargo Handling:Physical loading, unloading, and equipment coordination at ports and terminals.
- Inventory Management:Stock level monitoring and replenishment triggering across distributed networks.
- Order Fulfillment:Pick-pack-ship operations integrated with customer delivery promises.
Freight Forwarding holds installed capacity. Warehousing is rotating up the share rankings.
Application:
Application selection tracks operational complexity, with high-velocity fulfillment networks demanding specialized optimization engines.
- Intermodal Transport:Rail-truck-ocean coordination with container tracking across handoff points. Chemical shippers in Germany's industrial clusters require precise dwell time management at transshipment terminals to meet EU Green Deal emissions reporting requirements.
- Last-Mile Delivery:Urban distribution with sub-hour delivery windows and dynamic route resequencing. Quick-commerce channels in dense metropolitan zones force abandonment of static dispatch schedules in favor of real-time optimization.
- Cross-Docking:Direct freight transfer minimizing storage duration.
- Route Optimization:Algorithmic sequencing of stops for fuel and time efficiency.
- Fleet Management:Vehicle telematics integration with maintenance scheduling.
- Load Consolidation:Multi-shipment aggregation to improve trailer utilization.
Intermodal Transport anchors enterprise contract value. Last-Mile Delivery is expanding most quickly as consumer delivery expectations compress.
Deployment:
Deployment architecture determines capital recovery profiles and implementation risk allocation between vendor and customer.
- Cloud-Based:Scalable infrastructure with subscription pricing and automatic feature updates. Mid-market logistics providers across European markets favor this model to avoid data center capital expenditure while maintaining API connectivity with shipper ERP systems.
- SaaS Platforms:Multi-tenant software delivery with ecosystem integration marketplaces. Freight brokers seeking rapid carrier onboarding prioritize SaaS solutions with pre-built EDI and API connectors to major transportation networks.
- On-Premises:Customer-controlled infrastructure with perpetual licensing.
- Hybrid Solutions:Split processing between cloud and local environments.
- Edge Computing:Localized data processing at distribution hubs or vehicle gateways.
- Mobile Applications:Driver-facing interfaces for proof-of-delivery and communication.
Cloud-Based carries the largest current revenue base. Edge Computing is gaining share fastest as latency requirements tighten for real-time dispatch decisions.
End User:
Buyer sophistication and procurement authority vary dramatically across organizational types, shaping sales cycle complexity and solution customization requirements.
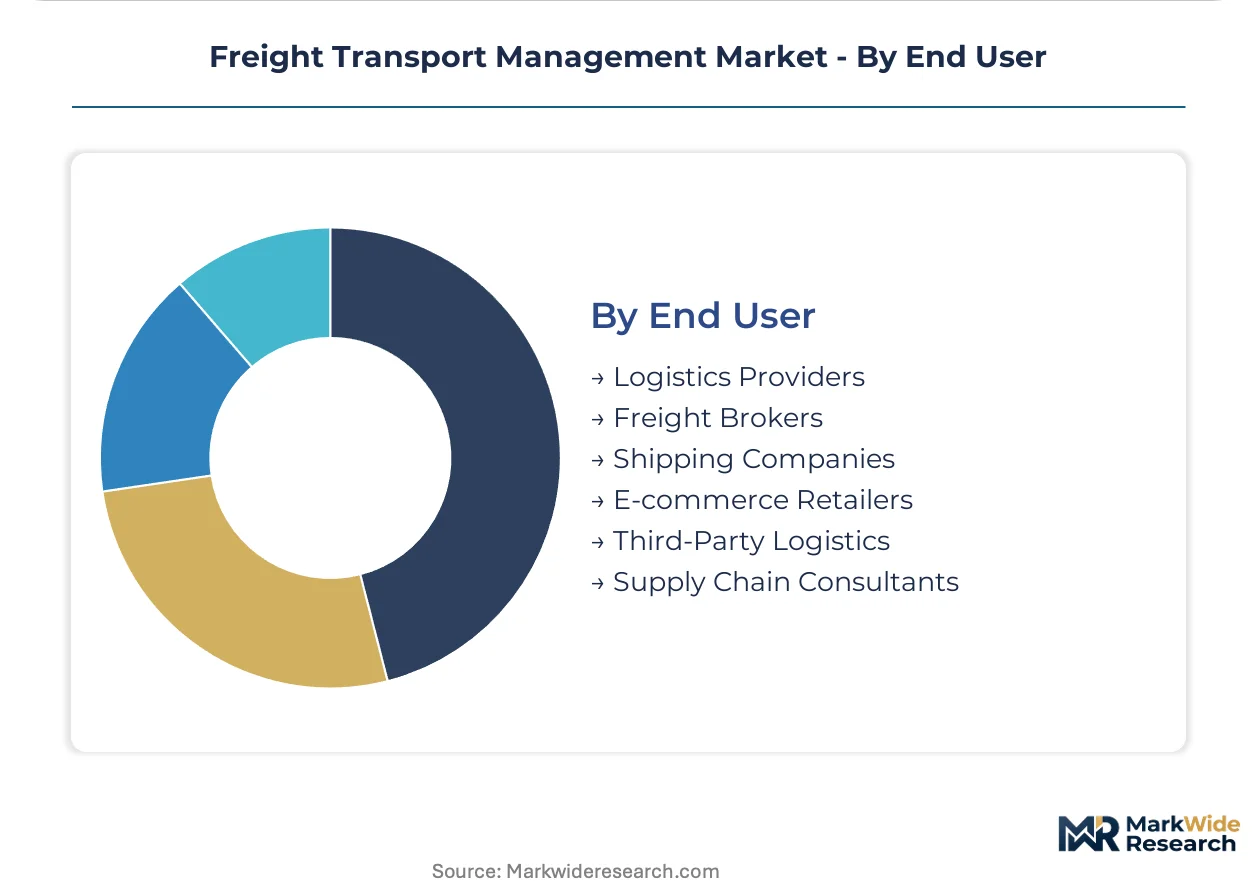
- E-commerce Retailers:Direct-to-consumer fulfillment networks with peak season volatility and delivery promise sensitivity. These organizations mandate sub-hour delivery windows and real-time visibility, forcing transport operators toward integrated platform investments.
- Third-Party Logistics:Asset-light intermediaries serving multiple shipper accounts with specialized requirements. 3PLs in North American truckload segments differentiate through proprietary carrier-matching algorithms and dynamic pricing engines.
- Logistics Providers:Asset-based carriers with owned fleet and facility infrastructure.
- Freight Brokers:Non-asset intermediaries matching shipper demand with carrier capacity.
- Shipping Companies:Ocean and air freight carriers with container or vessel assets.
- Supply Chain Consultants:Advisory firms implementing technology on behalf of shippers.
E-commerce Retailers are climbing the fastest as a buyer category. Third-Party Logistics retains the deepest technology procurement budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container terminals anchor European freight flows, while the US Interstate highway network and China's Yangtze River Delta manufacturing belt shape continental logistics architectures.
United States
E-commerce fulfillment networks in California's Inland Empire and Texas's Dallas-Fort Worth corridor drive demand for real-time visibility platforms. The EPA's Phase 2 greenhouse gas standards for medium- and heavy-duty trucks tighten through 2027, forcing fleet operators toward telematics-enabled compliance engines. Chicago's freight rail intermodal terminals concentrate cross-country container movements, with BNSF and Union Pacific investing in automated gate systems.
Germany
The Rhine-Ruhr logistics corridor generates continuous demand for multimodal optimization platforms serving chemical and automotive shippers. The KBA enforces periodic technical inspections that accelerate fleet renewal toward connected vehicles. Duisburg's inland port terminals handle the largest European container volumes by rail, with BASF and Bayer subsidiaries piloting dynamic freight marketplaces for chemical transport.
China
Cross-border e-commerce through Shenzhen and Guangzhou drives adoption of cloud-based freight forwarding platforms. The MIIT's dual carbon goals impose emissions monitoring requirements on commercial fleets operating along the Beijing-Shanghai expressway corridor. The Yangtze River Delta manufacturing belt concentrates demand for intermodal transport solutions linking Shanghai's deepwater port with interior production zones.
India
National highway corridor development and GST harmonization create white space for cloud-native freight platforms across the Delhi-Mumbai Industrial Corridor. The country's national logistics regulator mandates electronic waybills for interstate goods movement, accelerating digital adoption among fragmented truck operators. Gujarat's Mundra Port and Maharashtra's Jawaharlal Nehru Port Trust anchor container flows, with third-party logistics providers expanding warehouse networks in Pune and Ahmedabad.
Netherlands
Amsterdam's Schiphol cargo hub and Rotterdam's automated terminals position the country as Europe's freight gateway. The EU Green Deal's Fit for 55 package imposes carbon border adjustments on freight imports, driving telematics adoption among Dutch fleet operators. The Randstad logistics cluster integrates port, air, and road networks, with mid-market logistics providers favoring cloud-based deployment to avoid data center capital expenditure.
Freight Transport Management Market Competitive Landscape
Concentration sits with enterprise software conglomerates and specialized logistics technology providers. The vendor landscape organizes around three strategic archetypes: cloud infrastructure giants with transport management modules, pure-play logistics software specialists, and asset-light freight brokers with proprietary algorithmic platforms. Competitive dynamics center on API ecosystem expansion and embedded AI engine partnerships rather than traditional capacity competition.
Within the enterprise software tier, Oracle and SAP exemplify archetypes leveraging cloud infrastructure and ERP integration respectively to anchor enterprise-scale deployments. C.H. Robinson occupies a position representing the algorithmic brokerage model, with proprietary carrier-matching capabilities distinguishing asset-light intermediaries. These three entities collectively illustrate how competitive positioning fragments across technology stack layers rather than consolidating around uniform service delivery.
| Leading Market Players |
|---|
| Oracle |
| SAP |
| Manhattan Associates |
| C.H. Robinson |
| Blue Yonder Group |
| Descartes Systems Group |
| Accenture |
| Kuehne + Nagel |
| DB Schenker |
| Others |
Supply & Pricing Matrix
Ninety-day telematics hardware lead times compress pricing power for SaaS vendors while amplifying cost pass-through leverage for integrated platform providers serving Rhine-Ruhr chemical shippers. Inventory buffers at Taiwan semiconductor foundries directly shape subscription pricing tiers for European fleet operators facing EU Green Deal compliance deadlines.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and small-fleet bands, with pricing differentiation driven by API integration depth and real-time optimization engine access. Three-tier pricing separates premium predictive routing modules from standard dispatch automation from economy-grade compliance logging. Cost compression in the mid-market tier is intensifying because cloud-native entrants undercut legacy perpetual licenses. Small-fleet operators show highest price sensitivity, while enterprise chemical shippers prioritize compliance bundling over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and container availability on Asia-Europe trade lanes expose fleet operators to hardware delivery volatility that ripples through software deployment timelines. Semiconductor fabrication concentrates in Taiwan and South Korea, with edge-computing gateway assembly drawing from Chinese component suppliers. Single-source vulnerability sits with Taiwan-based telematics chip foundries. Distribution runs through third-party logistics providers integrating warehouse execution with transport management modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent software vendors face substitution pressure from cloud-native platforms that bypass legacy ERP integration complexity, forcing defensive repositioning around data moats and carrier network density.
For Market Incumbents: Secure carrier-matching algorithm exclusivity through long-term capacity contracts with Rhine-Ruhr chemical fleets. Lock in API ecosystem dominance by embedding compliance engines that preempt EU Green Deal reporting requirements. Vertical integration into edge-computing hardware insulates against Taiwan semiconductor supply volatility.
For New Entrants and Emerging Players: Differentiate on sub-hour delivery optimization for quick-commerce channels in dense metropolitan zones. Target India's Delhi-Mumbai Industrial Corridor where GST harmonization creates white space for cloud-native platforms unburdened by legacy middleware. Lead with mobile-first driver interfaces that bypass expensive telematics retrofits.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SaaS-native freight platforms as subscription revenue pools deepen relative to implementation overhead. Mid-market logistics software specialists with pre-built EDI connectors represent prime acquisition targets. Watch for EPA Phase 2 compliance cost spikes as fleet consolidation signals tipping toward integrated platform adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified supply chain operating systems compress implementation timelines for BASF and Bayer subsidiaries. |
| Edge Computing Deployment | Localized gateway processing enables sub-100-millisecond dispatch decisions at Rotterdam distribution hubs. |
| Regulatory Compliance Bundling | ISO 14064 carbon accounting modules open recurring revenue streams under EU Green Deal mandates. |
| Strategic Partnership | API ecosystem expansion with Oracle and SAP anchors enterprise-scale transport management deployments. |
| Geographic Expansion | India's national logistics regulator mandates electronic waybills, accelerating digital adoption among fragmented operators. |
Research Methodology
Cross-validation between primary interviews with fleet operations directors and secondary analysis of EPA regulatory filings anchors the qualitative findings. Conversations with third-party logistics procurement leads, transport management software engineers, chemical shipper supply chain managers, and KBA compliance officers generated operational insight. Secondary sources include EU Green Deal implementation documents, US EPA Phase 2 technical standards, SEC 10-K disclosures from logistics technology providers, and customs data from Rotterdam port authorities. Bottom-up carrier adoption modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across deployment mode, fleet size tier, and vertical industry shapes the analytical framework over the projection horizon. Segmentation dimensions include service delivery model, application complexity, infrastructure architecture, and buyer organizational type. CAGRs derive from logistic curve fitting to technology adoption patterns and regulatory compliance cost trajectories. Fuel price volatility indices and semiconductor lead-time fluctuations serve as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce fulfillment velocity or stable Taiwan semiconductor supply would require recalibration. Forecasts reflect documented assumptions around EPA Phase 2 enforcement timelines and EU carbon border adjustment implementation. Telematics hardware shortages or diesel price spikes beyond hedged ranges could compress margins faster than modeled. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
Europe Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Control Towers Market