
 Refrigerated Road Transportation Market | 2026-2036
Refrigerated Road Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Road Transportation Market Outlook
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles is shifting compliance costs toward refrigeration unit manufacturers and fleet operators. Marten Transport leverages its dedicated cold chain network to sustain premium service positioning across North American lanes. C.R. England anchors its competitive stance through extensive driver training programs and temperature-control specialization. Prime Inc. differentiates via integrated fleet maintenance capabilities that reduce reefer downtime across its refrigerated division.
Refrigerated road transportation encompasses temperature-controlled freight movement using insulated vehicles and active cooling systems, typically maintaining cargo between minus 25 degrees Celsius and plus 25 degrees Celsius depending on product requirements. Its primary purpose is preserving perishable goods integrity from origin through final delivery across pharmaceutical, food, and agricultural supply chains. Frozen food applications dominate product type volume due to established retail distribution patterns, though pharmaceuticals represents the fastest-growing segment as biologics expand. Reefer vehicles lead technology deployment, while active systems with telematics integration command premium positioning. Food and beverage industry end users generate baseline demand, with healthcare sector procurement tightening around GDP-compliant documentation and real-time temperature verification.
The EPA's evolving emissions framework, the FDA's food safety modernization requirements, and the USDA's agricultural transport protocols collectively shape equipment specifications and operational compliance burdens across the United States. California's Air Resources Board accelerates zero-emission refrigeration mandates through its Advanced Clean Trucks regulation, forcing fleet investment timelines. Stakeholders must monitor electric reefer total-cost-of-ownership trajectories against diesel baseline economics while positioning for cold chain insurance and liability frameworks that increasingly require continuous data logging.
Market Dynamics
Electric reefer unit adoption is compressing total-cost-of-ownership calculations against diesel baselines as fleet operators confront California's Advanced Clean Trucks mandates and EPA Phase 3 compliance deadlines.
Growth Catalysts
- Biologics cold chain:Temperature-sensitive pharmaceutical shipments now require continuous GDP-compliant monitoring from manufacturing through final-mile delivery.
- California's Advanced Clean Trucks regulation:Zero-emission refrigeration mandates are pulling forward electric reefer investment timelines for medium-duty and heavy-duty fleets operating in-state.
- Food retail consolidation:Regional distribution hub expansion across the United States is reshaping lane economics and increasing demand for dedicated refrigerated capacity.
Market Restraints
- Refrigerant cost volatility:Hydrofluorocarbon phase-down schedules under the Kigali Amendment are elevating input costs for reefer unit manufacturers dependent on legacy cooling chemistries.
- Battery supply concentration:Lithium-ion cell production for electric reefer units clusters in a narrow supplier base, exposing fleet procurement to price and availability shocks.
- Electric infrastructure gaps:Depot charging capacity limitations in secondary distribution corridors constrain route flexibility for battery-electric refrigerated vehicles.
Strategic Opportunities
- Last-mile pharmaceutical delivery:Urban cold chain gaps for biologics and cell therapies create white space for compact electric reefer vehicles with real-time temperature verification.
- Telematics-integrated active cooling:Convergence of IoT sensors and predictive maintenance algorithms enables premium service positioning through downtime reduction guarantees.
- Inflation Reduction Act credits:Commercial clean vehicle tax incentives offset electric reefer acquisition premiums for US-based fleet operators meeting domestic content thresholds.
Industry Challenges
- Refrigeration technician scarcity:Specialized skill requirements for electric reefer diagnostics and repair outpace vocational training program output across fleet maintenance networks.
- Multi-jurisdiction compliance complexity:Divergent state-level emissions protocols and FDA food safety documentation standards fragment operational standardization for interstate carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Road Transportation Market |
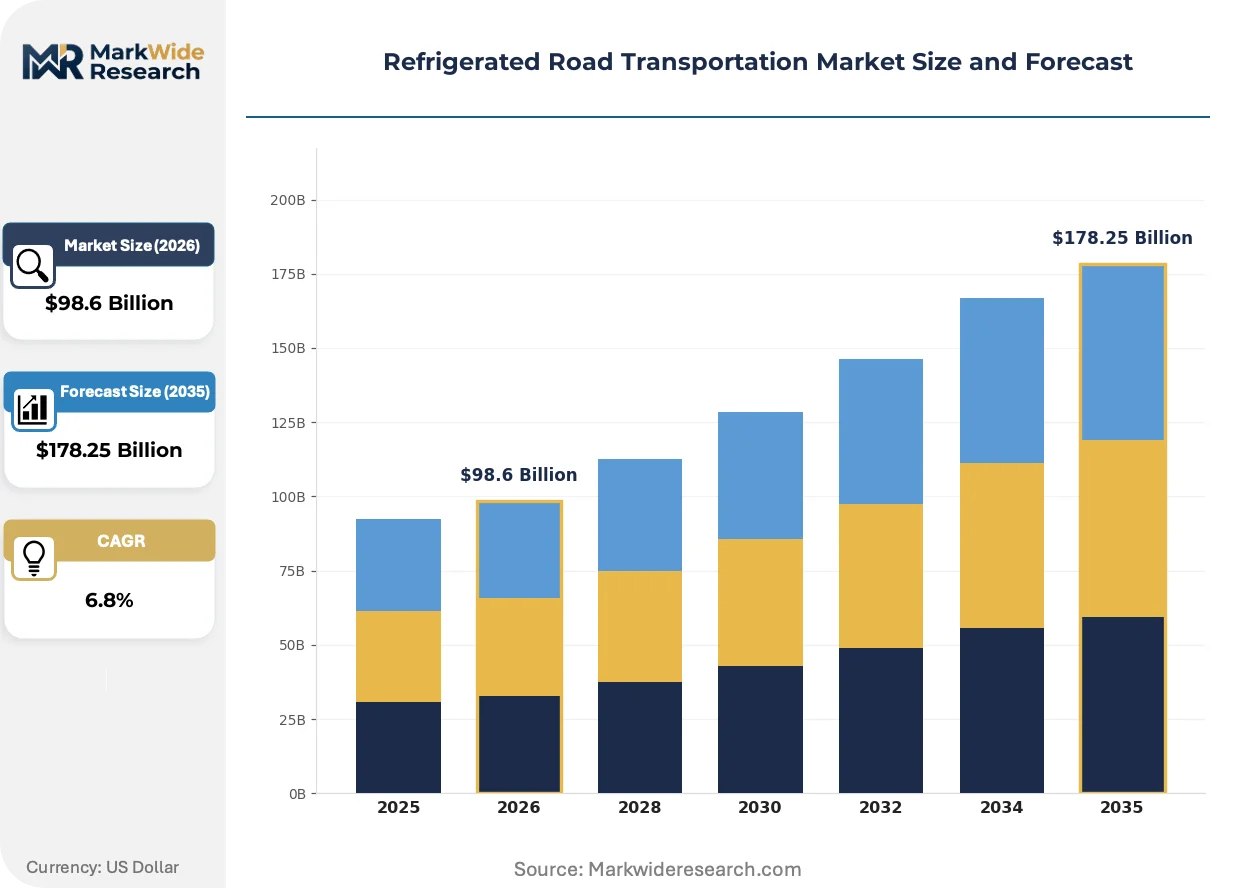
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Food, Dairy Products, Fresh Produce, Pharmaceuticals Technology: Reefer Vehicles, Refrigerated Containers, Insulated Trailers, Active Systems End User: Food & Beverage Industry, Healthcare Sector, Retail Chains, Logistics Providers Delivery Mode: Direct Delivery, Intermodal Transport, Scheduled Routes, Express Shipping |
| Companies Covered | Stevens Transport, Marten Transport, Prime Inc., NFI, Leonard's Express, C.R. England, Hirschbach Motor Lines, Day & Ross, KLLM Transport Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Road Transportation Market Strategic Shifts
Digital cold chain verification and zero-emission powertrains are converging to redefine equipment specifications and service-level agreements across temperature-controlled logistics.
Phase-change material thermal storage is expanding into pharmaceutical last-mile applications where payload density and temperature stability outweigh energy consumption penalties. Specialty pharmacy distributors and direct-to-patient delivery services are adopting PCM-equipped vans for same-day biologics transport. This technology is expanding into routes where conventional compressor-based systems face reliability constraints or noise restrictions.
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles are mandating CO2 reductions that cascade into refrigeration unit efficiency requirements. Manufacturers must redesign reefer compressors and insulation systems to avoid eroding tractor fuel economy gains. Foodservice distribution fleets operating across California, Oregon, and Washington face the steepest compliance acceleration timelines.
Buyer procurement of refrigerated transport capacity is fragmenting from annual contracted lanes toward spot-market flexibility with real-time temperature visibility. Large food retailers and pharmaceutical distributors now unbundle dedicated fleet commitments in favor of dynamic routing platforms that aggregate verified carrier capacity. This pattern is most pronounced in the Northeast corridor where lane density supports algorithmic load matching.
Refrigerated Road Transportation Market Segmentation
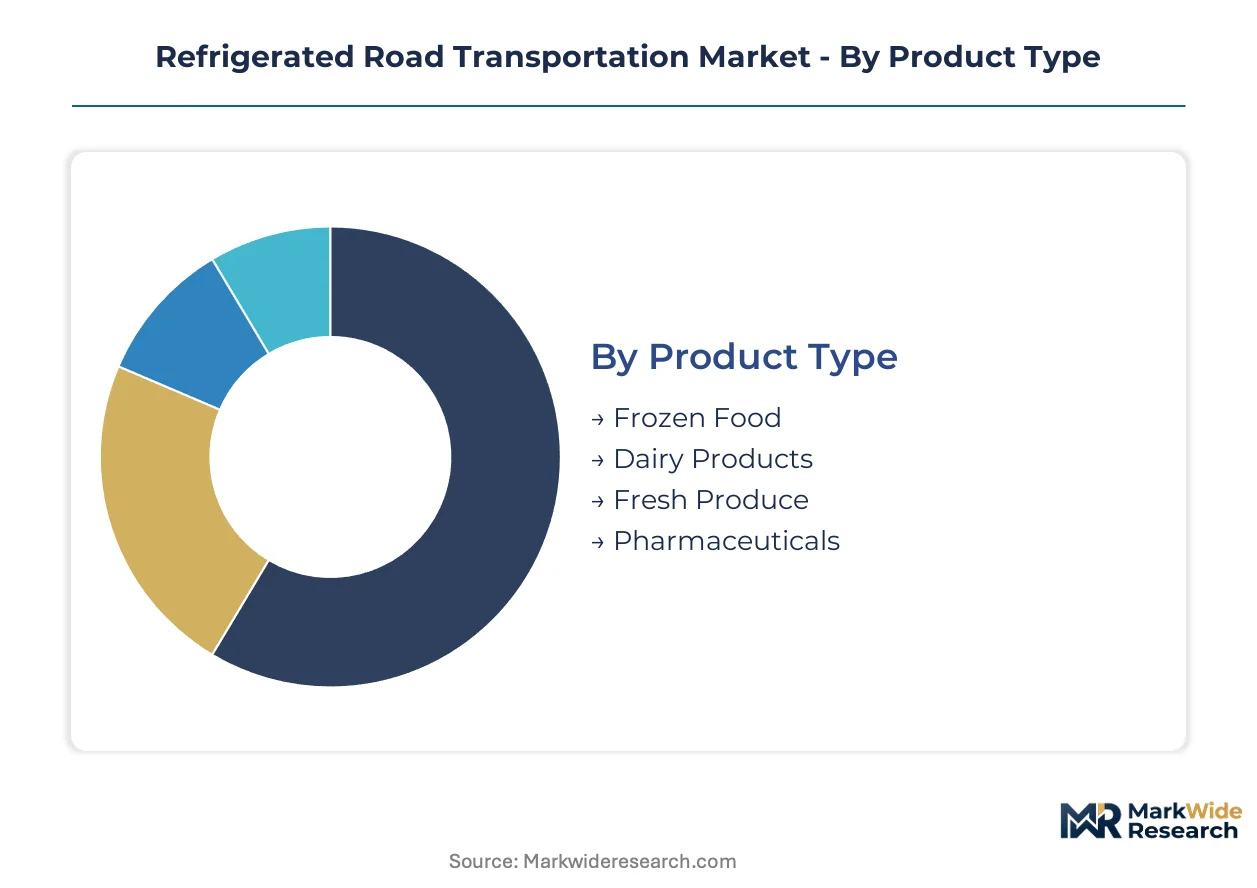
Segmentation in refrigerated road transportation reveals how equipment specifications, cargo requirements, and service models fragment procurement decisions. Fleet operators align asset configurations against temperature bands, regulatory jurisdictions, and customer compliance documentation needs.
Product Type:
Product temperature requirements dictate insulation specifications, cooling system sizing, and monitoring protocol intensity across fleet deployment decisions.
- Frozen Food:Cargo maintained below minus 18 degrees Celsius requires continuous compressor operation and reinforced thermal barriers. US food retail consolidation into regional distribution hubs concentrates frozen freight volume across Midwest and Southeast corridors.
- Pharmaceuticals:Biologics and cell therapies demand GDP-compliant cold chains with real-time temperature logging and excursion alert systems. Healthcare sector procurement tightening around FDA documentation standards accelerates specialized fleet investment.
- Dairy Products:Chilled transport between 2 and 6 degrees Celsius dominates short-haul distribution networks serving fluid milk and cheese processing facilities.
- Fresh Produce:Respiration-active cargo requires controlled atmosphere capabilities and rapid precooling integration at origin points.
Frozen food leads on scale; pharmaceuticals leads on momentum.
Technology:
Equipment technology selection hinges on route length, payload density, and regulatory compliance timelines rather than upfront capital cost alone.
- Reefer Vehicles:Integrated truck-and-trailer systems with dedicated compressor units dominate medium-haul pharmaceutical and foodservice distribution. California Air Resources Board zero-emission mandates pull forward electric reefer replacement cycles for in-state operators.
- Active Systems:Compressor-based cooling with telematics integration commands premium positioning through continuous temperature verification and predictive maintenance guarantees. Large pharmaceutical distributors specify active systems for GDP-compliant lanes.
- Refrigerated Containers:Intermodal-capable units bridge road and rail segments for bulk frozen commodities moving between coastal ports and inland processing centers.
- Insulated Trailers:Passive thermal protection without active cooling serves short-haul dairy and produce routes where dwell times remain minimal.
Reefer vehicles leads on scale; active systems leads on momentum.
End User:
End-user procurement patterns diverge between contract-dedicated capacity and dynamic spot-market sourcing based on inventory strategy and compliance risk tolerance.
- Food & Beverage Industry:Manufacturers and distributors of perishable goods generate baseline refrigerated transport demand through fixed-route distribution networks. Food safety modernization requirements elevate documentation standards for temperature excursion reporting.
- Healthcare Sector:Pharmaceutical manufacturers and specialty pharmacy distributors impose stringent GDP compliance and real-time visibility requirements. Biologics cold chain expansion concentrates procurement among carriers with dedicated healthcare certifications.
- Retail Chains:Grocery and mass merchandiser consolidation into regional hub-and-spoke networks reshapes lane density and dedicated fleet economics.
- Logistics Providers:Third-party cold chain operators aggregate shipper demand across multiple temperature bands and compliance tiers.
Food & beverage industry leads on scale; healthcare sector leads on momentum.
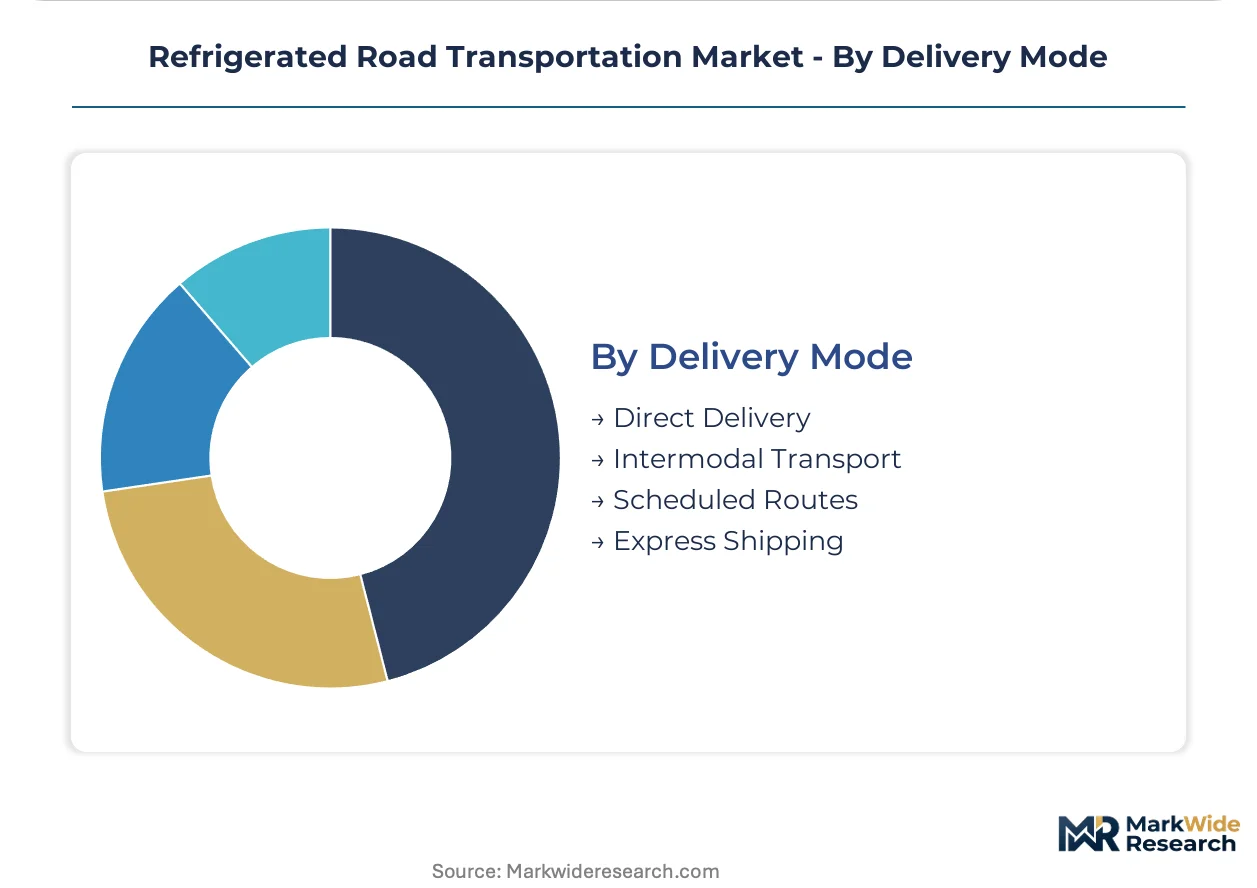
Delivery Mode:
Service level selection reflects trade-offs between inventory carrying cost, temperature risk exposure, and transportation spend optimization.
- Scheduled Routes:Fixed-day recurring service underpins food retail replenishment and pharmaceutical distribution to hospital systems. Route density economics favor dedicated fleet deployment over brokered capacity.
- Express Shipping:Time-definite delivery with temperature guarantee commands premium pricing for biologics and clinical trial materials. Direct-to-patient specialty pharmacy growth accelerates same-day cold chain requirements.
- Direct Delivery:Point-to-point service without intermediate handling suits high-value pharmaceutical shipments requiring chain-of-custody documentation.
- Intermodal Transport:Rail-truck combinations reduce line-haul cost for bulk frozen commodities moving across extended distances.
Scheduled routes leads on scale; express shipping leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The refrigerated road transportation industry traces its modern scale to post-war American interstate development, where frozen food retail expansion demanded dedicated temperature-controlled freight networks across continental distances.
United States
Food retail consolidation into regional distribution hubs concentrates frozen freight volume across Midwest and Southeast corridors. The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles mandate CO2 reductions that cascade into refrigeration unit efficiency requirements. California's Central Valley agricultural processing clusters and Chicago's intermodal rail terminals anchor national cold chain throughput.
Germany
Pharmaceutical exports from Rhine-Ruhr manufacturing centers drive GDP-compliant temperature-controlled logistics demand across European lanes. The EU F-Gas Regulation accelerates hydrofluorocarbon phase-down schedules for reefer unit manufacturers. Frankfurt's cargo airport integration with road networks supports high-value pharmaceutical distribution to Southern and Eastern European markets.
China
E-commerce fresh grocery penetration in tier-one cities expands last-mile refrigerated delivery requirements. The country's dual carbon goals under MEE oversight push fleet operators toward electric reefer trials in Beijing and Shanghai. Yangtze River Delta cold storage hubs connect seafood processing in Zhejiang with inland distribution networks.
India
Horticultural export growth from Maharashtra and Gujarat generates demand for refrigerated trucking to Mumbai and Mundra ports. FSSAI food safety modernization requirements elevate temperature documentation standards for dairy and pharmaceutical shipments. Bangalore's biologics manufacturing corridor concentrates specialized cold chain investment for clinical trial materials.
Brazil
Soybean and beef export logistics from Mato Grosso and Paraná rely on refrigerated road connections to Santos port terminals. ANVISA pharmaceutical distribution regulations tighten chain-of-custody requirements for temperature-sensitive vaccines. São Paulo's urban consolidation centers reshape last-mile cold chain economics for supermarket distribution.
Refrigerated Road Transportation Market Competitive Environment
The competitive structure tilts toward dedicated fleet operators with specialized cold chain infrastructure over general freight brokers. Tier-one carriers maintain premium positioning through temperature-control certifications and pharmaceutical GDP compliance, while mid-tier operators compete on lane density and equipment availability. Strategic archetypes include integrated pharmaceutical specialists, foodservice distribution dedicated fleets, and multi-temperature regional operators. Consolidation through fleet acquisition and electric reefer partnership programs represent dominant competitive moves.
Among North American dedicated refrigerated carriers, Marten Transport, C.R. England, and Prime Inc. exemplify contrasting strategic positions within the tiered competitive landscape. Marten Transport occupies a position emphasizing specialized cold chain network density across continental lanes. C.R. England represents the driver development and temperature-control training archetype. Prime Inc. anchors the integrated fleet maintenance and downtime reduction positioning within the refrigerated segment.
| Leading Market Players |
|---|
| Stevens Transport |
| Marten Transport |
| Prime Inc. |
| NFI |
| Leonard's Express |
| C.R. England |
| Hirschbach Motor Lines |
| Day & Ross |
| KLLM Transport Services |
| Others |
Value Chain & Pricing Dynamics
Captive fleet maintenance networks anchor pricing power for tier-one refrigerated carriers, integrating compressor service capabilities that reduce third-party dependency and sustain premium rate positioning against brokered spot capacity. This backward integration into after-sales service infrastructure allows dedicated cold chain operators to bundle uptime guarantees with transport pricing, extracting margin from pharmaceutical and foodservice accounts where temperature excursion liability concentrates procurement decisions.
Pricing Analysis
Bundled service contracts with guaranteed temperature compliance command premium positioning over unbundled spot-market transactions, with pharmaceutical distributors paying differential rates for GDP-certified active systems versus standard reefer units. Price differentiation separates carriers with real-time telematics integration from those offering basic temperature logging, while California's Advanced Clean Trucks mandates intensify cost compression in the electric reefer tier as fleet operators absorb compliance premiums. Food retail chains exhibit highest price sensitivity through dynamic routing platforms that algorithmically match loads against verified carrier capacity, whereas specialty pharmacy direct-to-patient services accept elevated rates for express cold chain guarantees.
Supply Chain Analysis
Lithium-ion cell supply rests on concentrated production clusters in China, South Korea, and Japan, exposing electric reefer manufacturers to battery procurement shocks when raw material processing faces export restrictions. Compressor units, insulation panels, and telematics hardware draw from automotive component networks anchored in Germany, Mexico, and the United States, with refrigerant chemistry transitions under the Kigali Amendment elevating input cost volatility. Single-source vulnerability in battery supply creates fleet procurement risk, while distribution runs through regional equipment dealer networks that service depot-based maintenance contracts for multi-unit operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Phase 3 greenhouse gas standards and California Air Resources Board mandates accelerate equipment replacement cycles and consolidate procurement among compliant fleet operators.
For Market Incumbents: Extend pharmaceutical GDP certification coverage into last-mile urban delivery corridors before compact electric reefer specialists capture biologics direct-to-patient growth. Anchor backward integration into electric compressor diagnostics training to offset refrigeration technician scarcity that threatens maintenance network expansion. Defend lane density economics in Midwest and Southeast food retail corridors against dynamic routing platforms by embedding temperature excursion insurance into contract rates. For New Entrants and Emerging Players: Electric reefer telematics platforms offer a technology-first wedge into pharmaceutical express shipping, where real-time temperature verification gaps persist among legacy carriers. Target urban last-mile routes in Northeast corridor cities where lane density supports algorithmic load matching and regulatory pressure favors zero-emission mandates. Pursue white-label fleet partnerships with specialty pharmacy distributors seeking captive cold chain capacity without asset ownership. For Investors and Strategic Acquirers: Roll-up economics work for regional multi-temperature operators because pharmaceutical compliance certification scarcity and driver training infrastructure create barriers that favor scaled platforms. Five-to-ten-year viability hinges on electric reefer total-cost-of-ownership trajectories crossing diesel baselines as battery supply diversifies. Watch California's Advanced Clean Trucks enforcement timelines as the inflection signal for accelerated fleet electrification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Reefer Fleet Conversion | EPA Phase 3 compliance deadlines force accelerated capital deployment toward zero-emission refrigeration units. |
| Pharmaceutical GDP Certification Investment | FDA documentation standards tighten procurement qualification for biologics cold chain carriers. |
| Telematics Platform Integration | IoT sensor convergence enables predictive maintenance guarantees that differentiate premium service tiers. |
| Regional Distribution Hub Expansion | Food retail consolidation into Midwest and Southeast corridors concentrates dedicated refrigerated capacity demand. |
| Refrigeration Technician Training Programs | Specialized electric reefer diagnostic skills scarcity threatens fleet maintenance network scalability. |
Study Parameters
Direct dialogue with fleet operations directors, pharmaceutical logistics procurement managers, reefer unit manufacturing engineers, and cold chain insurance underwriters grounded qualitative findings in operational reality across temperature-controlled transport networks. Secondary validation drew from EPA regulatory filings, California Air Resources Board enforcement data, FDA food safety modernization guidance, and USDA agricultural transport protocol updates. Bottom-up carrier capacity modeling and top-down pharmaceutical shipment volume estimates triangulated market size and growth trajectory.
Segment-level projections across product temperature bands, equipment technology tiers, and end-user compliance requirements fed into analytical frameworks spanning the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory mandate phase-in schedules, and electric reefer adoption curve modeling. Industry-specific inputs included biologics cold chain expansion rates, food retail hub-and-spoke network restructuring patterns, and refrigerant chemistry transition cost impacts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery supply diversification timelines and multi-jurisdiction regulatory harmonization progress. Projections reflect assumptions around electric infrastructure buildout rates, technician training program output, and pharmaceutical distributor unbundling of dedicated fleet commitments. A small set of named triggers—California zero-emission mandate enforcement stringency, lithium-ion cell production geographic diversification, and FDA GDP documentation standard revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
India Intra-City Logistics Market