
 India Private Banking Market | 2026-2036
India Private Banking Market Size, Share, and Industry Trends Forecast 2026-2036
India Private Banking Market Outlook
Market Context
Product bundling across wealth management and estate planning is hardening as the dominant configuration pattern for HNWI acquisition. HDFC Bank leverages its branch network density to anchor family office relationships across Mumbai and Delhi. ICICI Bank competes through technology leadership in digital portfolio analytics, while Kotak Mahindra Bank specializes in proprietary alternative investment funds for ultra-affluent clients.
Technical Definition and Structural Segments
India private banking denotes specialized financial services delivered to individuals with investable assets exceeding prescribed thresholds, encompassing discretionary portfolio management, trust structuring, and cross-border tax coordination through dedicated relationship managers. By client type, Ultra High Net Worth Individuals command the deepest margin pools due to complexity-driven fee structures, whereas family offices represent the fastest-growing category as promoter families professionalize capital deployment. Service type segmentation reveals wealth management as the mature revenue core, with investment advisory gaining share as SEBI registration requirements filter out unqualified distributors.
Regulatory Framework and Outlook
RBI governs prudential norms for bank-led private banking subsidiaries, while SEBI regulates investment advisors and portfolio managers through stringent qualification and disclosure mandates; the Income Tax Department's enhanced scrutiny of offshore structures shapes product design toward domestic tax-transparent vehicles. BIS certification requirements for financial product distribution add compliance layers that favor scaled institutions over boutique operators. Stakeholders must monitor evolving central bank digital currency frameworks and their implications for custody and settlement infrastructure serving affluent clients.
Market Dynamics
SEBI's tightened investment advisor regulations are compressing the distributor base while concentrating advisory relationships within licensed portfolio managers and bank-led private banking subsidiaries.
Growth Catalysts
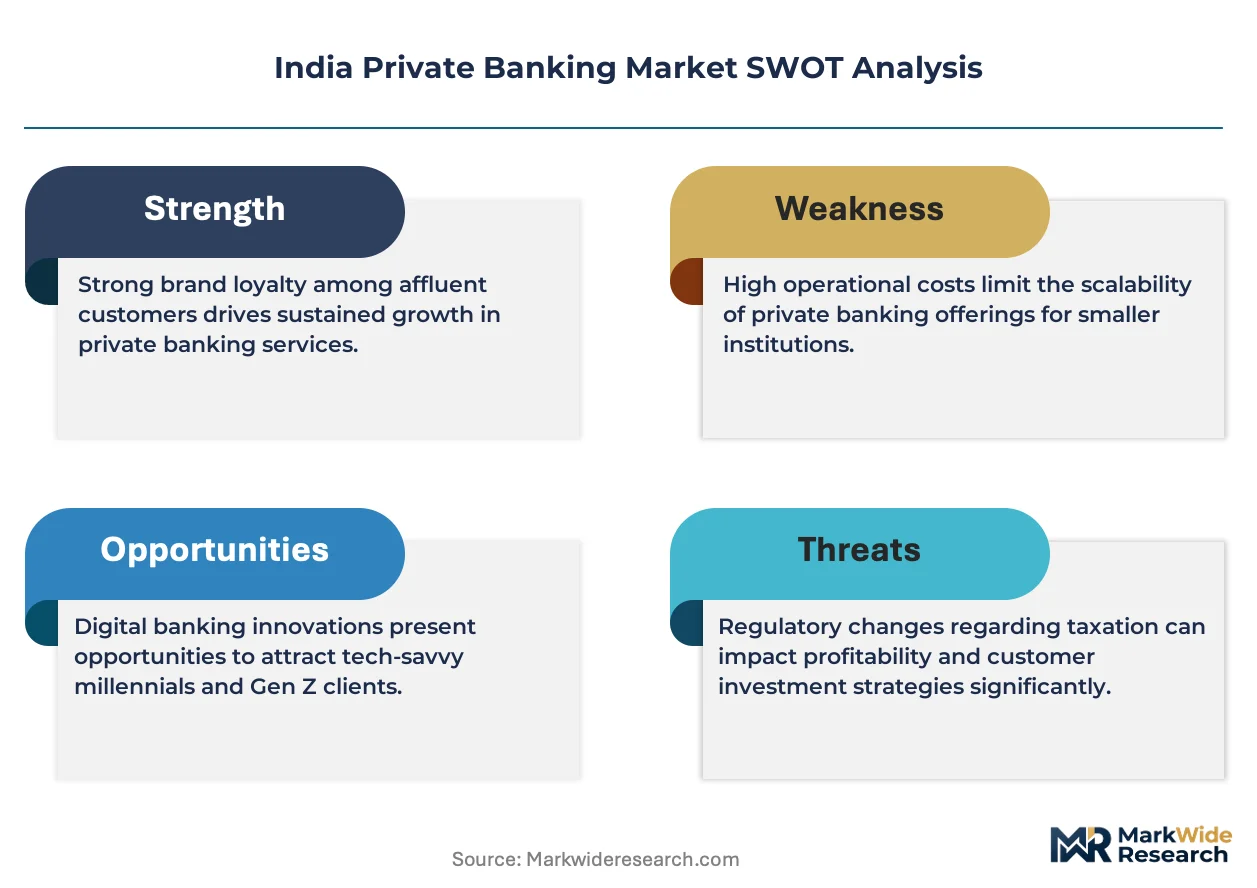
- Regulatory consolidation:SEBI's mandatory RIA registration filters out unqualified distributors, pushing HNWI assets toward licensed private banking platforms with compliant advisory infrastructure.
- Family office professionalization:Promoter families across Mumbai and Delhi are converting informal capital pools into structured family offices requiring integrated wealth management and estate planning services.
- Alternative investment democratization:RBI's wealth management licensing norms enable bank subsidiaries to offer proprietary AIF structures previously accessible only through offshore channels.
Market Restraints
- Compliance cost escalation:BIS certification requirements for financial product distribution impose fixed-cost burdens that disproportionately constrain boutique advisory firms.
- Talent concentration risk:Relationship managers with cross-border structuring expertise cluster in Mumbai and Delhi, leaving secondary cities underserved.
- Domestic vehicle limitations:Income Tax Department scrutiny of offshore trusts pushes demand toward tax-transparent domestic structures with narrower investment universes.
Strategic Opportunities
- Tier-II city penetration:Ahmedabad, Hyderabad, and Pune exhibit HNWI density growth without proportional private banking branch presence.
- Digital-first advisory models:Technology platforms enabling remote portfolio analytics and virtual family office governance reduce dependency on physical relationship manager coverage.
- CBDC infrastructure positioning:RBI's central bank digital currency pilot creates first-mover advantage for custody and settlement solutions targeting affluent clients.
Industry Challenges
- Cross-border coordination complexity:Estate structuring spanning Indian domestic assets and offshore holdings requires synchronized legal, tax, and regulatory expertise across multiple jurisdictions.
- Legacy system integration friction:Bank-led private banking units face technical debt from core banking platforms that resist seamless portfolio management system interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Private Banking Market |
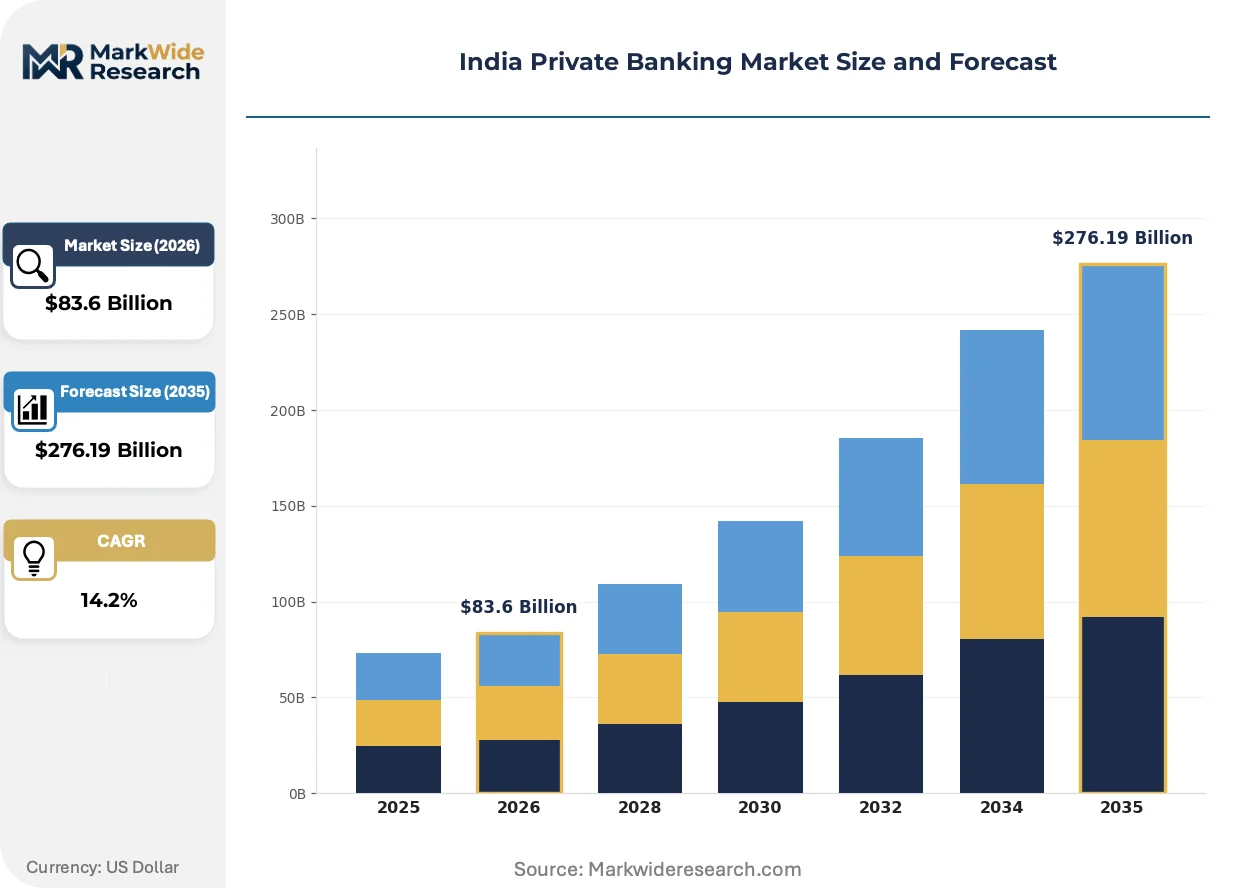
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $276.19 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: High Net Worth Individuals, Ultra High Net Worth Individuals, Corporates, Family Offices Service Type: Wealth Management, Investment Advisory, Estate Planning, Tax Advisory Product Type: Mutual Funds, Fixed Deposits, Insurance, Securities Distribution Channel: Branch Network, Online Platforms, Private Banking Representatives, Third-Party Advisors |
| Companies Covered | HDFC Bank, ICICI Bank, Kotak Mahindra Bank, Axis Bank, IndusInd Bank, Yes Bank, Federal Bank, IDFC FIRST Bank, HSBC Private Banking India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Private Banking Market Strategic Shifts
Technology convergence and regulatory digitization are compressing service delivery timelines while elevating transparency expectations among ultra-affluent clients.
Artificial intelligence-driven portfolio analytics is consolidating discretionary management workflows by automating risk attribution and scenario modeling. Ultra HNWIs and single-family offices in Mumbai are adopting these tools for real-time liquidity monitoring across illiquid alternative allocations. The technology is consolidating relationship manager bandwidth toward high-touch advisory conversations rather than routine reporting tasks.
SEBI's enhanced disclosure mandates for portfolio managers are compressing fee opacity and accelerating fee compression across advisory relationships. Registered investment advisors must now report granular performance attribution and conflict-of-interest disclosures quarterly. Family offices are responding by renegotiating fee structures toward pure advisory or hybrid models with explicit performance benchmarks.
Virtual family office governance platforms are displacing quarterly in-person board meetings as the coordination default for dispersed promoter families. Digital document execution, virtual investment committees, and encrypted communication channels enable real-time decision-making across geographic time zones. This shift is most visible among technology-sector founders with assets distributed across India, Singapore, and Dubai.
India Private Banking Market Segmentation
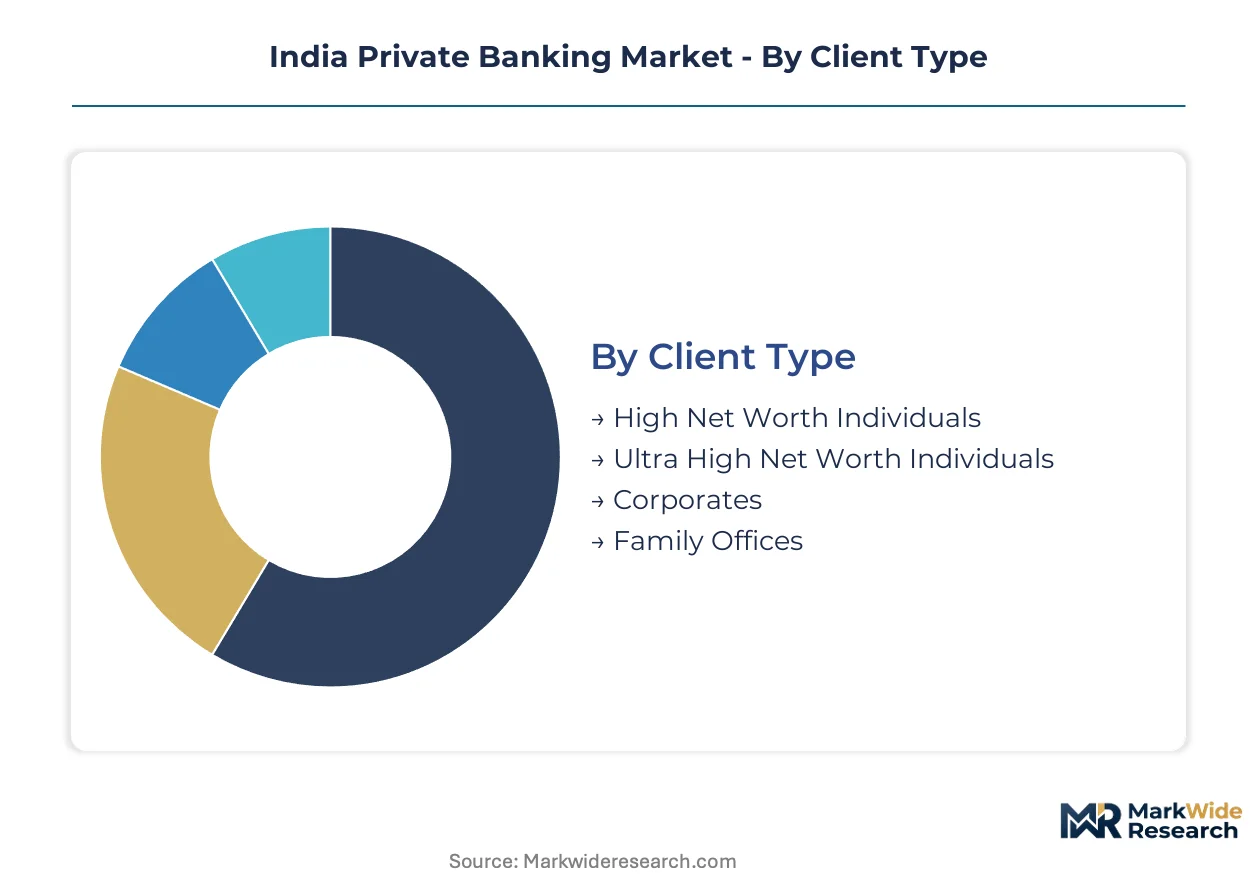
Segmentation in Indian private banking reveals how regulatory frameworks and wealth concentration patterns shape service configurations. Distinct client profiles, distribution economics, and product architectures create tiered margin structures across the market.
Client Type:
Asset thresholds and complexity tolerance determine advisory relationships and fee structures across client categories.
- Ultra High Net Worth Individuals:Clients with investable assets exceeding prescribed thresholds command complexity-driven fee structures. Mumbai and Delhi concentrate demand for cross-border estate structuring and alternative investment access through dedicated relationship managers.
- Family Offices:Promoter families professionalizing capital deployment represent the category gaining share fastest. SEBI's tightened investment advisor regulations accelerate conversion from informal capital pools into structured governance vehicles requiring integrated wealth and estate planning.
- High Net Worth Individuals:Affluent clients below ultra-HNWI thresholds drive volume through standardized wealth management products with lower customization requirements.
- Corporates:Treasury management and promoter wealth separation create demand for institutional-grade custody and liquidity solutions alongside personal wealth services.
Ultra High Net Worth Individuals lead on scale; Family Offices lead on momentum.
Service Type:
Regulatory licensing requirements and margin profiles differentiate service delivery models across advisory and execution functions.
- Wealth Management:Discretionary portfolio management constitutes the mature revenue core with established fee structures. RBI's wealth management licensing norms elevate entry barriers, concentrating activity within bank-led subsidiaries with compliant infrastructure.
- Investment Advisory:SEBI's mandatory RIA registration filters unqualified distributors, pushing assets toward licensed platforms. Granular performance attribution disclosures compress fee opacity and accelerate structural shifts toward pure advisory or hybrid benchmarked models.
- Estate Planning:Trust structuring and succession coordination face Income Tax Department scrutiny of offshore vehicles, redirecting demand toward domestic tax-transparent structures with narrower jurisdictional scope.
- Tax Advisory:Cross-border coordination complexity requires synchronized expertise across multiple jurisdictions, creating specialist scarcity and premium pricing power.
Wealth Management dominates current revenue; Investment Advisory shows the steepest expansion trajectory.
Product Type:
Risk-return profiles and distribution economics shape product penetration across client wealth tiers.
- Securities:Direct equity and debt instruments anchor discretionary portfolios for sophisticated clients. Digital portfolio analytics platforms automate risk attribution, consolidating relationship manager bandwidth toward high-touch advisory.
- Mutual Funds:BIS certification requirements for financial product distribution add compliance layers favoring scaled institutions with established fund distribution infrastructure.
- Fixed Deposits:Conservative capital preservation vehicles retain relevance for risk-averse segments and liquidity buffers within diversified allocations.
- Insurance:Wealth-linked protection products integrate with estate planning for succession security and tax-efficient wealth transfer mechanisms.
Securities command the deepest margins; Mutual Funds deliver the broadest reach.
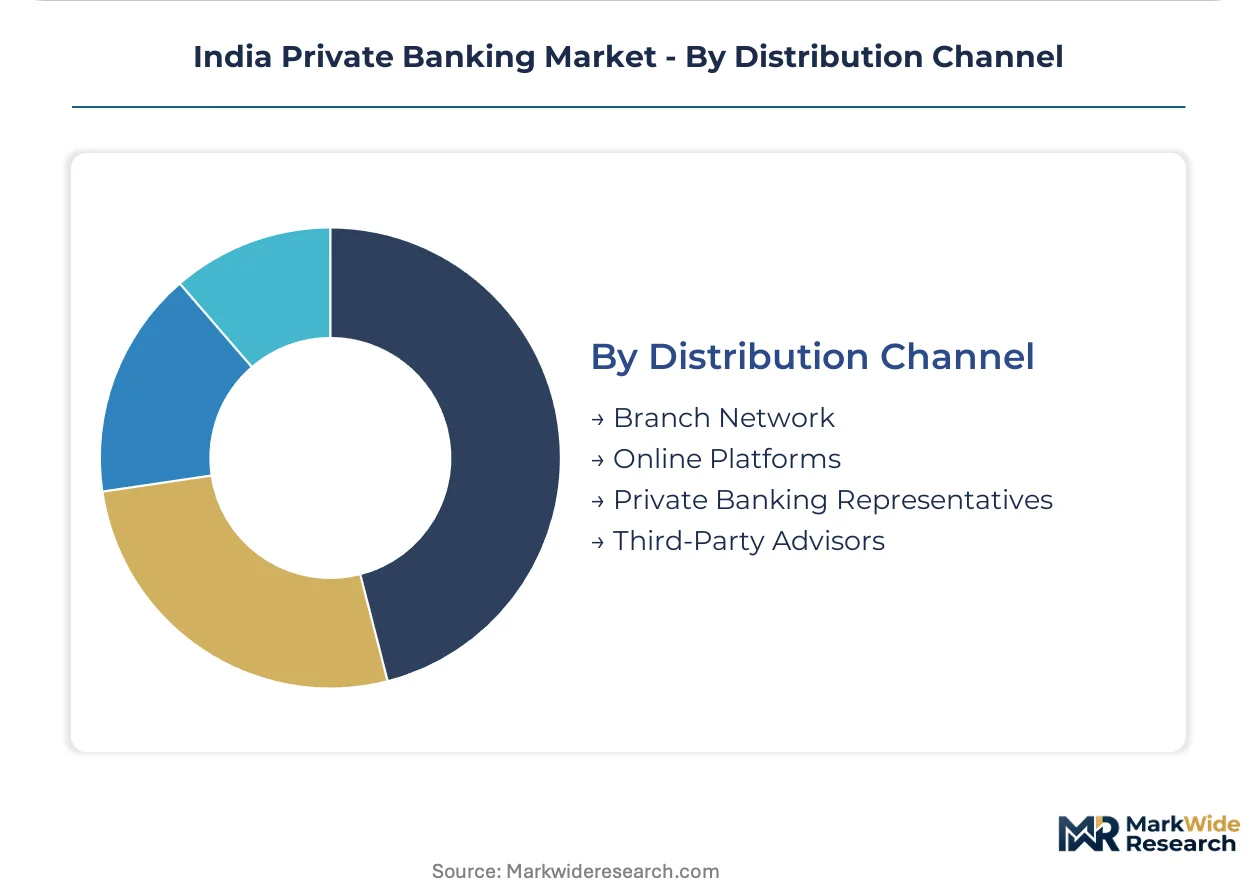
Distribution Channel:
Physical presence density and technology integration determine client acquisition economics across coverage models.
- Branch Network:HDFC Bank leverages physical density to anchor family office relationships across Mumbai and Delhi. Fixed-cost infrastructure creates scale advantages for high-touch onboarding and complex product distribution.
- Private Banking Representatives:Relationship managers with cross-border structuring expertise cluster in primary cities, leaving Ahmedabad, Hyderabad, and Pune underserved relative to HNWI density growth.
- Online Platforms:ICICI Bank competes through technology leadership in digital portfolio analytics, reducing dependency on physical coverage for routine monitoring and reporting functions.
- Third-Party Advisors:SEBI's tightened regulations compress the unlicensed distributor base, redirecting flows toward compliant bank-led and registered investment advisor channels.
Branch Network retains relationship primacy; Online Platforms capture efficiency gains fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private banking in India traces its institutional roots to colonial-era merchant banking houses in Mumbai and Kolkata, evolving through nationalization waves into today's licensed wealth management framework governed by RBI and SEBI.
Maharashtra
Mumbai concentrates India's deepest ultra-HNWI pools, with promoter families from manufacturing and financial services driving demand for cross-border estate structuring. SEBI's portfolio manager regulations require granular quarterly disclosure, elevating compliance infrastructure investments among Bandra-Kurla Complex advisory firms. The Mumbai-Delhi corridor anchors relationship manager talent clusters with specialized expertise in offshore trust coordination.
Delhi-NCR
Delhi's family offices professionalize capital deployment from real estate and infrastructure wealth accumulated across NCR satellite cities. RBI's wealth management licensing norms restrict proprietary AIF distribution to bank-led subsidiaries with adequate net worth thresholds. Gurugram and Noida house expanding advisory operations serving technology-sector founders with assets distributed across Singapore and Dubai.
Gujarat
Ahmedabad and Surat exhibit HNWI density growth from diamond trading and textile manufacturing without proportional private banking branch presence. BIS certification requirements for financial product distribution favor scaled institutions with established compliance infrastructure over boutique operators. The diamond bourse ecosystem generates demand for liquidity management and trade-finance-linked wealth structures.
Karnataka
Bangalore's technology founder wealth drives adoption of virtual family office governance platforms for dispersed asset coordination. SEBI's mandatory RIA registration redirects advisory flows from unlicensed distributors toward compliant bank-led channels. The city's startup exit ecosystem creates first-generation wealth requiring integrated estate planning and philanthropic structuring services.
Telangana
Hyderabad's pharmaceutical and real estate wealth concentrates in Jubilee Hills and Banjara Hills enclaves with limited dedicated relationship manager coverage. The Income Tax Department's enhanced scrutiny of offshore structures shapes product design toward domestic tax-transparent vehicles. Family offices here lag Mumbai and Delhi in professionalization, presenting advisory platform expansion opportunities.
India Private Banking Market Competitive Environment
Premium-margin players sit above commodity-margin players across advisory complexity and client asset thresholds. The market structures around three tiers: bank-led subsidiaries with branch network density, technology-forward digital platforms, and boutique specialists in alternative investments. Two dominant competitive moves concentrate activity: regulatory consolidation through SEBI licensing compliance and technology investments in portfolio analytics automation.
Within the bank-led tier, HDFC Bank, ICICI Bank, and Kotak Mahindra Bank occupy positions defined by distinct strategic vectors. HDFC Bank exemplifies branch-network-anchored relationship models across Mumbai and Delhi. ICICI Bank represents technology-forward positioning in digital portfolio analytics. Kotak Mahindra Bank sits within the alternative investment specialist archetype, serving ultra-affluent clients through proprietary fund structures.
| Leading Market Players |
|---|
| HDFC Bank |
| ICICI Bank |
| Kotak Mahindra Bank |
| Axis Bank |
| IndusInd Bank |
| Yes Bank |
| Federal Bank |
| IDFC FIRST Bank |
| HSBC Private Banking India |
| Others |
Value Chain & Pricing Dynamics
Ultra-affluent client demand for seamless cross-border estate coordination is compressing advisory margins and forcing private banking subsidiaries to consolidate compliance infrastructure investments, which in turn hardens fee differentiation across complexity tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates advisory relationships, with complexity-driven fees separating ultra-HNWI bespoke mandates from standardized wealth management products. Price differentiation rests on SEBI registration status and cross-border structuring capability. Cost compression in the mid-tier is intensifying because unlicensed distributor attrition redirects price-sensitive HNWI assets toward compliant platforms. Family offices show least price sensitivity due to governance complexity premiums, while first-generation technology founders exhibit highest sensitivity to advisory fee transparency.
Supply Chain Analysis
Regional distribution centers for relationship manager talent cluster in Mumbai and Delhi, creating hub-and-spoke coverage patterns that leave secondary cities underserved. Geographic supply concentration centers on India, Singapore, and Dubai for cross-border trust administration and offshore coordination expertise. Raw material dependencies include licensed portfolio management software, encrypted virtual governance platforms, and BIS-certified financial product distribution infrastructure. Single-source vulnerability runs through Mumbai-Delhi talent clusters for offshore structuring specialists. Distribution runs through bank-led branch networks for high-touch onboarding, with digital platforms capturing efficiency gains in portfolio analytics delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's private banking market functions as a geographic-arbitrage play where SEBI's tightened RIA registration requirements create compliance cost differentials between Mumbai-Delhi incumbents and Tier-II city challengers.
For Market Incumbents: Extend proprietary alternative investment fund capabilities into Ahmedabad, Hyderabad, and Pune before regional competitors establish compliant infrastructure. Consolidate relationship manager talent clusters through retention structures targeting cross-border estate specialists. Defend against technology-forward entrants by embedding AI-driven portfolio analytics into existing high-touch advisory workflows.
For New Entrants and Emerging Players: SEBI's mandatory RIA registration in India opens a window for digital-first advisory platforms to capture price-sensitive HNWI segments underserved by branch-heavy incumbents. Target technology-sector first-generation wealth in Bangalore and Hyderabad with virtual family office governance solutions. Penetrate through hybrid fee models combining pure advisory with transparent performance benchmarks.
For Investors and Strategic Acquirers: Asymmetric upside sits with boutique advisory firms possessing SEBI-registered portfolio management licenses and established family office relationships in Tier-II cities. Long-term viability hinges on regulatory compliance scalability rather than asset accumulation velocity. Watch RBI central bank digital currency pilot expansion as custody infrastructure inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| SEBI Registration Compliance | RIA licensing filters unqualified distributors and concentrates HNWI assets within compliant platforms. |
| Alternative Investment Fund Launch | Proprietary AIF structures capture ultra-affluent demand previously served through offshore channels. |
| Virtual Family Office Platform | Digital governance tools displace quarterly board meetings for dispersed promoter families across time zones. |
| Tier-II City Branch Expansion | Ahmedabad and Hyderabad HNWI density growth outpaces relationship manager coverage. |
| CBDC Custody Infrastructure | RBI digital currency pilot creates first-mover advantage for settlement solutions targeting affluent clients. |
Study Parameters
Multiple input streams — primary interviews with private banking heads, SEBI-registered investment advisors, and family office executives; secondary validation through RBI circulars, SEBI disclosure filings, and Income Tax Department guidance — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured relationship manager capacity constraints, advisory fee renegotiation patterns, and alternative investment fund distribution economics. Secondary sources encompassed regulatory gazettes, portfolio manager registration databases, and wealth management licensing records.
Historical growth patterns were cross-referenced against panel input from advisory platform operators to anchor projections across the analysis window. Segmentation dimensions modeled include client wealth tier, service type licensing status, product risk classification, and distribution channel density. CAGRs were derived from asset flow trajectories and fee structure evolution rather than macroeconomic extrapolation. Industry-specific forecast inputs incorporated SEBI registration attrition rates and family office professionalization velocity.
Revisions become necessary when regulatory enforcement intensity shifts, central bank digital currency frameworks expand, or cross-border tax coordination treaties materially alter estate structuring economics. Forecasts reflect documented assumptions around compliance cost trajectories and talent concentration patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Wealth Management Software Market