
 Merchant Banking Services Market | 2026-2036
Merchant Banking Services Market Size, Share, and Industry Trends Forecast 2026-2036
Merchant Banking Services Market Intelligence
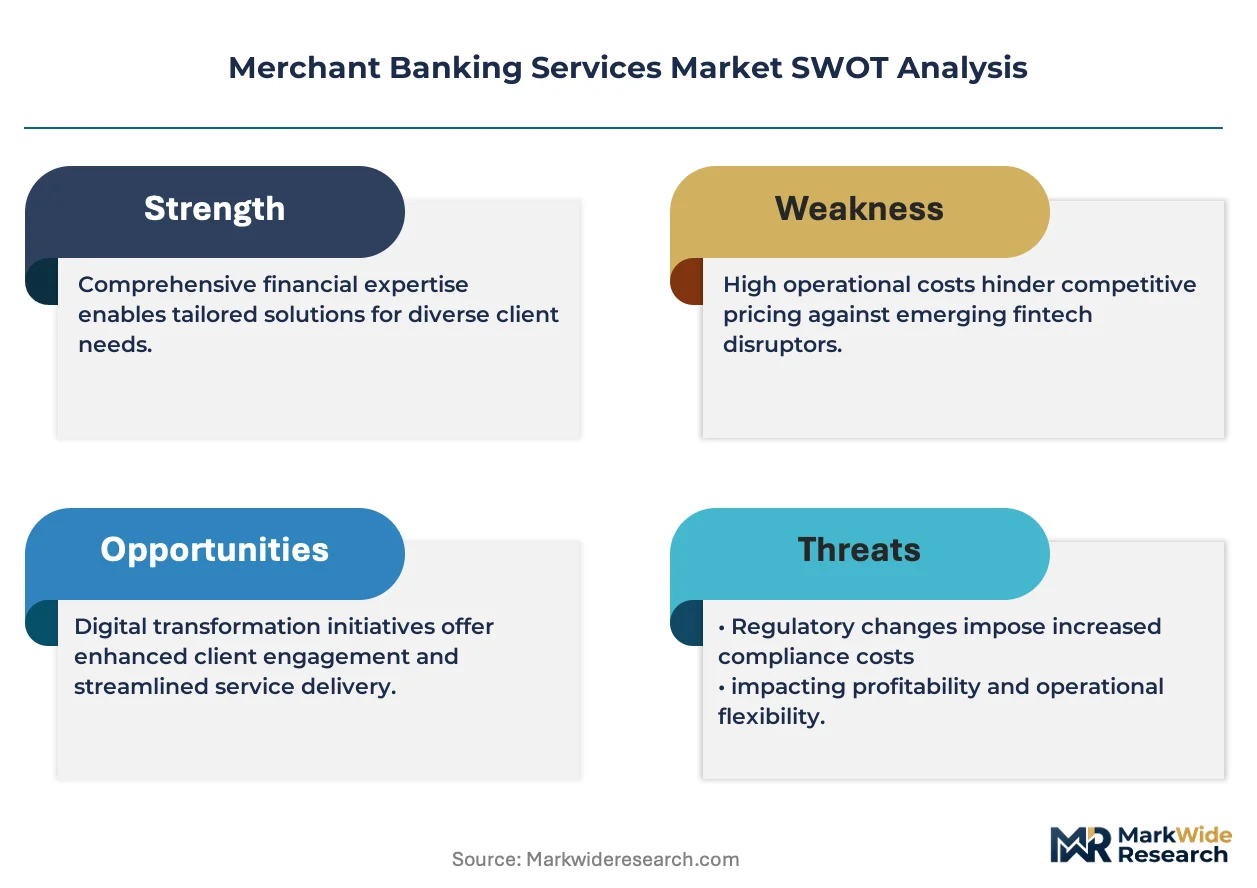
Unbundled advisory modules are replacing full-service retainers as the default engagement pattern, and this shift is pivoting how mid-market clients evaluate provider relationships. Goldman Sachs Group Inc leverages its balance sheet strength to anchor complex structured finance transactions across energy transitions. Lazard Ltd specializes in independent M&A advisory, competing on conflict-free positioning against integrated banking platforms. JPMorgan Chase & Co dominates debt underwriting distribution, extending its network effects into private credit origination.
Merchant banking services encompass capital-raising, strategic advisory, and balance-sheet solutions delivered to corporate and institutional clients, typically involving bespoke security structuring and long-dated risk commitment rather than standardized retail products. These functions require dedicated industry coverage teams, regulatory capital allocation, and issuer-specific covenant design to execute principal transactions. Advisory services and M&A retainers command premium pricing and recurring revenue visibility, while project-based engagement models in equity issuance face compression from automation in documentation and roadshow logistics. Debt financing sustains volume leadership across client types, though performance-based fee structures in restructuring mandates capture outsized margin pools during credit cycle stress.
SEC disclosure requirements and the EU's CSRD framework shape reporting obligations for listed issuers, expanding due diligence scope and liability exposure for underwriters and advisors. The Federal Reserve's prudential standards and Basel III implementation constrain leverage ratios and risk-weighted asset treatment, directly affecting balance-sheet-intensive merchant banking activities. Stakeholders must monitor how central bank liquidity transitions and evolving climate disclosure mandates reshape capital commitment capacity and fee sustainability across service lines.
Market Dynamics
Unbundled advisory modules are displacing full-service retainers as private equity sponsors and corporate treasurers demand granular, transaction-specific expertise rather than relationship-based coverage. This fragmentation is compressing pricing power for integrated platforms while elevating specialists with targeted sector depth.
Growth Catalysts
- CSRD Disclosure Mandates:The EU's Corporate Sustainability Reporting Directive is expanding due diligence scope for cross-border M&A, driving advisory mandates for ESG-linked financing structures and climate risk integration.
- Private Credit Expansion:Direct lending funds are capturing share from traditional bank syndications, creating origination partnerships and co-underwriting opportunities for merchant banking platforms with distribution networks.
- Energy Transition Capital:Project finance pipelines for renewables and grid infrastructure are generating structured commodity and tax equity advisory demand across North America and Europe.
Market Restraints
- Basel III Capital Constraints:Risk-weighted asset treatment for long-dated principal commitments is tightening balance-sheet capacity, forcing selective deployment into highest-return mandates.
- Documentation Automation:Natural language processing tools are commoditizing equity issuance roadshow logistics and prospectus drafting, eroding fee pools for standardized capital-raising.
- Regulatory Arbitrage Compression:Cross-border regulatory divergence between SEC disclosure requirements and EU AI Act provisions is elevating compliance costs for multinational advisory engagements.
Strategic Opportunities
- Climate Disclosure Tailwinds:The EU AI Act and expanding SEC climate rules are mandating scenario analysis and transition planning, opening advisory white space for specialized sustainability practices.
- Restructuring Cycle Positioning:Credit cycle stress in commercial real estate and leveraged lending is generating performance-based fee structures for distressed balance-sheet solutions.
- Technology Sector Convergence:Semiconductor and software clients are demanding integrated M&A and debt underwriting for cross-border carve-outs, favoring platforms with sector-dedicated coverage teams.
Industry Challenges
- Talent Scarcity in Structured Finance:Specialized covenant design and bespoke security structuring expertise is concentrating among senior practitioners, constraining team buildout velocity.
- Legacy System Integration:Proprietary risk management infrastructure from acquired platforms is creating data fragmentation, complicating real-time exposure monitoring across advisory and principal activities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Merchant Banking Services Market |
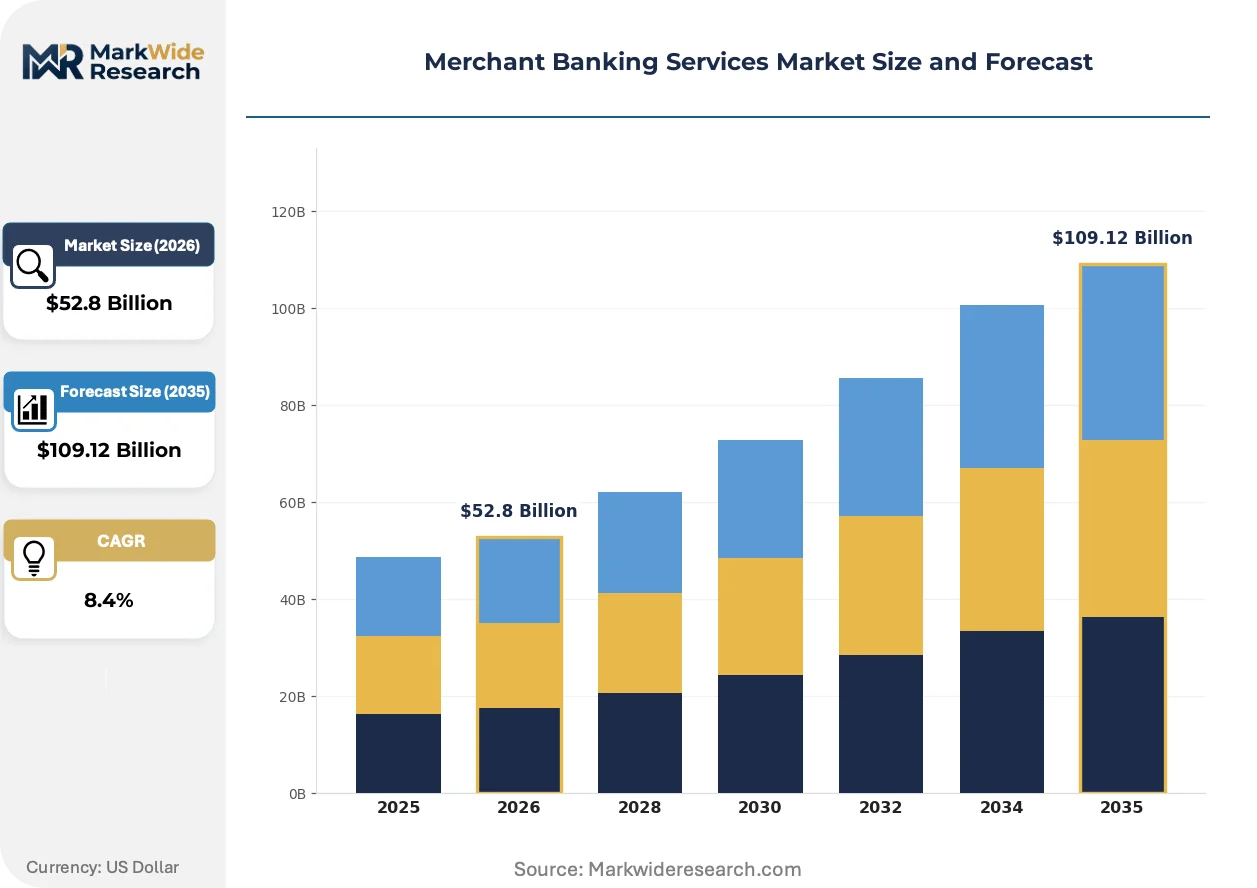
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mergers & Acquisitions, Debt Financing, Equity Issuance, Advisory Services Client Type: Corporations, Government Entities, High Net-Worth Individuals, Small & Medium Enterprises Industry Vertical: Energy, Technology, Real Estate, Manufacturing Engagement Model: Retainer-Based, Project-Based, Performance-Based, Hourly Billing |
| Companies Covered | JPMorgan Chase & Co, Bank of America Corporation, Goldman Sachs Group Inc, Morgan Stanley, HSBC Holdings plc, Royal Bank of Canada, China Merchants Bank, Industrial and Commercial Bank of China, Lazard Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Merchant Banking Services Market Strategic Shifts & Innovations
Generative tools and regulatory complexity are simultaneously compressing commoditized service lines and expanding premium advisory white space. Three developments are reconfiguring competitive positioning.
Natural language processing is automating document generation for standardized equity and debt issuances. Mid-market corporate issuers are adopting these tools for routine capital-raising, compressing fees for roadshow logistics and prospectus drafting. This automation is forcing merchant banks to redeploy junior talent toward bespoke structuring and complex covenant negotiation where judgment remains irreplaceable.
The EU AI Act's risk-based classification system is reshaping due diligence protocols for technology sector transactions. Automated decision-making systems in target companies now trigger enhanced algorithmic impact assessments, extending transaction timelines and elevating liability exposure for underwriters. European technology sponsors are responding by embedding AI governance specialists into deal teams preemptively.
Sponsor-backed financing is fragmenting procurement patterns across private equity portfolios. General partners are unbundling M&A advisory from financing execution, awarding mandates to conflict-free boutiques for sell-side processes while retaining integrated platforms for balance-sheet-intensive underwritings. This bifurcation is most visible in United States mid-market transactions where sponsor concentration has elevated bargaining power.
Merchant Banking Services Market Segmentation
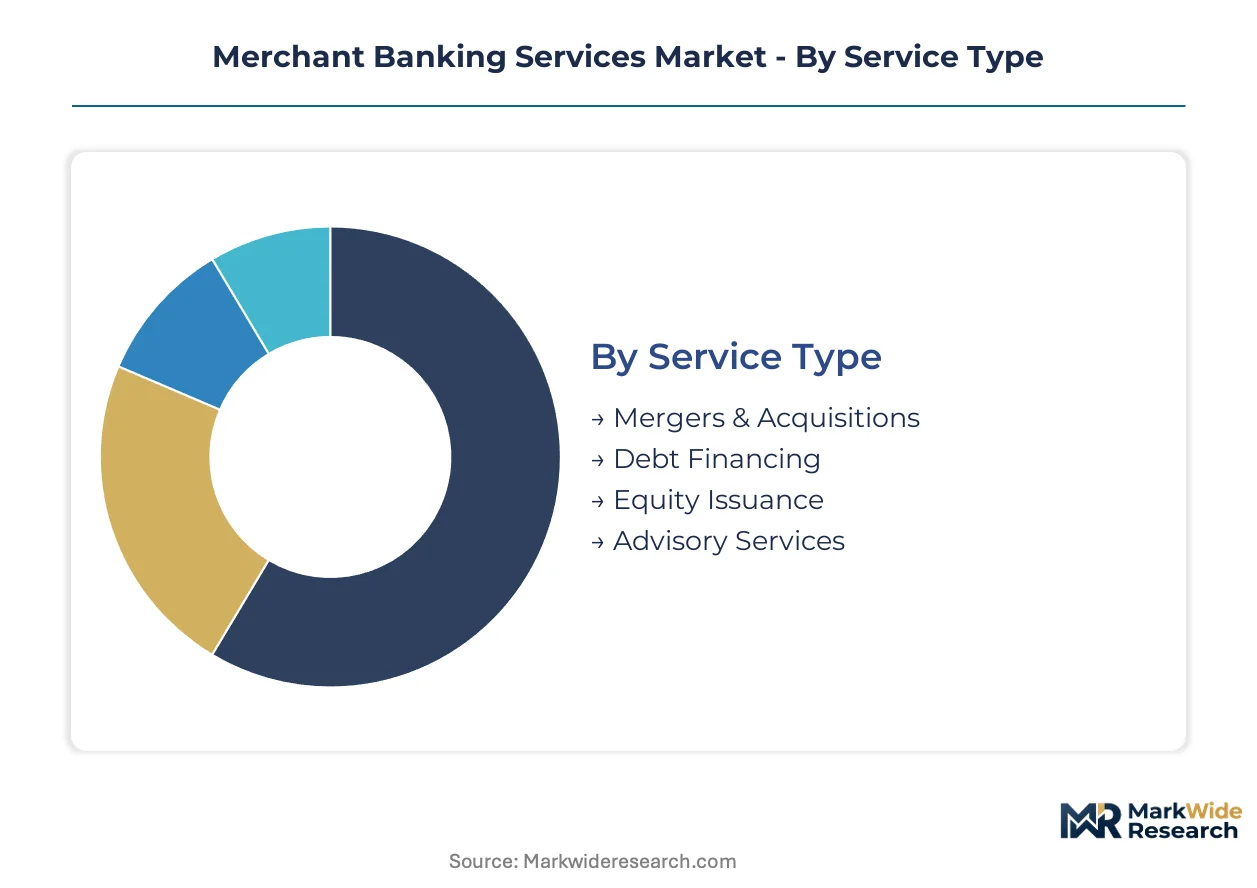
Merchant banking services fragment across four structural dimensions that determine pricing architecture, regulatory exposure, and talent deployment. Each segmentation axis reveals distinct margin profiles and competitive dynamics that reshape how platforms allocate capital and coverage resources.
Service Type:
SEC disclosure rules for underwriters and the EU AI Act's risk classification system impose divergent certification burdens across service lines, with principal transactions facing heavier capital treatment than advisory mandates.
- Mergers & Acquisitions:Complex transaction structuring involving fairness opinions, target valuation, and regulatory clearance navigation. Demand concentrates among technology sector sponsors in the United States pursuing cross-border carve-outs, driven by semiconductor consolidation mandates and software vertical integration imperatives.
- Debt Financing:Syndicated lending, private credit origination, and structured commodity facilities requiring balance-sheet commitment. Issuance volume clusters with private equity sponsors in sponsor-backed financing, constrained by Basel III leverage ratio requirements that tighten risk-weighted asset treatment for long-dated commitments.
- Equity Issuance:Capital-raising through initial public offerings, follow-ons, and convertible securities. Documentation automation via natural language processing tools is compressing fees for standardized roadshow logistics and prospectus drafting.
- Advisory Services:Strategic counsel on capital structure optimization, shareholder activism defense, and ESG-linked financing design. EU CSRD disclosure mandates are expanding due diligence scope for climate risk integration and transition planning advisory.
Debt Financing sits at the top of the volume ranking, with Advisory Services climbing the fastest.
Client Type:
Procurement patterns diverge sharply by counterparty sophistication, with institutional clients unbundling advisory modules while retail-facing segments retain bundled relationship pricing.
- Corporations:Strategic acquirers and capital-intensive issuers requiring integrated coverage teams. Energy transition project finance mandates from North American utilities and European grid operators are generating structured commodity and tax equity advisory demand.
- Private Equity Sponsors:General partners unbundling M&A advisory from financing execution, awarding sell-side mandates to conflict-free boutiques while retaining integrated platforms for underwritings. This bifurcation elevates bargaining power in United States mid-market transactions.
- Government Entities:Sovereign wealth funds and development finance institutions pursuing infrastructure and energy transition allocations. Procurement runs through multilateral framework agreements with extended diligence timelines.
- High Net-Worth Individuals:Family offices and single-family investment vehicles seeking bespoke wealth structuring and direct co-investment access. Relationship-based pricing persists against the unbundling trend visible in institutional segments.
Corporations anchor absolute fee generation, with Government Entities expanding most quickly on energy transition capital deployment.
Industry Vertical:
Sector coverage depth determines competitive positioning as clients demand transaction-specific expertise rather than generalist execution.
- Energy:Renewables project finance, grid infrastructure capital-raising, and transition risk advisory. Real estate debt stress in commercial mortgage-backed securities is generating restructuring mandates for distressed balance-sheet solutions.
- Technology:Semiconductor and software M&A, cross-border carve-outs, and algorithmic governance compliance under EU AI Act provisions. Automated decision-making systems in target companies trigger enhanced due diligence protocols.
- Real Estate:Commercial mortgage origination, REIT capital access, and distressed asset repositioning. Credit cycle stress in leveraged lending and office exposure is elevating performance-based fee structures.
- Manufacturing:Working capital facilities, supply chain finance, and industrial carve-out advisory. Automation in documentation is compressing margins for standardized capital-raising relative to bespoke structuring.
Energy commands the largest advisory fee pool, with Technology gaining share fastest on AI governance and semiconductor consolidation mandates.
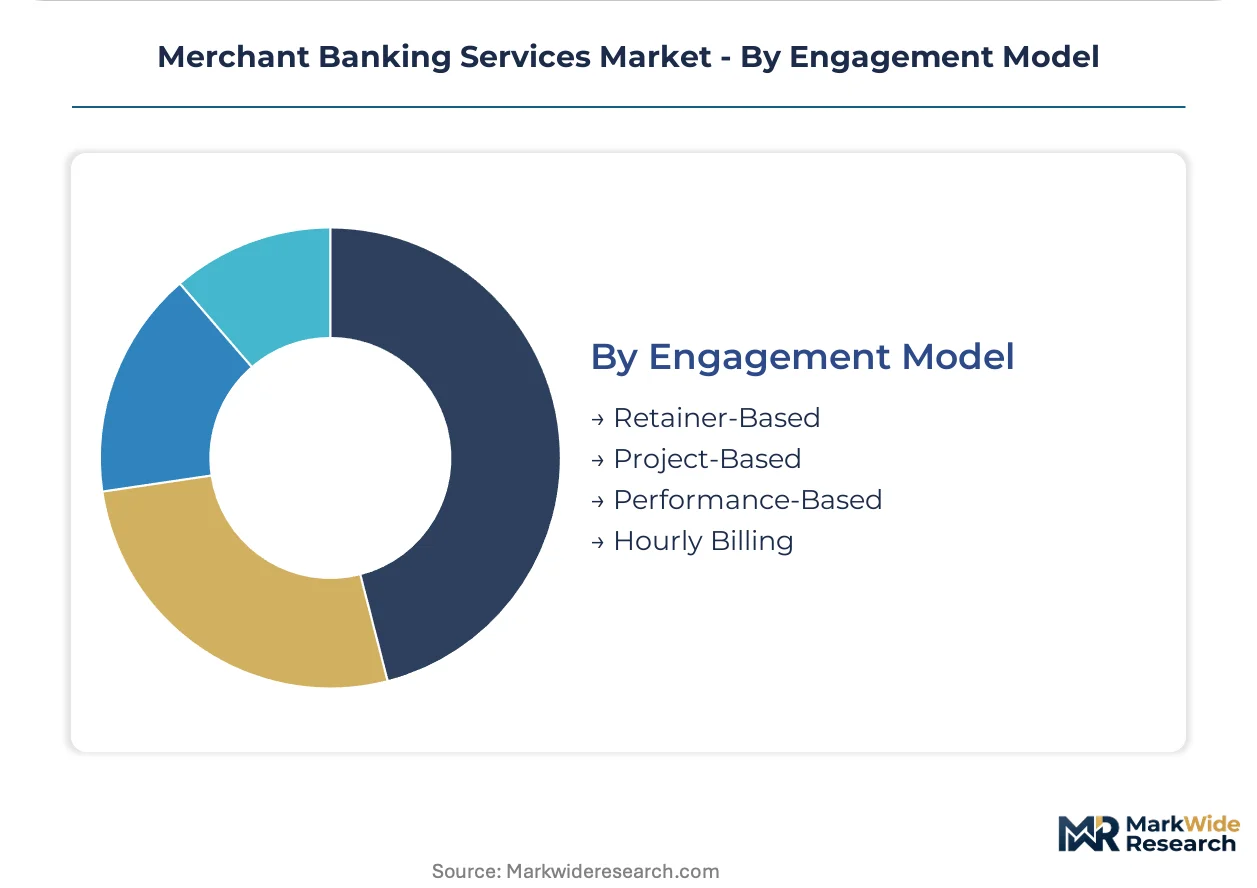
Engagement Model:
Fee architecture shapes revenue visibility and talent incentives, with performance structures capturing outsized returns during credit cycle stress.
- Retainer-Based:Recurring coverage fees for ongoing strategic counsel and relationship maintenance. Unbundling pressure from private equity sponsors is compressing pricing power for integrated platforms offering blanket coverage.
- Project-Based:Transaction-specific mandates with defined deliverables and timeline milestones. Equity issuance automation is eroding fee pools for standardized capital-raising while preserving premiums for complex covenant negotiation.
- Performance-Based:Contingent compensation tied to transaction completion, valuation achievement, or restructuring outcome. Commercial real estate distress and leveraged lending stress are expanding margin pools for distressed balance-sheet solutions.
- Hourly Billing:Time-based fees for regulatory advisory, diligence support, and special committee assignments. EU AI Act compliance and CSRD disclosure preparation are elevating utilization for specialized practitioners.
Project-Based structures dominate transaction volume, with Performance-Based fees expanding most steeply on restructuring cycle positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant banking services originated in the City of London during the 19th century, where merchant houses financed commodity trades and colonial infrastructure before evolving into today's advisory and capital-raising functions. The industry's geographic footprint now tracks private capital formation, regulatory sophistication, and cross-border deal flow intensity.
United States
Private equity sponsors in New York and Boston drive sponsor-backed financing volume, with mid-market buyout activity concentrating advisory demand. SEC disclosure requirements for underwriters shape liability exposure and due diligence scope for cross-border transactions. The technology corridor spanning San Francisco and Seattle generates semiconductor and software M&A mandates requiring integrated debt underwriting capabilities.
United Kingdom
London's historical position as a eurodollar trading center sustains deep syndicated lending and structured commodity finance expertise. The Financial Conduct Authority's prudential standards intersect with EU CSRD disclosure rules for firms with European operations, expanding climate risk advisory obligations. The Square Mile and Canary Wharf clusters host conflict-free boutiques competing with integrated platforms for sell-side M&A mandates.
Germany
Industrial conglomerates in the Rhine-Ruhr region and automotive suppliers in Baden-Württemberg demand bespoke covenant design for carve-out financings. BaFin implementation of Basel III leverage ratios constrains balance-sheet capacity for long-dated principal commitments. The Frankfurt financial center anchors debt underwriting distribution networks serving Mittelstein export manufacturers.
China
State-owned enterprises and technology champions in Shanghai and Shenzhen pursue cross-border listings and strategic acquisitions despite capital control frameworks. The People's Bank of China's macroprudential policies influence liquidity conditions for offshore bond issuance and project finance. The Yangtze River Delta manufacturing belt generates working capital facility demand from supply chain finance programs.
Singapore
Sovereign wealth funds and regional family offices deploy capital into Southeast Asian infrastructure and energy transition projects. The Monetary Authority of Singapore's fintech licensing regime supports digital asset custody and tokenized security structuring experiments. The Marina Bay financial district serves as a coordination hub for Indonesia and Vietnam project finance mandates.
Merchant Banking Services Market Key Industry Players
Premium-margin players sit above commodity-margin players across advisory specialization and balance-sheet commitment intensity, creating a tiered structure where independent boutiques capture conflict-sensitive mandates while integrated platforms dominate financing execution. The vendor base clusters around three archetypes: full-service universal banks with global distribution networks, independent advisory specialists competing on conflict-free positioning, and regional champions with dominant domestic market share. Consolidation pressures favor scale-driven M&A between mid-tier platforms seeking coverage team depth, while technology investments in documentation automation separate efficiency leaders from laggards.
Within the integrated banking tier, JPMorgan Chase & Co and Goldman Sachs Group Inc exemplify platforms leveraging balance-sheet strength to anchor complex structured transactions. Among independent specialists, Lazard Ltd occupies a position defined by M&A advisory purity without lending conflicts. These named entities represent strategic archetypes rather than exhaustive market coverage, with each sitting within broader competitive dynamics shaped by regulatory capital constraints and sponsor procurement fragmentation.
| Leading Market Players |
|---|
| JPMorgan Chase & Co |
| Bank of America Corporation |
| Goldman Sachs Group Inc |
| Morgan Stanley |
| HSBC Holdings plc |
| Royal Bank of Canada |
| China Merchants Bank |
| Industrial and Commercial Bank of China |
| Lazard Ltd |
| Others |
Cost & Logistics Intelligence
Natural language processing tools are compressing documentation costs for standardized equity issuances while simultaneously elevating premiums for bespoke covenant negotiation, concentrating pricing power among practitioners with irreplaceable structuring judgment. This technological bifurcation feeds back into talent deployment decisions across coverage teams, as platforms redirect junior resources toward commoditized workflows and reserve senior capacity for complex mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates engagement architecture, with premium tiers capturing conflict-free advisory mandates from private equity sponsors and economy tiers facing compression from automation in roadshow logistics. Price differentiation rests on sector coverage depth and balance-sheet commitment scale, with technology sector mandates commanding premiums against standardized manufacturing facilities. Cost compression in economy-tier equity issuance is intensifying because natural language processing tools commoditize prospectus drafting. Corporate treasurers exhibit highest price sensitivity for routine capital-raising, while private equity sponsors prioritize execution certainty over fee minimization for complex carve-outs.
Supply Chain Analysis
Domestic-content mandates in EU CSRD disclosure preparation and SEC climate reporting are reshaping sourcing patterns for specialized advisory talent, elevating demand for practitioners with dual-jurisdiction certification. Supply concentration centers on the United States, United Kingdom, and Germany, where regulatory sophistication and private capital formation create clustering effects for covenant design expertise. Raw material dependencies include senior structured finance practitioners, ESG disclosure specialists, and technology sector coverage bankers. Single-source vulnerability concentrates among boutiques with narrow sector focus and limited succession depth. Distribution runs through sponsor procurement committees, corporate treasury functions, and sovereign wealth fund investment divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in advisory services and performance-based restructuring mandates, justified by automation-driven cost compression in standardized capital-raising workflows that frees capacity for premium-tier deployment.
For Market Incumbents: To counter unbundling pressure from private equity sponsors, integrated platforms should deepen sector coverage teams in semiconductor and software verticals while embedding ESG disclosure specialists preemptively into deal workflows. Capacity addition in Frankfurt and Singapore anchors European and Asian energy transition advisory demand. Certification investment in EU AI Act risk classification protocols differentiates due diligence offerings against automated compliance tools. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for algorithmic governance advisory boutiques to capture technology sector mandates from conflict-sensitive sponsors. White-space targets include cross-border carve-out financing for Mittelstein manufacturers and climate risk integration for real estate debt restructuring. A go-to-market angle emphasizing pure advisory positioning without lending conflicts penetrates sponsor-backed sell-side processes most effectively. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier platforms with legacy infrastructure but strong sector coverage depth in energy transition and technology verticals. Long-term viability favors acquirers who can absorb coverage teams and modernize risk management systems without client attrition. The signal to watch is sponsor procurement committee composition shifts toward unbundled mandate awarding.| Strategic Initiative | Industry Significance |
|---|---|
| Advisory Practice Acquisition | Captures conflict-sensitive mandates from private equity sponsors unbundling M&A and financing execution. |
| ESG Disclosure Specialist Buildout | Addresses EU CSRD mandates expanding due diligence scope for climate risk integration advisory. |
| Technology Sector Coverage Expansion | Secures semiconductor and software M&A mandates requiring integrated debt underwriting capabilities. |
| Documentation Automation Investment | Compresses costs for standardized equity issuance while redeploying talent toward bespoke structuring. |
| Restructuring Cycle Positioning | Captures performance-based fees from commercial real estate distress and leveraged lending stress. |
Research Approach
Multiple input streams — primary interviews with managing directors, coverage team heads, and sponsor procurement officers; secondary validation through SEC filings, EU regulatory submissions, and private placement memoranda; and transaction database reconciliation — were triangulated against bottom-up segment builds and top-down market sizing. Coverage team heads at integrated platforms and independent boutiques provided mandate flow visibility. Sponsor procurement officers revealed unbundling patterns and mandate awarding criteria. Secondary sources included Basel III implementation disclosures, CSRD preparatory guidance, and technology sector M&A announcement tracking.
Data-stream reconciliation anchored the forecast framework across service type, client sophistication tier, industry vertical, and engagement model dimensions throughout the projection horizon. CAGRs were derived from segment-level buildups validated against macroeconomic scenario overlays specific to private capital formation and central bank liquidity transitions. Industry-specific forecast inputs incorporated sponsor dry powder deployment rates and energy transition capital commitment pipelines.
Revisions become necessary when central bank liquidity transitions accelerate, regulatory divergence between SEC and EU frameworks widens, or sponsor procurement patterns shift toward fully automated advisory tools. Forecasts reflect assumptions about talent mobility constraints and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Brazil Retail Banking Market
Banking
Banking Credit Analytics Market
Banking
Disaster Recovery in Banking Market
Banking
China Data Analytics in Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Digital LED Retail Banking Market
Banking
Germany Neobanking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
US Retail Banking Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Banking CRM Software Market
Banking
Data Analytics in Banking Market
Banking
Australia Neobanking Market
Banking
Blockchain in Banking Market
Banking
ATM Market
Banking
Germany Banking As a Service Market