
 Asia Pacific Wealth Management Market | 2026-2036
Asia Pacific Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wealth Management Market Outlook
Platform licensing revenue is rewriting profitability structures across the Asia Pacific wealth management landscape. UBS Group AG leverages its Swiss private banking heritage to anchor ultra-high-net-worth relationships across Singapore and Hong Kong. HSBC Holdings plc sustains mass-affluent penetration through its integrated retail-to-wealth channel architecture spanning mainland China corridors. DBS Group competes aggressively on digital onboarding velocity, capturing next-generation investors across Southeast Asian growth markets.
Asia Pacific wealth management encompasses the professional advisory and asset allocation services delivered to individuals and institutions seeking capital preservation, growth, and intergenerational transfer across diverse currency, regulatory, and tax jurisdictions. The discipline integrates portfolio construction, risk analytics, estate structuring, and compliance navigation across fragmented Asian regulatory environments. Investment advisory services command premium pricing where cross-border complexity intersects with family office sophistication. Portfolio management functions increasingly automate rebalancing and tax-loss harvesting through algorithmic engines. Private banks retain margin dominance in ultra-high-net-worth segments where relationship depth and discretion override cost sensitivity.
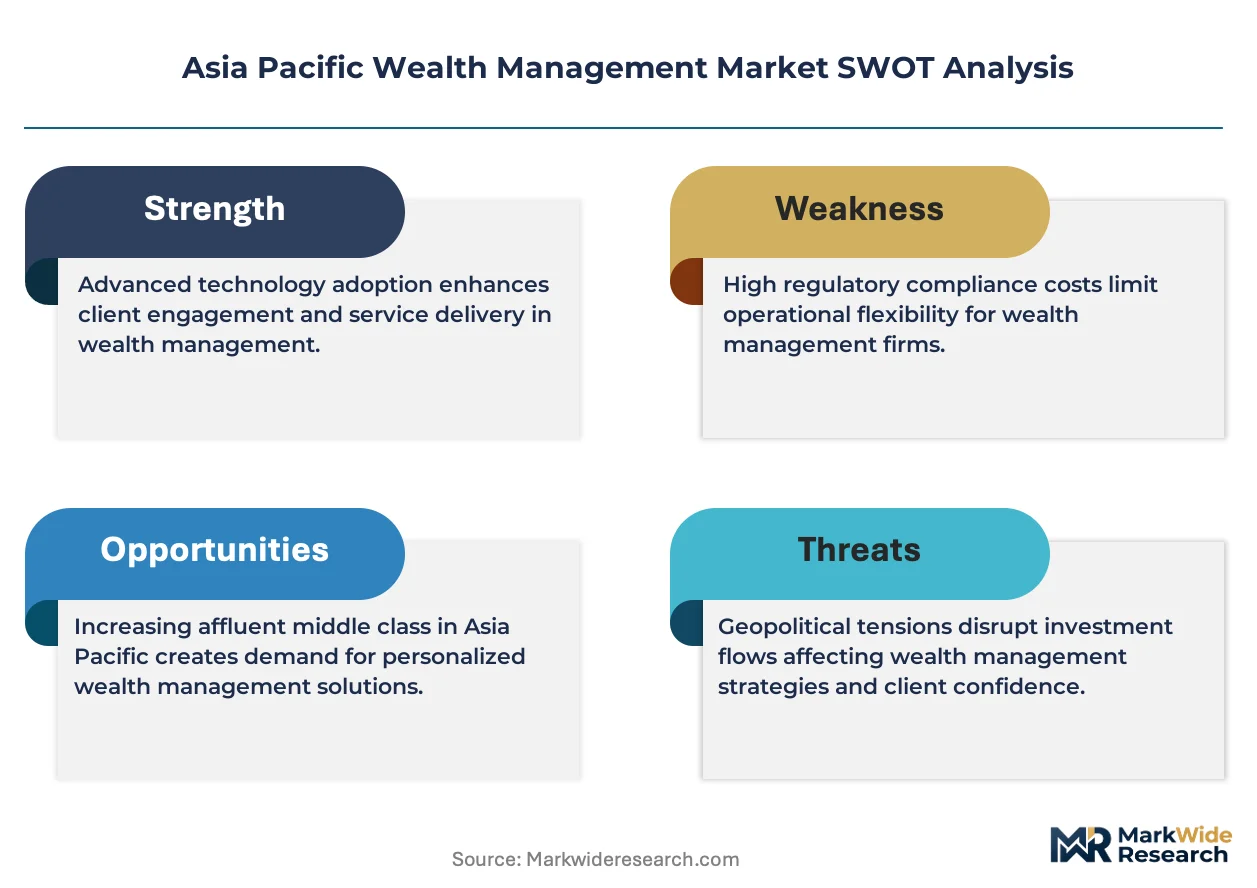
Monetary Authority of Singapore licensing requirements enforce minimum capital thresholds and fit-and-proper standards for wealth managers operating within the city-state's jurisdiction. Australia's Australian Securities and Investments Commission governs financial advice through strict best-interest duties and fee disclosure regimes affecting superannuation-linked wealth products. Japan's Financial Services Agency imposes segregation and custody rules on investment management contracts that shape product packaging for domestic retail investors. Stakeholders must weigh regulatory arbitrage opportunities against escalating compliance costs as each major Asian jurisdiction tightens consumer protection frameworks independently.
Market Dynamics
Platform licensing revenue is compressing traditional fee structures across Asia Pacific wealth management, forcing incumbents to rebuild margin architecture around digital delivery infrastructure rather than relationship density alone.
Growth Catalysts
- India's SEBI investment adviser framework:Licensing expansion is professionalizing retail advisory penetration, channeling household savings into regulated portfolio products at scale.
- Singapore private banking hub status:Monetary Authority of Singapore custody and tax transparency rules are attracting regional family office consolidation, concentrating cross-border asset flows.
- Algorithmic rebalancing engines:Automated tax-loss harvesting and portfolio optimization are reducing marginal cost-to-serve for mass-affluent segments across Southeast Asian digital platforms.
Market Restraints
- Compliance cost escalation:Fragmented regulatory frameworks across ASEAN jurisdictions are inflating operational overhead for cross-border wealth managers without harmonization mechanisms.
- Relationship manager scarcity:Talent concentration in Singapore and Hong Kong SAR is constraining service expansion into secondary Southeast Asian markets.
- Fiduciary liability expansion:Australia's ASIC best-interest duties and India's SEBI adviser obligations are compressing product distribution margins through fee disclosure mandates.
Strategic Opportunities
- Vietnam and Philippines mass-affluent penetration:Underbanked high-net-worth households in these markets present first-mover advantages for digitally native wealth platforms.
- Superannuation-linked advisory in Australia:Mandatory retirement contribution flows create captive asset pools requiring sophisticated lifecycle investment strategies.
- Artificial intelligence and natural language processing convergence:Hybrid advisory models combining algorithmic portfolio construction with human relationship oversight are opening premium service tiers.
Industry Challenges
- Legacy core banking integration:Incumbent wealth managers face multi-year system migration timelines to unify customer data across siloed retail and private banking infrastructure.
- Cross-border data localization:Divergent privacy requirements across China, India, and ASEAN markets are fragmenting client analytics capabilities and compliance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wealth Management Market |
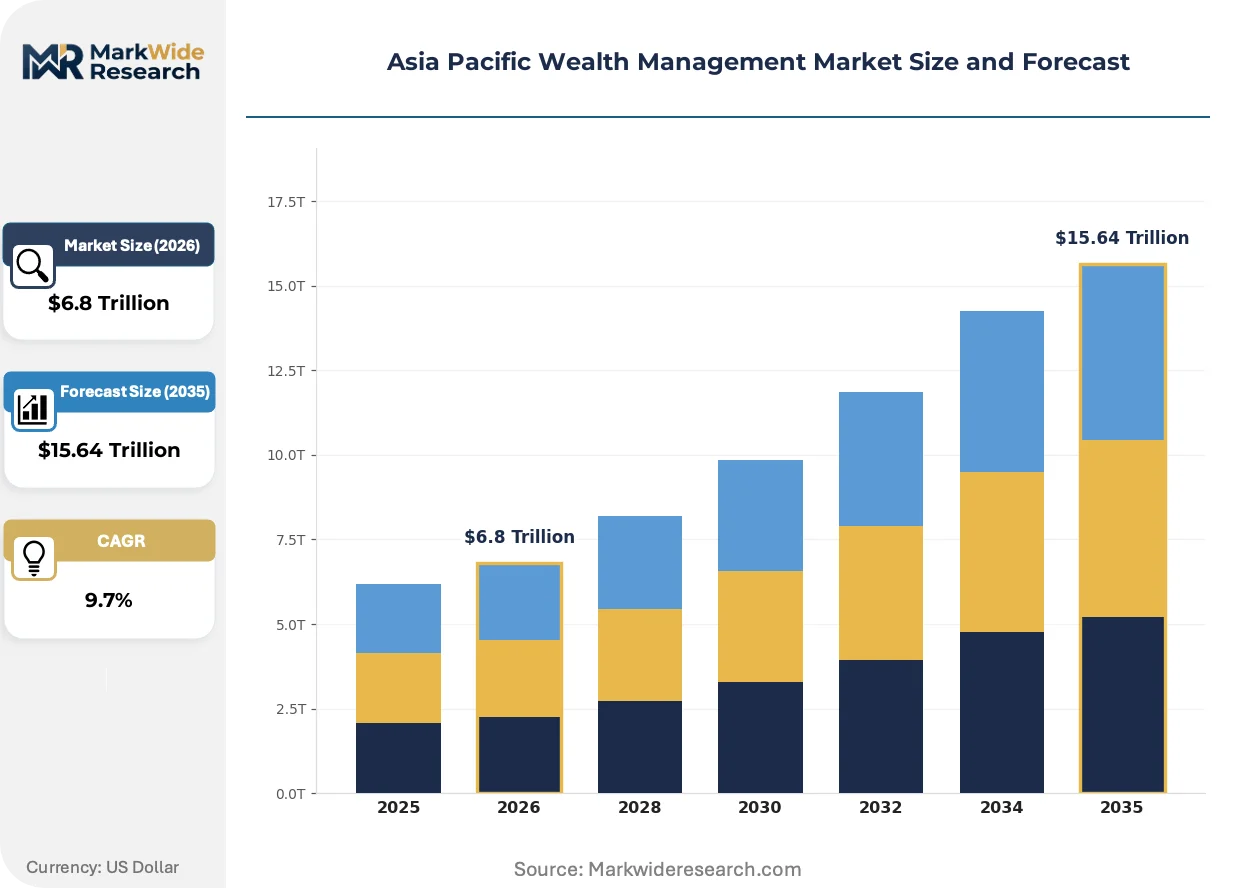
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $15.64 Trillion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Investment Advisory, Portfolio Management, Tax Planning, Estate Planning Client Segment: High Net Worth Individuals, Ultra High Net Worth Individuals, Mass Affluent, Institutions Investment Strategy: Alternative Investments, Equity Investments, Fixed Income, Real Estate Distribution Channel: Online Platforms, Private Banks, Financial Advisors, Brokerage Firms |
| Companies Covered | UBS Group AG, HSBC Holdings plc, Morgan Stanley, Credit Suisse Group AG, DBS Group, Citigroup Inc., JPMorgan Chase & Co., BNP Paribas, Goldman Sachs, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wealth Management Market Strategic Shifts
Wealth management delivery models across Asia Pacific are bifurcating between algorithmic efficiency and high-touch relationship architecture, with hybrid intermediation emerging as the dominant competitive response.
Robo-advisory platforms are hybridizing conventional portfolio construction with behavioral nudging and goal-based visualization tools. Mass-affluent investors across Indonesia, Thailand, and Malaysia are adopting these interfaces at velocity previously reserved for pure digital banks. The technology is hybridizing cost structures, compressing marginal advisory fees while expanding addressable household segments beyond traditional private banking minimums.
Monetary Authority of Singapore's enhanced technology risk management guidelines are mandating operational resilience standards for digital wealth platforms. These requirements are elevating cybersecurity and business continuity investment thresholds, favoring larger institutional players with dedicated infrastructure budgets. Private banks and licensed fund managers operating from Singapore are responding by consolidating technology vendors and pursuing unified data governance frameworks.
Next-generation investors across Southeast Asia are demanding transparent fee structures and real-time portfolio analytics accessible through mobile-native interfaces. Traditional branch-dependent distribution channels in markets like Indonesia and the Philippines are losing primacy to app-based onboarding and video-enabled advisory consultations. This behavioral pivot is most visible among tech-sector professionals in Ho Chi Minh City and Manila, where employer equity compensation programs are creating concentrated demand for sophisticated tax-aware wealth planning.
Asia Pacific Wealth Management Market Segmentation
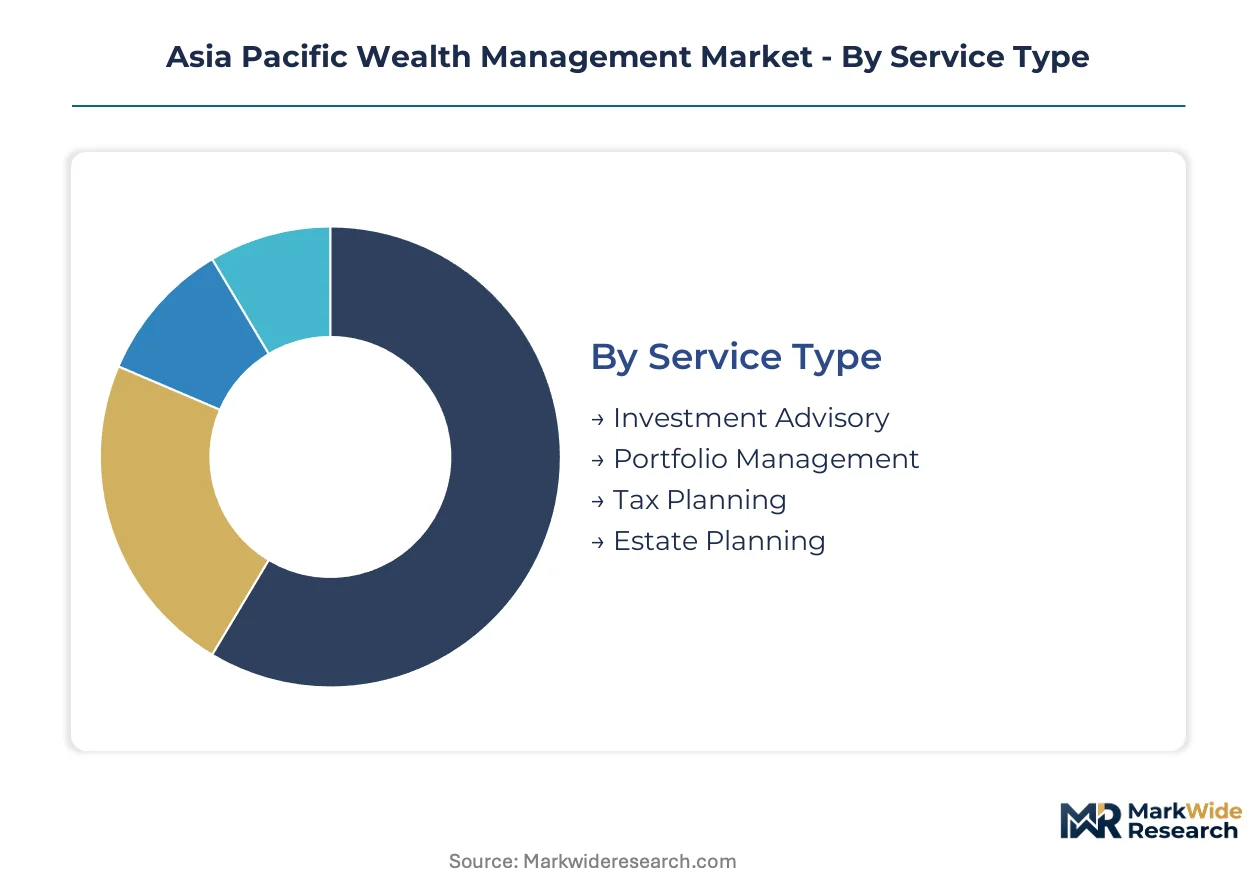
Wealth management service delivery varies dramatically across client sophistication tiers and regulatory environments. Understanding segment turnover velocity reveals where relationship managers allocate attention versus where algorithmic infrastructure dominates.
Service Type:
Portfolio rebalancing cycles compress advisory engagement frequency, while estate structuring extends relationship horizons across generational transfers.
- Investment Advisory:SEBI-licensed advisers in India deliver goal-based recommendations through hybrid digital-human interfaces. Regulatory professionalization drives household penetration in Mumbai and Bangalore, though fee compression from robo-competitors constrains margin expansion.
- Portfolio Management:Discretionary mandates concentrate in Singapore's private banking hub where family offices demand cross-border tax-aware construction. Discretionary accounts turn over fastest among mass-affluent segments adopting algorithmic rebalancing.
- Tax Planning:Australia's superannuation-linked strategies dominate institutional flows.
- Estate Planning:Intergenerational transfers in Hong Kong SAR sustain longest engagement cycles.
Portfolio Management anchors the volume base while Investment Advisory gains share at the steepest rate.
Client Segment:
Cost-to-serve stratification separates premium relationship architecture from digitally delivered mass-market propositions.
- High Net Worth Individuals:Singapore-domiciled private banks cultivate multi-currency liquidity management and concentrated equity hedging. Jakarta and Bangkok emerging wealth creates pipeline pressure on relationship manager capacity.
- Ultra High Net Worth Individuals:Family office consolidation concentrates assets under single-custody structures with bespoke governance frameworks. Singapore's Monetary Authority custody rules attract regional consolidation from Indonesian and Malaysian dynastic wealth.
- Mass Affluent:Vietnam and Philippines digital platforms capture first-mover advantages.
- Institutions:Australia's superannuation funds mandate lifecycle strategies.
Mass Affluent segments deploy lowest-cost infrastructure while Ultra High Net Worth Individuals command premium pricing architecture.
Investment Strategy:
Application-driven allocation separates yield-seeking institutional mandates from growth-oriented individual portfolios.
- Alternative Investments:Private equity and hedge fund exposures concentrate in Singapore and Hong Kong SAR family office structures. Regulatory familiarity with offshore fund structures accelerates adoption among cross-border Asian investors.
- Equity Investments:Direct share ownership dominates Australian superannuation choice architecture and Indian retail brokerage penetration. India's demat account expansion channels household savings into domestic equity at institutional scale.
- Fixed Income:Singapore dollar bonds anchor regional liquidity management.
- Real Estate:Australian REITs and Singapore property trusts structure income-focused exposure.
Equity Investments sustain the broadest participant base while Alternative Investments climb the fastest among sophisticated allocators.
Distribution Channel:
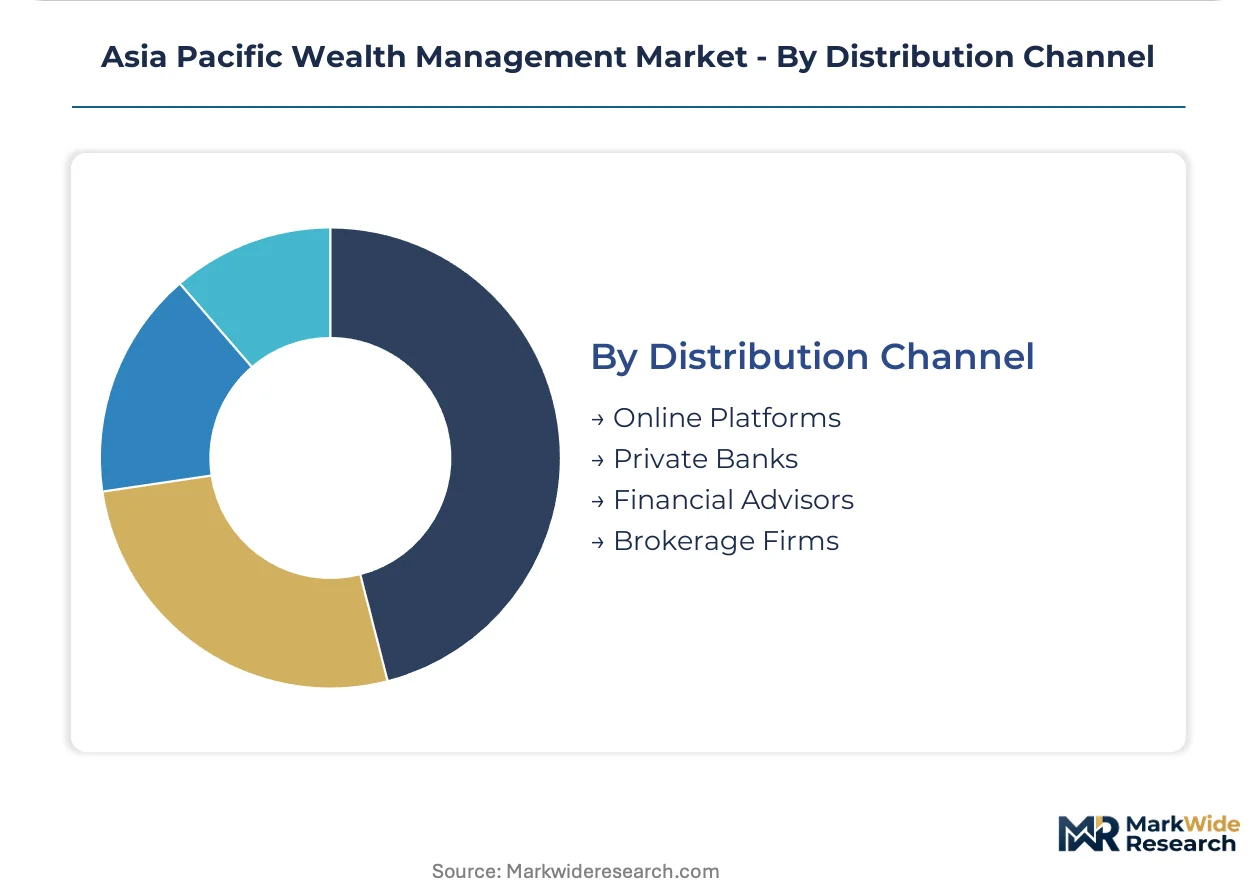
Customer acquisition economics separate high-touch onboarding from automated conversion funnels.
- Online Platforms:Digital-native wealth interfaces in Indonesia, Thailand, and Malaysia compress marginal cost-to-serve through algorithmic portfolio construction. Behavioral nudging and goal-based visualization tools drive adoption velocity among tech-sector professionals.
- Private Banks:Relationship density in Singapore and Hong Kong SAR sustains margin dominance through discretion and cross-border complexity navigation. UBS and Credit Suisse heritage anchors ultra-high-net-worth trust in these jurisdictions.
- Financial Advisors:India's SEBI framework professionalizes commission-disclosure standards.
- Brokerage Firms:Australia's integrated bank-broker networks capture superannuation rollover flows.
Private Banks retain the highest revenue per relationship while Online Platforms expand most quickly across Southeast Asian mass-affluent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass-affluent investors in Southeast Asia demonstrate acute price sensitivity to advisory fees, while Singapore's ultra-high-net-worth households prioritize discretion and cross-border expertise over cost considerations. This demand-elasticity divide shapes where wealth managers deploy algorithmic infrastructure versus relationship-intensive service models.
Singapore
Family office consolidation and multi-currency liquidity management anchor ultra-high-net-worth demand. Monetary Authority of Singapore custody and tax transparency rules attract regional asset flows from Indonesian and Malaysian dynastic wealth. Marina Bay and Orchard Road clusters host the highest concentration of private banking relationship managers per capita.
Australia
Mandatory superannuation contribution flows create captive institutional asset pools requiring lifecycle investment strategies. Australian Securities and Investments Commission best-interest duties enforce strict fee disclosure regimes affecting advisory margins. Sydney and Melbourne financial districts concentrate superannuation fund administration and retail wealth platform headquarters.
India
Demat account expansion channels household savings into domestic equity at institutional scale. SEBI investment adviser licensing framework professionalizes commission-disclosure standards and expands regulated advisory participation. Mumbai and Bangalore urban clusters drive SEBI-licensed adviser penetration through hybrid digital-human interfaces.
Japan
Domestic retail investors seek yield enhancement through structured product wrappers under negative interest rate conditions. Financial Services Agency segregation and custody rules shape investment management contract packaging for conservative household segments. Tokyo's Marunouchi and Nihonbashi districts retain concentration of trust banking and asset management headquarters.
Vietnam
Tech-sector professionals in Ho Chi Minh City generate concentrated demand for tax-aware wealth planning around employer equity compensation. Underbanked mass-affluent households present first-mover advantages for digitally native wealth platforms. Ho Chi Minh City's District 1 and Thu Thiem financial zone clusters attract initial digital wealth platform licensing applications.
Asia Pacific Wealth Management Market Competitive Environment
Swiss-heritage private banks and integrated Asia-Pacific banking groups split the market between ultra-high-net-worth discretion and mass-affluent digital scale. Consolidation concentrates relationship manager talent in Singapore and Hong Kong SAR, while fragmentation persists in emerging Southeast Asian markets. Three archetypes dominate: heritage Swiss private banks, integrated universal banks with retail-to-wealth channels, and digitally native platform operators. Competitive moves center on digital onboarding velocity acceleration and cross-border family office custody consolidation.
Within the heritage private banking tier, UBS Group AG and Credit Suisse Group AG anchor ultra-high-net-worth trust through Swiss-domiciled discretion and multi-generational relationship architecture. HSBC Holdings plc exemplifies the integrated universal bank archetype, leveraging mainland China corridor access and retail banking density to sustain mass-affluent penetration. DBS Group occupies a position between these models, competing aggressively on Southeast Asian digital platform deployment and next-generation investor acquisition velocity.
| Leading Market Players |
|---|
| UBS Group AG |
| HSBC Holdings plc |
| Morgan Stanley |
| Credit Suisse Group AG |
| DBS Group |
| Citigroup Inc. |
| JPMorgan Chase & Co. |
| BNP Paribas |
| Goldman Sachs |
| Others |
Value Chain & Pricing Dynamics
Singapore's Marina Bay financial cluster concentrates relationship manager talent and custody infrastructure, translating upstream capacity scarcity into premium pricing power for ultra-high-net-worth mandates across Southeast Asian markets.
Pricing Analysis
After-sales revenue from estate structuring and intergenerational advisory services drives lifetime client value beyond initial portfolio construction fees. Three-tier pricing structure across premium discretionary mandates, standard advisory services, and economy robo-advisory tiers captures divergent willingness-to-pay across wealth segments. Pricing pressure stems from algorithmic platform compression in mass-affluent segments, while relationship-intensive tiers retain margin resilience. Mass-affluent investors in Vietnam and Philippines exhibit acute price sensitivity; Singapore family offices demonstrate cost indifference where discretion and cross-border complexity dominate.
Supply Chain Analysis
Technology vendor consolidation among core banking platform providers and custody infrastructure specialists concentrates critical supply capacity. Singapore, Hong Kong SAR, and Australia anchor wealth management technology supply, drawing from specialized software vendors in India and cloud infrastructure providers across Southeast Asia. Single-source vulnerability concentrates in legacy core banking migration timelines where incumbent vendors lock switching costs. Distribution runs through hybrid digital-human channels: private banking relationship networks for ultra-high-net-worth segments, app-based platforms for mass-affluent acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable barriers—licensing requirements and custody rule familiarity embed incumbents while fragmenting competitive entry.
For Market Incumbents: Entrench position through vertical integration into proprietary custody infrastructure and accelerated technology vendor consolidation. Relationship manager scarcity in secondary Southeast Asian markets threatens expansion capacity; defend by establishing dedicated training academies in Singapore and licensing technology stacks for remote advisory delivery. Regulatory arbitrage opportunities are narrowing as SEBI, ASIC, and Monetary Authority of Singapore tighten consumer protection frameworks independently. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Philippines mass-affluent segments where digitally native platforms face limited heritage competition. Underbanked high-net-worth households in Ho Chi Minh City and Manila present first-mover advantages for algorithmic portfolio services with tax-aware equity compensation planning. Go-to-market should emphasize mobile-native onboarding velocity and transparent fee structures to differentiate from branch-dependent incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from universal banking groups seeking to divest non-core wealth management units in fragmented ASEAN markets. Long-term viability favors platforms with demonstrated regulatory navigation across multiple Asian jurisdictions and scalable technology infrastructure. Monitor SEBI licensing expansion velocity and Monetary Authority of Singapore family office application volumes as inflection indicators for regional asset flow concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Onboarding Velocity Acceleration | DBS Group and regional challengers capture next-generation investors through sub-15-minute account opening in Southeast Asian markets. |
| Cross-Border Family Office Custody Consolidation | Singapore's Monetary Authority custody rules attract Indonesian and Malaysian dynastic wealth into single-custody structures. |
| Algorithmic Rebalancing Engine Deployment | Automated tax-loss harvesting reduces marginal cost-to-serve for mass-affluent segments across Thailand and Malaysia. |
| Regulatory Licensing Expansion | SEBI investment adviser framework professionalizes retail advisory penetration in Mumbai and Bangalore urban clusters. |
| Hybrid Advisory Model Development | Artificial intelligence and natural language processing convergence opens premium service tiers combining algorithmic construction with human oversight. |
Study Parameters
A standing panel of private banking relationship managers, SEBI-licensed investment advisers, superannuation fund strategists, and family office governance specialists provided ongoing calibration against market developments. Primary interviews with these practitioners combined with secondary validation from Monetary Authority of Singapore regulatory filings, ASIC disclosure registers, SEBI licensing databases, and ASEAN central bank policy statements. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing framed analytical projections across the modeling period, with CAGRs derived from segment-level adoption curves and regulatory capacity expansion timelines. Service type, client segment, investment strategy, and distribution channel dimensions structured the forecast architecture. Inputs incorporated demat account expansion rates in India, superannuation contribution flow projections, and family office licensing application trajectories in Singapore.
Sensitivities concentrate around regulatory harmonization failures across ASEAN jurisdictions and relationship manager talent migration patterns. Forecasts reflect assumptions regarding digital platform adoption velocity and custody rule stability. Quarterly review of SEBI licensing issuance, Monetary Authority of Singapore family office approvals, and robo-advisory platform download metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
MENA Wealth Management Market