
 MENA Wealth Management Market | 2026-2036
MENA Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Wealth Management Market Foresight
Cloud-native portfolio analytics is rewriting how wealth managers construct and rebalance client portfolios across the Gulf. UBS Global Wealth Management leverages its Zurich-engineered risk engines to anchor institutional-grade family office mandates in Dubai and Riyadh. QNB Private dominates Qatar's captive sovereign-related wealth pool through its Doha-centric relationship banking model. Emirates NBD Private Banking differentiates via its integrated digital onboarding platform that compresses account opening cycles for inbound expatriate capital.
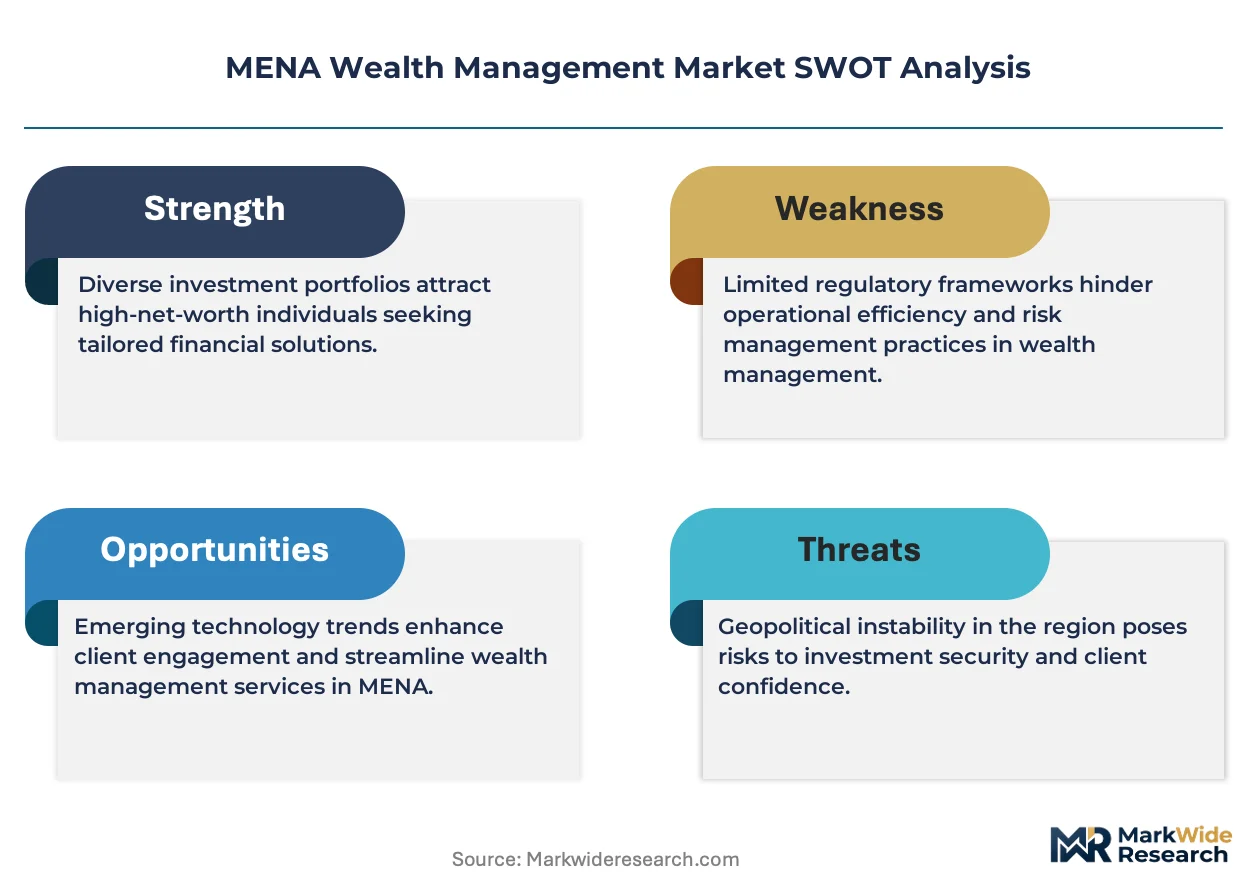
MENA wealth management encompasses the professional administration of investable assets, fiduciary oversight, and succession structuring for affluent individuals and institutional principals across the Middle East and North Africa, typically requiring minimum thresholds of USD one million in liquid net worth and operating through segregated mandate structures or discretionary portfolio contracts. The primary commercial purpose centers on capital preservation, generational transfer efficiency, and Sharia-compliant return generation within volatile hydrocarbon-revenue economies. The client type dimension concentrates margin pools among ultra high net worth individuals whose complexity demands bespoke structuring across multiple jurisdictions. The service type dimension shows investment advisory commanding the largest revenue share while tax optimization accelerates fastest as Gulf states introduce corporate and personal income frameworks. The asset class dimension reveals alternative investments deepening penetration as regional sovereign wealth co-investment vehicles democratize access previously reserved for state entities.
The Dubai Financial Services Authority enforces prudential suitability standards for retail and professional clients operating within the Dubai International Financial Centre, while the Saudi Capital Market Authority governs investment advisory licensing and product distribution across the Kingdom's expanding wealth management perimeter. The Central Bank of the UAE oversees anti-money laundering protocols that shape onboarding friction and cross-border remittance corridors for private banking flows. Stakeholders must monitor how regulatory divergence between onshore UAE frameworks and DIFC opt-in regimes affects operating model economics and client segmentation strategies.
Market Dynamics
The Dubai Financial Services Authority's suitability standard tightening is compressing advisory margins while forcing wealth managers toward higher-touch, fee-based fiduciary models across the Gulf.
Growth Catalysts
- Sovereign co-investment vehicles:Saudi Arabia's Public Investment Fund and UAE sovereign wealth structures are democratizing access to private equity and infrastructure deals previously reserved for state entities, expanding allocable alternative asset pools for family offices.
- Corporate income tax introduction:The UAE's 2023 federal corporate tax framework is accelerating demand for tax-efficient structuring, trust formation, and cross-border holding company architecture among resident ultra-high-net-worth individuals.
- Cloud-native portfolio analytics:Real-time risk engines and automated rebalancing tools are compressing operational costs and enabling scaled personalization across discretionary mandates.
Market Restraints
- Relationship banker scarcity:The Gulf's shallow talent pool of bilingual advisors credentialed in both Sharia-compliant structuring and Western fiduciary standards limits organic growth capacity for established players.
- Onshore-offshore regulatory divergence:The Central Bank of the UAE's anti-money laundering protocols impose heavier documentation burdens than DIFC opt-in regimes, fragmenting operating economics across client segments.
- Concentrated hydrocarbon revenue dependency:Client liquidity flows remain correlated with oil price volatility, compressing predictable advisory fee streams during commodity downturns.
Strategic Opportunities
- Egypt's underpenetrated mass-affluent tier:Cairo and Alexandria's expanding professional class sits below traditional private banking thresholds but above retail wealth product suitability, creating white space for digital-hybrid advisory models.
- Generational transfer acceleration:First-generation Gulf family business founders are entering succession planning phases, driving demand for multi-jurisdictional trust structures and next-generation governance education.
- Islamic fintech convergence:The integration of blockchain-based sukuk issuance platforms with robo-advisory distribution channels is opening Sharia-compliant wealth accumulation products to previously excluded investor tiers.
Industry Challenges
- Multi-jurisdictional licensing complexity:Wealth managers operating across Saudi Arabia, UAE, and Qatar must maintain separate regulatory permissions from the Saudi Capital Market Authority, Dubai Financial Services Authority, and Qatar Financial Centre, inflating compliance overhead.
- Legacy core banking integration:Established Gulf banks' decades-old custody and settlement infrastructure resists API connectivity with modern portfolio management systems, delaying real-time client reporting deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Wealth Management Market |
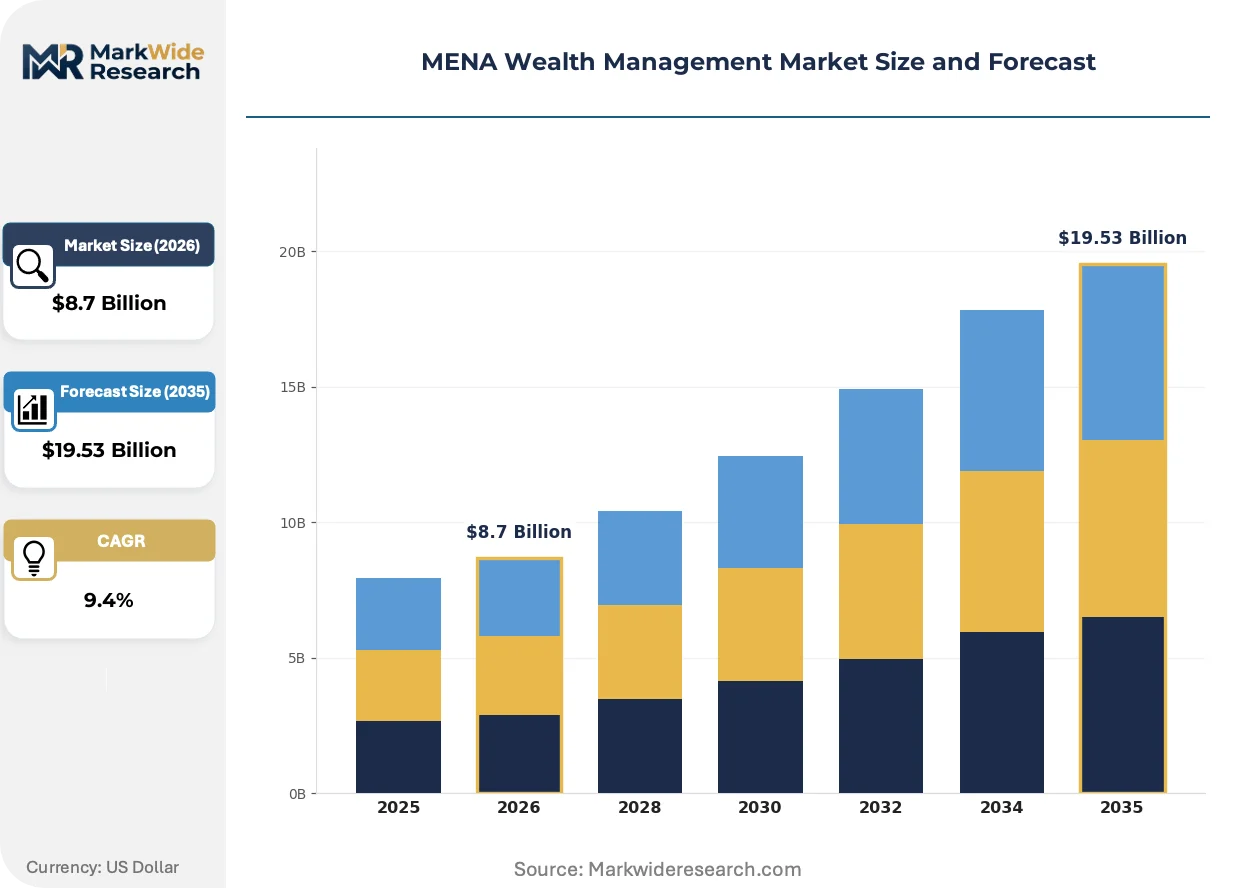
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
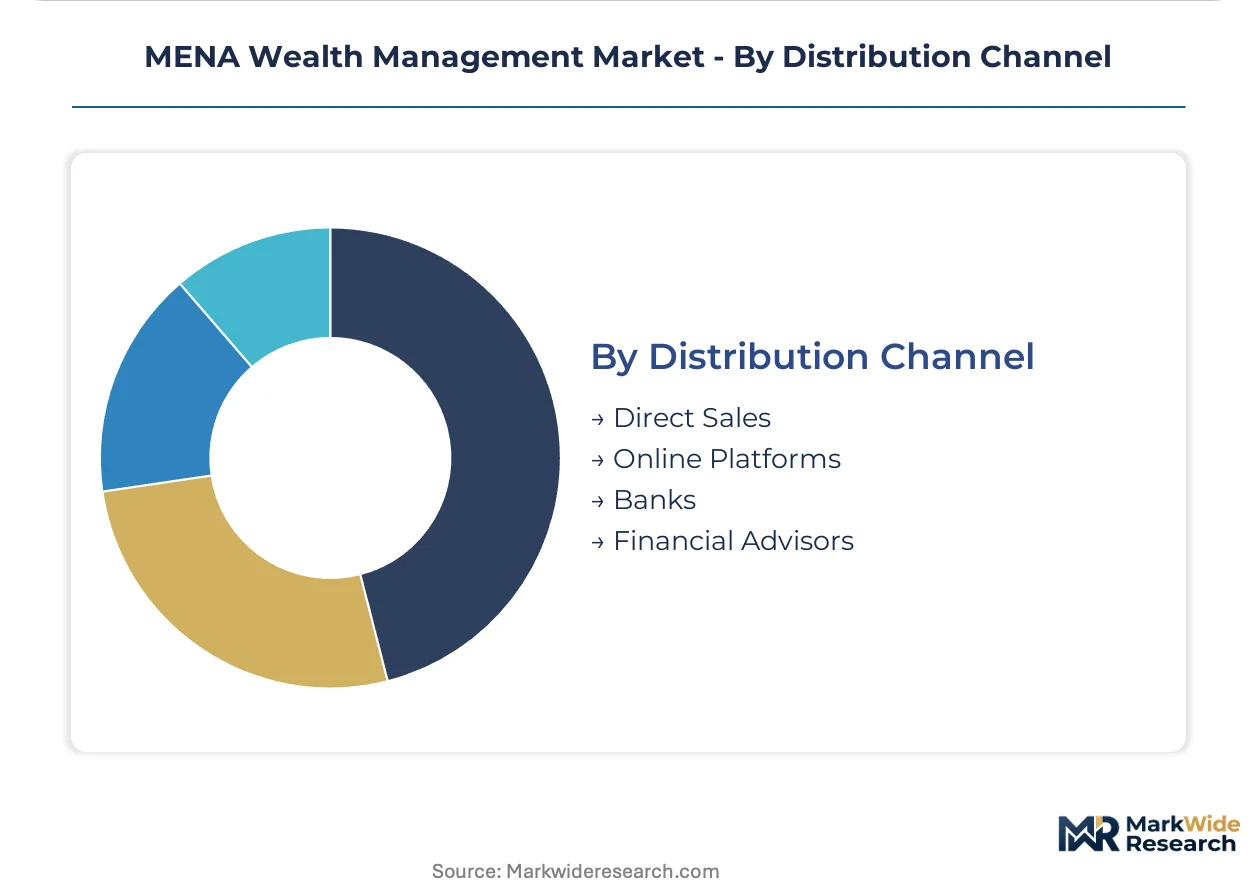
| Segmentation | Client Type: High Net Worth Individuals, Ultra High Net Worth Individuals, Family Offices, Corporates Service Type: Investment Advisory, Financial Planning, Tax Optimization, Estate Planning Asset Class: Equities, Fixed Income, Real Estate, Alternative Investments Distribution Channel: Direct Sales, Online Platforms, Banks, Financial Advisors |
| Companies Covered | UBS Global Wealth Management - Middle East, QNB Private, Emirates NBD Private Banking, BNP Paribas Wealth Management Gulf, Mashreq Private Banking, First Abu Dhabi Bank (FAB) Private Banking, Julius Baer Middle East, NBK Wealth, HSBC Global Private Banking - MENA, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Wealth Management Market Shifts & Advancements
Digital infrastructure is compressing the traditional relationship-banking model while regulatory technology and behavioral analytics reshape how wealth managers acquire, serve, and retain clients across volatile Gulf economies.
Cloud-native portfolio analytics is virtualizing the traditional face-to-face advisory encounter. Family offices in Dubai and Riyadh now demand real-time risk visualization and scenario modeling accessible through secure mobile interfaces. This technology compression is collapsing the historical trade-off between personalization and scale, enabling a single relationship manager to oversee substantially larger discretionary mandates without service degradation.
The Dubai Financial Services Authority's 2024 suitability guidance amendments are mandating granular documentation of client risk tolerance and product appropriateness. Wealth managers must now maintain auditable trails linking every investment recommendation to stated investment objectives and liquidity constraints. Smaller advisory boutiques lacking compliant record-keeping infrastructure are exiting the DIFC perimeter, concentrating activity among better-capitalized institutions.
Next-generation inheritors are rejecting their parents' single-bank relationship models in favor of multi-custody, open-architecture platforms. Younger Gulf family members seek transparency into fee structures and performance attribution across competing providers, unbundling custody from investment advice and execution. This behavioral pivot is most visible in Saudi Arabia's Riyadh and Jeddah corridors, where digitally native heirs are driving RFP processes for family office outsourcing mandates.
MENA Wealth Management Market Segmentation

Client complexity, regulatory jurisdiction, and asset liquidity requirements fragment the MENA wealth management landscape into distinct commercial pockets. Each segmentation dimension carries different margin profiles and operational intensity, forcing providers to calibrate staffing models and technology investment against specific revenue pools.
Client Type:
Customer type determines advisory intensity, with complexity escalating across the wealth spectrum from individual portfolios to multi-generational family governance structures.
- Ultra High Net Worth Individuals:Clients holding liquid net worth above USD thirty million command bespoke multi-jurisdictional structuring and dedicated relationship teams. Dubai and Riyadh concentrate this tier, where succession planning and Sharia-compliant cross-border holding companies drive mandate complexity.
- Family Offices:Single-family and multi-family offices manage consolidated investment operations for dynastic wealth, requiring integrated reporting across custody, private equity co-investments, and philanthropic vehicles. Saudi Arabia's first-generation business founders are accelerating demand for next-generation governance education and governance infrastructure.
- High Net Worth Individuals:The USD one million to thirty million segment seeks discretionary portfolio management with periodic strategic advisory touchpoints. Emirates NBD Private Banking targets this tier through digital onboarding compression and automated rebalancing tools.
- Corporates:Regional conglomerates and family holding companies utilize treasury management, liquidity optimization, and employee benefit trust structuring. Qatar's captive sovereign-related entities dominate this segment through relationship banking models anchored in Doha.
Ultra High Net Worth Individuals hold installed capacity. Family Offices is rotating up the share rankings.
Service Type:
Margin architecture varies sharply across the service mix, with transactional advisory yielding lower retention than fiduciary structuring and recurring oversight mandates.
- Tax Optimization:The UAE's federal corporate tax introduction and Saudi Arabia's zakat modernization are accelerating demand for tax-efficient trust formation, cross-border holding company architecture, and transfer pricing documentation. This segment climbs the fastest as Gulf fiscal frameworks converge with OECD standards.
- Investment Advisory:Discretionary and non-discretionary portfolio construction commands the largest revenue share, anchored by UBS Global Wealth Management's Zurich-engineered risk engines deployed across Dubai and Riyadh family office mandates.
- Estate Planning:Multi-jurisdictional will structuring, probate avoidance mechanisms, and generational governance protocols address the Gulf's accelerating wealth transfer cycle. The Dubai International Financial Centre's trust law amendments are expanding jurisdictional flexibility for regional families.
- Financial Planning:Integrated cash flow modeling, education funding, and retirement liability matching serve the mass-affluent tier approaching traditional private banking thresholds. Egypt's underpenetrated professional class in Cairo and Alexandria represents expansion white space for digital-hybrid models.
Investment Advisory retains revenue concentration. Tax Optimization is gaining share fastest.
Asset Class:
Allocation preferences reflect hydrocarbon-revenue volatility and regional sovereign wealth co-investment democratization, shifting portfolios toward illiquid alternatives and income-generating real assets.
- Alternative Investments:Private equity, infrastructure, and venture capital allocations are deepening as Saudi Arabia's Public Investment Fund and UAE sovereign wealth structures open co-investment vehicles previously reserved for state entities. Family offices in Dubai and Riyadh now demand direct deal access alongside fund commitments.
- Real Estate:Direct property holdings, REITs, and development partnerships anchor Gulf wealth preservation strategies, with Dubai's prime residential and commercial segments attracting inbound expatriate capital seeking hard-asset stability.
- Equities:Regional and international listed equity exposure operates through segregated mandates and model portfolios, with cloud-native portfolio analytics enabling real-time risk visualization and automated rebalancing across discretionary relationships.
- Fixed Income:Sukuk, conventional bonds, and private credit structures serve liquidity management and income generation objectives. Sharia-compliant issuance platforms are integrating with robo-advisory distribution channels to expand access.
Equities holds installed capacity. Alternative Investments is rotating up the share rankings.
Distribution Channel:
Channel economics are compressing as digital infrastructure virtualizes traditional face-to-face advisory encounters and next-generation inheritors reject single-bank relationship models.
- Banks:Established Gulf institutions leverage captive deposit bases and integrated custody infrastructure to anchor comprehensive wealth relationships. Legacy core banking systems resist API connectivity with modern portfolio management platforms, delaying real-time client reporting deployment.
- Financial Advisors:Independent advisory boutiques and multi-family office platforms are consolidating as the Dubai Financial Services Authority's suitability standard tightening forces smaller players to exit for lack of compliant record-keeping infrastructure.
- Direct Sales:Relationship manager-led origination remains dominant for ultra-high-net-worth complexity, though talent scarcity of bilingual advisors credentialed in both Sharia-compliant structuring and Western fiduciary standards constrains organic growth capacity.
- Online Platforms:Robo-advisory and hybrid digital channels are penetrating the mass-affluent tier below traditional private banking thresholds, with blockchain-based sukuk issuance integration opening Sharia-compliant accumulation products to previously excluded investor tiers.
Banks hold installed capacity. Online Platforms is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth family principals and sovereign-related entities concentrate wealth management demand across the Gulf's financial centers, with regulatory divergence between onshore and offshore regimes fragmenting service delivery models.
United Arab Emirates
Dubai's expatriate capital inflows and Abu Dhabi's sovereign wealth co-investment programs drive advisory complexity. The Dubai Financial Services Authority enforces prudential suitability standards within the DIFC perimeter, tightening documentation requirements for discretionary mandates. Emirates NBD Private Banking anchors its digital onboarding platform in Dubai to compress account opening cycles for inbound international capital.
Saudi Arabia
First-generation family business founders entering succession phases and the Public Investment Fund's private equity democratization are accelerating mandate growth. The Saudi Capital Market Authority governs investment advisory licensing and product distribution across the Kingdom's expanding wealth perimeter. Riyadh and Jeddah corridors concentrate next-generation inheritors rejecting single-bank relationship models in favor of multi-custody platforms.
Qatar
Captive sovereign-related wealth pools and regional conglomerate treasury management sustain relationship banking economics. The Qatar Financial Centre regulatory framework shapes licensing requirements for advisory boutiques operating alongside established institutions. Doha-centric banking models dominate as QNB Private leverages integrated custody infrastructure to anchor comprehensive wealth relationships.
Kuwait
Dynastic family wealth preservation and cross-border holding company restructuring generate structuring demand amid regional tax harmonization pressures. The Central Bank of Kuwait oversees anti-money laundering protocols that shape onboarding friction for private banking flows. Kuwait City's concentration of multi-generational family offices drives demand for Sharia-compliant succession architecture and next-generation governance education.
Egypt
Cairo and Alexandria's expanding professional class sits below traditional private banking thresholds but above retail wealth product suitability, creating white space for digital-hybrid advisory models. The Financial Regulatory Authority governs non-banking financial services including investment advisory licensing. Egypt's underpenetrated mass-affluent tier represents expansion opportunity for automated portfolio construction tools targeting emerging wealth segments.
MENA Wealth Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where relationship depth and regulatory compliance infrastructure determine positioning. The market consolidates around three archetypes: global private banking networks with Zurich-anchored risk engines, Gulf-headquartered institutions leveraging captive deposit bases, and independent advisory boutiques serving single-family office complexity. Competitive moves center on digital infrastructure investment compressing operational costs and regulatory technology deployment satisfying suitability documentation mandates.
Within the global network tier, UBS Global Wealth Management and HSBC Global Private Banking exemplify institutions deploying Zurich-engineered and London-anchored risk engines respectively across Dubai and Riyadh family office mandates. Among Gulf-headquartered relationship banks, QNB Private and Emirates NBD Private Banking occupy positions integrating digital onboarding with captive custody infrastructure. Julius Baer Middle East represents the independent Swiss-heritage advisory archetype targeting ultra-high-net-worth complexity outside integrated banking conglomerates.
| Leading Market Players |
|---|
| UBS Global Wealth Management - Middle East |
| QNB Private |
| Emirates NBD Private Banking |
| BNP Paribas Wealth Management Gulf |
| Mashreq Private Banking |
| First Abu Dhabi Bank (FAB) Private Banking |
| Julius Baer Middle East |
| NBK Wealth |
| HSBC Global Private Banking - MENA |
| Others |
Supply & Pricing Matrix
Zurich-engineered risk engine licensing concentrates among three global private banking networks, anchoring margin pools in discretionary mandate fees rather than transactional spreads across Dubai and Riyadh. This upstream technology concentration forces Gulf-headquartered institutions to absorb premium vendor costs or accept performance attribution gaps against global competitors.
Pricing Analysis
Cost-plus advisory contracts indexed to AUM thresholds dominate ultra-high-net-worth relationships, with three-tier pricing structure across premium, standard, and economy levels differentiating by relationship manager seniority and reporting frequency. Price differentiation rests on Sharia certification tier and multi-jurisdictional structuring complexity. Pricing pressure stems from the Dubai Financial Services Authority's suitability documentation mandates inflating compliance overhead. Family offices exhibit lowest price sensitivity; Egypt's mass-affluent digital-hybrid adopters face highest elasticity.
Supply Chain Analysis
Tariff exposure between the United Kingdom and Gulf Cooperation Council jurisdictions dominates cross-border trust structuring economics. Talent sourcing concentrates in Switzerland, Singapore, and the United Kingdom for bilingual advisors credentialed in Western fiduciary standards. Raw material dependencies include cloud infrastructure from hyperscalers, regulatory technology software, and prime brokerage custody services. Single-source vulnerability sits with legacy core banking vendors resisting API connectivity. Distribution runs through relationship manager-led origination anchored in DIFC and onshore UAE licensing regimes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MENA wealth management market functions as a defensive-moat arena where regulatory entrenchment creates durable positioning. Switching costs escalate as multi-jurisdictional trust structures and multi-generational governance protocols embed clients within incumbent ecosystems.
For Market Incumbents: Insulate advisory margins by embedding proprietary risk engines deeper into family office operating infrastructure, creating technical switching costs that resist unbundling. Acquire boutique advisory practices in Riyadh and Jeddah corridors to capture next-generation inheritor relationships before multi-custody platform adoption accelerates. The Dubai Financial Services Authority's suitability tightening threatens smaller competitors lacking compliant record-keeping infrastructure. For New Entrants and Emerging Players: Build out digital-hybrid advisory capacity targeting Egypt's mass-affluent professional class in Cairo and Alexandria, where traditional private banking thresholds exclude incumbent coverage. Develop blockchain-integrated sukuk distribution platforms to access Sharia-compliant wealth accumulation demand previously excluded from conventional channels. White-space concentration sits below USD one million liquid net worth thresholds. For Investors and Strategic Acquirers: Capital is best deployed toward independent advisory boutiques with established DIFC licensing and next-generation governance education capabilities, positioned for consolidation as regulatory overhead forces exit among undercapitalized competitors. Long-term viability over the coming decade hinges on technology infrastructure amortization across expanding AUM bases. The signal to watch is accelerated RFP activity from Saudi family offices seeking multi-custody platform arrangements.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Deployment | Automated suitability documentation satisfies Dubai Financial Services Authority audit trails while compressing compliance headcount. |
| Next-Generation Governance Education | Structured programs for Saudi inheritors build multi-decade retention across family office succession cycles. |
| Cloud-Native Risk Engine Integration | Real-time portfolio analytics from Zurich-engineered platforms differentiate discretionary mandates in Riyadh. |
| Multi-Jurisdictional Licensing Expansion | Permissions across Saudi Capital Market Authority, Dubai Financial Services Authority, and Qatar Financial Centre unlock cross-border mandate capture. |
| Islamic Fintech Platform Development | Blockchain-based sukuk issuance integration opens Sharia-compliant accumulation products to previously excluded investor tiers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with relationship managers at UBS Global Wealth Management and Emirates NBD Private Banking, family office principals in Dubai and Riyadh, regulatory affairs specialists at the Dubai Financial Services Authority, and technology vendors serving portfolio analytics infrastructure. Secondary validation drew from Saudi Capital Market Authority licensing disclosures, Central Bank of the UAE anti-money laundering guidance, DIFC trust law amendments, and sovereign wealth fund co-investment vehicle prospectuses. Bottom-up AUM aggregation and top-down macroeconomic allocation modeling were triangulated.
Calibration against historical mandate growth patterns and regulatory implementation timelines shaped projections across the analysis window. Segmentation dimensions modeled include client type, service type, asset class, and distribution channel complexity. CAGRs were derived from trend extrapolation adjusted for sovereign wealth co-investment democratization velocity and corporate tax framework maturation. Forecast inputs incorporated relationship manager hiring pipelines and cloud infrastructure adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive technology investment by Gulf-headquartered relationship banks or accelerated regulatory harmonization across GCC jurisdictions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Family Offices Market