
 Japan Private Banking Market | 2026-2036
Japan Private Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Private Banking Market Outlook
Japan's aging certified financial planner workforce is reorganizing how private banks staff their relationship management tiers. Nomura Holdings leverages its domestic securities heritage to anchor ultra-high-net-worth mandates in Tokyo and Osaka. Mitsubishi UFJ Morgan Stanley Private Banking competes through bicultural deal teams that navigate cross-border succession planning for Japanese family offices. UBS extends its Switzerland-based wealth architecture into Japan via dedicated multi-currency platforms.
Japan private banking denotes discretionary and non-discretionary asset management services delivered to individuals with investable assets exceeding one hundred million yen, emphasizing intergenerational wealth transfer, tax-advantaged wrappers, and concentrated equity positions in unlisted domestic enterprises. The service type dimension shows wealth management and estate planning commanding the deepest margin pools as demographic tailwinds intensify demand for inheritance structuring. Client type segmentation reveals Ultra High Net Worth Individuals as the fastest-expanding cohort, while affluent investors remain the most numerically significant addressable base for digital onboarding channels.
Japan's Financial Services Agency enforces suitability standards and disclosure requirements that shape product governance across trust banks and foreign registered advisers. METI's stewardship code and the JFSA's principles for customer-oriented business conduct collectively elevate demand for transparent fee structures and documented investment policy statements. Stakeholders must monitor whether proposed revisions to Japan's inheritance tax regime alter the relative attractiveness of domestic trusts versus offshore structuring vehicles.
Market Dynamics
Japan's demographic inversion is compressing traditional wealth transfer timelines while METI's stewardship code pressures fee transparency across trust banks and foreign registered advisers. This dual squeeze is forcing relationship managers to restructure advisory tiers around documented investment policy statements and intergenerational succession mandates.
Growth Catalysts
- NISA tax-exempt framework expansion:Ultra High Net Worth Individuals are channeling greater allocations into alternative investment vehicles under Japan's revised NISA structure, deepening demand for specialized custody and reporting infrastructure.
- Tokyo-Osaka financial corridor concentration:Domestic trust banks and foreign wealth managers are expanding flagship advisory centers in Marunouchi and Roppongi to capture concentrated ultra-high-net-worth mandates.
- Certified financial planner workforce aging:The accelerating retirement of Japan's CFP cohort is creating urgent replacement demand for digitally-augmented relationship management platforms.
Market Restraints
- JFSA suitability enforcement:The Financial Services Agency's escalating disclosure requirements and product governance standards are compressing margin pools on structured products and concentrated equity positions.
- Domestic trust bank concentration:Mitsubishi UFJ, Mizuho, and Sumitomo Mitsui control the majority of custody infrastructure, limiting price competition and platform interoperability for foreign registered advisers.
- Inheritance tax regime uncertainty:Proposed revisions to Japan's inheritance tax framework are freezing long-term estate planning commitments as clients await clarity on domestic versus offshore structuring attractiveness.
Strategic Opportunities
- Kansai region penetration gap:Osaka and Kyoto present underdeveloped ultra-high-net-worth density relative to Tokyo, with limited dedicated private banking presence from foreign wealth managers.
- Digital onboarding for affluent segment:Below-threshold investors represent numerically significant addressable base for automated portfolio construction and tax-loss harvesting tools.
- METI-JFSA regulatory convergence:The alignment of stewardship code principles with customer-oriented business conduct rules creates compliant pathway for transparent fee-only advisory models.
Industry Challenges
- Cross-border succession expertise scarcity:Bilingual deal teams capable of navigating Japanese family office structures with US, Swiss, and Singapore tax considerations command premium compensation and limited supply.
- Legacy core banking integration:Trust banks' mainframe-dependent custody systems resist API connectivity with portfolio analytics platforms, delaying real-time reporting deployments.
- Multi-currency platform compliance:Constructing JFSA-registered vehicles that accommodate Switzerland-based wealth architecture requires extended licensing timelines and documented investment policy statement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Private Banking Market |
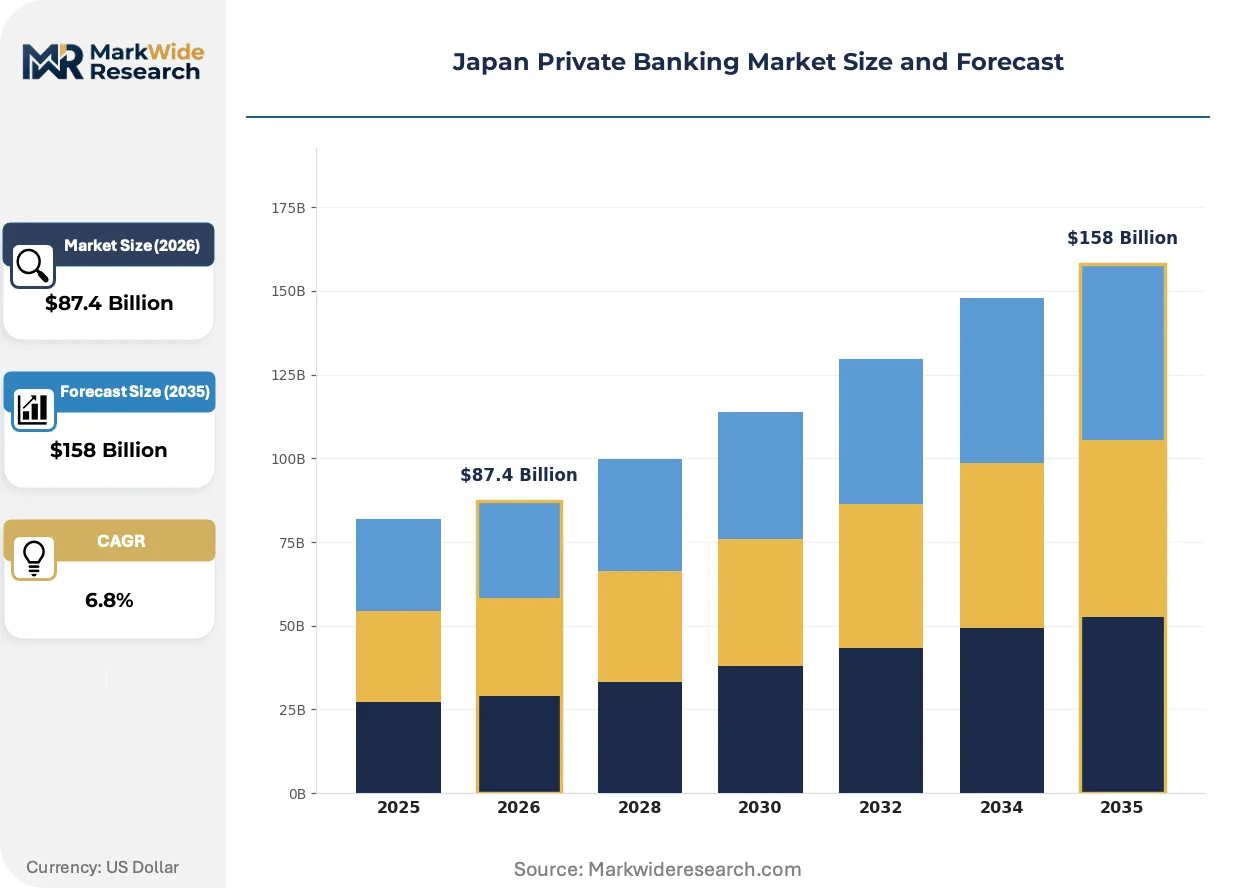
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: High Net Worth Individuals, Ultra High Net Worth Individuals, Affluent Investors, Retail Clients Service Type: Wealth Management, Investment Advisory, Estate Planning, Tax Optimization Investment Strategy: Equities, Fixed Income, Alternative Investments, Real Estate Channel: Direct Sales, Online Platforms, Branch Network, Wealth Advisors |
| Companies Covered | Nomura Holdings, UBS, Mitsubishi UFJ Morgan Stanley Private Banking, SBI Holdings, Japan Post Bank Co., Ltd., Sumitomo Mitsui Trust Bank, Daiwa Securities Group, Resona Holdings, Mizuho Private Wealth Management, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Private Banking Market Strategic Shifts
Technology deployment is fragmenting the traditional relationship-manager monopoly on investment decisions while regulatory pressure accelerates fee compression. Three shifts are restructuring how value is captured and delivered across Japan's private banking tier.
Portfolio analytics and artificial intelligence tools are fragmenting the concentration of discretionary authority that once resided solely with senior relationship managers. Domestic trust banks are deploying algorithmic rebalancing engines to augment aging CFP workforces, compressing the premium attached to traditional advisory relationships while expanding serviceable client ratios per front-office professional.
METI's stewardship code and the JFSA's principles for customer-oriented business conduct are mandating documented fee structures and investment policy statements across all registered advisers. This regulatory layering is elevating compliance costs for foreign wealth managers while creating structural advantage for institutions with existing trust bank infrastructure and native Japanese documentation capabilities.
Wealthy households are unbundling after-sales service expectations from core asset management relationships, demanding standalone succession planning, philanthropic structuring, and next-generation financial literacy programs. Domestic family offices in Tokyo's Minato ward are piloting subscription-based advisory retainers that separate ongoing counsel from transaction-dependent compensation, with Osaka-based enterprises beginning to replicate this procurement pattern.
Japan Private Banking Market Segmentation
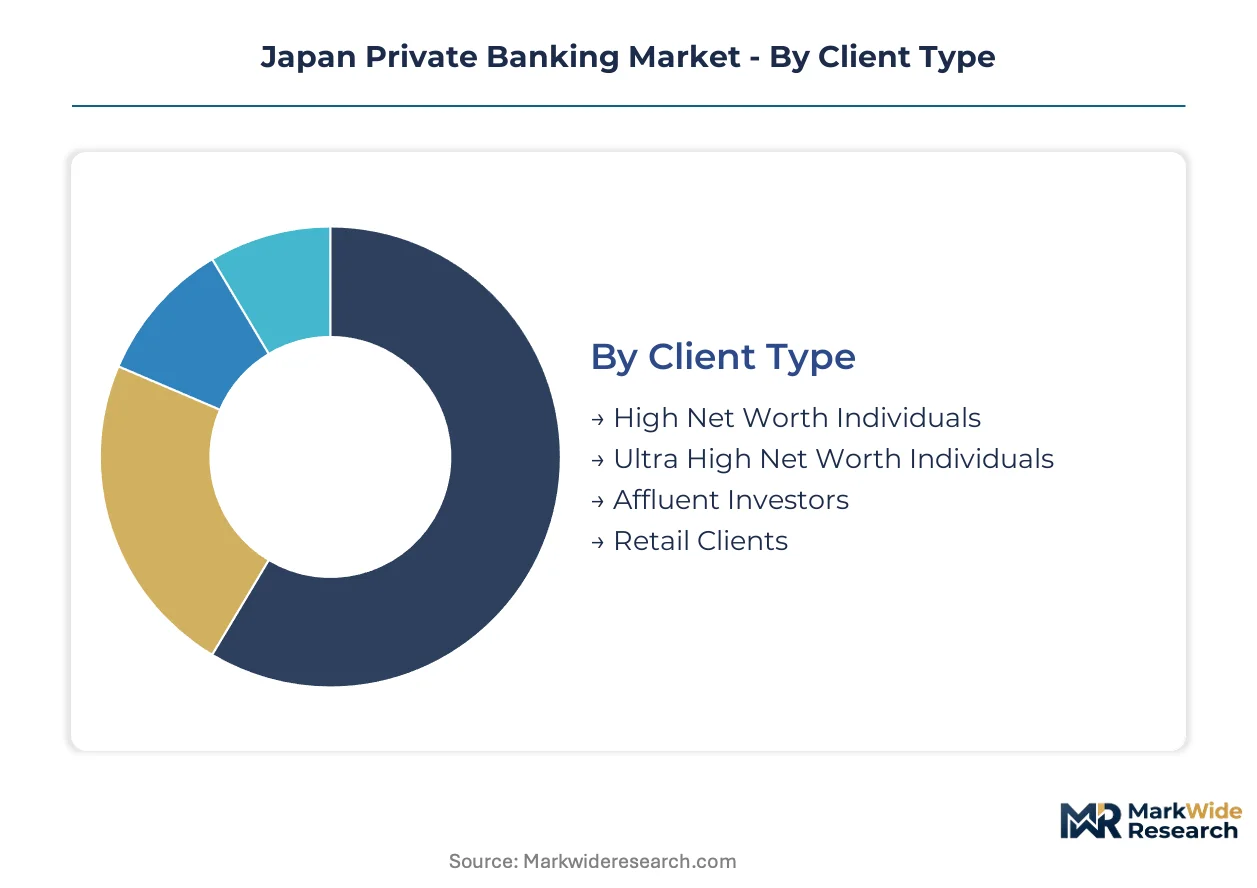
Segmentation in Japan's private banking market reveals how demographic pressures and regulatory frameworks reshape service delivery. Each dimension exposes distinct margin pressures and growth vectors across Tokyo's concentrated wealth corridors.
Client Type:
Margin pools concentrate at the apex of wealth concentration, where intergenerational complexity justifies premium advisory retainers.
- Ultra High Net Worth Individuals:Clients exceeding one hundred million yen in investable assets command bespoke succession planning and concentrated equity management. Demand clusters in Tokyo's Minato ward and Osaka's northern business district, driven by NISA framework expansion into alternative vehicles.
- High Net Worth Individuals:This tier requires documented investment policy statements under JFSA customer-oriented conduct rules. Marunouchi-based trust banks capture recurring revenue through discretionary mandates as certified financial planner retirements accelerate.
- Affluent Investors:Digital onboarding channels service this numerically significant base with automated portfolio construction tools.
- Retail Clients:Mass-market wealth products operate through branch networks with compressed fee structures.
Ultra High Net Worth Individuals hold installed capacity. Affluent Investors is rotating up the share rankings.
Service Type:
Service architecture separates transaction-dependent compensation from subscription-based advisory models as fee transparency mandates intensify.
- Estate Planning:Intergenerational wealth transfer mandates dominate advisory relationships in Japan's demographic inversion. Tokyo family offices demand bilingual structuring for cross-border succession, combining domestic trusts with Swiss and Singapore considerations.
- Wealth Management:Discretionary and non-discretionary asset management anchors revenue through custody infrastructure controlled by domestic trust banks. Roppongi advisory centers deploy multi-currency platforms for concentrated equity positions in unlisted enterprises.
- Investment Advisory:Non-discretionary counsel faces margin compression from algorithmic rebalancing engines.
- Tax Optimization:NISA wrapper structuring and inheritance tax regime navigation freeze long-term commitments pending regulatory clarity.
Estate Planning commands premium positioning. Tax Optimization is climbing the fastest as regime uncertainty persists.
Investment Strategy:
Strategy allocation reflects METI stewardship code pressures on documented environmental and governance integration.
- Alternative Investments:Private equity, hedge funds, and infrastructure vehicles deepen under revised NISA tax-exempt thresholds. Ultra-high-net-worth households in Tokyo channel greater allocations through specialized custody and reporting infrastructure.
- Real Estate:Direct property holdings and REIT exposure concentrate in Osaka-Kyoto corridor development projects, with limited foreign wealth manager penetration relative to Tokyo density.
- Equities:Concentrated positions in unlisted domestic enterprises require succession-integrated liquidation planning.
- Fixed Income:JGB and corporate bond ladders provide yield certainty for aging household cash flow requirements.
Alternative Investments holds installed capacity. Real Estate is gaining share fastest in regional wealth dispersion.
Channel:
Channel economics bifurcate between high-touch advisory for complex mandates and automated service for scalable segments.
- Wealth Advisors:Relationship managers augmented by portfolio analytics tools service ultra-high-net-worth complexity. Bicultural deal teams command premium compensation for navigating Japanese family office structures with US and Swiss tax considerations.
- Branch Network:Domestic trust banks maintain flagship advisory centers in Marunouchi and Roppongi for face-to-face estate planning execution.
- Online Platforms:Digital onboarding targets affluent investors below threshold with API-constrained integration to legacy custody systems.
- Direct Sales:Product-specific distribution operates through securities firm heritage channels with suitability documentation requirements.
Wealth Advisors holds installed capacity. Online Platforms is rotating up the share rankings as CFP workforce aging accelerates digital augmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto and Kansai regions deploy private banking services through fundamentally different channel architectures, with Tokyo favoring high-touch advisory centers while Osaka accelerates digital onboarding for affluent investors below ultra-high-net-worth thresholds.
Kanto/Tokyo
Ultra-high-net-worth households in Minato and Chiyoda wards drive demand for bilingual succession planning and cross-border trust structures. METI's stewardship code pressures documented fee transparency across Marunouchi advisory centers. Domestic trust banks and foreign wealth managers concentrate flagship operations in Roppongi Hills and Toranomon financial clusters, deploying multi-currency platforms for concentrated equity positions.
Kansai/Osaka
Family offices in northern Osaka business districts seek estate planning services with limited foreign wealth manager penetration relative to Tokyo density. JFSA customer-oriented conduct rules mandate investment policy statements for high-net-worth segments. Osaka-based enterprises pilot subscription-based advisory retainers that separate ongoing counsel from transaction-dependent compensation, replicating Minato ward procurement patterns.
Chubu/Nagoya
Manufacturing-derived wealth concentrates in Aichi prefecture, creating demand for intergenerational transfer of unlisted enterprise equity. Inheritance tax regime uncertainty freezes long-term commitments as clients await clarity on domestic versus offshore structuring attractiveness. Nagoya's Sakae district hosts limited dedicated private banking presence, with most mandates serviced through Tokyo-based relationship managers.
Kyushu
Fukuoka's emerging startup ecosystem generates first-generation wealth requiring foundational estate planning infrastructure. NISA tax-exempt framework expansion channels allocations into alternative vehicles, deepening demand for specialized custody and reporting. Regional banks maintain primary advisory relationships, with ultra-high-net-worth households traveling to Osaka or Tokyo for complex cross-border mandates.
Hokkaido
Agricultural and tourism-derived wealth in Sapporo presents underdeveloped ultra-high-net-worth density with minimal dedicated private banking infrastructure. Certified financial planner workforce aging accelerates digital augmentation for affluent segments below threshold. Most high-net-worth households rely on securities firm heritage channels with suitability documentation requirements rather than dedicated wealth management platforms.
Japan Private Banking Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with domestic trust banks controlling custody infrastructure while foreign registered advisers compete through bicultural deal teams. The market structure reflects concentration among three megabank trust operations alongside Swiss and US-based wealth managers with dedicated Japan platforms. Strategic archetypes include integrated trust-custody-advisory institutions, foreign wealth managers with multi-currency architecture, and securities heritage firms with CFP-augmented relationship management. Dominant competitive moves center on API integration with legacy core banking systems and geographic expansion into underpenetrated Kansai corridors.
Within the integrated trust bank tier, Mitsubishi UFJ Morgan Stanley Private Banking and Sumitomo Mitsui Trust Bank exemplify institutions leveraging custody infrastructure to anchor ultra-high-net-worth mandates. Nomura Holdings occupies a position representing securities heritage firms that deploy domestic brand recognition across Tokyo and Osaka advisory centers. UBS sits within the foreign wealth manager archetype, extending Switzerland-based architecture through JFSA-registered multi-currency platforms.
| Leading Market Players |
|---|
| Nomura Holdings |
| UBS |
| Mitsubishi UFJ Morgan Stanley Private Banking |
| SBI Holdings |
| Japan Post Bank Co., Ltd. |
| Sumitomo Mitsui Trust Bank |
| Daiwa Securities Group |
| Resona Holdings |
| Mizuho Private Wealth Management |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Japan's domestic trust banks anchors pricing power across custody infrastructure, compressing margin pools for foreign registered advisers while elevating fee floors for ultra-high-net-worth mandates requiring bilingual succession expertise.
Pricing Analysis
Long-term advisory retainers dominate ultra-high-net-worth relationships, while affluent segments gravitate toward subscription-based digital platforms. Price differentiation rests on certification tier—certified financial planner credentials command premium positioning—and geographic delivery cost, with Tokyo's Minato ward advisory centers extracting higher fees than Osaka equivalents. Pricing pressure stems from METI's stewardship code mandating documented fee transparency, eroding opaque product-linked compensation. Affluent investors exhibit highest price sensitivity, whereas family offices with cross-border succession complexity demonstrate lowest elasticity.
Supply Chain Analysis
Just-in-time talent deployment characterizes relationship management staffing as certified financial planner retirements accelerate. Human capital supply concentrates in Japan, Switzerland, and Singapore, where bicultural deal teams with US tax expertise command scarcity premiums. Raw material dependencies include proprietary custody infrastructure, multi-currency platform licenses, and JFSA regulatory documentation capabilities. Single-source vulnerability sits with Mitsubishi UFJ, Mizuho, and Sumitomo Mitsui trust bank concentration controlling API-constrained legacy systems. Distribution runs through flagship advisory centers in Marunouchi and Roppongi for high-touch mandates, supplemented by digital channels for scalable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of bilingual succession specialists capable of navigating Japanese family office structures with Swiss and US tax considerations concentrates competitive advantage among institutions with established trust bank infrastructure and native documentation capabilities.
For Market Incumbents: Consolidate custody infrastructure advantage through API integration investments that bridge legacy core banking systems with portfolio analytics platforms. Deepen vertical integration into estate planning capabilities to offset margin compression from JFSA suitability enforcement on structured products. Prioritize Kansai corridor expansion before foreign wealth managers establish Osaka presence. For New Entrants and Emerging Players: Lead with digital onboarding tools targeting affluent investors below ultra-high-net-worth thresholds, where certified financial planner workforce aging creates service gaps. Osaka and Kyoto present underpenetrated density relative to Tokyo. Deploy subscription-based advisory retainers replicating Minato ward procurement patterns without transaction-dependent compensation baggage. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors institutions with existing JFSA-registered multi-currency platforms and native Japanese documentation capabilities over foreign wealth managers facing extended licensing timelines. Long-term viability hinges on succession planning demand intensifying through demographic inversion. Watch for inheritance tax regime clarity as inflection indicator for estate planning commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration with Legacy Custody Systems | Enables real-time portfolio analytics for aging CFP-augmented relationship teams at domestic trust banks. |
| Kansai Region Advisory Center Expansion | Captures Osaka-Kyoto ultra-high-net-worth density before foreign wealth managers establish dedicated presence. |
| Subscription-Based Advisory Retainer Launch | Separates ongoing counsel from transaction fees under METI-JFSA fee transparency convergence. |
| Bicultural Deal Team Recruitment | Addresses scarcity of specialists navigating Japanese family offices with Swiss and US tax considerations. |
| Multi-Currency Platform JFSA Registration | Extends Switzerland-based wealth architecture through compliant vehicles with documented investment policy protocols. |
Study Parameters
A spread of perspectives from private banking relationship managers, trust bank custody infrastructure heads, certified financial planner educators, JFSA regulatory affairs specialists, and family office principals converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Financial Services Agency disclosure filings, METI stewardship code implementation reports, Japan Trustee Services Bank data, and securities firm regulatory submissions. Bottom-up client segmentation analysis triangulated against top-down market sizing from trust bank AUM disclosures.
Segmentation dimensions modeled span client type tiers, service architecture categories, investment strategy allocations, and channel economics across the projection horizon. CAGRs derived from trend extrapolation of NISA framework utilization, demographic transition timelines, and regulatory implementation schedules. Forecast inputs incorporated certified financial planner workforce retirement curves and inheritance tax regime scenario probabilities.
The analysis sits within stated boundaries; outcomes outside sustained NISA expansion, stable JFSA enforcement posture, or predictable demographic transition would require recalibration. Forecasts reflect assumptions regarding regulatory continuity and wealth transfer velocity. Revision becomes warranted when inheritance tax regime uncertainty crosses thresholds into legislative clarity or when foreign wealth manager licensing timelines compress materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Private Banking Market