
 Global Wealth Management Platform Market | 2026-2036
Global Wealth Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wealth Management Platform Market Foresight
The wealth management platform landscape is rebalancing around a widening capability gap between premium enterprise suites and commoditized back-office tools. SS&C Technologies leverages its custody-technology heritage to anchor complex multi-asset workflows for institutional clients. Envestnet competes through open-architecture aggregation that sustains advisor-facing marketplaces across fragmented data sources.
A wealth management platform is an integrated software environment that unifies portfolio analytics, risk engines, client reporting, and regulatory compliance modules through APIs and data lakes, typically processing sub-second rebalancing across thousands of accounts. Its commercial purpose centers on enabling advisors to scale personalized investment strategies while automating fiduciary documentation and audit trails. Cloud-based deployment leads solution uptake as asset managers outsource infrastructure to reduce capital intensity, while compliance monitoring commands disproportionate margin pools due to jurisdictional complexity. Portfolio management retains volume dominance but faces modular unbundling as point solutions from specialized vendors erode bundled pricing power.
SEC oversight in the United States, FINMA guidelines in Switzerland, and MAS technology risk management requirements in Singapore collectively elevate platform standards around data residency, algorithmic transparency, and cybersecurity attestations. The EU AI Act adds a cross-border layer by classifying certain robo-advisory outputs as high-risk AI systems, forcing architecture redesigns for firms serving European clients. Stakeholders must weigh regulatory divergence against the cost of maintaining jurisdiction-specific platform variants versus unified global deployments.
Market Dynamics
The wealth management platform sector is rebalancing around algorithmic transparency mandates from the EU AI Act, which force architecture redesigns for cross-border advisory services while creating compliance-driven procurement cycles among multi-jurisdictional asset managers.
Growth Catalysts
- EU AI Act algorithmic classification:High-risk system designations for robo-advisory outputs create mandatory upgrade cycles across European client bases, accelerating replacement of legacy compliance modules.
- Family office technology consolidation:Single-family and multi-family offices in Singapore and Switzerland are unifying fragmented point solutions into integrated environments to reduce operational overhead across dispersed asset holdings.
- Cloud infrastructure outsourcing:Asset managers are migrating core portfolio analytics to hosted environments to eliminate capital-intensive data center maintenance and redirect resources toward client-facing capabilities.
Market Restraints
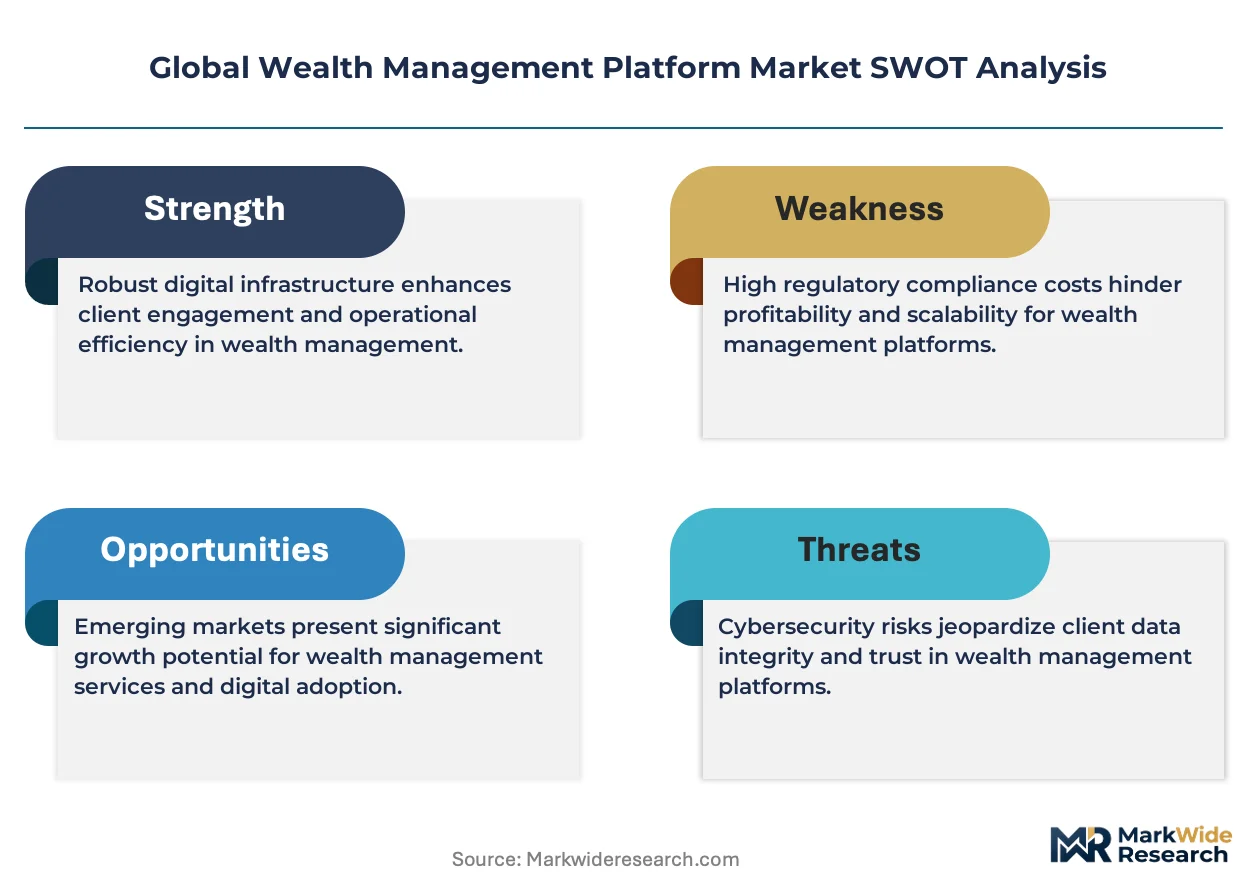
- Data residency fragmentation:Divergent SEC, FINMA, and MAS requirements for audit trail localization force vendors to maintain jurisdiction-specific platform variants, inflating engineering overhead.
- Cybersecurity attestation costs:Third-party penetration testing and SOC 2 Type II certification for multi-tenant environments impose recurring compliance burdens that compress margins for mid-tier providers.
- Specialized vendor unbundling:Point solutions for ESG scoring, alternative asset valuation, and tax-loss harvesting are eroding pricing power of bundled enterprise suites through modular API integration.
Strategic Opportunities
- India private wealth expansion:SEBI-registered investment advisors and portfolio managers are digitizing operations to serve HNI segments in Mumbai and Delhi, creating demand for localized compliance automation.
- Generative AI document synthesis:Large language models are converging with structured portfolio data to automate regulatory filing preparation and client communication personalization at scale.
- Carbon accounting integration:CSRD-aligned scope 3 emissions tracking for investment portfolios opens advisory fee premiums as European institutional clients mandate climate disclosure alignment.
Industry Challenges
- Quantitative risk engineering scarcity:Platforms struggle to recruit talent capable of building stochastic models for complex derivatives and private market illiquidity stress testing.
- Legacy core banking integration:SOAP-based mainframe connections at established custodians require expensive middleware development to enable real-time position reconciliation with modern REST API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wealth Management Platform Market |
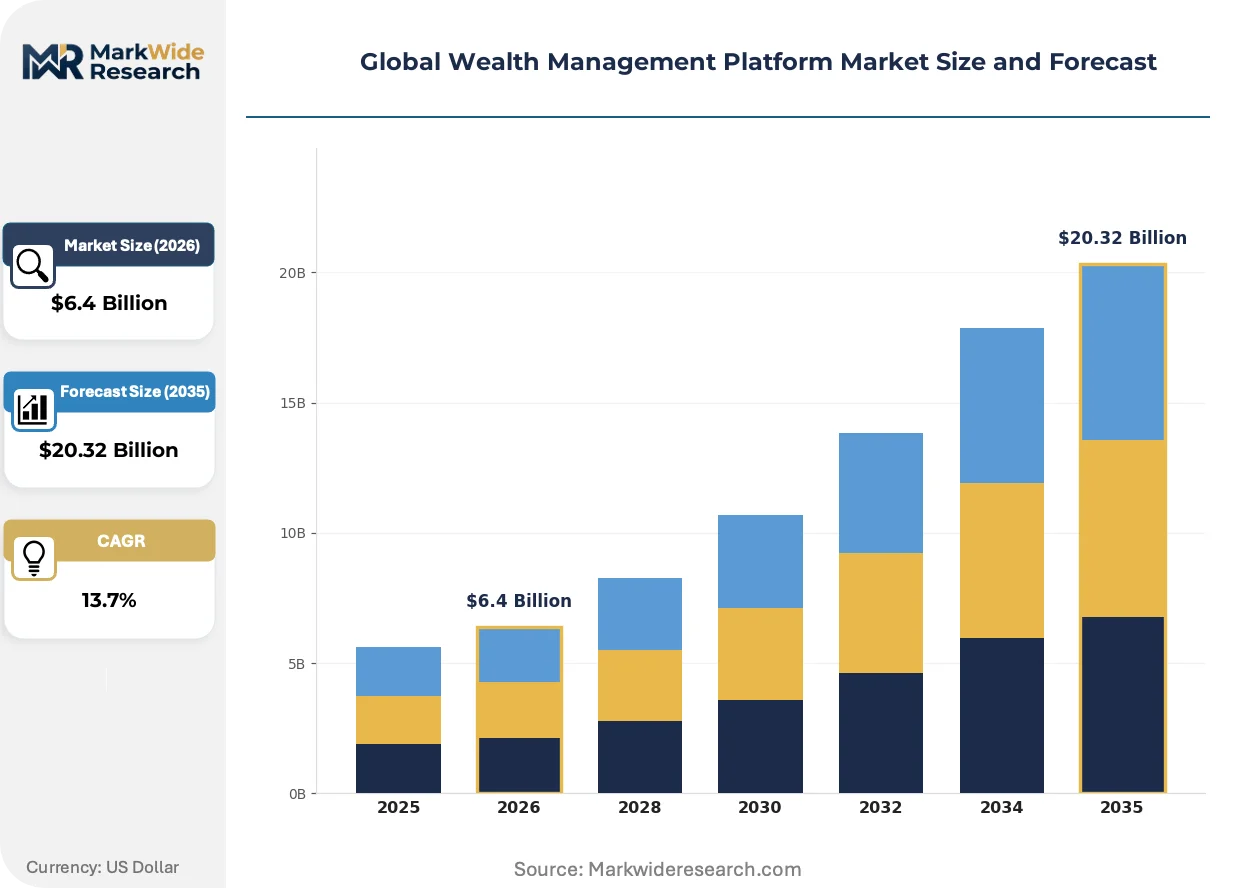
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $20.32 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Portfolio Management, Risk Assessment, Financial Planning, Client Reporting, Compliance Monitoring End User: Private Banks, Family Offices, Asset Managers, Brokerage Firms, Registered Investment Advisors Investment Strategy: Growth Investing, Income Investing, Value Investing, Balanced Strategy, Alternative Investments |
| Companies Covered | SS&C Technologies, Fidelity National Information Services, BlackRock, Temenos, Broadridge Financial Solutions, Avaloq Group, Envestnet, SEI Investments Company, Fiserv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wealth Management Platform Market Shifts & Advancements
Generative AI and embedded compliance engines are compressing the traditional trade-off between advisor productivity and regulatory precision, enabling mass-customization of fiduciary services previously reserved for ultra-high-net-worth segments.
Embedded finance infrastructure is converging with wealth management workflows to enable real-time portfolio funding through banking-as-a-service integrations. Retail brokerages and neobanks in Brazil and Mexico are white-labeling robo-advisory engines to capture deposit-to-investment conversion. This convergence is collapsing the historical separation between transactional banking and discretionary portfolio management into unified mobile experiences.
The EU AI Act's high-risk system classification for algorithmic investment advice triggers mandatory human-in-the-loop documentation and explicability requirements. European wealth managers must redesign model governance frameworks to satisfy conformity assessments before deploying automated rebalancing. Firms serving cross-border clients are segmenting their technology stacks to isolate European advisory logic from less restrictive jurisdictions.
Advisory fee compression is accelerating unbundling of portfolio construction from ongoing relationship management. Family offices in Singapore are negotiating à-la-carte platform access, paying only for compliance monitoring and tax reporting while sourcing investment research through independent channels. This pattern fragments vendor revenue streams and rewards modular architecture flexibility over bundled feature depth.
Global Wealth Management Platform Market Segmentation
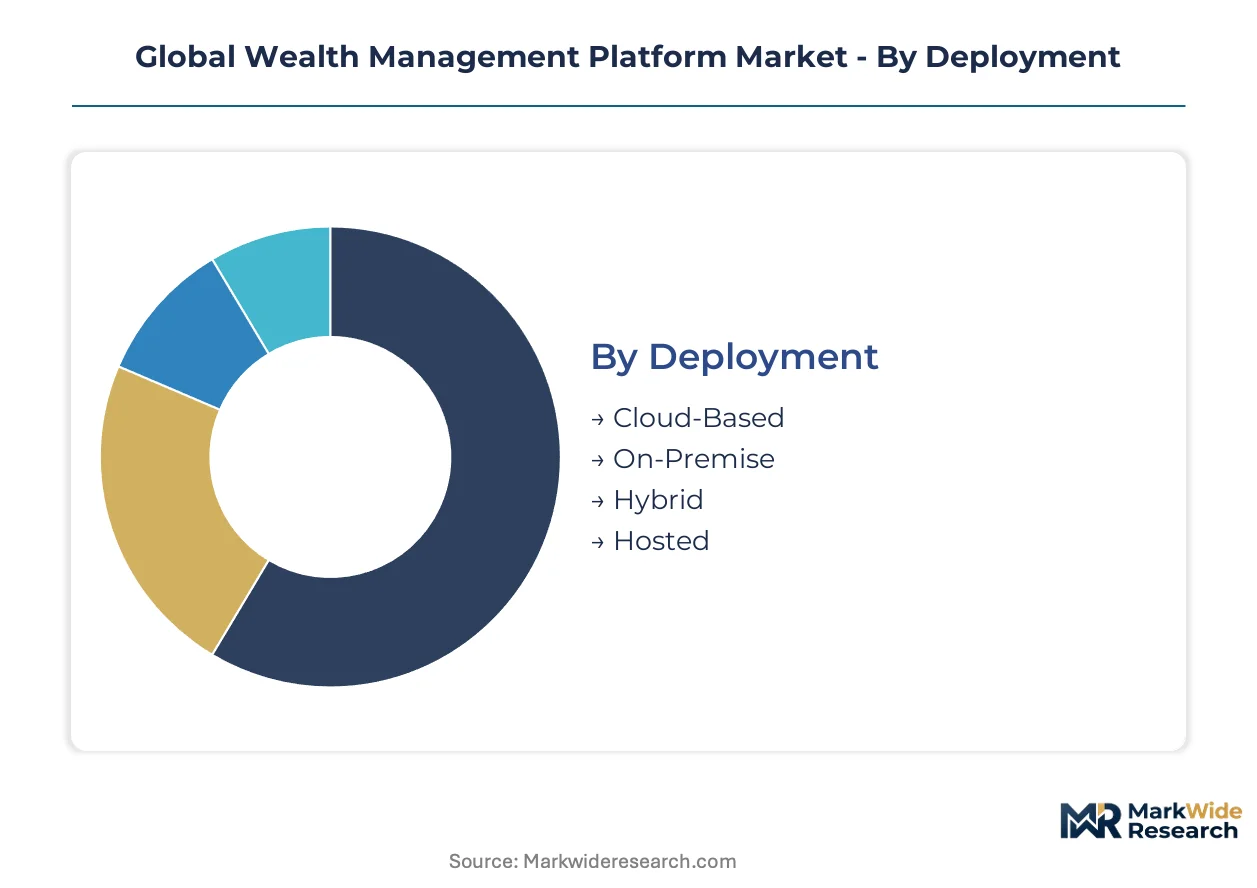
Deployment architecture determines total cost of ownership and regulatory flexibility for wealth managers operating across multiple jurisdictions. Solution modularity shapes competitive positioning as family offices and registered investment advisors demand configurable workflows over monolithic suites.
Deployment:
Buyer decisions hinge on data sovereignty requirements versus capital efficiency trade-offs across custody relationships.
- Cloud-Based:Multi-tenant SaaS environments deliver elastic compute for portfolio rebalancing and eliminate data center capital expenditure. Demand concentrates among mid-sized asset managers in Singapore and Switzerland seeking rapid scaling without infrastructure buildout.
- On-Premise:Dedicated hardware installations within client facilities satisfy FINMA and SEC audit trail localization mandates. Large private banks in Zurich and New York maintain on-premise stacks to preserve direct custody integration and sub-millisecond latency for high-frequency overlay strategies.
- Hybrid:Split architectures isolate sensitive client data on-premise while offloading analytics workloads to cloud instances.
- Hosted:Single-tenant managed deployments at vendor data centers bridge compliance control with outsourced maintenance.
Volume sits with Cloud-Based; growth tilts toward Hybrid as cross-border managers segment data residency by jurisdiction.
Solution Type:
Functional priority follows regulatory pressure intensity, with automation of fiduciary documentation commanding premium pricing.
- Compliance Monitoring:Real-time surveillance engines track SEC, FINMA, and MAS rule changes across advisory workflows and flag potential violations before execution. European wealth managers facing EU AI Act high-risk system classifications are procuring upgraded modules to automate human-in-the-loop documentation.
- Portfolio Management:Unified analytics environments aggregate multi-asset positions across custodians and calculate risk-adjusted performance attribution. Family offices in Singapore drive demand for platforms handling private market illiquidity alongside public securities.
- Risk Assessment:Stochastic engines model tail scenarios for derivatives and alternative asset exposures.
- Financial Planning:Goal-based engines project lifetime cash flows and tax-optimized withdrawal sequences.
- Client Reporting:Automated document generation produces personalized statements and regulatory filings.
Revenue concentrates in Portfolio Management; margin expansion is climbing the fastest in Compliance Monitoring due to jurisdictional complexity.
End User:
Organizational sophistication determines integration depth, with multi-family offices requiring the most fragmented data aggregation.
- Family Offices:Single and multi-family entities manage dispersed holdings across real estate, private equity, and liquid portfolios through unified platforms. Singapore-based multi-family offices are consolidating point solutions to reduce operational overhead across generational wealth transfers.
- Asset Managers:Institutional firms scale model portfolio distribution to thousands of accounts through centralized rebalancing engines. US-registered investment advisors leverage open-architecture aggregation to serve fragmented data sources.
- Private Banks:Full-service institutions embed platforms within relationship management workflows.
- Brokerage Firms:Transactional platforms integrate robo-advisory engines for deposit-to-investment conversion.
- Registered Investment Advisors:Independent fiduciaries prioritize cost-efficient compliance automation.
Asset Managers anchor volume; Family Offices are expanding most quickly as operational complexity drives technology consolidation.
Investment Strategy:
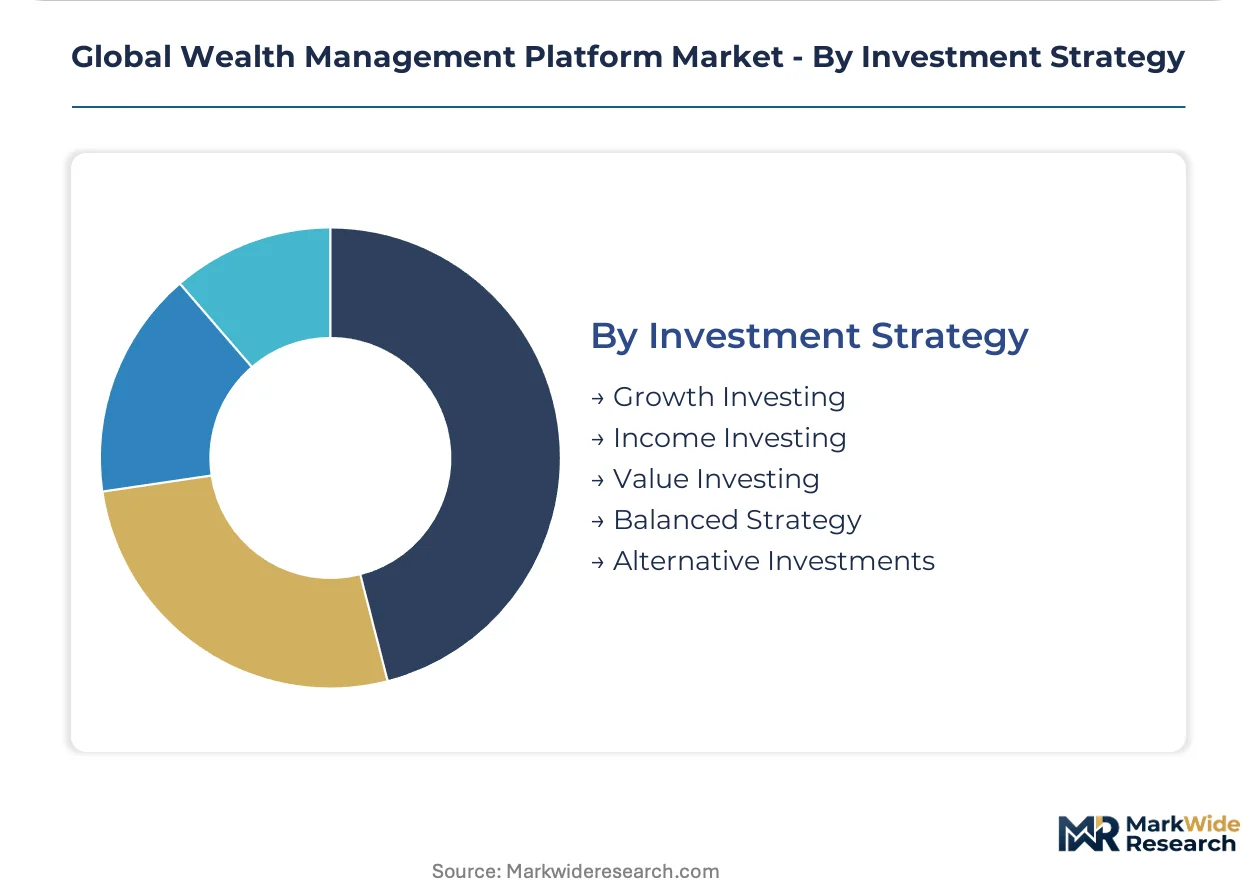
Strategy specialization shapes data requirements, with alternative assets demanding bespoke valuation and liquidity frameworks.
- Alternative Investments:Platforms track private equity, hedge fund, and real asset exposures with customized waterfall calculations and capital call forecasting. Swiss family offices allocate increasing platform budgets to alternatives modules as direct deal activity rises.
- Growth Investing:Momentum-oriented analytics screen high-growth equities and venture exposures with sector-specific valuation multiples. Technology-focused advisors in California and Tel Aviv demand integrated ESG scoring for growth portfolio construction.
- Income Investing:Yield-focused engines optimize fixed income ladders and dividend sustainability analysis.
- Value Investing:Fundamental screening tools identify mispriced securities through discounted cash flow automation.
- Balanced Strategy:Glide path engines adjust equity-fixed income mixes by client life stage and risk tolerance.
Balanced Strategy holds the largest installed base; Alternative Investments shows the steepest expansion trajectory as illiquid allocations rise across private wealth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors the highest concentration of family office platform deployments outside Zurich, with asset managers clustering around the Monetary Authority of Singapore's regulatory sandbox framework.
United States
Registered investment advisors in New York and Boston drive demand for open-architecture aggregation tools that reconcile fragmented custodial data. SEC oversight mandates algorithmic transparency documentation for robo-advisory outputs, forcing architecture upgrades across multi-state advisory networks. Silicon Valley technology corridors incubate specialized vendors targeting venture-capital-backed wealth managers with API-first portfolio construction modules.
Switzerland
Private banks in Zurich and Geneva maintain on-premise installations to satisfy FINMA audit trail localization requirements for ultra-high-net-worth client segments. The Swiss Financial Market Supervisory Authority's cybersecurity attestation standards elevate platform procurement criteria beyond neighboring jurisdictions. Zug's crypto valley corridor attracts wealth managers seeking hybrid architectures that bridge traditional custody with digital asset portfolio tracking.
Singapore
Multi-family offices consolidate point solutions into unified environments to manage dispersed holdings across Southeast Asian real estate and liquid portfolios. MAS technology risk management requirements mandate penetration testing and SOC 2 Type II certification for multi-tenant deployments. The Raffles Place financial district hosts the region's densest concentration of cloud-based platform implementations among mid-sized asset managers.
United Kingdom
Wealth managers in London's Square Mile procure compliance monitoring modules to automate FCA regulatory filing preparation and client suitability documentation. The Financial Conduct Authority's operational resilience requirements force business continuity architecture redesigns for advisory platforms serving retail investors. Canary Wharf technology clusters incubate vendors specializing in generative AI document synthesis for regulatory communication personalization.
India
SEBI-registered investment advisors in Mumbai and Delhi digitize operations to serve high-net-worth segments with localized compliance automation. Securities and Exchange Board of India regulations mandate portfolio manager registration and disclosure standards that elevate platform procurement criteria. The Bandra-Kurla Complex financial district attracts vendors configuring India-specific tax-loss harvesting and capital gains reporting modules.
Global Wealth Management Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across custody-technology heritage and compliance automation depth, with the sector consolidating around three structural tiers. Enterprise suites anchored by custody-technology heritage command pricing power through sub-millisecond latency and direct mainframe integration. Mid-tier providers compete through modular API architectures that unbundle portfolio construction from relationship management. Commodity players face margin compression as specialized vendors erode bundled pricing through point solutions for ESG scoring and alternative asset valuation. Dominant competitive moves include strategic partnerships with neobanks for embedded finance integration and geographic expansion into India and Brazil through localized compliance modules.
Within the custody-technology tier, SS&C Technologies and Fidelity National Information Services occupy positions defined by multi-asset workflow complexity and institutional client concentration. Envestnet exemplifies the open-architecture aggregation archetype, competing through advisor-facing marketplaces that sustain fragmented data source reconciliation. BlackRock represents the asset-manager-owned platform model, leveraging proprietary risk analytics and model portfolio distribution scale across thousands of advisory accounts. Temenos and Avaloq Group anchor European private banking specialization, with architecture designs shaped by EU AI Act high-risk system classifications and FINMA cybersecurity attestations.
| Leading Market Players |
|---|
| SS&C Technologies |
| Fidelity National Information Services |
| BlackRock |
| Temenos |
| Broadridge Financial Solutions |
| Avaloq Group |
| Envestnet |
| SEI Investments Company |
| Fiserv |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs cascade through wealth management platform pricing tiers, with multi-tenant SaaS compute expenses compressing entry-level subscription rates while FINMA-mandated data residency requirements inflate on-premise premiums for Zurich and Geneva private banks.
Pricing Analysis
Outcome-based pricing tied to advisory assets under management anchors enterprise negotiations, with custody-technology heritage vendors commanding premium tiers through sub-millisecond latency guarantees. Price differentiation separates SOC 2 Type II certified environments from uncertified alternatives, while EU AI Act compliance modules extract further premiums from European client bases. Cost compression in mid-tier SaaS subscriptions intensifies as specialized ESG and alternative asset valuation APIs erode bundled suite pricing power. Registered investment advisors exhibit highest price sensitivity, whereas Singapore multi-family offices prioritize compliance automation depth over per-seat economics.
Supply Chain Analysis
Regional distribution centers in Singapore, Switzerland, and the United States anchor hub-and-spoke delivery patterns for platform implementations, with MAS technology risk management requirements mandating localized penetration testing nodes. Engineering talent pools draw from India, Poland, and Portugal for back-end development, while front-end UX specialists concentrate in London and New York. Single-source vulnerability sits with hyperscaler cloud infrastructure dependencies for AWS, Azure, and Google Cloud regions. Distribution runs through direct enterprise sales teams for institutional clients and advisor-facing marketplaces for mid-tier aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wealth management platform market reads as a cost-of-compliance story, with the EU AI Act's high-risk system classification creating a regulatory moat that favors incumbents bearing certification infrastructure investments.
For Market Incumbents: Acquire specialized alternative asset valuation engines to defend against modular unbundling by ESG-scoring point solution vendors. Consolidate middleware development capabilities for SOAP-to-REST mainframe integration, as legacy custody connections remain sticky with Zurich and New York private banks. Channel control through embedded finance partnerships with Brazil and Mexico neobanks represents the priority lever against open-architecture aggregators. For New Entrants and Emerging Players: Launch via white-label robo-advisory distribution to Brazil and Mexico retail brokerages seeking deposit-to-investment conversion infrastructure. Target SEBI-registered investment advisors in Mumbai and Delhi with India-specific tax-loss harvesting modules, as localization gaps persist among global vendors. Regulatory sandbox participation through MAS frameworks offers the most penetrable entry path for cloud-native architectures. For Investors and Strategic Acquirers: Distressed-cycle entries favor custody-technology specialists with FINMA cybersecurity attestations in Switzerland, as compliance overhead deters new capital formation. Long-term viability centers on platforms bridging generative AI document synthesis with structured portfolio data infrastructure. Watch EU AI Act conformity assessment timelines as the inflection signal for European procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Module Development | Automates human-in-the-loop documentation for high-risk robo-advisory outputs under European regulator mandates. |
| Embedded Finance Integration Partnership | Enables real-time portfolio funding through banking-as-a-service APIs at Brazil and Mexico neobanks. |
| Alternative Asset Valuation Acquisition | Captures private equity waterfall modeling demand from Singapore multi-family offices deploying direct deal capital. |
| India Localization Buildout | Configures SEBI-mandated disclosure standards and capital gains reporting for Mumbai and Delhi advisory networks. |
| Generative AI Document Synthesis Launch | Automates regulatory filing preparation and client communication personalization at UK wealth managers facing FCA operational resilience requirements. |
Research Methodology
SEC disclosure filings, MAS regulatory sandbox participant lists, and EU AI Act implementation guidance formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with wealth management platform CTOs, family office chief operating officers, and SEBI-registered portfolio managers validated architecture deployment patterns and procurement timelines. Bottom-up account-level aggregation across 15 countries combined with top-down sector expenditure analysis to triangulate installed base estimates and replacement cycle assumptions.
Historical trendline analysis of custody-technology spending and compliance automation procurement established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated deployment architecture, solution type modularity, end-user organizational sophistication, and investment strategy specialization dimensions. CAGRs derived from vendor revenue disclosures and advisory asset growth correlations, with cloud migration velocity and regulatory upgrade cycle intensity serving as primary forecast inputs.
EU AI Act enforcement delays, FINMA audit trail localization requirement modifications, and hyperscaler cloud pricing volatility are the dominant revision risks to platform adoption assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Wealth Management Software Market