
 Asia Pacific Private Banking Market | 2026-2036
Asia Pacific Private Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Private Banking Market Analysis
Wealth concentration among first-generation entrepreneurs across Southeast Asia is restructuring how private banks allocate relationship manager resources and customize product shelves. UBS Global Wealth Management leverages its Swiss-Asian booking center network to sustain cross-border advisory capabilities. DBS Private Bank anchors Singapore-dollar denominated wealth solutions for regional family offices. HSBC Private Banking competes through its Greater China corridor expertise and mainland China license access.
Asia Pacific private banking encompasses personalized financial services delivering investment management, estate structuring, and tax optimization to affluent individuals and their holding vehicles, typically requiring minimum investable assets exceeding one million dollars and operating through fiduciary mandates with discretionary portfolio authority. The client type dimension shows ultra high net worth individuals commanding the deepest margin pools due to complexity-driven fee structures, while family offices represent the fastest-growing category as multi-generational wealth transfer accelerates across Indonesia and Vietnam. Within service type, wealth advisory and estate planning together capture premium pricing power where jurisdictional expertise in Singapore trust law and Hong Kong succession frameworks differentiates provider profitability.
The Monetary Authority of Singapore imposes stringent fit-and-proper criteria on private banking licenses, while Hong Kong's Securities and Futures Commission mandates enhanced due diligence for cross-border client relationships, collectively elevating compliance infrastructure costs but also filtering out marginal competitors. India's SEBI and RBI jointly oversee foreign portfolio investment channels that private banks utilize for non-resident Indian wealth repatriation, adding regulatory layering to product architecture. Stakeholders must monitor how Australia's ASIC disclosure reforms and Japan's FSA stewardship code expectations reshape fee transparency and product suitability standards across the region.
Market Dynamics
Cross-border wealth mobility among first-generation entrepreneurs is fragmenting traditional relationship-banker coverage models across Southeast Asia, forcing private banks to reconstruct their geographic resource allocation and product localization strategies.
Growth Catalysts
- Family office registrations:Singapore's regulatory enhancements for single-family offices are attracting mainland Chinese and Indian capital, expanding the addressable client base for fiduciary services.
- Digital onboarding infrastructure:Biometric identity verification and distributed ledger-based KYC protocols are compressing client acquisition timelines from months to weeks.
- Intergenerational wealth transfer:Indonesia and Vietnam are experiencing accelerated succession events among manufacturing and commodity fortunes, generating demand for estate structuring and trust administration.
Market Restraints
- Compliance infrastructure costs:The Monetary Authority of Singapore's fit-and-proper licensing criteria and Hong Kong's Securities and Futures Commission cross-border due diligence mandates are elevating fixed cost bases for smaller competitors.
- Relationship manager scarcity:Mandarin-speaking private bankers with jurisdictional expertise in both Singapore trust law and Hong Kong succession frameworks command compensation premiums that compress margin structures.
- Capital repatriation friction:India's SEBI and RBI joint oversight of foreign portfolio investment channels creates regulatory layering that delays product architecture for non-resident Indian wealth.
Strategic Opportunities
- Vietnam's emerging ultra-affluent:Ho Chi Minh City and Hanoi are producing first-generation technology and real estate fortunes with minimal incumbent private banking penetration.
- Islamic wealth solutions:Malaysia's regulatory framework for Shariah-compliant trust structures offers a template for capturing Indonesian Muslim family office demand.
- Philanthropic advisory services:Australia's ASIC disclosure reforms on fee transparency are creating precedent for structured giving vehicles that blend tax optimization with impact measurement.
Industry Challenges
- Legacy system integration:Established private banks face technical debt when embedding API-based portfolio analytics into core banking platforms originally architected for discretionary mandates.
- Certification timelines:Japan's FSA stewardship code expectations require relationship managers to complete specialized sustainability disclosure training before advising on ESG-integrated mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Private Banking Market |
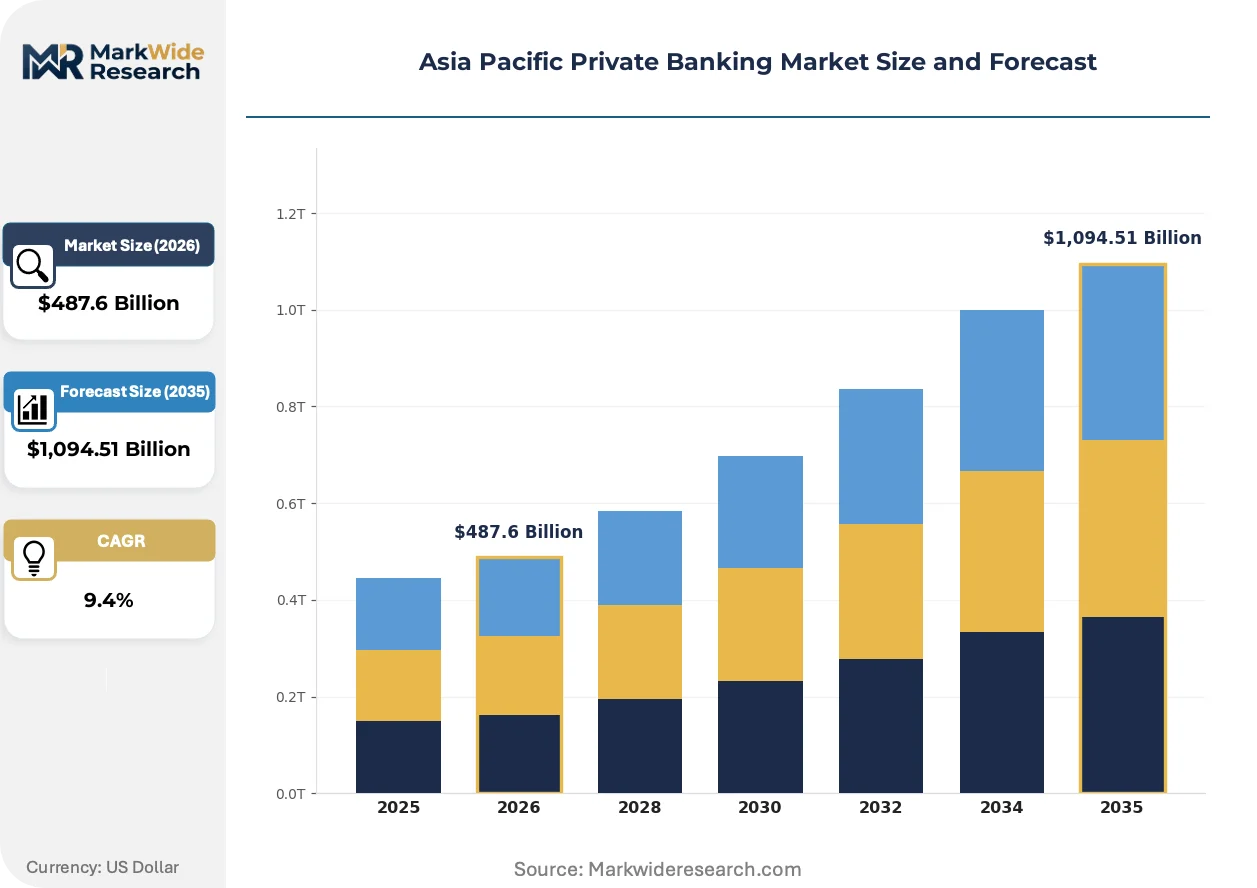
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,094.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: High Net Worth Individuals, Ultra High Net Worth Individuals, Family Offices, Corporations Service Type: Investment Management, Estate Planning, Wealth Advisory, Tax Optimization Delivery Model: In-Person Consulting, Remote Advisory, Digital Platforms, Hybrid Services Financial Product: Mutual Funds, Hedge Funds, Private Equity, Structured Products |
| Companies Covered | J.P. Morgan Private Bank, BNP Paribas Wealth Management, DBS Private Bank, PineBridge, OCBC, UBS Global Wealth Management, Bank of Singapore, SC Lowy, HSBC Private Banking, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Private Banking Market Emerging Trajectories
Distributed ledger infrastructure and algorithmic portfolio construction are compressing the traditional boundary between high-touch advisory and self-directed wealth management across Asia Pacific booking centers.
Blockchain-based asset tokenization is decentralizing custody arrangements for alternative investments including private equity and real estate exposure. Family offices in Singapore and Hong Kong are piloting fractionalized direct investment structures that bypass traditional fund-of-funds fee layers. This architecture is decentralizing control over portfolio construction from bank-managed discretionary mandates toward client-directed allocation frameworks.
Singapore's variable capital company legislation and Hong Kong's open-ended fund company regime are converging to create standardized holding vehicle templates for cross-border wealth structures. The industrial consequence is reduced legal documentation friction for multi-jurisdictional family office setups. Ultra high net worth individuals with holdings across mainland China, India, and Southeast Asia are responding by consolidating booking center relationships in Singapore rather than maintaining fragmented European or Caribbean structures.
Subscription-based advisory pricing is displacing traditional asset-under-management fee calculations among technology-entrepreneur clients. This model unbundles investment management from financial planning and estate structuring services. The shift is most visible in Hong Kong, where mainland Chinese fintech founders prefer transparent fixed fees over percentage-based arrangements that obscure total cost of ownership across complex cross-border holdings.
Asia Pacific Private Banking Market Segmentation
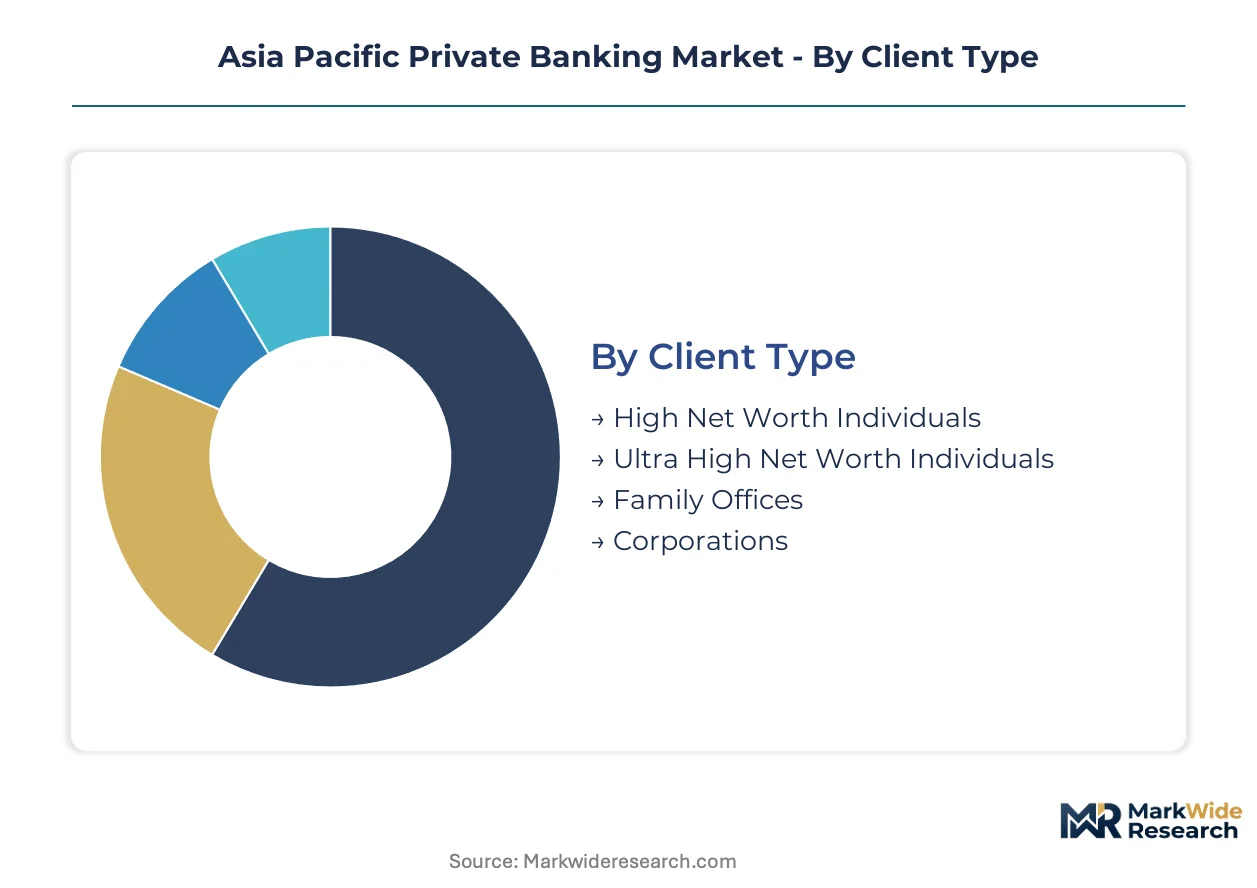
Segmentation in Asia Pacific private banking determines how relationship managers allocate time across complexity tiers and which compliance protocols apply to each engagement. Banks calibrate product shelves, pricing frameworks, and regulatory coverage based on these dimensional cuts.
Client Type:
Ultra high net worth individuals generate disproportionate revenue per relationship hour, while family offices are expanding most quickly across Singapore and Hong Kong booking centers.
- Ultra High Net Worth Individuals:Clients with investable assets exceeding thirty million dollars command complexity-driven fee structures for multi-jurisdictional holdings. Singapore's Monetary Authority reports concentrated demand from mainland Chinese entrepreneurs restructuring manufacturing fortunes through Singapore trust law frameworks.
- Family Offices:Single and multi-family vehicles manage consolidated balance sheets across generations, requiring fiduciary mandates with discretionary authority. Indonesia and Vietnam are producing first-generation family office formations as manufacturing and commodity wealth transfers accelerate.
- High Net Worth Individuals:Entry-tier clients with one to thirty million in investable assets receive standardized product shelves with limited customization.
- Corporations:Treasury and pension fund vehicles require institutional-grade custody and liquidity management rather than personalized estate structuring.
Today's leader: Ultra High Net Worth Individuals. Tomorrow's challenger: Family Offices.
Service Type:
Margin concentration follows jurisdictional expertise rather than transaction volume, with cross-border structuring commanding premium pricing.
- Wealth Advisory:Holistic financial planning integrates investment allocation with liability management and liquidity forecasting. Hong Kong's Securities and Futures Commission mandates enhanced due diligence for cross-border advisory relationships, elevating compliance costs but filtering marginal competitors.
- Estate Planning:Trust administration and succession frameworks require expertise in Singapore trust law and Hong Kong probate regimes. Demand concentrates among Indonesian and Vietnamese families navigating first-generation wealth transfer events.
- Investment Management:Discretionary portfolio construction spans traditional and alternative allocations.
- Tax Optimization:Jurisdictional arbitrage and treaty structuring minimize effective tax rates across multi-country holdings.
Wealth Advisory anchors current profitability. Estate Planning is gaining share fastest as generational turnover accelerates.
Delivery Model:
Digital infrastructure investment is compressing client acquisition timelines while preserving relationship-manager touchpoints for complexity.
- Hybrid Services:Blended models combine digital onboarding with scheduled relationship-manager reviews for strategic decisions. Singapore's biometric identity verification and distributed ledger-based KYC protocols are reducing onboarding from months to weeks.
- Digital Platforms:Self-directed interfaces with algorithmic portfolio construction serve technology-entrepreneur preferences for transparent fixed fees over percentage-based arrangements.
- In-Person Consulting:High-touch engagement remains mandatory for trust establishment and complex succession planning.
- Remote Advisory:Video-based relationship management expanded during mobility restrictions and persists for routine portfolio reviews.
Hybrid Services dominate new client acquisition. Digital Platforms show the steepest expansion trajectory among fintech-founder demographics.
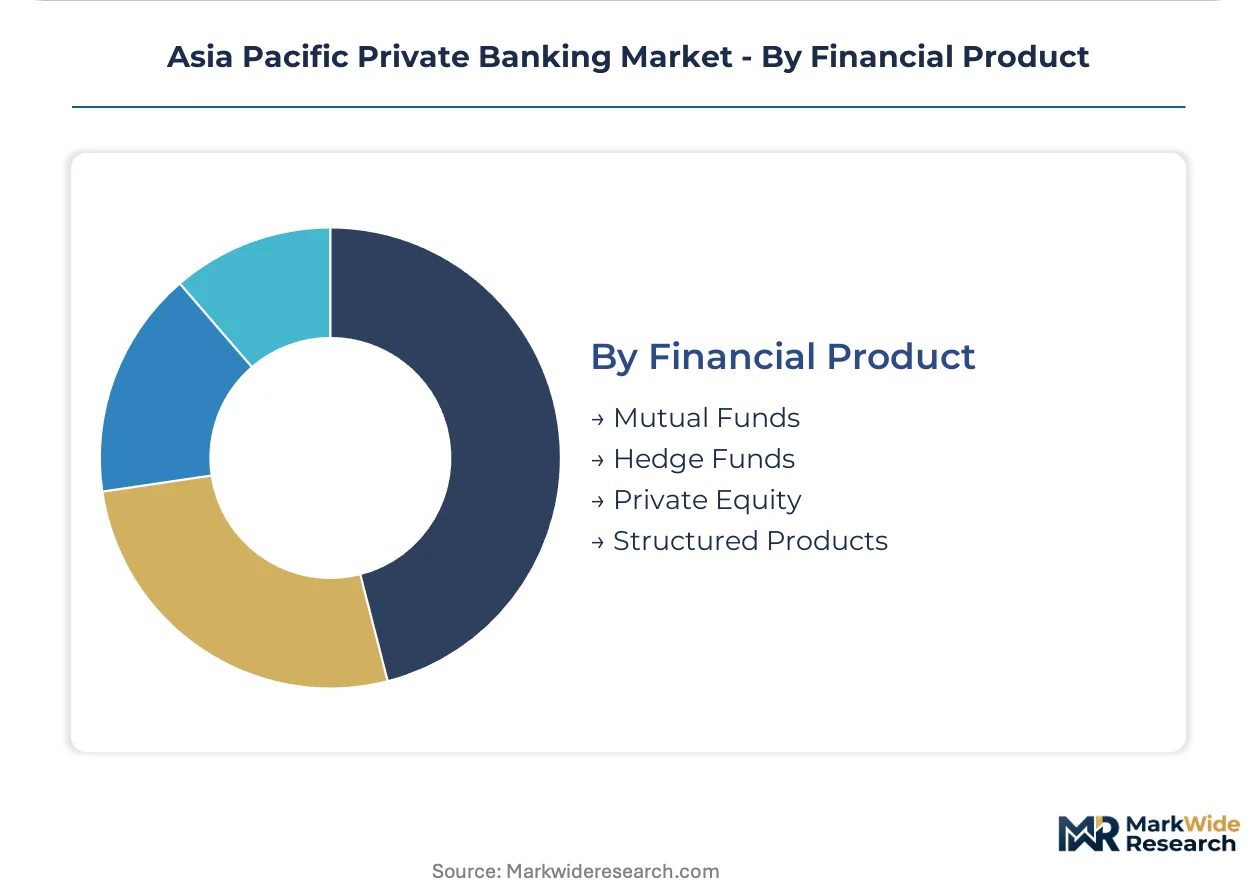
Financial Product:
Alternative investments are displacing traditional fund-of-funds structures as family offices seek direct exposure with reduced fee layers.
- Private Equity:Direct and co-investment structures bypass traditional fund-of-funds fee layers through fractionalized ownership of underlying assets. Singapore's variable capital company legislation is standardizing holding vehicle templates for these allocations.
- Structured Products:Customized derivatives provide tailored risk-return profiles for specific liability matching or currency hedging requirements. Hong Kong's open-ended fund company regime is reducing legal documentation friction for multi-jurisdictional deployment.
- Hedge Funds:Absolute return strategies through regulated fund structures.
- Mutual Funds:Standardized pooled vehicles for core satellite allocations.
Structured Products command current margin premiums. Private Equity is climbing the fastest as direct investment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's family office registrations from mainland China and India outpace Hong Kong's cross-border advisory volumes, yet Hong Kong retains deeper mainland China license access for wealth repatriation channels.
Singapore
The Monetary Authority of Singapore's fit-and-proper licensing criteria and single-family office regulatory enhancements attract mainland Chinese and Indian capital. Singapore trust law frameworks anchor estate structuring demand from Indonesian and Vietnamese families. Raffles Place and Marina Bay financial clusters concentrate relationship manager talent and fiduciary service providers.
Hong Kong
Mainland Chinese fintech founders prefer subscription-based advisory pricing with transparent fixed fees over percentage-based arrangements. The Securities and Futures Commission mandates enhanced due diligence for cross-border client relationships. Central and Admiralty districts host booking centers leveraging the Greater China corridor expertise.
India
Non-resident Indian wealth repatriation drives foreign portfolio investment channel utilization through private banking intermediaries. SEBI and RBI joint oversight creates regulatory layering in product architecture. Mumbai's Bandra-Kurla Complex and Delhi's institutional corridors concentrate private banking operations serving diaspora fortunes.
Indonesia
First-generation manufacturing and commodity wealth transfers accelerate family office formations requiring estate structuring and trust administration. The country's central bank maintains capital flow monitoring for cross-border investment vehicles. Jakarta's Sudirman Central Business District clusters domestic private banking headquarters serving regional ultra high net worth individuals.
Vietnam
Ho Chi Minh City and Hanoi produce first-generation technology and real estate fortunes with minimal incumbent private banking penetration. Regulatory frameworks for foreign financial institution licensing remain under development. District 1 in Ho Chi Minh City and Ba Dinh District in Hanoi concentrate emerging ultra-affluent wealth creation.
Asia Pacific Private Banking Market Vendor Landscape
Singapore-based institutions anchor one tier; Swiss-Asian booking center specialists hold cross-border advisory capabilities. The market structures around three concentration tiers: global universal banks with multi-jurisdictional license networks, regional champions with Singapore-dollar or Greater China corridor expertise, and boutique advisors serving single-market ultra high net worth segments. Strategic moves center on biometric identity verification infrastructure deployment and distributed ledger-based KYC protocol integration.
Among Swiss-anchored universal banks, UBS Global Wealth Management exemplifies the cross-border advisory archetype through its booking center network. Within the Singapore-based regional tier, DBS Private Bank and Bank of Singapore occupy positions differentiated by Singapore-dollar wealth solutions and family office fiduciary mandates respectively. HSBC Private Banking represents the Greater China corridor specialist model.
| Leading Market Players |
|---|
| J.P. Morgan Private Bank |
| BNP Paribas Wealth Management |
| DBS Private Bank |
| PineBridge |
| OCBC |
| UBS Global Wealth Management |
| Bank of Singapore |
| SC Lowy |
| HSBC Private Banking |
| Others |
Supply Flow & Price Mechanics
Subscription-based advisory preferences among mainland Chinese fintech founders are compressing traditional asset-under-management fee structures and forcing private banks to reconfigure their cost bases around fixed-fee service delivery models.
Pricing Analysis
Capacity additions in Singapore's family office ecosystem are reshaping price floors for fiduciary mandates as relationship manager scarcity persists. Three-tier pricing structure across premium, standard, and economy levels separates ultra high net worth complexity-driven fees from high net worth standardized offerings. Cost compression in entry-tier segments is intensifying because biometric onboarding infrastructure reduces acquisition timelines without proportional margin recovery. Technology-entrepreneur clients exhibit highest price sensitivity through their preference for transparent fixed fees, while multi-generational family offices remain least sensitive due to complexity premiums for jurisdictional expertise.
Supply Chain Analysis
Freight costs for physical document verification and notarization across Singapore, Hong Kong, and Switzerland add friction to cross-border trust establishment workflows. Talent supply concentrates in Singapore, Hong Kong, and Switzerland as Mandarin-speaking private bankers with dual jurisdictional expertise command compensation premiums. Raw material dependencies include biometric identity verification systems, distributed ledger infrastructure, and specialized legal documentation software. Single-source vulnerability sits with concentrated relationship manager pools possessing Singapore trust law and Hong Kong succession framework expertise. Distribution runs through hybrid digital-physical channels combining algorithmic portfolio platforms with scheduled in-person reviews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific private banking market represents a late-cycle quality story as first-generation entrepreneurs across Indonesia and Vietnam shift demand toward premium estate structuring and multi-jurisdictional fiduciary mandates.
For Market Incumbents: Cement cross-border advisory capabilities through Swiss-Asian booking center network expansion before regional champions consolidate Greater China corridor access. Invest in biometric identity verification infrastructure to compress client acquisition timelines against digital-native competitors. Prioritize relationship manager development programs addressing Singapore trust law and Hong Kong succession framework expertise scarcity. For New Entrants and Emerging Players: Enter via Vietnam's emerging ultra-affluent segment in Ho Chi Minh City and Hanoi where incumbent penetration remains minimal. Target first-generation technology and real estate fortunes requiring foundational estate structuring rather than complex multi-jurisdictional mandates. Deploy subscription-based advisory pricing to differentiate from percentage-based legacy fee structures. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique advisors possessing concentrated Mandarin-speaking talent pools and Singapore regulatory licenses. Long-term viability hinges on capturing intergenerational wealth transfer events across Indonesia and Vietnam as manufacturing and commodity fortunes mature. Monitor family office registration velocity in Singapore as inflection indicator for fiduciary service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Onboarding Infrastructure Deployment | Compresses client acquisition timelines from months to weeks per Monetary Authority of Singapore protocols. |
| Swiss-Asian Booking Center Network Expansion | Sustains cross-border advisory capabilities for mainland Chinese wealth restructuring through Singapore trust law. |
| Relationship Manager Certification Investment | Addresses scarcity of Mandarin-speaking bankers with Singapore trust and Hong Kong succession expertise. |
| Variable Capital Company Vehicle Standardization | Reduces legal documentation friction for multi-jurisdictional family office setups per Singapore legislation. |
| Islamic Wealth Solutions Framework Development | Captures Indonesian Muslim family office demand through Malaysia's Shariah-compliant trust structure templates. |
Methodological Framework
Bottom-up family office formation modeling reconciled against top-down regulatory filing tracking forms the analytical core of this study. Primary interviews with private bank relationship managers, trust administration officers, family office principals, and Monetary Authority of Singapore regulatory officials combined with secondary validation against Securities and Futures Commission disclosure filings, Monetary Authority of Singapore licensing databases, and private banking industry association reports. Triangulation across these sources ensures coverage of both demand-side wealth structuring preferences and supply-side capacity constraints.
Historical trendline analysis of family office registrations and cross-border advisory volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include client type tiers, service type complexity levels, delivery model digitization stages, and financial product alternative investment exposure. CAGRs were derived through regression analysis of booking center relationship growth against regulatory capacity expansion. Industry-specific forecast inputs incorporate single-family office regulatory enhancement impacts and distributed ledger KYC protocol adoption curves.
The model holds under stable Singapore and Hong Kong regulatory frameworks; deviation in India's SEBI-RBI foreign portfolio investment channel restrictions or Indonesia's capital flow monitoring tightening would shift non-resident Indian and Indonesian wealth repatriation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
India Private Banking Market