
 Digital Wealth Management Market | 2026-2036
Digital Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Wealth Management Market Analysis
Fragmentation across retail investors is restructuring how digital wealth platforms allocate development resources. Addepar specializes in data aggregation for complex portfolios. Wealthfront leverages automated tax-loss harvesting to differentiate its core offering. SS&C Black Diamond anchors institutional-grade reporting for advisory firms.
Digital wealth management encompasses algorithm-driven financial advisory services delivered through software platforms that automate portfolio construction, rebalancing, and tax optimization with minimum account thresholds often below traditional human advisors. These systems process client risk profiles, time horizons, and liquidity needs through rule-based or machine-learning engines to generate personalized asset allocations. Robo-advisory services dominate transaction volume due to low fee structures, while AI-powered analytics command premium positioning among family offices seeking predictive risk modeling. Blockchain-based custody and settlement infrastructure represents an emerging margin pool as institutional clients demand immutable transaction records.
The SEC enforces fiduciary standards through Regulation Best Interest, while the EU AI Act classifies credit-scoring algorithms as high-risk systems requiring human oversight. FINRA audits digital platforms for suitability in automated recommendation engines. Stakeholders must monitor evolving cross-border data localization requirements as jurisdictions tighten controls on client financial information flows.
Market Dynamics
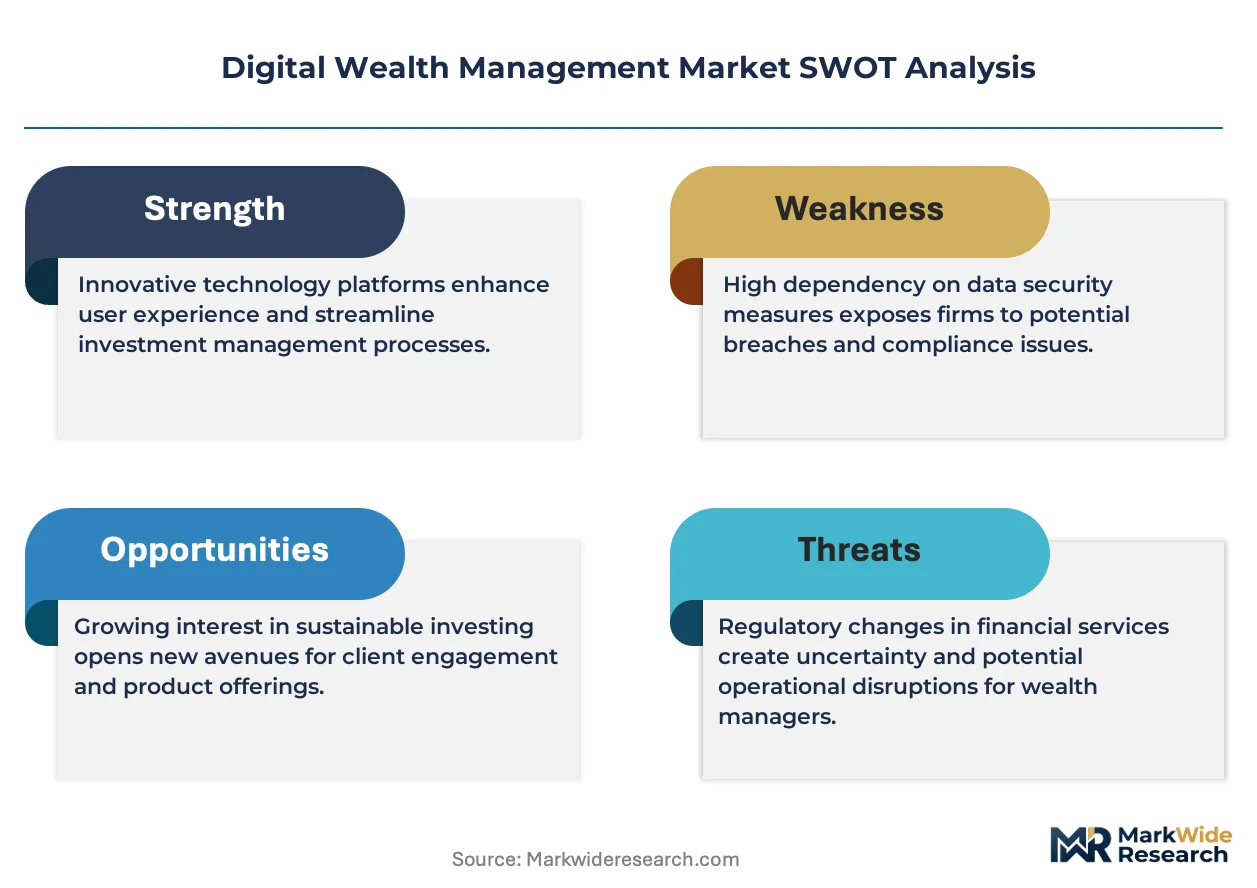
Algorithmic transparency mandates under the EU AI Act and SEC disclosure rules are forcing platforms to re-engineer their recommendation engines, creating a structural divide between compliant infrastructure-heavy providers and stripped-down challengers.
Growth Catalysts
- EU AI Act compliance infrastructure:Mandatory human oversight requirements for credit-scoring algorithms are creating specialized demand for explainable AI tooling among European wealth platforms.
- Mobile-first retail investor onboarding:Smartphone-native account opening with sub-$500 minimums is expanding addressable households among millennials and Gen Z cohorts in the United States.
- Automated tax-loss harvesting:Systematic realization of capital losses across ETF portfolios is compressing after-tax return advantages previously reserved for high-net-worth advisory relationships.
Market Restraints
- Cloud infrastructure concentration:Dependency on AWS, Azure, and Google Cloud for real-time portfolio analytics creates single-point-of-failure exposure during regional outages.
- Fiduciary liability expansion:SEC Regulation Best Interest enforcement is elevating E&O insurance costs for algorithm-driven recommendation platforms.
- Human advisor substitution floor:Complex estate planning and concentrated stock positions still require manual intervention, capping pure-digital penetration.
Strategic Opportunities
- Blockchain custody infrastructure:Immutable settlement records for alternative assets are attracting family office demand for transparent ownership verification.
- India SEBI fintech sandbox:Regulatory permission to test algorithmic advisory models without full licensing is lowering market entry barriers for foreign platform providers.
- Predictive risk modeling convergence:Integration of alternative data streams with traditional portfolio theory is enabling anticipatory rebalancing for institutional clients.
Industry Challenges
- Quantitative risk engineer scarcity:Shortage of professionals capable of translating machine-learning outputs into regulator-defensible suitability documentation is throttling product pipeline velocity.
- Legacy core banking integration:SOAP-based mainframe architectures at incumbent custodians impose latency penalties on real-time rebalancing execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Wealth Management Market |
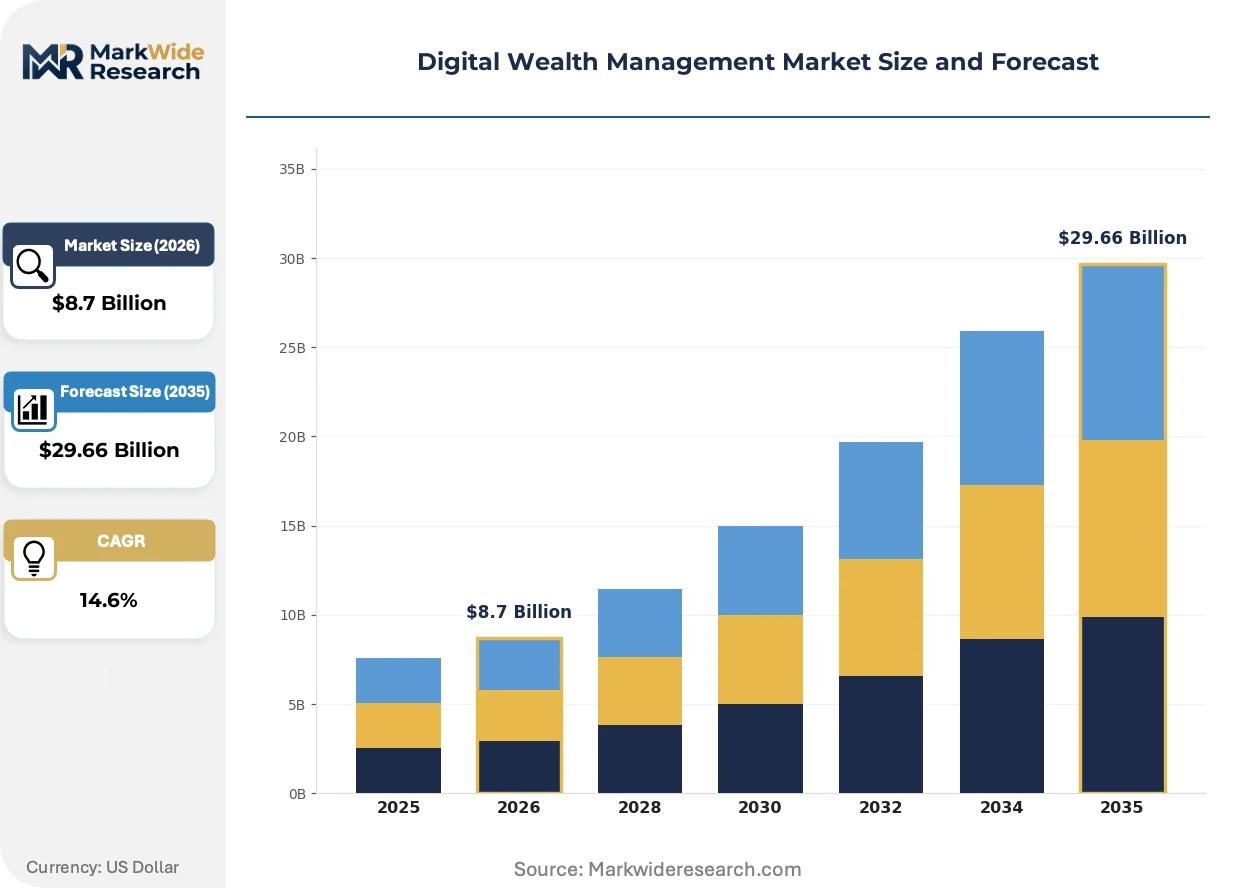
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Robo-Advisory, Financial Planning, Portfolio Management, Risk Assessment Client Type: HNWIs, Institutions, Family Offices, Retail Investors Technology: AI, Mobile Applications, Blockchain, Big Data Delivery Model: Subscription, Fee-Based, Commission-Based, Hybrid |
| Companies Covered | Masttro, Landytech, Addepar, Farther Finance, Acorns, SS&C Black Diamond, Altoo, Vise, Wealthfront, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Wealth Management Market Emerging Trajectories
Platform architecture is pivoting from monolithic robo-advisory stacks toward modular, API-first ecosystems that embed wealth management capabilities into non-financial applications.
Embedded finance infrastructure is unifying banking, investment, and insurance workflows within single mobile interfaces. Retail aggregators and neobanks are white-labeling automated portfolio construction to deepen customer lifetime value. This convergence is compressing standalone robo-advisory margins while expanding total addressable touchpoints.
The EU AI Act's high-risk system classification is mandating algorithmic audit trails and human-in-the-loop overrides for automated investment advice. European wealth platforms are re-architecting their inference pipelines to satisfy documentation requirements. United States SEC staff are signaling analogous disclosure expectations through enforcement actions against opaque recommendation engines.
Subscription-based advisory pricing is displacing traditional AUM-based fee structures among tech-savvy investor segments. Flat monthly rates for unlimited access to financial planning tools and automated portfolio management are gaining traction through employer-sponsored benefits channels. This shift is most visible in the United States, where workplace financial wellness programs are becoming primary distribution vectors for digital wealth services.
Digital Wealth Management Market Segmentation
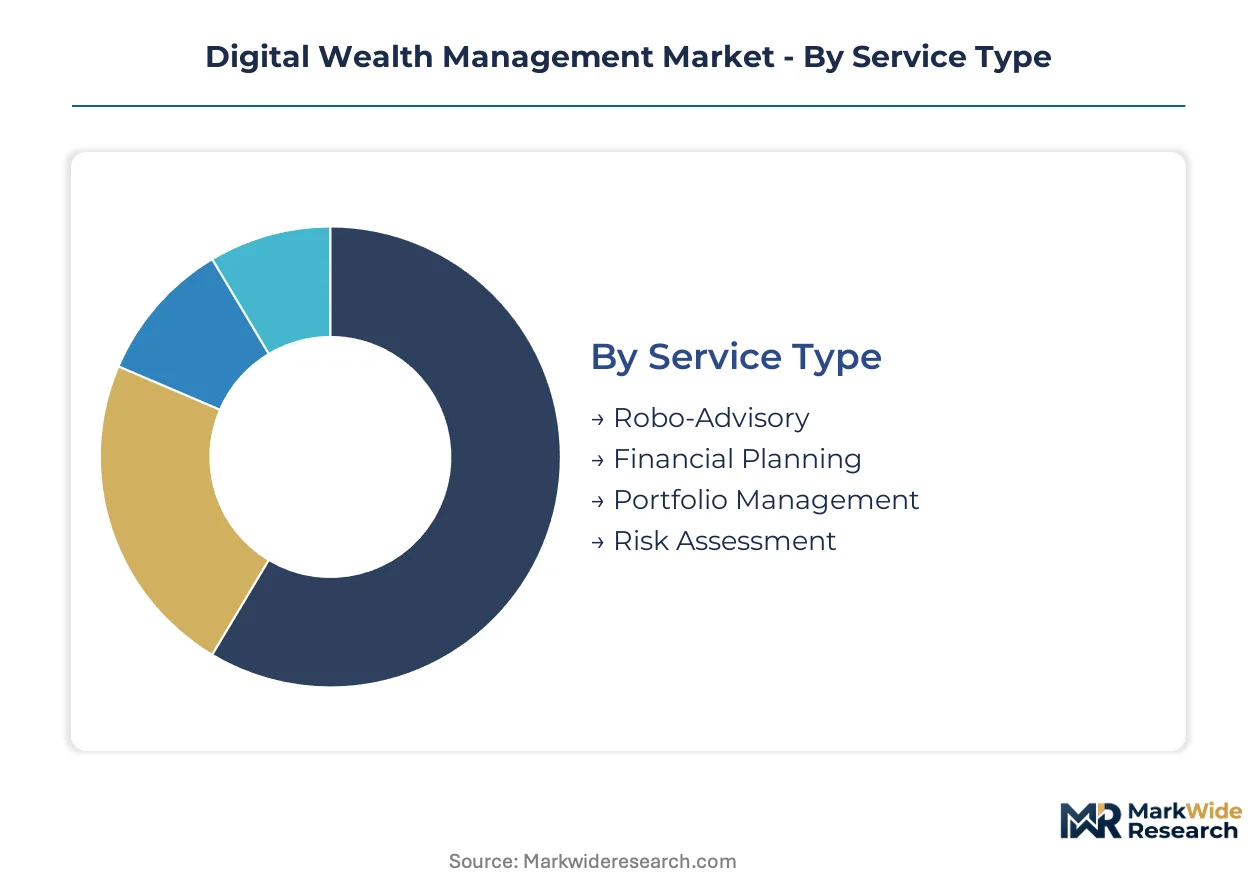
Digital wealth platforms architect their service portfolios around distinct client sophistication levels and technology readiness. Segmentation reveals how pricing models, advisory depth, and infrastructure investments diverge across investor archetypes and delivery mechanisms.
Service Type:
Advisory complexity and automation depth drive platform selection, with investors trading off personalization against cost efficiency.
- Robo-Advisory:Algorithm-driven portfolio construction and rebalancing execute through rule-based engines with minimal human intervention. Demand concentrates among US millennials and Gen Z investors seeking sub-50 basis point fee structures and sub-$500 account minimums.
- Financial Planning:Comprehensive cash flow modeling, retirement trajectory simulation, and goal-based allocation recommendations integrate tax and estate considerations. Family offices in the United States adopt these services to complement concentrated stock position management with automated scenario testing.
- Portfolio Management:Active oversight of asset allocation across ETF, mutual fund, and direct indexing strategies.
- Risk Assessment:Quantitative profiling of volatility tolerance and drawdown capacity through psychometric questionnaires and behavioral data analysis.
Volume sits with Robo-Advisory; growth tilts toward Financial Planning as hybrid advisory models gain traction.
Client Type:
Wealth concentration and relationship complexity determine platform feature prioritization and support infrastructure intensity.
- HNWIs:Investors with liquid assets exceeding standard thresholds require bespoke tax-loss harvesting across multiple account registrations and concentrated position management. US tech executives deploy these platforms to optimize equity compensation liquidation schedules.
- Institutions:Pension funds, endowments, and asset managers demand institutional-grade reporting, custom benchmark construction, and audit-ready documentation trails. European adoption accelerates under EU AI Act compliance requirements for algorithmic transparency.
- Family Offices:Multi-generational wealth structures with alternative asset exposure.
- Retail Investors:Mass-affluent households with straightforward financial situations and preference for mobile-first interfaces.
Institutions command the largest AUM flows; Retail Investors are expanding most quickly through employer-sponsored distribution channels.
Technology:
Infrastructure architecture choices separate premium-positioned platforms from cost-optimized challengers.
- AI:Machine learning inference engines power predictive risk modeling, natural language processing for client communication, and alternative data integration for sentiment-driven rebalancing. SEC disclosure scrutiny and EU AI Act high-risk system classification are forcing explainability investments.
- Mobile Applications:Native smartphone interfaces with biometric authentication, push notification alerts, and fractional share trading dominate US millennial onboarding.
- Blockchain:Distributed ledger infrastructure for custody verification and settlement immutability.
- Big Data:Aggregation and normalization of disparate financial account feeds for unified household balance sheet visualization.
Mobile Applications capture the highest user counts; AI claims the steepest expansion trajectory as regulatory compliance tooling demands surge.
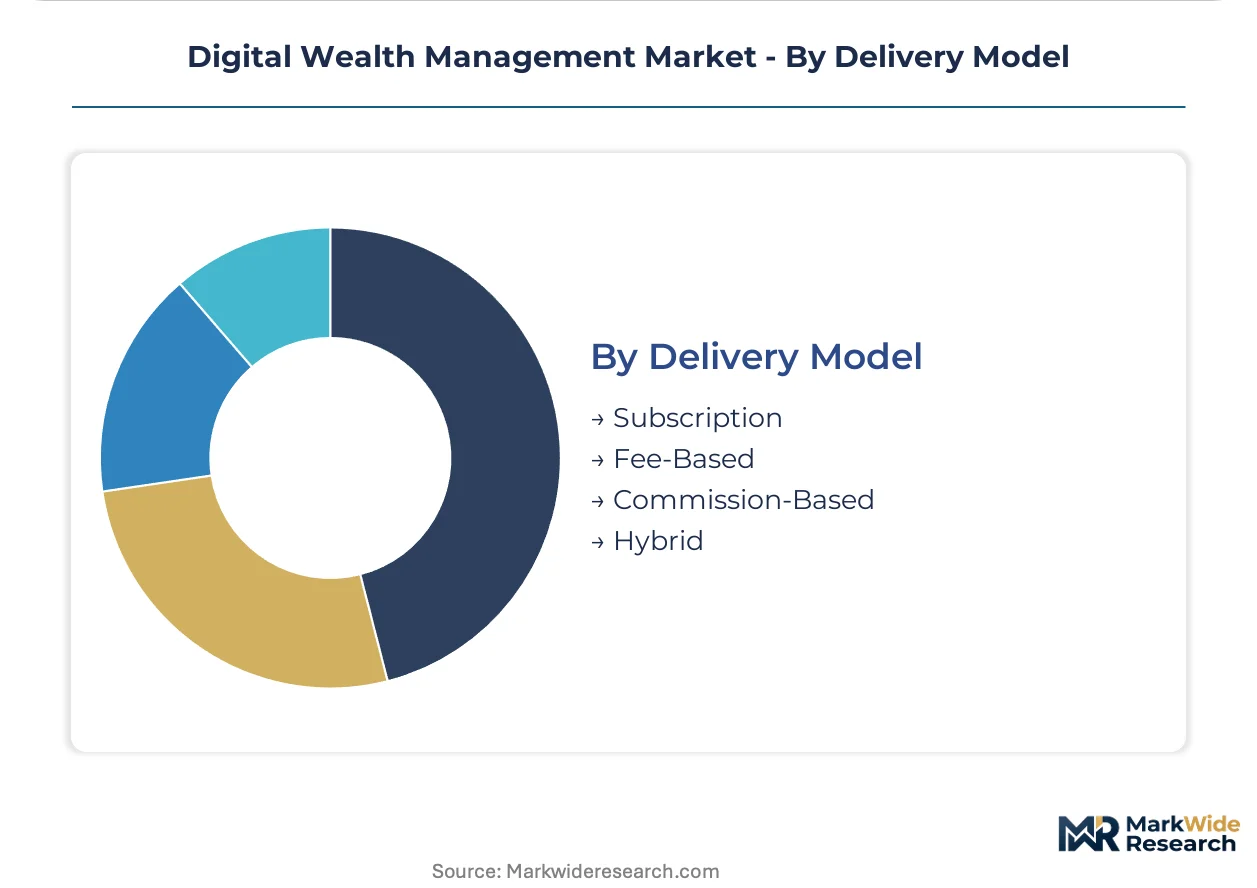
Delivery Model:
Fee structure alignment with client usage patterns and advisor involvement level shapes revenue predictability and customer lifetime value.
- Subscription:Flat monthly or annual rates for unlimited platform access and automated advisory services. US workplace financial wellness programs distribute these models through employer benefits marketplaces.
- Fee-Based:Assets-under-management pricing scaled to account size with tiered service levels.
- Commission-Based:Transaction-generated revenue from product placement and fund distribution agreements.
- Hybrid:Blended structures combining base subscription fees with AUM overlays for complex planning engagements.
Fee-Based structures still dominate AUM; Subscription models are gaining share fastest among tech-native investor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households concentrate demand for mobile-first wealth platforms, with tech-savvy millennials and Gen Z investors driving account openings below $500 minimums. Regulatory divergence across jurisdictions is fragmenting platform architecture investments.
United States
Workplace financial wellness programs and employer-sponsored benefits channels are accelerating subscription-based advisory adoption among millennials. SEC Regulation Best Interest enforcement elevates E&O insurance costs for algorithm-driven platforms. Silicon Valley and New York City clusters host the densest concentration of robo-advisory engineering talent and venture funding flows.
Germany
Retail investor demand for automated portfolio construction is expanding through neobank partnerships and embedded finance integrations. EU AI Act high-risk system classification mandates explainable AI tooling for credit-scoring algorithms used in advisory engines. Frankfurt's financial technology corridor anchors compliance infrastructure development for algorithmic transparency requirements.
United Kingdom
Subscription pricing models are displacing traditional AUM-based fees among tech-native investor segments in London and Southeast England. The Financial Conduct Authority's consumer duty rules impose stricter suitability documentation standards on automated recommendation systems. The City of London remains a hub for institutional-grade reporting platform development serving family offices.
India
SEBI's fintech sandbox permissions are lowering market entry barriers for foreign platform providers testing algorithmic advisory models. Mobile-native account onboarding with sub-$500 minimums is expanding addressable households among urban millennials. Mumbai and Bangalore clusters concentrate engineering talent for predictive risk modeling and alternative data integration.
Singapore
Family office demand for blockchain-based custody infrastructure and immutable settlement records is attracting platform specialization in alternative asset verification. The Monetary Authority of Singapore's digital asset framework provides regulatory clarity for distributed ledger custody solutions. The city-state's wealth management hub status concentrates multi-generational wealth structures seeking transparent ownership verification.
Digital Wealth Management Market Vendor Landscape
United States producers anchor the high-velocity retail tier; European specialists hold the compliance-heavy institutional segment. The vendor base stratifies across three tiers: venture-backed challengers with mobile-first architectures, incumbent custodians with legacy integration capabilities, and modular API providers enabling embedded finance distribution. Strategic archetypes include automated tax-optimization specialists, data aggregation platforms for complex portfolios, and white-label infrastructure providers for neobanks. Dominant competitive moves center on M&A for engineering talent acquisition and strategic partnerships with employer benefits marketplaces.
Within the data aggregation archetype, Addepar occupies a position serving complex portfolio visualization needs. SS&C Black Diamond anchors institutional-grade reporting capabilities for advisory firms. Wealthfront exemplifies the automated tax-loss harvesting specialization that compresses after-tax return advantages for retail investors. These three represent distinct strategic postures: portfolio data unification, enterprise reporting infrastructure, and consumer-facing automation.
| Leading Market Players |
|---|
| Masttro |
| Landytech |
| Addepar |
| Farther Finance |
| Acorns |
| SS&C Black Diamond |
| Altoo |
| Vise |
| Wealthfront |
| Others |
Supply Flow & Price Mechanics
Employer-sponsored benefits channels in the United States are compressing customer acquisition costs and forcing platforms to restructure pricing around subscription economics rather than AUM-based revenue capture.
Pricing Analysis
Volume sits with sub-50 basis point robo-advisory tiers; margin concentrates in AI-powered analytics for family offices. Three-tier pricing structure across premium, standard, and economy levels separates white-label infrastructure providers from direct-to-consumer challengers. Price differentiation rests on explainable AI certification depth and human advisor overlay availability. Pricing pressure stems from embedded finance integrations that commoditize standalone portfolio construction tools. Retail investors exhibit highest price sensitivity; institutions tolerate premium positioning for audit-ready documentation trails.
Supply Chain Analysis
Direct-to-employer channels handle hyperscale buyer demand through benefits marketplace integrations. Cloud infrastructure concentrates in the United States, Ireland, and Singapore for regulatory compliance and latency optimization. Platform architecture draws from AWS compute clusters, specialized GPU instances for ML inference, and blockchain node networks for custody verification. Single-source vulnerability in hyperscaler dependency creates outage exposure during regional service disruptions. Distribution runs through neobank partnerships, advisory firm technology stacks, and workplace financial wellness program aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital wealth management is becoming a vertical-integration race as platforms pursue captive control over data aggregation pipelines to defend margin erosion from modular API competitors.
For Market Incumbents: To counter embedded finance commoditization, Wealthfront-class specialists should deepen upstream integration into tax-loss harvesting algorithm development and secure exclusive employer benefits marketplace distribution through multi-year platform exclusivity agreements. SS&C Black Diamond-tier providers must harden compliance infrastructure for EU AI Act documentation requirements to defend institutional pricing power against challenger erosion. For New Entrants and Emerging Players: Neobank partnership channels offer the most penetrable entry vector for venture-backed challengers seeking rapid scale without proprietary customer acquisition infrastructure. India's SEBI fintech sandbox presents regulatory permission to test algorithmic advisory models before full licensing commitment. White-label infrastructure provision to regional banks in Germany and Southeast Asia enables asset-light market presence with faster path to revenue. For Investors and Strategic Acquirers: The window for entry favors explainable AI tooling specialists with regulator-defensible suitability documentation capabilities. Long-term viability centers on platforms achieving employer-sponsored distribution lock-in through workplace financial wellness program integration. Monitor SEC enforcement patterns against opaque recommendation engines as inflection indicator for compliance infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Infrastructure Investment | EU AI Act high-risk system classification mandates human-in-the-loop documentation for European wealth platforms. |
| Employer Benefits Marketplace Partnership | Workplace financial wellness programs in the United States are becoming primary distribution vectors for subscription-based advisory. |
| Blockchain Custody Capability Buildout | Family offices in Singapore demand immutable settlement records for alternative asset ownership verification. |
| Neobank White-Label Integration | Embedded finance convergence compresses standalone robo-advisory margins while expanding total addressable touchpoints. |
| India SEBI Sandbox Market Entry | Regulatory permission to test algorithmic advisory models lowers entry barriers for foreign platform providers. |
Methodological Framework
Independent corroboration across robo-advisory platform executives, SEC compliance officers, EU regulatory affairs leads, and neobank partnership directors underwrites the qualitative findings. Secondary validation draws from SEC enforcement action records, EU AI Act implementation guidance, SEBI sandbox participant disclosures, and hyperscaler infrastructure capex reports. Bottom-up triangulation across platform engineering resource allocation and top-down validation against employer benefits marketplace penetration data anchor the segmentation outputs.
Comparable-period anchoring to historical AUM flows and account opening velocity patterns structures the projection framework. The analysis models service type, client sophistication tier, technology architecture, and delivery mechanism dimensions across the analysis window. CAGRs derive from employer-sponsored channel adoption curves, regulatory compliance cost trajectories, and cloud infrastructure scaling economics. Forecast inputs include mobile-native onboarding friction coefficients and explainable AI tooling penetration rates.
Caveats apply where SEC fiduciary enforcement intensification or EU AI Act audit requirement expansion could materially shift the outlook. Forecasts reflect assumptions around employer benefits marketplace channel maturation and neobank embedded finance adoption velocity. Practitioners should monitor hyperscaler regional outage frequency and quantitative risk engineer labor market tightness for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market