
 Private Banking Market | 2026-2036
Private Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Private Banking Market Analysis
Embedded artificial intelligence in portfolio construction is rewriting how private banks deliver customized investment mandates at scale. UBS Global Wealth Management leverages predictive analytics to anticipate liquidity events across multi-generational client books. Goldman Sachs Private Wealth Management anchors its competitive position through proprietary risk-scoring engines that integrate alternative asset data feeds.
Private banking denotes bespoke financial and advisory services delivered to individuals with substantial investable assets, typically involving minimum thresholds, segregated account structures, and personalized asset allocation across liquid and illiquid instruments. The practice centers on capital preservation, intergenerational transfer efficiency, and concentrated position management for clients with complex balance sheets. Ultra high net worth individuals command the deepest margin pools across client type segments, while impact investing represents the fastest-expanding investment strategy as capital owners align portfolios with climate and social metrics. Wealth management services dominate service type revenue due to recurring fee structures, though tax optimization offerings are gaining structural importance amid cross-border regulatory tightening.
The SEC enforces fiduciary standards that reshape compensation structures and product suitability requirements across US-domiciled advisory relationships. The EU's MiFID II disclosure regime and the OECD's common reporting standard collectively raise compliance costs while favoring institutions with integrated reporting infrastructure. Stakeholders must monitor how jurisdictional regulatory divergence affects booking center economics and client domicile preferences.
Market Dynamics
Digital onboarding infrastructure is compressing client acquisition timelines while simultaneously elevating compliance scrutiny across booking centers. The tension between automation speed and fiduciary accountability is restructuring how private banks deploy capital toward technology versus relationship management.
Growth Catalysts
- EU MiFID II Disclosure Regime:Mandatory fee transparency requirements are accelerating advisory model consolidation as smaller institutions exit due to reporting infrastructure costs.
- Singapore Family Office Ecosystem:Regulatory incentives for single-family office structures are concentrating ultra high net worth capital flows into Asia-Pacific booking centers.
- Embedded Predictive Analytics:Artificial intelligence engines for liquidity event anticipation are deepening share-of-wallet capture across multi-generational client relationships.
Market Restraints
- Compliance Cost Escalation:OECD Common Reporting Standard implementation is requiring integrated cross-border reporting systems that favor scale players over boutique advisors.
- Fiduciary Rule Evolution:SEC enforcement of suitability standards is compressing commission-based product distribution margins across US advisory relationships.
- Alternative Data Integration:Technical limitations in standardizing illiquid asset data feeds are constraining risk-scoring engine accuracy for concentrated positions.
Strategic Opportunities
- Impact Investing Mandates:Climate and social metric alignment is creating new advisory fee pools as capital owners demand portfolio-level ESG integration.
- Tax Optimization Services:Cross-border regulatory tightening is elevating demand for specialized transfer efficiency and domicile structuring expertise.
- Convergence of Blockchain and KYC:Distributed ledger verification combined with digital identity frameworks is enabling automated beneficial ownership documentation.
Industry Challenges
- Quantitative Talent Scarcity:Shortage of professionals combining portfolio construction expertise with data science capabilities is constraining predictive analytics deployment.
- Legacy System Integration:Core banking platform modernization requirements are absorbing technology budgets that would otherwise flow to client-facing innovation.
- Intergenerational Transition Complexity:Next-generation client preference for digital interfaces is misaligned with incumbent advisor relationship models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Banking Market |
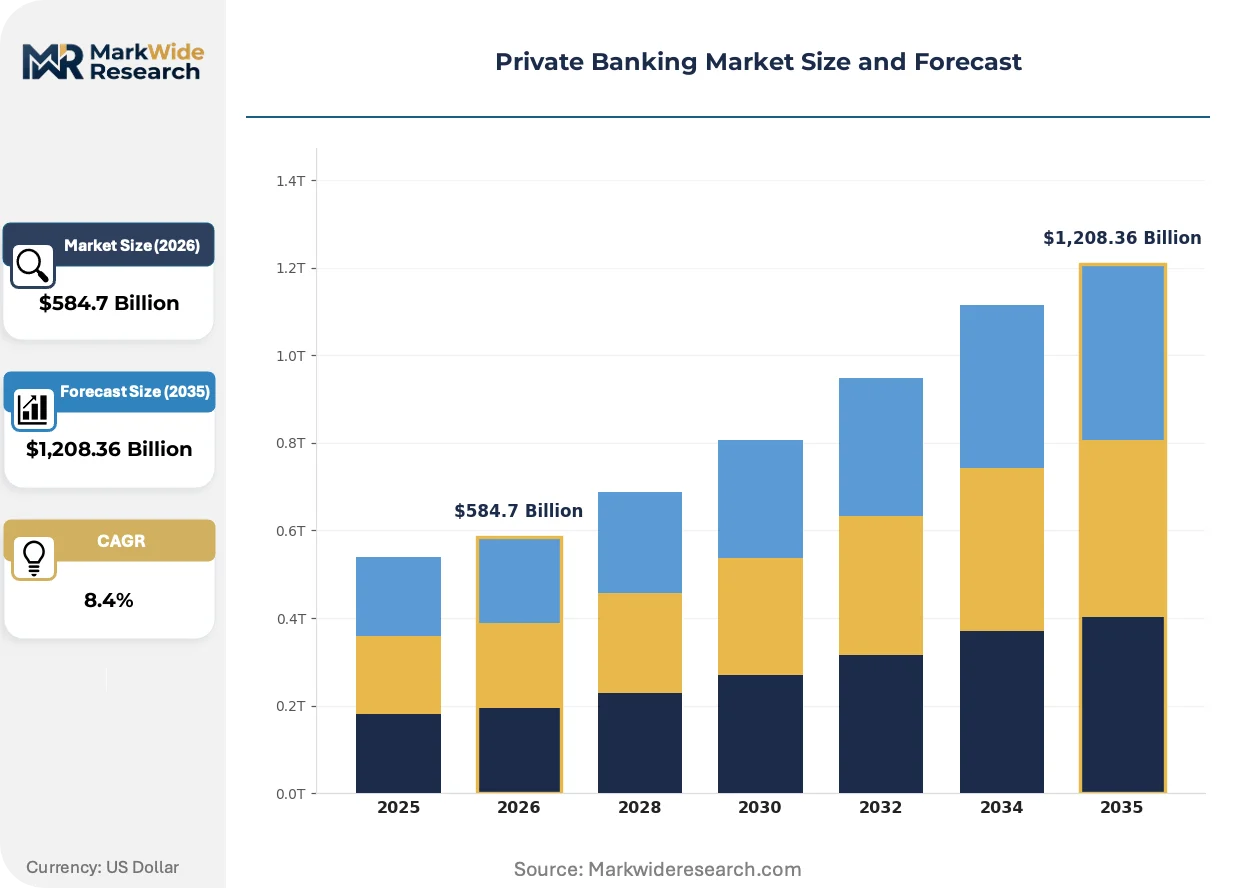
| Market Size in 2026 | $584.7 Billion |
| Market Size in 2035 | $1,208.36 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: High Net Worth Individuals, Ultra High Net Worth Individuals, Family Offices, Corporations Service Type: Wealth Management, Investment Advisory, Estate Planning, Tax Optimization Distribution Channel: Direct Sales, Online Platforms, Financial Advisors, Private Client Relationship Managers Investment Strategy: Growth Investing, Income Investing, Impact Investing, Alternative Investments |
| Companies Covered | J.P. Morgan Private Bank, UBS Global Wealth Management, Goldman Sachs Private Wealth Management, Morgan Stanley Private Wealth Management, Citi Private Bank, HSBC Private Banking, Julius Baer, RBC Wealth Management, Bank of America Private Bank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Banking Market Emerging Trajectories
Artificial intelligence is virtualizing the traditional relationship-manager role while regulatory fragmentation across jurisdictions is forcing modular compliance architectures. These forces are simultaneously compressing margins and opening new service categories.
Portfolio construction software incorporating natural language processing for earnings call sentiment analysis is virtualizing the research function that previously required dedicated analyst teams. Ultra high net worth clients are adopting these tools through white-labeled platforms at accelerating velocity. The technology is virtualizing the information asymmetry that once justified premium advisory fees.
The SEC's evolving fiduciary standard is mandating documented suitability rationales for every product recommendation across US-domiciled relationships. This regulatory pressure is forcing advisory models toward fee-only structures and away from commission-based product distribution. US private banks are responding by consolidating product shelves and investing in compliance workflow automation.
Family offices are unbundling traditional bundled advisory services, purchasing tax optimization, direct investment sourcing, and philanthropic structuring as separate line items. This procurement fragmentation is disrupting the full-service model that anchored private banking economics for decades. Singapore and Switzerland are witnessing the most pronounced unbundling as multi-family offices proliferate.
Private Banking Market Segmentation
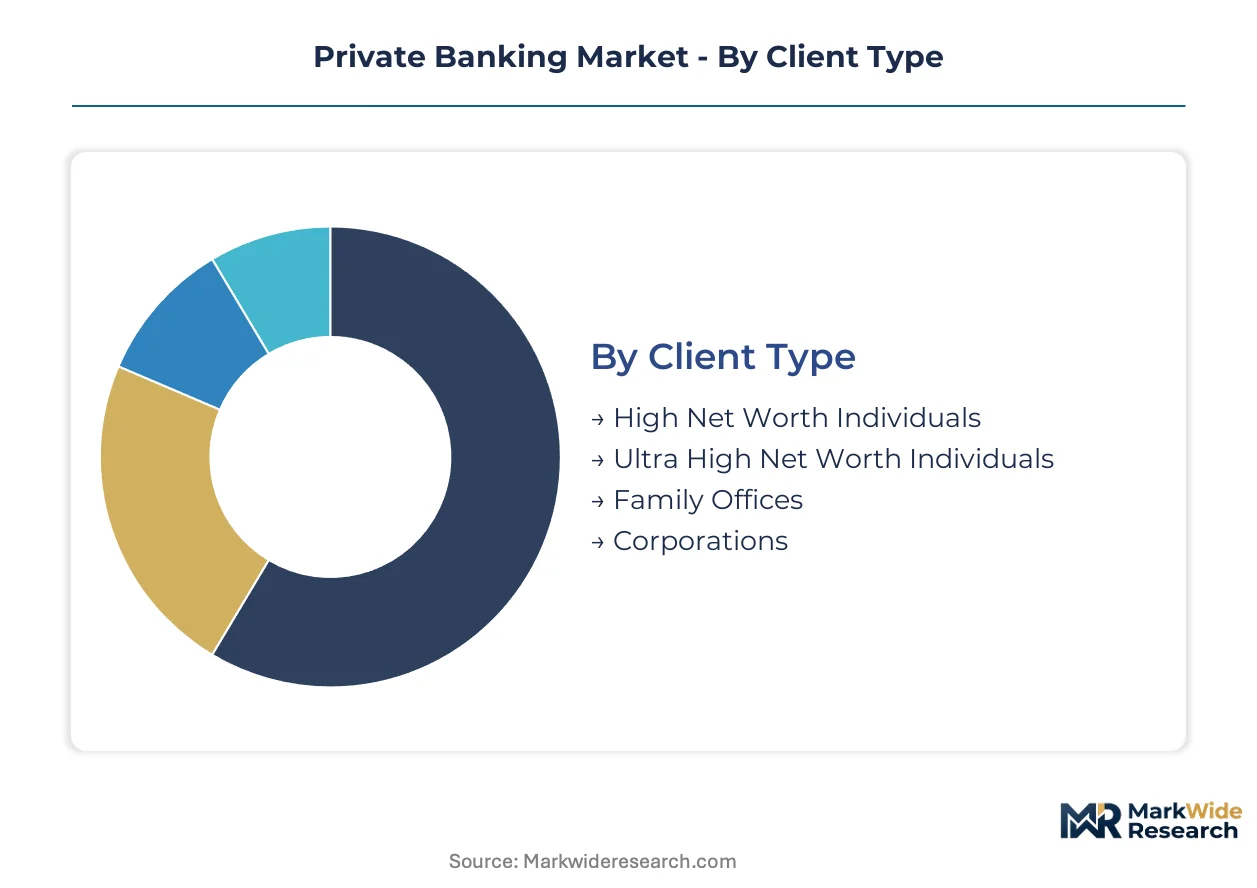
Segmentation in private banking reveals how margin pools concentrate across client sophistication tiers and service complexity levels. The report examines four structural dimensions that determine pricing power, regulatory exposure, and technology investment priorities.
Client Type:
Mature wealth segments anchor recurring revenue while emerging client categories reshape acquisition economics and service bundling.
- Ultra High Net Worth Individuals:Clients with investable assets exceeding thirty million dollars command bespoke portfolio construction and concentrated position management. Singapore and Switzerland booking centers capture the deepest share-of-wallet from this segment as multi-generational relationships justify dedicated family office infrastructure.
- Family Offices:Single-family and multi-family structures unbundle traditional private banking into discrete procurement categories including direct investment sourcing and philanthropic structuring. This segment is expanding most quickly in Singapore's regulatory incentive environment as capital owners seek operational control over advisory relationships.
- High Net Worth Individuals:Clients with one to thirty million dollars in investable assets represent the volume foundation across developed markets.
- Corporations:Treasury management and executive compensation structuring for privately held enterprises generate ancillary private banking revenue streams.
Ultra High Net Worth Individuals retain volume leadership; Family Offices hold the steepest expansion curve.
Service Type:
Cost tier differentiation separates commoditized offerings from premium advisory categories that sustain fee compression resistance.
- Wealth Management:Comprehensive portfolio oversight with recurring fee structures dominates revenue composition across established private banks. The SEC's fiduciary rule evolution is forcing documented suitability rationales that favor institutions with integrated compliance workflow automation.
- Tax Optimization:Cross-border transfer efficiency and domicile structuring expertise is gaining structural importance amid OECD Common Reporting Standard implementation. Demand concentrates in Switzerland and Singapore as regulatory tightening elevates specialized advisory premiums.
- Investment Advisory:Product recommendation and asset allocation guidance faces margin pressure from digital portfolio construction tools.
- Estate Planning:Intergenerational wealth transfer and trust structuring services anchor multi-decade client retention.
Wealth Management retains volume leadership; Tax Optimization holds the steepest expansion curve.
Distribution Channel:
Customer type preferences are fragmenting access models as digital-native clients diverge from relationship-driven acquisition pathways.
- Private Client Relationship Managers:Dedicated advisors managing concentrated books of business sustain premium pricing through information asymmetry and trust-based retention. Legacy institutions including UBS and Goldman Sachs deploy predictive analytics to deepen share-of-wallet across these relationships.
- Online Platforms:Digital onboarding infrastructure compresses client acquisition timelines while elevating compliance scrutiny across booking centers. Robo-advisory hybrids are climbing the fastest among next-generation clients who prioritize interface efficiency over traditional relationship models.
- Financial Advisors:Independent intermediaries introduce private banking products to mass-affluent segments outside core wealth thresholds.
- Direct Sales:Institutional outreach to family offices and corporate treasuries bypasses intermediary economics.
Private Client Relationship Managers retain volume leadership; Online Platforms hold the steepest expansion curve.
Investment Strategy:
Application-driven mandates are displacing traditional risk-profile segmentation as capital owners align portfolios with non-financial objectives.
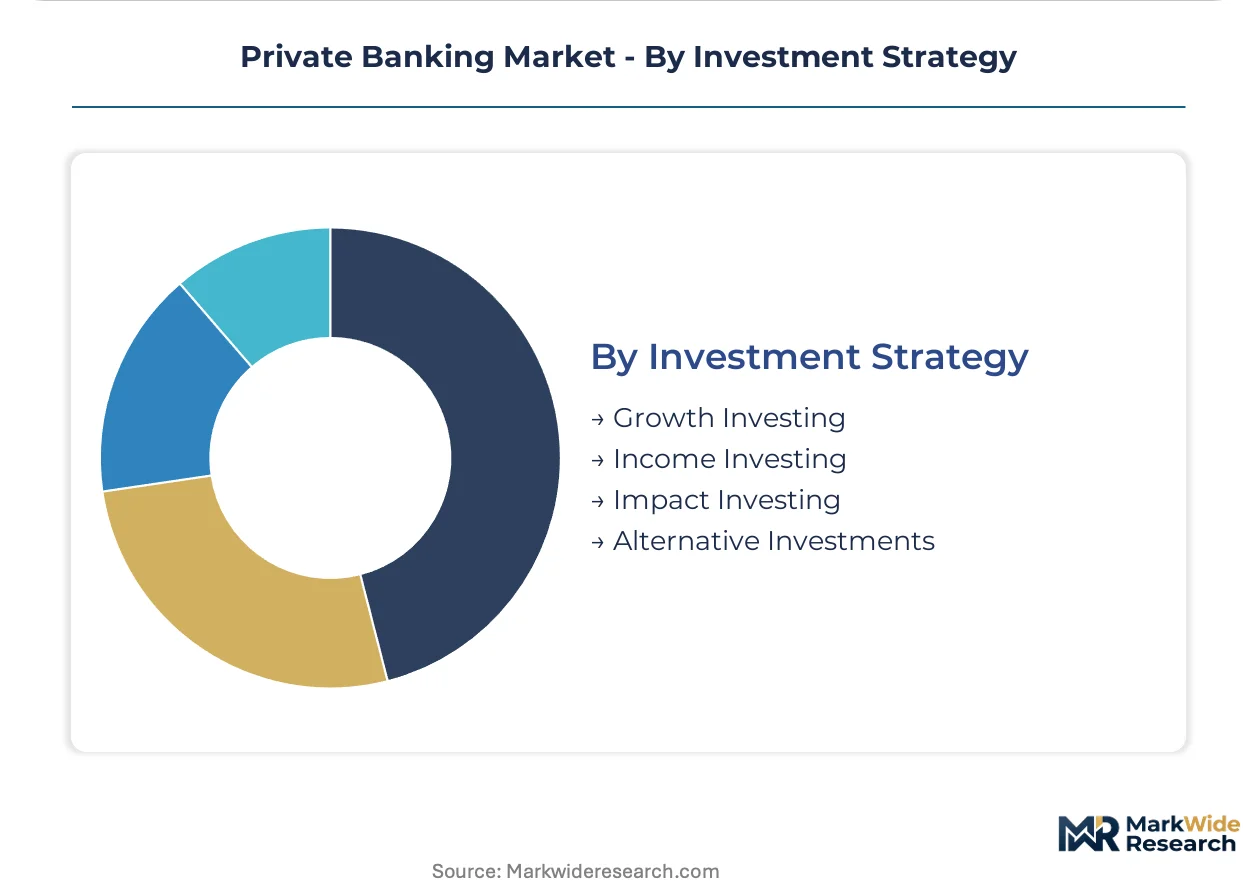
- Impact Investing:Climate and social metric integration creates new advisory fee pools as capital owners demand portfolio-level ESG alignment. Singapore's family office ecosystem is channeling significant capital flows into this category through regulatory incentives for sustainable finance.
- Alternative Investments:Private equity, hedge fund, and real asset exposure requires specialized risk-scoring engines that integrate illiquid data feeds. Technical limitations in standardizing concentrated position analysis constrain deployment scale across smaller institutions.
- Growth Investing:Capital appreciation mandates dominate equity-oriented portfolio construction for younger wealth holders.
- Income Investing:Yield-focused strategies anchor retirement-phase portfolio allocations across mature wealth segments.
Growth Investing retains volume leadership; Impact Investing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra high net worth individuals concentrate booking center activity in jurisdictions offering regulatory certainty and multi-generational wealth infrastructure. Singapore and Switzerland anchor the deepest margin pools as family office formations accelerate.
United States
Technology entrepreneurs and private equity principals drive demand for concentrated position management and liquidity event planning. The SEC enforces evolving fiduciary standards that compress commission-based distribution margins. New York and Greenwich family office clusters witness accelerating unbundling of traditional bundled advisory services into discrete procurement categories.
Switzerland
Cross-border wealth transfer and domicile structuring expertise sustains premium advisory fees amid OECD Common Reporting Standard implementation. Swissmedic and FINMA oversight maintains regulatory credibility for international capital flows. Zurich and Geneva booking centers deepen share-of-wallet through multi-generational relationship infrastructure.
Singapore
Regulatory incentives for single-family office structures channel ultra high net worth capital flows into Asia-Pacific booking centers. The Monetary Authority of Singapore administers tax incentive frameworks for fund management activities. The city-state's family office ecosystem now anchors regional sustainable finance mandates including impact investing deployment.
United Kingdom
Intergenerational wealth transfer and philanthropic structuring services anchor multi-decade client retention across established private banks. The Financial Conduct Authority oversees disclosure requirements under MiFID II alignment protocols. London's Mayfair and City clusters concentrate relationship manager talent and alternative asset data integration capabilities.
Germany
Mittelstand business owners generate demand for estate planning and executive compensation structuring alongside traditional portfolio oversight. BaFin supervision enforces suitability documentation standards across advisory relationships. Frankfurt and Munich private banking centers leverage predictive analytics to anticipate liquidity events across multi-generational client books.
Private Banking Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale determines compliance infrastructure viability. Consolidation favors institutions with integrated reporting systems capable of satisfying OECD Common Reporting Standard and MiFID II disclosure requirements. Two archetypes dominate: full-service private banks with dedicated relationship manager networks, and modular specialists unbundling tax optimization and direct investment sourcing. Competitive moves concentrate on technology licensing for predictive analytics deployment and strategic partnerships for alternative data feed integration.
Within the full-service archetype, UBS Global Wealth Management and Goldman Sachs Private Wealth Management exemplify institutions leveraging proprietary risk-scoring engines and predictive analytics to deepen share-of-wallet. J.P. Morgan Private Bank occupies a position representing the scale-driven end where integrated compliance workflow automation supports documented suitability rationales. Julius Baer sits within the specialist tier emphasizing cross-border wealth transfer expertise.
| Leading Market Players |
|---|
| J.P. Morgan Private Bank |
| UBS Global Wealth Management |
| Goldman Sachs Private Wealth Management |
| Morgan Stanley Private Wealth Management |
| Citi Private Bank |
| HSBC Private Banking |
| Julius Baer |
| RBC Wealth Management |
| Bank of America Private Bank |
| Others |
Supply Flow & Price Mechanics
Overcapacity in digital onboarding infrastructure across Singapore and Switzerland booking centers is compressing implementation timelines while simultaneously elevating compliance scrutiny, forcing suppliers to absorb certification costs that would otherwise flow through to advisory fee structures.
Pricing Analysis
Cost-plus contracts with LIBOR/SOFR indexation dominate multi-year advisory mandates between ultra high net worth clients and full-service private banks. Three-tier pricing structure across premium, standard, and economy levels separates bespoke family office infrastructure from modular tax optimization services and digital-only portfolio tools. Pricing pressure stems from MiFID II disclosure requirements that commoditize traditional fee opacity. Family offices exhibit lowest price sensitivity due to operational control demands, while high net worth individuals migrating from mass-affluent segments drive standard-tier negotiation intensity.
Supply Chain Analysis
Contract-manufacturing concentration in portfolio construction software rests with fintech vendors specializing in natural language processing engines and predictive analytics modules. Technology development clusters in the United States, Switzerland, and Singapore anchor supply for risk-scoring infrastructure and compliance workflow automation. Raw material dependencies include alternative data feeds for illiquid assets, cloud computing capacity for client-facing platforms, and quantitative talent pipelines for model development. Single-source vulnerability concentrates in proprietary risk-scoring engines held by tier-one institutions. Distribution runs through white-label licensing agreements that extend technology capabilities to regional specialists lacking in-house development capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private banking operates as a defensive-moat business where regulatory entrenchment creates durable barriers against new entrant displacement, as multi-jurisdictional licensing requirements and multi-generational relationship infrastructure compound switching costs for ultra high net worth capital owners.
For Market Incumbents: Pre-empt unbundling pressure by acquiring specialized tax optimization boutiques in Switzerland and Singapore before multi-family offices consolidate procurement categories. Integrate compliance workflow automation to absorb MiFID II documentation burdens that would otherwise erode relationship manager productivity. Vertical integration into alternative data feeds for private equity and real asset exposure deepens risk-scoring differentiation against modular specialists.
For New Entrants and Emerging Players: Southeast Asian ultra high net worth penetration outside Singapore's established ecosystem offers white-space expansion as regulatory incentives channel family office formations into secondary booking centers. Target digital-native next-generation clients through robo-advisory hybrids that prioritize interface efficiency over traditional relationship models. Partner with established custodians to bypass licensing timelines that would otherwise delay market entry.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialists with embedded regulatory infrastructure and multi-generational client books. Long-term viability favors acquisition targets combining predictive analytics capabilities with concentrated position management expertise. Monitor SEC fiduciary rule enforcement intensity as an inflection indicator for advisory model consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Licensing | Extends liquidity anticipation capabilities to regional specialists lacking proprietary development resources. |
| Regulatory Infrastructure Acquisition | Absorbs MiFID II compliance burdens that would otherwise force smaller institutions into exit. |
| Alternative Data Feed Integration | Deepens risk-scoring accuracy for concentrated private equity and real asset positions. |
| Digital Onboarding Platform Expansion | Compresses client acquisition timelines while elevating compliance scrutiny across booking centers. |
| Family Office Infrastructure Buildout | Captures unbundling demand for operational control over advisory relationships in Singapore. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with private bank relationship managers, family office chief investment officers, regulatory compliance leads at booking centers, and fintech platform engineers. Secondary validation drew from SEC enforcement releases, Monetary Authority of Singapore regulatory circulars, Swissmedic oversight reports, and OECD Common Reporting Standard implementation guidance. Bottom-up triangulation across client acquisition metrics and top-down reconciliation against aggregate assets under management produced convergent estimates.
Calibration against historical advisory fee compression patterns and technology adoption curves anchored projections across the analysis window. Segmentation dimensions modeled include client sophistication tier, service complexity level, distribution channel architecture, and investment mandate type. CAGRs were derived from trend extrapolation moderated by regulatory inflection assessment. Forecast inputs incorporated booking center capacity utilization rates and predictive analytics deployment velocity across multi-generational client books.
Practitioners should monitor SEC fiduciary rule enforcement intensity, Singapore family office incentive modifications, and OECD reporting standard expansion for early signals of advisory model restructuring. Forecasts reflect assumptions regarding regulatory trajectory and technology substitution rates. Quarterly review of compliance cost escalation indicators and next-generation client preference shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market