
 United States Private Banking Market | 2026-2036
United States Private Banking Market Size, Share, and Industry Trends Forecast 2026-2036
United States Private Banking Market Outlook
The SEC's Regulation Best Interest is decoupling commission-based brokerage from fee-only advisory models across the wealth management sector. JPMorgan Chase & Co. leverages its universal banking footprint to anchor custody and lending relationships within single-family offices. Morgan Stanley Private Wealth Management differentiates through its technology-integrated wealth platform that spans alternative asset access and concentrated stock management. Goldman Sachs Private Wealth Management specializes in serving founders and entrepreneurs with liquidity event structuring and pre-IPO equity planning.
United States Private Banking denotes specialized financial services delivered to affluent individuals and entities with investable assets typically exceeding one million dollars, encompassing discretionary portfolio management, trust administration, tax-efficient structuring, and intergenerational wealth transfer coordination. The client type dimension shows Ultra High Net Worth Individuals commanding the deepest advisory relationships, while family offices represent the fastest-growing engagement model as principals seek consolidated oversight across legal, investment, and philanthropic domains. Within service type, investment management retains the largest revenue pool, though wealth advisory and estate planning are capturing expanding share as demographic transition accelerates.
The SEC enforces fiduciary standards through Regulation Best Interest and ongoing advisor examination protocols, while the IRS shapes demand through estate tax thresholds and trust income treatment rules that directly influence structuring decisions. State-level trust legislation, notably Delaware's directed trust statutes and South Dakota's privacy frameworks, creates jurisdictional competition that influences custody location and governance design. Stakeholders must monitor evolving IRS guidance on grantor trust taxation and anticipated SEC rules around predictive data analytics in investor interactions.
Market Dynamics
The SEC's Regulation Best Interest is compressing commission-based revenue models while fee-only advisory structures capture relationship primacy across multi-generational wealth transfers.
Growth Catalysts
- Intergenerational Wealth Transfer:Demographic transition is accelerating demand for coordinated estate planning and trust administration services among principals aged 55-75 preparing succession frameworks.
- Regulation Best Interest:The SEC's enhanced fiduciary disclosure requirements are decoupling brokerage from advisory models, creating structural preference for fee-based relationship pricing.
- Delaware Directed Trust Statutes:State-level jurisdictional competition for trust situs is expanding governance flexibility and attracting family office relocations from restrictive jurisdictions.
Market Restraints
- Talent Acquisition Costs:Certified trust and estate specialists command compensation premiums exceeding 40% above generalist advisors, compressing margin structures at mid-tier institutions.
- Concentrated Geographic Demand:California and New York metropolitan corridors anchor over half of relationship value, leaving regional institutions with sub-scale coverage economics.
- IRS Grantor Trust Uncertainty:Pending guidance on intentionally defective grantor trust taxation is freezing complex structuring decisions among ultra-high-net-worth households.
Strategic Opportunities
- Texas and Florida Migration:Wealth relocation from high-tax coastal states is creating advisory infrastructure gaps that regional banks and independent RIAs can capture.
- Alternative Asset Platforms:Direct private equity and infrastructure access is absorbing demand previously routed through fund-of-funds, enabling custody-to-commitment vertical integration.
- South Dakota Privacy Frameworks:The state's dynasty trust legislation and sealed court records are attracting multi-generational family office establishment from international jurisdictions.
Industry Challenges
- Cybersecurity Compliance Intensity:SEC examination protocols on client data protection are requiring material infrastructure investment at institutions below $10 billion in assets under management.
- Legacy System Integration:Core banking platforms from the 1990s lack API connectivity with modern portfolio analytics, forcing expensive middleware development for unified reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Private Banking Market |
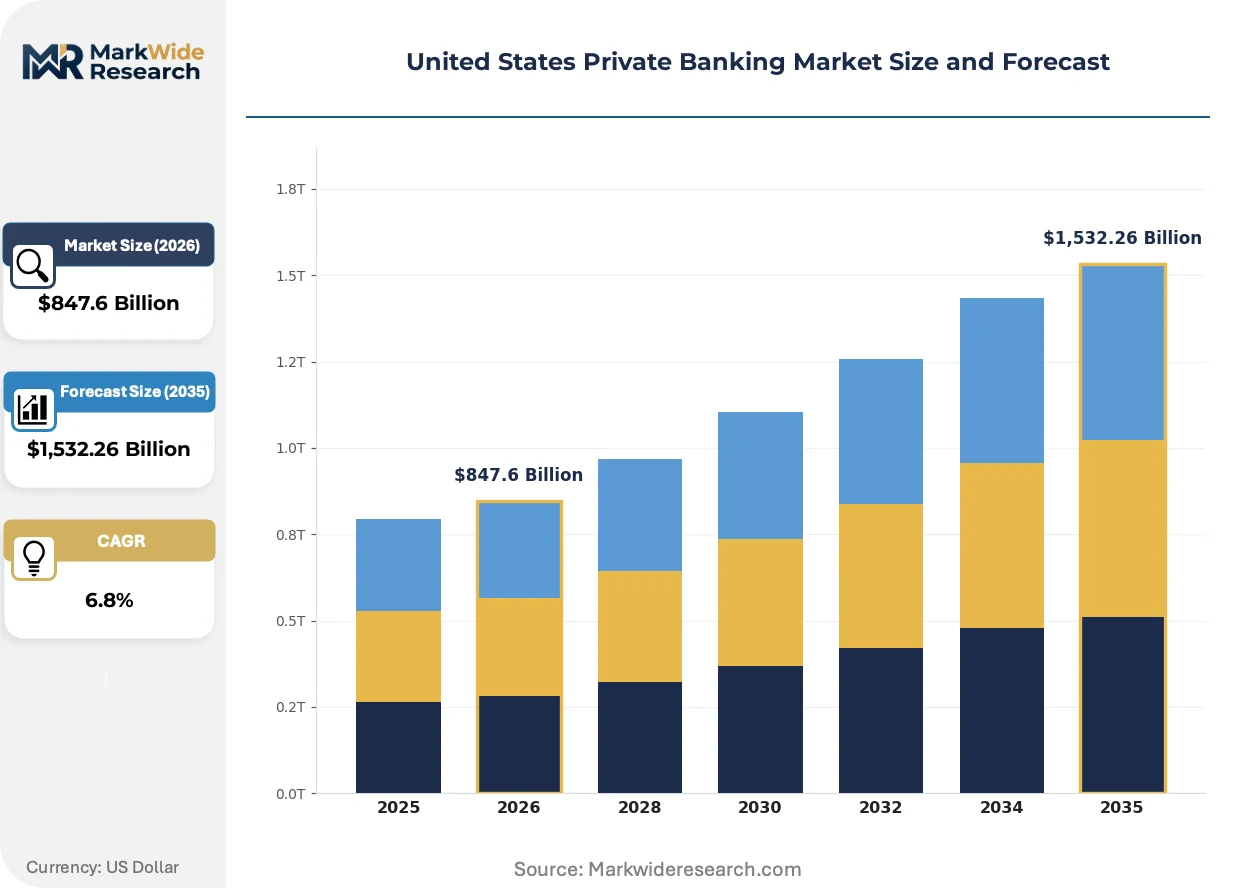
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,532.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: High Net Worth Individuals, Ultra High Net Worth Individuals, Family Offices, Institutional Investors Service Type: Investment Management, Wealth Advisory, Tax Planning, Estate Planning Account Type: Trust Accounts, Custodial Accounts, Managed Accounts, Brokerage Accounts Investment Strategy: Equity Investments, Fixed Income, Alternative Investments, Real Estate |
| Companies Covered | JPMorgan Chase & Co., Bank of America Private Bank, Morgan Stanley Private Wealth Management, Wells Fargo Wealth & Investment Management, Citigroup Private Bank, Goldman Sachs Private Wealth Management, UBS Global Wealth Management, Northern Trust Wealth Management, PNC Private Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Private Banking Market Strategic Shifts
Digitization is compressing the advisor-to-client ratio while simultaneously expanding the scope of services deliverable through integrated wealth platforms. Three forces are actively restructuring competitive positioning.
Artificial intelligence-driven portfolio analytics is absorbing routine rebalancing and tax-loss harvesting functions previously executed by human advisors. Single-family offices with assets exceeding $500 million are deploying these tools at scale, reducing headcount in investment operations while expanding coverage of alternative asset monitoring. This compression is enabling advisors to absorb concentrated stock position management and direct co-investment sourcing.
The SEC's proposed rules on predictive data analytics in investor interactions are reshaping how algorithms engage retail-adjacent high-net-worth clients. The industrial consequence is mandatory human oversight of digital recommendation engines, increasing compliance staffing ratios at technology-forward institutions. California-based RIAs are responding fastest, establishing dedicated algorithm governance committees ahead of formal adoption.
Direct indexing is displacing mutual fund and ETF wrappers among households with taxable assets exceeding $5 million. The disrupted channel is packaged product distribution through wirehouse platforms; the replacement is separately managed account infrastructure with customization at the individual security level. This shift is most visible in New York and Connecticut, where concentrated equity positions from executive compensation demand tax-managed transition strategies.
United States Private Banking Market Segmentation
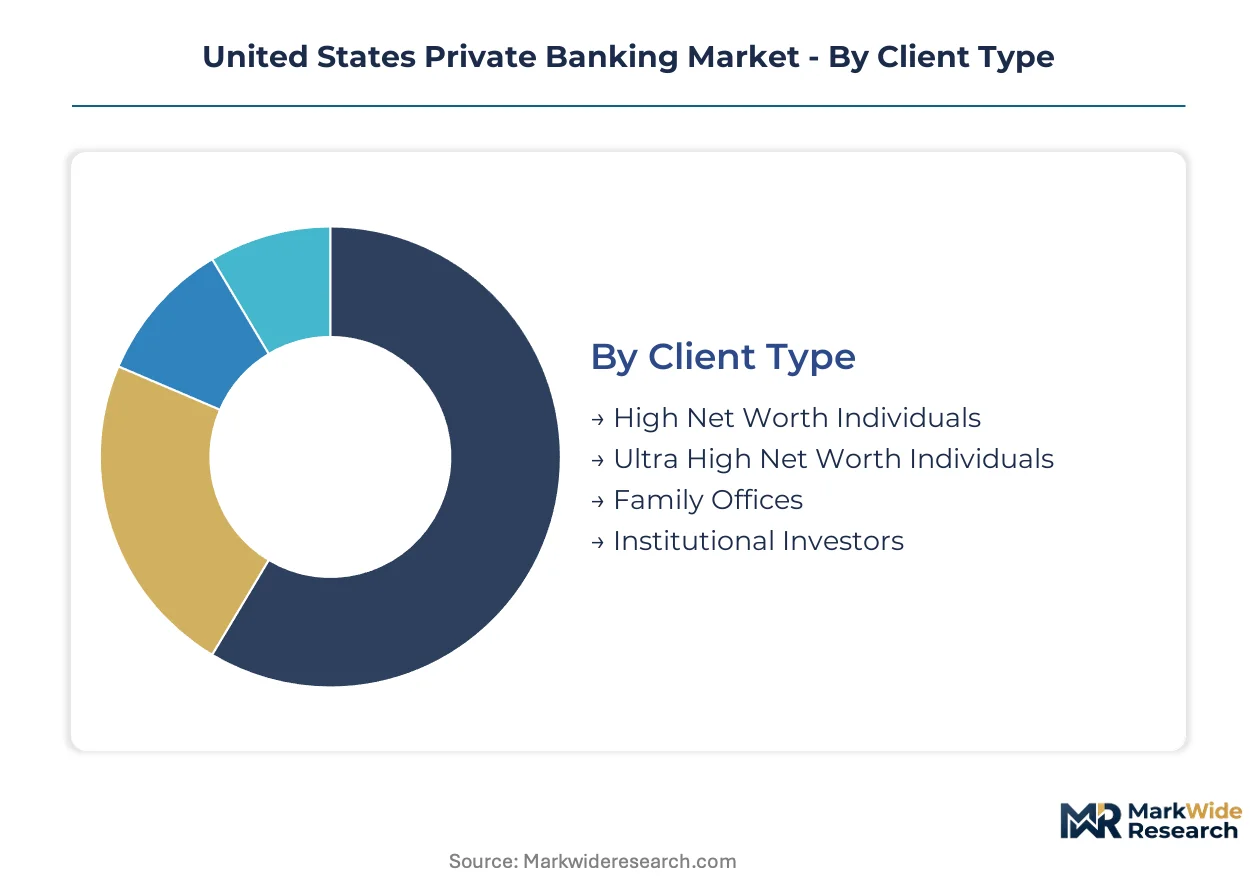
Segmentation in United States private banking reveals how advisory relationships cluster around wealth thresholds, service complexity, and structural preferences for custody and investment vehicles. Understanding these divisions exposes where margin compression and expansion occur across relationship types.
Client Type:
Upgrade cycles in advisory sophistication drive movement between tiers as household complexity evolves.
- Ultra High Net Worth Individuals:Households with investable assets exceeding $30 million command bespoke structuring across multi-jurisdictional holdings. California and New York metropolitan corridors concentrate this demand, where principals require coordination across legal, philanthropic, and concentrated equity domains.
- Family Offices:Dedicated advisory structures serving single or multiple households represent the steepest expansion trajectory as principals consolidate oversight functions. Texas and Florida are capturing relocations from high-tax coastal states, creating infrastructure gaps that regional institutions now target.
- High Net Worth Individuals:Households with $1-30 million in investable assets typically engage through private bank advisory teams rather than dedicated office structures.
- Institutional Investors:Endowments, foundations, and pension funds accessing private banking channels for custody and specialized credit facilities.
Ultra High Net Worth Individuals sit at the top of the volume ranking, with Family Offices climbing the fastest.
Service Type:
Margin structures diverge sharply between standardized investment execution and advisory functions requiring specialized credentials.
- Investment Management:Discretionary portfolio construction and ongoing rebalancing retain the largest revenue pool across the sector. Fee compression is most acute here as direct indexing and algorithmic tax-loss harvesting displace traditional active management relationships.
- Estate Planning:Intergenerational wealth transfer coordination is expanding share fastest as demographic transition accelerates among principals aged 55-75. Delaware directed trust statutes and South Dakota privacy frameworks are reshaping jurisdictional demand for situs selection.
- Wealth Advisory:Holistic financial planning encompassing liquidity management, concentrated stock strategies, and lending coordination.
- Tax Planning:Structuring around income recognition, estate tax thresholds, and grantor trust mechanics pending IRS guidance.
Investment Management commands the deepest revenue base, while Estate Planning is expanding most quickly.
Account Type:
Custody location decisions increasingly hinge on state-level legislative frameworks rather than institutional brand alone.
- Trust Accounts:Fiduciary structures governed by state law with assets held for beneficiary benefit. South Dakota's dynasty trust legislation and sealed court records are attracting multi-generational establishment from international jurisdictions.
- Managed Accounts:Separately managed account infrastructure enables security-level customization previously unavailable through packaged products. Direct indexing adoption among households with taxable assets exceeding $5 million is displacing mutual fund and ETF wrappers in New York and Connecticut.
- Custodial Accounts:Safekeeping arrangements without discretionary investment authority, often anchoring lending relationships.
- Brokerage Accounts:Transaction-based custody facing structural decline as Regulation Best Interest compresses commission-based revenue models.
Trust Accounts anchor the highest relationship values, with Managed Accounts gaining share fastest.
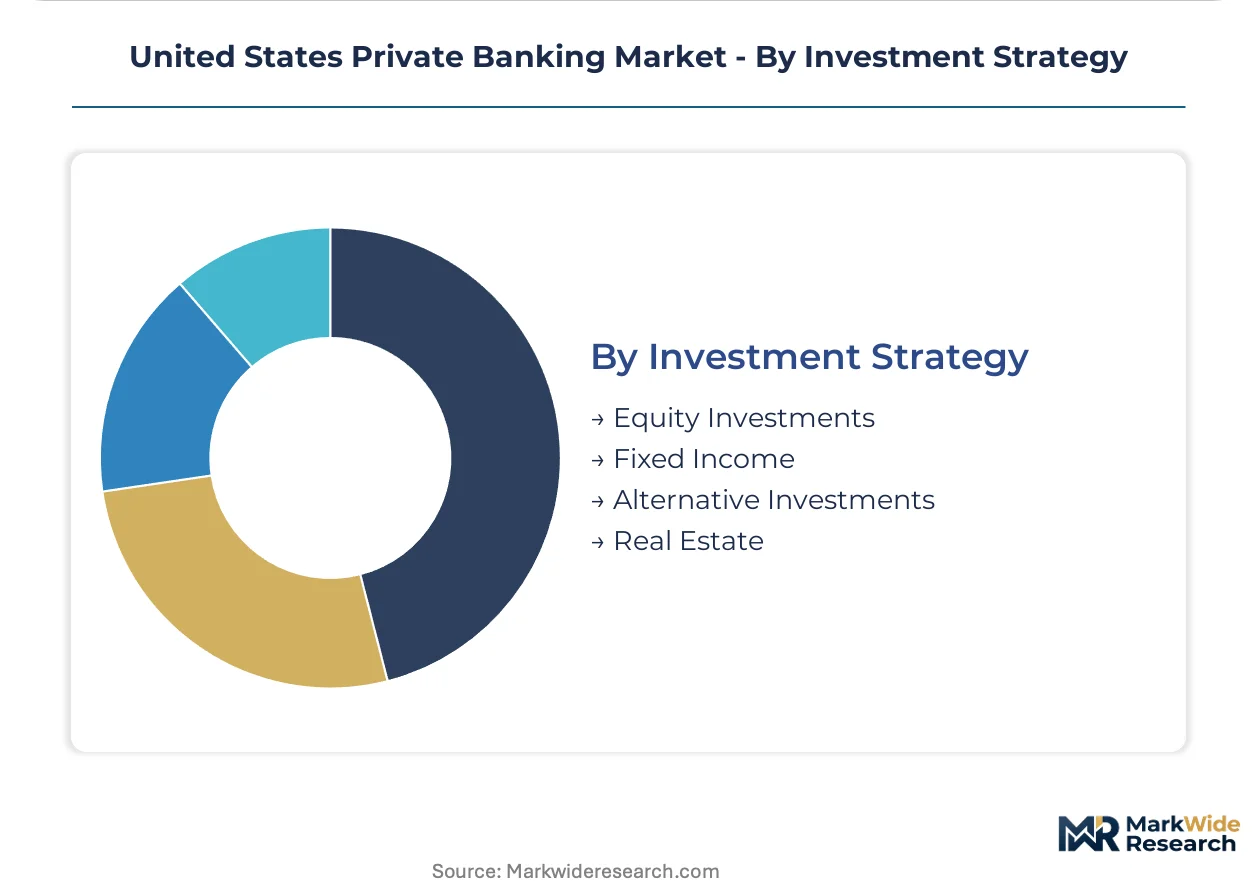
Investment Strategy:
Channel preferences are fragmenting as principals seek direct access to previously intermediated asset classes.
- Alternative Investments:Direct private equity, infrastructure, and private credit commitments are absorbing demand previously routed through fund-of-funds structures. Single-family offices with assets exceeding $500 million are deploying AI-driven monitoring tools to expand coverage without proportional headcount growth.
- Equity Investments:Concentrated positions from executive compensation and founder liquidity events dominate taxable portfolio construction. Tax-managed transition strategies are most visible in California and New York corridors where diversification demands collide with embedded gains.
- Fixed Income:Municipal bond ladders and credit strategies structured around estate liquidity requirements and income timing.
- Real Estate:Direct property holdings and private real estate funds integrated with trust structures for transfer tax efficiency.
Equity Investments retains the broadest participation base, with Alternative Investments expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified trust and estate specialists cluster disproportionately in coastal financial centers, with compensation premiums exceeding forty percent above generalist advisors. This talent concentration shapes where multi-generational family offices establish advisory infrastructure and custody relationships.
California
Ultra-high-net-worth households in the San Francisco Bay Area and Los Angeles metropolitan corridor drive demand for concentrated equity management and pre-IPO liquidity structuring. The SEC's Regulation Best Interest has accelerated decoupling of brokerage from advisory models among technology founders. Silicon Valley and Westside Los Angeles anchor the deepest advisory relationships, where principals require coordination across legal, philanthropic, and venture capital domains.
New York
Multi-generational family office structures dominate advisory relationships in the New York metropolitan area, with demand concentrating for intergenerational wealth transfer coordination. Delaware directed trust statutes influence custody location decisions for principals maintaining legal residence in Connecticut and New Jersey. Manhattan and Greenwich anchor the highest relationship values, where tax-managed transition strategies absorb demand from executive compensation-derived equity positions.
Texas
Wealth relocation from high-tax coastal states has created advisory infrastructure gaps that regional banks and independent RIAs now target. The absence of state income tax attracts single-family office establishment from California and New York principals. Dallas and Houston metropolitan areas capture the steepest expansion trajectory, where principals seek consolidated oversight across investment, legal, and philanthropic functions.
Florida
High-net-worth household migration from the Northeast corridor drives demand for estate planning and trust administration services among principals aged fifty-five to seventy-five. South Dakota dynasty trust legislation competes with Florida's lack of state income tax for custody location decisions. Miami and Palm Beach anchor the fastest-growing engagement model, where international principals establish multi-generational structures.
South Dakota
Dynasty trust legislation and sealed court records attract multi-generational family office establishment from international jurisdictions seeking privacy frameworks. State-level jurisdictional competition for trust situs expands governance flexibility beyond traditional coastal financial centers. Sioux Falls anchors specialized custody infrastructure, where directed trust statutes enable bifurcation of investment and distribution functions.
United States Private Banking Market Competitive Environment
Capital-heavy universal banking platforms compete with asset-light independent advisory models for relationship primacy across wealth tiers. The vendor base concentrates among institutions with custody scale exceeding five hundred billion dollars in assets under management, while mid-tier regional banks face sub-scale coverage economics. Three archetypes dominate: universal banks leveraging lending and custody integration, independent registered investment advisors emphasizing fee-only fiduciary structures, and specialized single-family office boutiques. Competitive moves center on technology platform investments for direct indexing capabilities and geographic expansion into Texas and Florida migration corridors.
Within the universal banking tier, JPMorgan Chase & Co. and Bank of America Private Bank occupy positions defined by integrated lending and custody relationships. Morgan Stanley Private Wealth Management exemplifies the technology-forward archetype, while Goldman Sachs Private Wealth Management anchors the founder-and-entrepreneur specialization vector. These institutions represent how scale, technology integration, and demographic targeting segment competitive positioning across the advisory landscape.
| Leading Market Players |
|---|
| JPMorgan Chase & Co. |
| Bank of America Private Bank |
| Morgan Stanley Private Wealth Management |
| Wells Fargo Wealth & Investment Management |
| Citigroup Private Bank |
| Goldman Sachs Private Wealth Management |
| UBS Global Wealth Management |
| Northern Trust Wealth Management |
| PNC Private Bank |
| Others |
Value Chain & Pricing Dynamics
Fee-only advisory premium tiers diverge sharply from commission-based brokerage discount tiers, with this bifurcation manifesting in both pricing structures and advisor compensation supply chains across the United States private banking landscape. The SEC's Regulation Best Interest accelerates this decoupling, compressing transactional revenue pools while expanding recurring fee-based relationship economics.
Pricing Analysis
Bundled wealth platform pricing dominates ultra-high-net-worth relationships, while unbundled transactional pricing persists in brokerage-retained accounts. Price differentiation hinges on fiduciary certification level and alternative asset access depth. Cost compression in commission-based tiers intensifies because Regulation Best Interest disclosure requirements raise compliance overhead. High-net-worth individuals with one to five million dollars in investable assets exhibit greatest price sensitivity, whereas family offices with dedicated infrastructure show minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements for custody infrastructure mandate that family offices maintain qualified relationships with at least two institutional trustees, typically pairing a universal bank with a specialized trust company. Geographic supply concentration centers on New York, Delaware, and South Dakota as trust situs jurisdictions. Raw material dependencies include certified trust and estate specialists, portfolio analytics software licenses, and alternative asset due diligence frameworks. Single-source vulnerability persists in concentrated equity management expertise. Distribution runs through registered investment advisor networks and private bank direct sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between California's high-tax regulatory environment and Texas or Florida's absence of state income tax creates substantial cost differentials for family office establishment and advisory relationship migration.
For Market Incumbents: Anticipate fee compression in standardized investment management as direct indexing platforms displace active management relationships. Defensive consolidation moves include acquiring specialized trust administration boutiques in Delaware and South Dakota to capture jurisdictional migration flows. Talent retention levers center on equity participation structures for certified trust and estate specialists facing forty percent compensation premiums. For New Entrants and Emerging Players: Technology founders with pre-IPO equity concentration represent an underserved buyer archetype requiring liquidity event structuring expertise absent at regional institutions. White-space targets include Dallas and Houston metropolitan corridors where wealth relocation from California has outpaced advisory infrastructure development. Go-to-market positioning should emphasize concentrated stock management and direct private equity access rather than standardized portfolio construction. For Investors and Strategic Acquirers: Consolidation pressure builds where sub-scale regional banks lack custody scale to cover Texas and Florida expansion economics profitably. Long-term viability favors asset-light independent registered investment advisors with established fiduciary structures over universal banking platforms facing legacy system integration burdens. Acquisition target archetypes include Delaware and South Dakota trust companies with directed trust statute expertise. The signal to watch is IRS guidance resolution on intentionally defective grantor trust taxation, which would unlock frozen structuring demand among ultra-high-net-worth households.| Strategic Initiative | Industry Significance |
|---|---|
| Delaware Trust Company Acquisition | Captures directed trust statute demand from family offices fleeing high-tax coastal jurisdictions. |
| Direct Indexing Platform Deployment | Enables security-level customization for taxable portfolios exceeding five million dollars in New York and Connecticut corridors. |
| Texas Advisory Infrastructure Expansion | Addresses coverage gaps created by wealth relocation from California principals seeking consolidated oversight functions. |
| Alternative Asset Due Diligence Partnership | Secures private equity and infrastructure access previously routed through fund-of-funds intermediaries. |
| Certified Specialist Talent Retention Program | Offsets forty percent compensation premiums eroding margin structures at mid-tier institutions. |
Study Parameters
Bottom-up family office and high-net-worth household modeling reconciled against top-down custody asset tracking forms the analytical core of this study. Primary interviews with private bank relationship managers, trust administration officers, registered investment advisor principals, and family office chief investment officers combined with secondary validation against SEC examination disclosures, IRS guidance publications, state trust legislation databases, and institutional custody regulatory filings. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of advisory relationship pricing and custody asset flows established baseline trajectories across the projection horizon. Segmentation dimensions modeled include client type, service type, account type, and investment strategy, with geographic migration patterns and regulatory compliance intensity as industry-specific overlay factors. CAGRs derived from regression analysis against demographic transition timelines and jurisdictional competition dynamics. Forecast inputs incorporate intergenerational wealth transfer velocity and alternative asset platform adoption curves.
Underlying measurement precision varies by segment; ultra-high-net-worth individual and family office categories carry tighter precision than high-net-worth individual estimates due to disclosure requirements. Forecasts reflect assumptions around SEC rule finalization timing and IRS guidance release schedules. Deviation in grantor trust taxation resolution or predictive data analytics rule adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market