
 Family Office Services Market | 2026-2036
Family Office Services Market Size, Share, and Industry Trends Forecast 2026-2036
Family Office Services Market Insights
The shift from embedded in-house teams toward outsourced specialist providers is restructuring how ultra-wealthy families manage intergenerational wealth. UBS leverages its integrated global platform to anchor cross-border tax and estate capabilities across European and Asian jurisdictions. Bessemer Trust differentiates through its century-old multi-family office model that sustains deep fiduciary relationships with legacy industrial wealth holders. Stonehage Fleming specializes in governance and succession frameworks for international families with assets spanning multiple legal systems.
Family office services encompass integrated financial, legal, and administrative solutions delivered to ultra-high-net-worth families, typically requiring minimum investable assets exceeding twenty-five million dollars and involving coordinated custody, reporting, and fiduciary oversight across jurisdictions. Wealth management functions as the foundational service layer, generating recurring fee income while estate planning commands premium pricing due to the scarcity of qualified trust and tax attorneys capable of navigating multi-jurisdictional inheritance regimes. Multi-family offices represent the fastest-scaling client type as cost-sharing economics attract families below the single-office threshold, while alternative investments within the investment strategy dimension attract disproportionate operational resources due to complex valuation, custody, and reporting demands.
The SEC imposes investment adviser registration and disclosure obligations on family offices managing third-party capital, while the IRS enforces transfer tax compliance that shapes estate planning service design and pricing structures. FATCA and CRS information-sharing frameworks between tax authorities have intensified cross-border transparency requirements, forcing service providers to build dedicated compliance infrastructure. Stakeholders must monitor evolving digital asset custody regulations and artificial intelligence governance standards as these emerging domains increasingly intersect with traditional family office mandates.
Market Dynamics
The migration of ultra-wealthy families from single-family offices toward outsourced multi-family structures is compressing fee structures while expanding service scope, forcing providers to automate reporting and consolidate custody relationships.
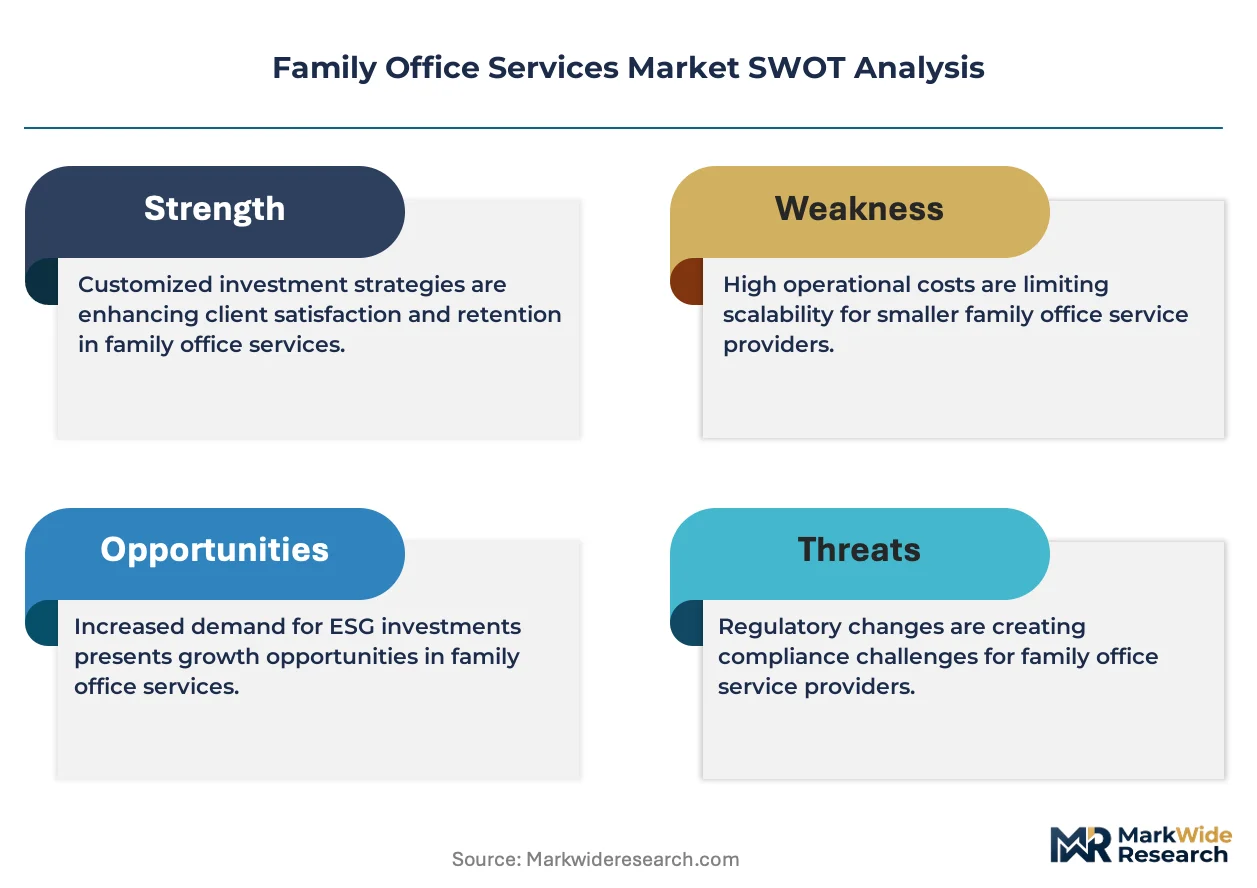
Growth Catalysts
- FATCA and CRS frameworks:Cross-border transparency mandates from the IRS and OECD member tax authorities are compelling families to consolidate fragmented accounts under unified reporting platforms.
- Healthcare sector wealth creation:Biotechnology entrepreneurs and pharmaceutical founders in Boston and San Diego are generating liquidity events that require coordinated estate and philanthropic structuring.
- Tokenization infrastructure:Distributed ledger technology for private fund interests is absorbing operational overhead from manual subscription and capital call processes.
Market Restraints
- Qualified trustee scarcity:The limited pipeline of attorneys credentialed in both common-law and civil-law trust jurisdictions restricts service expansion for international families.
- Concentrated custody risk:Three global banks dominate institutional-grade asset safekeeping, creating operational dependency for mid-sized multi-family offices.
- Substitution by embedded wealth tech:Direct indexing platforms and automated tax-loss harvesting tools are absorbing routine portfolio management functions previously outsourced.
Strategic Opportunities
- Digital asset governance:The SEC's evolving custody rulemaking for cryptocurrencies creates advisory white space for providers building qualified custodian relationships.
- Next-generation education services:Structured financial literacy programs for heirs aged 18-30 represent an unbundled revenue stream beyond traditional AUM fees.
- Singapore and Dubai expansion:Asset migration to these jurisdictions by Asia-Pacific and Middle Eastern families is driving demand for local trust company licensing.
Industry Challenges
- Cybersecurity certification complexity:SOC 2 Type II and ISO 27001 audits for family-specific data environments require 12-18 month implementation timelines.
- Intergenerational advisor transition:Succession planning for relationship managers serving century-old client families threatens continuity of fiduciary oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Family Office Services Market |
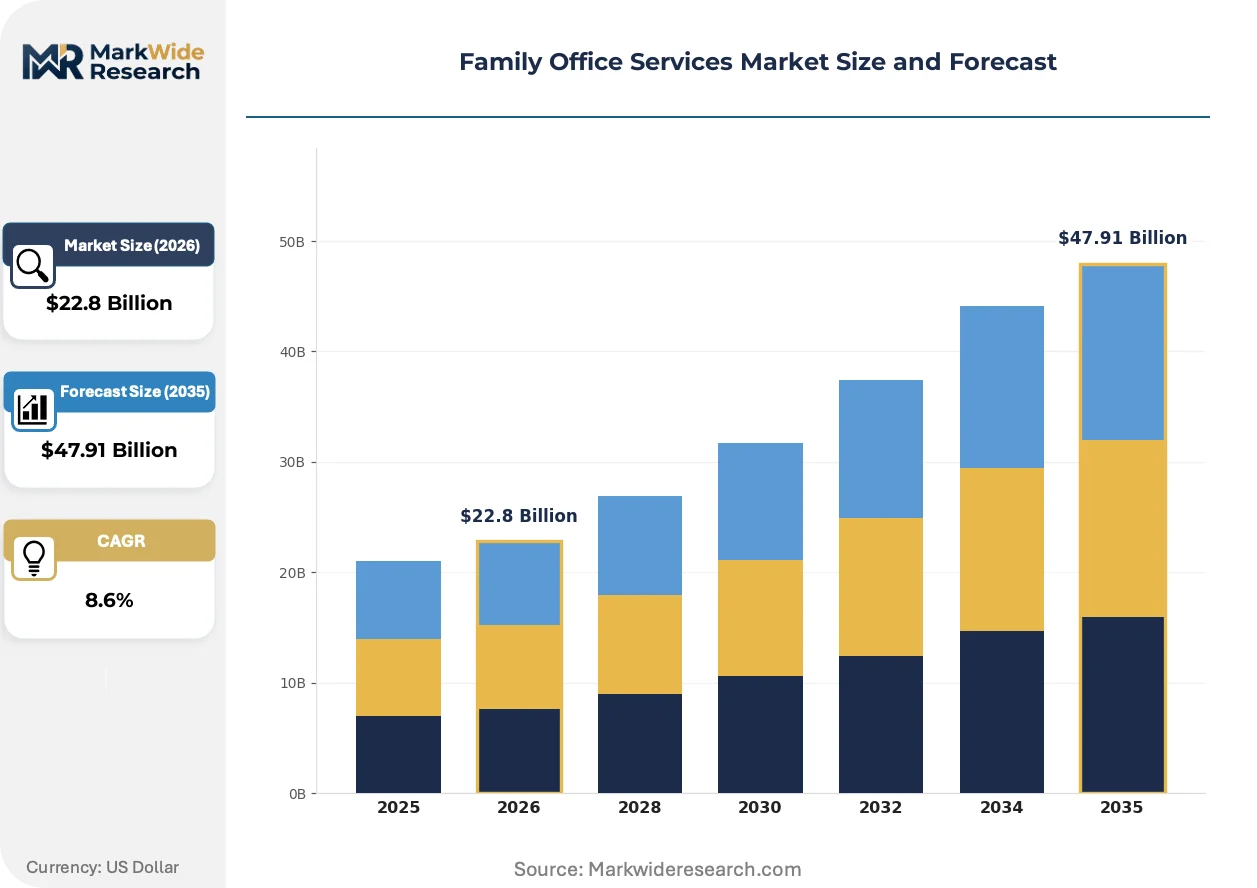
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wealth Management, Tax Advisory, Estate Planning, Philanthropy Consulting, Succession Planning Client Type: Single-Family Offices, Multi-Family Offices, Virtual Family Offices, Embedded Family Offices Investment Strategy: Alternative Investments, Public Equities, Fixed Income, Real Assets, Private Equity Asset Class: Real Estate, Hedge Funds, Venture Capital, Commodities, Debt Instruments |
| Companies Covered | UBS, J.P. Morgan, Northern Trust, Bessemer Trust, Citi Private Bank, Goldman Sachs, Morgan Stanley, HSBC Private Banking, Stonehage Fleming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Family Office Services Market Trends and Innovations
Artificial intelligence is absorbing compliance and reporting workflows that previously consumed analyst bandwidth, while regulatory fragmentation across jurisdictions forces modular service architectures.
Generative AI for document analysis is absorbing trust administration and KYC verification tasks previously handled by paralegal staff. Multi-family offices with over five hundred million dollars in aggregate AUM are deploying these tools for beneficiary disclosure preparation. The technology is absorbing routine legal drafting hours and compressing service delivery timelines from weeks to days.
The EU's Digital Operational Resilience Act (DORA) imposes ICT risk management mandates on financial entities including Luxembourg and Irish fund structures commonly used by international families. Service providers must implement incident reporting protocols and third-party risk monitoring by 2025. European-domiciled family offices are responding by segregating critical technology vendors and negotiating contractual exit rights.
Direct indexing platforms are unbundling traditional separately managed account relationships that bundled tax optimization with custody and reporting. Ultra-high-net-worth families with fifty million dollars or more in taxable assets are adopting these tools for customization and transparency. This pattern is most visible in California and New York, where concentrated stock positions from technology IPOs demand systematic transition strategies.
Family Office Services Market Segmentation
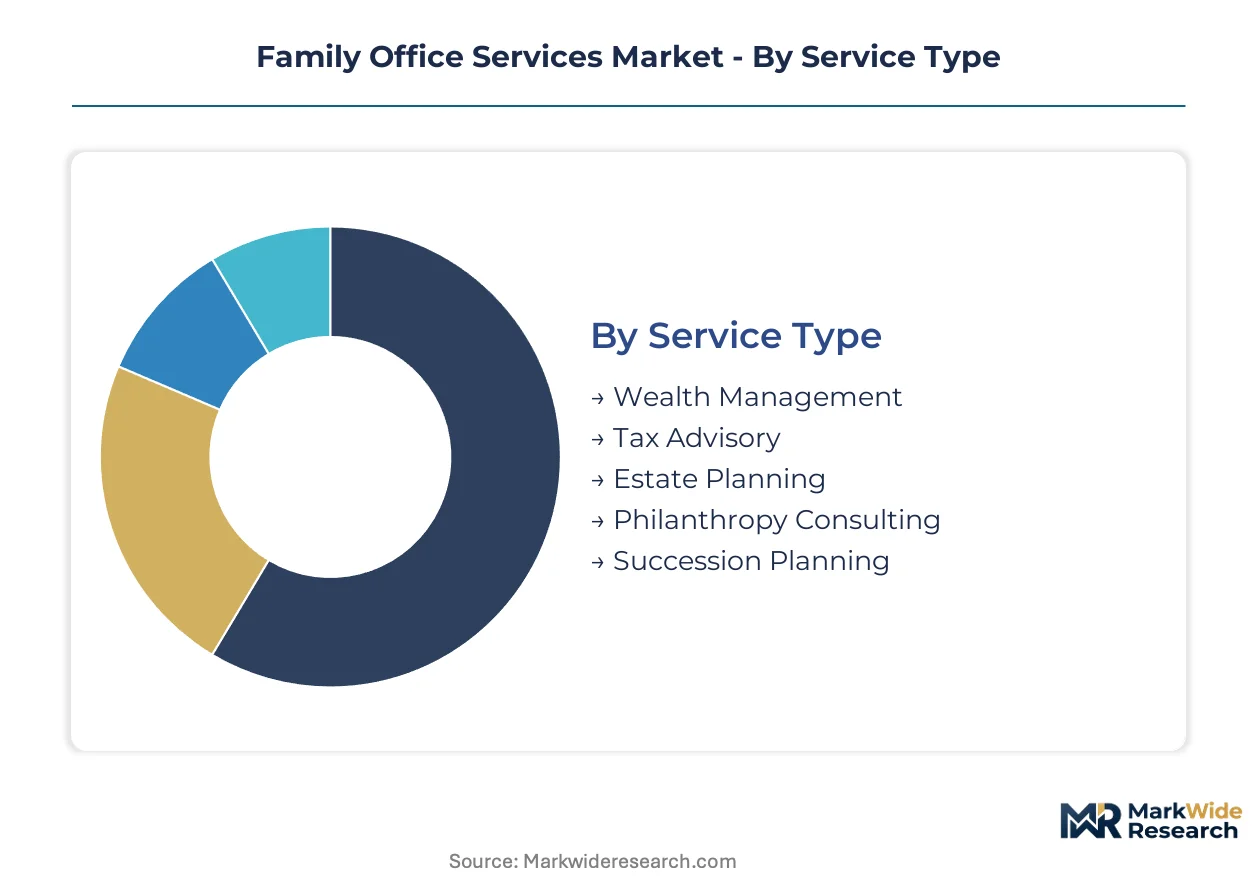
Family office services fragment across service delivery models, client structures, and asset deployment strategies that each impose distinct operational requirements and margin profiles on providers. Understanding these segment boundaries clarifies where capital is concentrating and which configurations absorb disproportionate compliance overhead.
Service Type:
Supply concentration sits with fiduciary functions that demand credentialed personnel and regulatory licensing across multiple jurisdictions.
- Wealth Management:Core portfolio construction, custody coordination, and consolidated reporting functions form the foundational revenue layer for most providers. Demand clusters in New York and California where technology and healthcare liquidity events generate taxable asset transitions requiring systematic rebalancing and tax-loss harvesting protocols.
- Estate Planning:Trust structuring, multi-jurisdictional inheritance coordination, and transfer tax minimization command premium pricing due to attorney scarcity. Families with assets spanning common-law and civil-law jurisdictions drive demand for unified succession frameworks that reconcile conflicting forced heirship regimes.
- Tax Advisory:Cross-border compliance, FATCA/CRS reporting coordination, and jurisdictional arbitrage structuring for families with multinational footprints.
- Philanthropy Consulting:Donor-advised fund administration, foundation governance, and impact measurement frameworks for intergenerational giving strategies.
- Succession Planning:Governance framework design, next-generation education protocols, and family constitution drafting to manage intergenerational wealth transitions.
Wealth management absorbs the bulk of installed capacity; estate planning is expanding most quickly.
Client Type:
Cost tier differentiation separates capital-intensive dedicated infrastructure from variable-cost shared service models.
- Multi-Family Offices:Shared governance, consolidated custody relationships, and pooled operational overhead allow families below the single-office threshold to access institutional-grade reporting and compliance infrastructure. Boston and San Diego biotechnology wealth is migrating toward these structures post-liquidity events.
- Single-Family Offices:Dedicated staff, proprietary technology stacks, and bespoke governance frameworks serving one family with assets typically exceeding five hundred million dollars. Operational complexity and fixed cost burdens are driving fragmentation toward outsourced models.
- Virtual Family Offices:Networked specialist providers coordinated through technology platforms without dedicated physical infrastructure.
- Embedded Family Offices:Wealth management functions retained within operating businesses or family-controlled holding companies rather than standalone entities.
Multi-family offices capture the steepest expansion trajectory; single-family offices retain the highest revenue per client.
Investment Strategy:
Application complexity varies sharply across liquidity profiles and valuation methodology requirements.
- Alternative Investments:Private fund interests, co-investment structures, and direct deal sourcing demand specialized custody, capital call management, and illiquidity budgeting. Operational resources concentrate here due to manual subscription processes and bespoke side-letter negotiation.
- Private Equity:Long-dated fund commitments, secondary market transactions, and direct company board representation require dedicated monitoring infrastructure and governance integration with family operating expertise.
- Public Equities:Systematic rebalancing, direct indexing implementation, and securities lending programs for taxable efficiency.
- Fixed Income:Laddered maturity structures, credit analysis, and liability-driven investing for spending-rule compliance.
- Real Assets:Direct property ownership, infrastructure fund exposure, and natural resource investment with physical asset management coordination.
Alternative investments absorb disproportionate operational headcount; private equity is climbing the fastest among institutional allocations.
Asset Class:
Maturity gradients separate regulated custodial assets from emerging categories with evolving oversight frameworks.
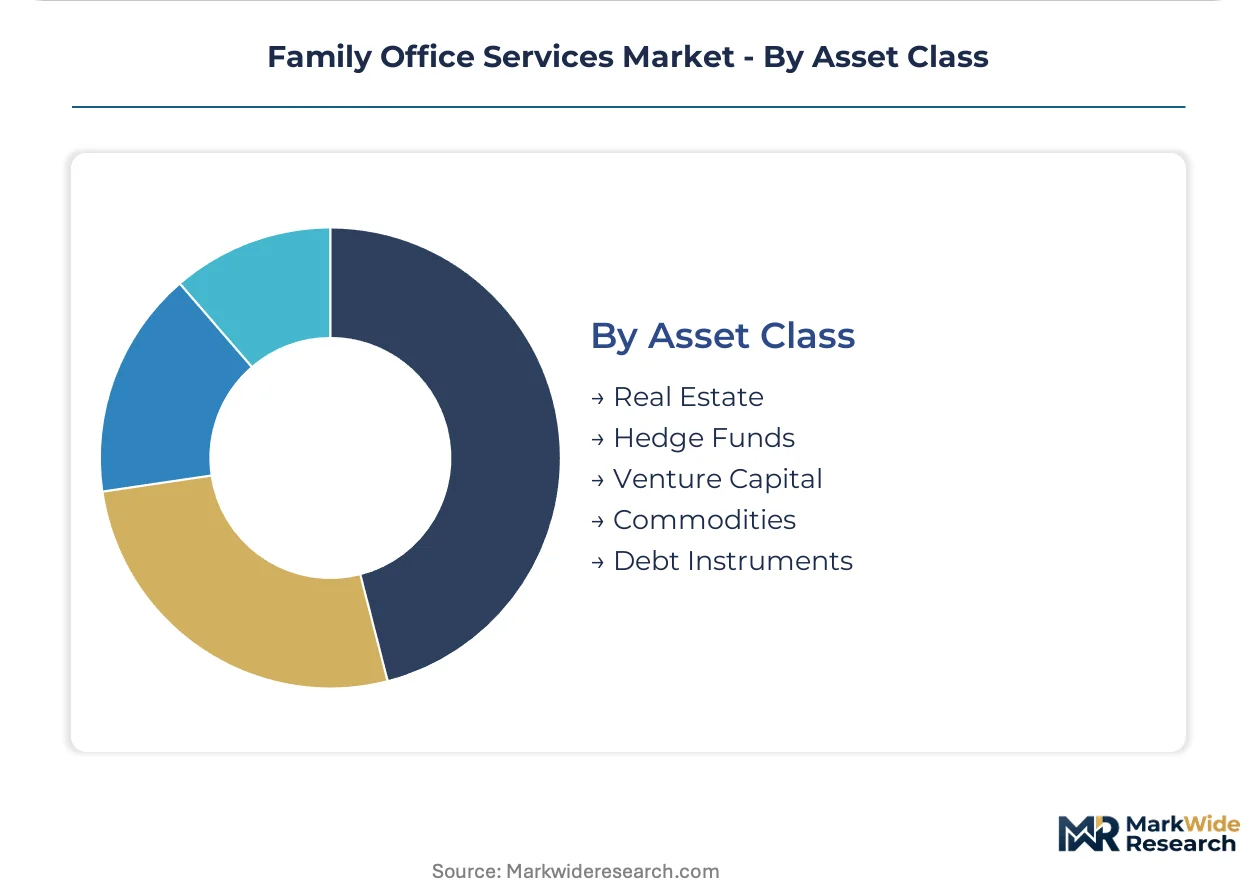
- Real Estate:Direct property holdings, real estate fund commitments, and development joint ventures spanning residential, commercial, and agricultural categories. Concentrated positions in gateway cities create geographic risk requiring systematic diversification protocols.
- Venture Capital:Early-stage technology exposure, fund-of-funds diversification, and direct angel investing with high failure rates and concentrated return profiles. Silicon Valley and Boston families deploy dedicated allocation teams for sourcing and due diligence.
- Hedge Funds:Multi-strategy fund exposure, managed account platforms, and liquid alternative replication for volatility management.
- Commodities:Physical precious metals, futures-based exposure, and natural resource equity positions for inflation hedging.
- Debt Instruments:Private credit, distressed debt, and structured fixed income for yield enhancement in low-rate environments.
Real estate anchors the largest allocation share; venture capital is gaining share fastest among technology wealth holders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York and London anchor the primary capital pools that feed family office service demand, with Singapore and Dubai emerging as secondary wealth hubs attracting Asia-Pacific and Middle Eastern capital migration.
United States
Biotechnology liquidity events in Boston and San Diego generate concentrated demand for estate structuring and philanthropic coordination. The SEC's expanded investment adviser oversight mandates registration for multi-family offices managing third-party capital. New York and California multi-generational wealth holders drive premium adoption of integrated reporting platforms.
United Kingdom
Historic industrial wealth and incoming Asia-Pacific family capital sustain demand for multi-jurisdictional trust administration. The FCA's consumer duty regulations reshape disclosure obligations for cross-border advisory relationships. London's Mayfair district concentrates bespoke single-family office infrastructure serving legacy asset holders.
Switzerland
Cross-border wealth preservation and confidentiality frameworks attract European and Latin American family capital. FINMA's updated fintech licensing creates pathways for digital asset custody integration within traditional fiduciary structures. Geneva and Zurich private banks anchor institutional-grade safekeeping relationships for international families.
Singapore
Family office incentive schemes and territorial tax structures draw Asia-Pacific wealth migration from Hong Kong and mainland China. The Monetary Authority of Singapore's trust company licensing framework enables local fiduciary infrastructure development. The city-state's fund domicile ecosystem supports private equity and venture capital allocation strategies for regional families.
United Arab Emirates
Zero personal income tax and golden visa programs attract Russian, Indian, and African wealth migration. The Dubai International Financial Centre's common-law trust framework enables English-law succession planning for non-resident families. Abu Dhabi's sovereign wealth proximity creates co-investment and direct deal sourcing opportunities for regional family offices.
Family Office Services Market Competitive Landscape
Global majors compete with regional champions across custody infrastructure and cross-border tax coordination, producing a tiered structure where integrated universal banks anchor the premium segment and specialized multi-family offices capture mid-market expansion. Three archetypes dominate: balance-sheet-heavy private banking divisions, independent fiduciary specialists, and technology-enabled platform aggregators. Competitive moves concentrate on trust company licensing in emerging wealth hubs and automated reporting stack consolidation.
Within the integrated banking tier, UBS and J.P. Morgan occupy positions spanning custody, lending, and cross-border structuring for the largest family relationships. Bessemer Trust exemplifies the independent fiduciary archetype with century-old multi-family office infrastructure. Stonehage Fleming represents the governance-specialist segment with international family succession frameworks.
| Leading Market Players |
|---|
| UBS |
| J.P. Morgan |
| Northern Trust |
| Bessemer Trust |
| Citi Private Bank |
| Goldman Sachs |
| Morgan Stanley |
| HSBC Private Banking |
| Stonehage Fleming |
| Others |
Pricing and Supply Chain Analysis
Century-old fiduciary specialists and private-equity-rolled-up multi-family office platforms anchor supply-side concentration, enabling premium pricing for cross-border trust administration while compressing margins through shared-service economics for mid-market entrants.
Pricing Analysis
Warranty and service-bundling differentiation separates integrated fiduciary packages from unbundled component pricing across wealth management, estate planning, and tax advisory tiers. Pricing stratifies across premium, standard, and economy tiers based on jurisdictional complexity and attorney credential depth, with cross-border common-law and civil-law trust expertise commanding substantial premiums. Cost compression in the virtual family office segment is intensifying because direct indexing platforms and automated reporting tools absorb routine portfolio functions previously outsourced. Single-family offices with dedicated staff show the least price sensitivity; multi-family office entrants below the single-office threshold exhibit the highest.
Supply Chain Analysis
Certification and qualification gating through SOC 2 Type II and ISO 27001 audits restricts vendor eligibility for family-specific data environments, creating 12-18 month implementation barriers. Supply concentrates in the United States, Switzerland, and Singapore, where regulatory infrastructure supports cross-border fiduciary licensing. Raw material dependencies include credentialed trust and tax attorneys, institutional-grade custody relationships with global banks, and proprietary governance technology platforms. Single-source vulnerability runs through the three dominant global banks controlling institutional asset safekeeping. Distribution runs through direct relationship-manager channels for high-touch fiduciary services and technology-enabled platforms for virtual office coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where SEC investment adviser registration mandates and EU MiFID II transparency requirements erect barrier-to-entry moats favoring incumbent providers with established regulatory infrastructure.
For Market Incumbents: To counter embedded wealth technology substitution, deepen proprietary custody relationships with the three dominant global banks and accelerate generative AI deployment for trust administration workflows. Invest in trust company licensing in Singapore and Dubai to capture Asia-Pacific and Middle Eastern wealth migration. Attorney credential pipelines in common-law and civil-law jurisdictions represent the priority capability lock-up. For New Entrants and Emerging Players: Capture digital asset governance white space by building qualified custodian relationships ahead of SEC custody rulemaking finalization. Target next-generation education services for heirs aged 18-30 as an unbundled revenue stream beyond traditional AUM-based pricing. A technology-enabled platform aggregation model with networked specialist providers offers the most penetrable entry path against integrated banking incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent fiduciary specialists with established multi-jurisdictional licensing in Switzerland and Luxembourg over balance-sheet-heavy private banking divisions. Long-term viability across the coming decade hinges on successful intergenerational advisor transition and cybersecurity certification maintenance. The signal to watch is regulatory clarity on digital asset custody standards as an inflection indicator for platform valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Trust Company Licensing Expansion | Monetary Authority of Singapore and Dubai International Financial Centre approvals enable local fiduciary infrastructure for migrating Asia-Pacific and Middle Eastern capital. |
| Generative AI Document Automation | Deployment for trust administration and KYC verification compresses service delivery timelines from weeks to days at multi-family offices with substantial aggregate AUM. |
| Qualified Custodian Relationship Development | SEC custody rulemaking for cryptocurrencies creates advisory white space for providers building institutional-grade digital asset safekeeping capabilities. |
| Next-Generation Education Program Launch | Structured financial literacy protocols for heirs aged 18-30 represent unbundled revenue beyond traditional AUM fees at multi-family offices. |
| Cybersecurity Certification Investment | SOC 2 Type II and ISO 27001 implementation for family-specific data environments satisfies EU Digital Operational Resilience Act mandates by 2025. |
Research Methodology
Independent corroboration across primary interviews with family office principals, trust company executives, regulatory compliance officers, and cross-border tax attorneys, combined with secondary validation of SEC registration filings, FINMA fintech licensing disclosures, Monetary Authority of Singapore trust company registers, and EU regulatory implementation notices, underwrites the qualitative findings. Bottom-up aggregation of service provider capacity and top-down demand estimation from ultra-high-net-worth population databases establish analytical triangulation.
Rate-of-change decomposition across the projection horizon segments volume and value trajectories by service type, client structure, and investment strategy dimensions. Modeled segmentation spans wealth management, estate planning, tax advisory, and succession planning functions; multi-family, single-family, virtual, and embedded office configurations; and alternative investment, private equity, public equity, and real asset deployment strategies. CAGRs derive from regression analysis against ultra-high-net-worth population growth, liquidity event frequency in technology and healthcare sectors, and regulatory implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to digital asset custody regulatory clarity, artificial intelligence governance standard evolution, and intergenerational wealth transfer velocity. Forecasts reflect documented assumptions regarding SEC and EU regulatory enforcement intensity, FATCA and CRS information-sharing framework expansion, and technology sector liquidity event persistence. A model refresh is warranted upon material change in qualified trustee pipeline availability or cybersecurity certification requirement scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
India Private Banking Market