
 UK Pension Fund Market | 2026-2036
UK Pension Fund Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pension Fund Market Insights
Asset management fee revenue is tilting from active equity mandates toward lower-cost passive and alternative investment strategies. Nest Corporation leverages its government-backed scale to dominate the auto-enrolment default fund space. Legal & General Mastertrust anchors institutional flows through its integrated insurance-pension platform. The People's Pension competes aggressively on cost, positioning itself as the low-fee option for small and medium employers.
A UK pension fund constitutes a pooled investment vehicle governed by trust law, regulated under the Pensions Act framework, and structured to provide retirement income through accumulated contributions and investment returns over multi-decade horizons. Its primary purpose is to transform periodic employer and employee contributions into sustainable post-retirement cash flows while managing longevity risk and inflation erosion. Defined benefit schemes now occupy a shrinking but capital-intensive segment where liability-driven investment strategies preserve funded status against gilt yield movements. Defined contribution arrangements represent the fastest-growing fund type as auto-enrolment mandates channel new flows into master trust vehicles. Within asset class allocation, alternatives including infrastructure and private credit attract sponsor attention as equity-bond correlations shift.
The Pensions Regulator enforces funding standards and scheme governance, while the Financial Conduct Authority oversees investment conduct and consumer protection for contract-based arrangements. The Department for Work and Pensions shapes structural policy through auto-enrolment thresholds and collective defined contribution legislation. Stakeholders must monitor how the UK government's Mansion House reforms redirect pension capital toward unlisted equity and productive finance assets.
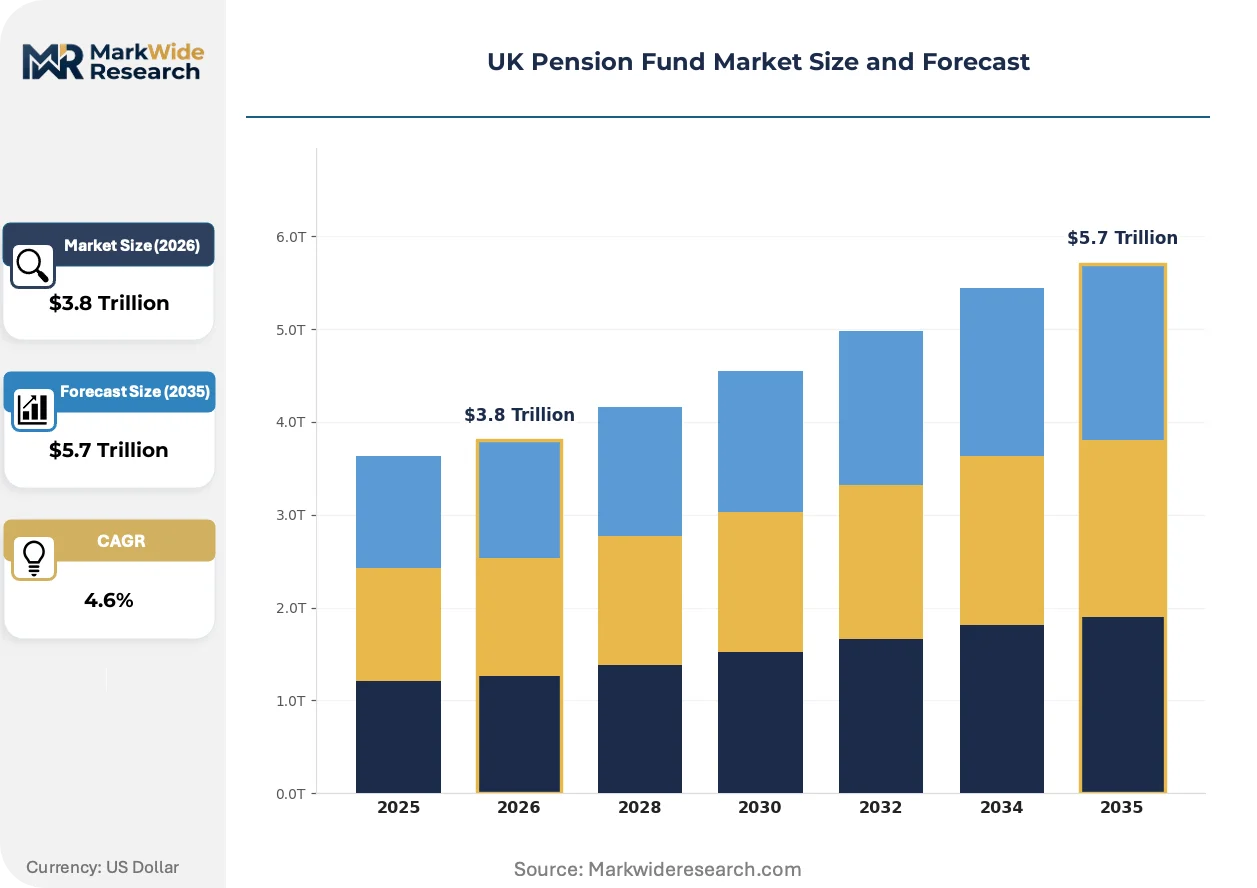
Market Dynamics
Auto-enrolment mandates and the 2023 Mansion House reforms are redirecting pension capital toward productive finance assets, fundamentally altering trustee investment mandates and reshaping the competitive landscape for master trust providers.
Growth Catalysts
- Auto-Enrolment Threshold Expansion:The Department for Work and Pensions has progressively lowered minimum earnings thresholds, capturing part-time workers and younger demographics into defined contribution schemes.
- Technology Sector Employer Migration:Portable retirement benefits align with gig-economy and tech sector employment patterns, driving demand for master trusts over single-employer arrangements.
- LDI Strategy Maturation:Liability-driven investment frameworks now protect defined benefit funded status against gilt volatility, preserving scheme solvency for sponsoring employers.
Market Restraints
- Gilt Yield Dependency:Defined benefit scheme valuations remain hypersensitive to UK government bond movements, creating balance sheet volatility for corporate sponsors.
- Fee Compression Dynamics:Master trust providers face margin pressure as The People's Pension and Nest Corporation compete aggressively on basis-point pricing.
- Longevity Risk Concentration:Annuity providers and scheme trustees bear unhedged exposure to mortality improvement assumptions across pooled cohorts.
Strategic Opportunities
- Scottish Financial Services Cluster:Edinburgh and Glasgow host concentrated pension administration expertise, offering operational scale for platform consolidation.
- Collective Defined Contribution Legislation:The Pensions Schemes Act 2021 enables risk-sharing structures that blend defined benefit stability with defined contribution portability.
- Infrastructure Asset Allocation:Mansion House reforms explicitly channel retirement capital toward unlisted equity and productive finance, creating new investment mandates.
Industry Challenges
- Actuarial Talent Scarcity:Defined benefit scheme wind-downs have shrunk the specialist workforce needed for complex liability valuation and hedging execution.
- Legacy System Integration:Master trust platforms struggle to reconcile disparate data architectures when consolidating acquired pension books.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pension Fund Market |
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $5.7 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Type: Defined Benefit, Defined Contribution, Hybrid, Cash Balance Investment Strategy: Growth, Income, Balanced, Conservative Asset Class: Equities, Fixed Income, Real Estate, Alternatives Client Segment: Corporate, Public Sector, Not-for-Profit, Retail |
| Companies Covered | Nest Corporation, Universities Superannuation Scheme, BT Pension Scheme, Electricity Supply Pension Scheme, Aviva Master Trust, Legal & General Mastertrust, The People's Pension, Scottish Widows Master Trust, Local Government Pension Fund, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pension Fund Market Trends and Innovations
Pension fund operations are digitizing rapidly, with trustees demanding real-time risk analytics and members expecting mobile-first engagement interfaces that mirror retail banking experiences.
Portfolio construction is migrating from traditional 60/40 equity-bond splits toward multi-asset approaches incorporating private credit, infrastructure, and absolute return strategies. Large defined contribution schemes are adopting these frameworks fastest, driven by pressure for yield in low-gilt environments. The shift is compressing demand for conventional active equity mandates while expanding alternatives allocation.
The Pensions Regulator's new single code of practice consolidates 15 previous sets of guidance into unified governance standards. Trustee boards must now demonstrate explicit systems and controls documentation or face escalated enforcement. Smaller defined benefit schemes are responding through accelerated buyout transactions to offload regulatory burden to insurance consolidators.
Member engagement patterns are fragmenting across generational cohorts, with younger participants demanding app-based contribution tracking and ESG transparency tools. Traditional paper-based annual statements are yielding to personalized digital nudges and retirement income calculators. This behavioral shift is most visible among auto-enrolled employees in technology and professional services sectors, where employer benefits platforms integrate pension dashboards with broader financial wellness offerings.
UK Pension Fund Market Segmentation
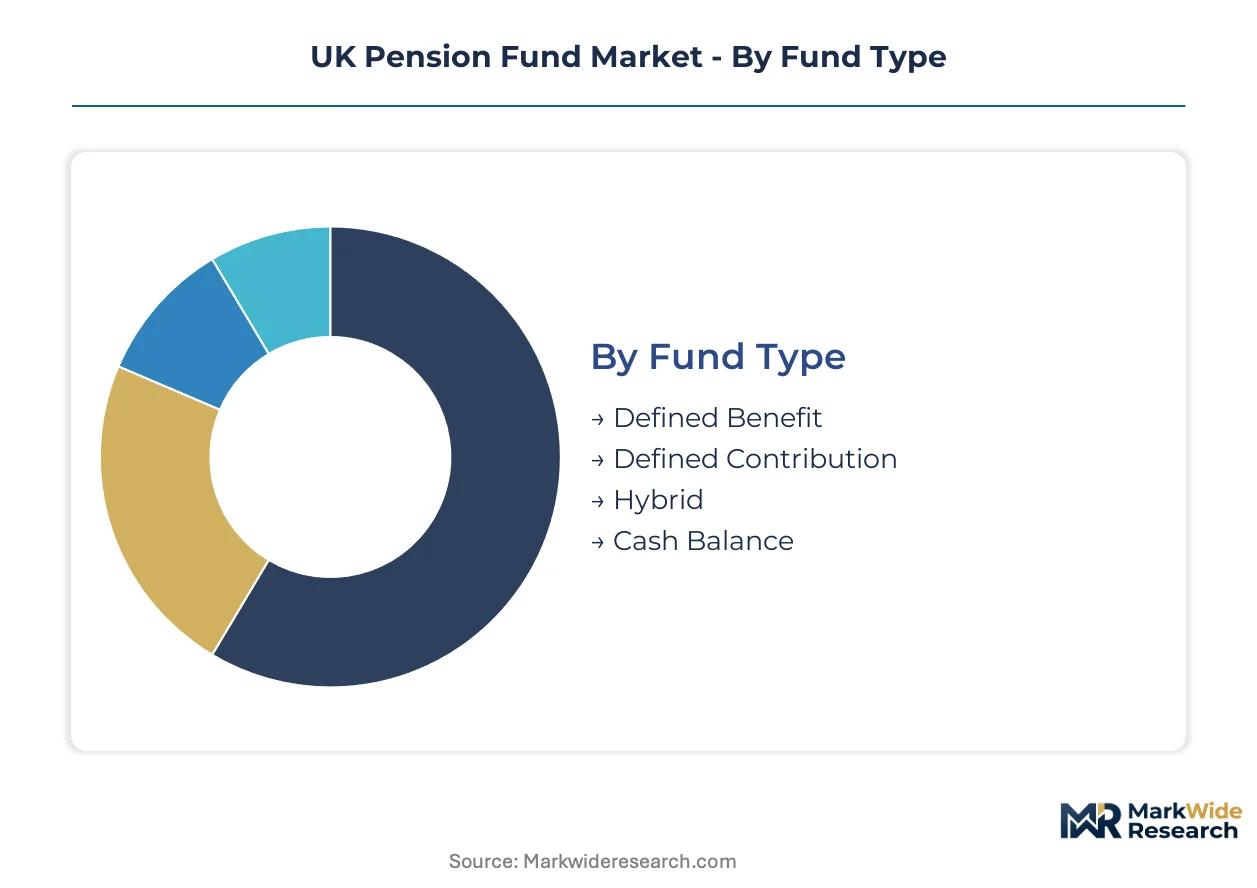
Segmentation in the UK pension fund market reveals how trustee mandates, sponsor risk appetites, and regulatory frameworks partition capital across structurally distinct vehicles. Understanding these divisions exposes where fee compression bites deepest and where Mansion House reforms are redirecting asset allocation priorities.
Fund Type:
Defined contribution vehicles turn over membership fastest through auto-enrolment churn and job mobility, while defined benefit schemes exhibit decades-long liability run-off cycles that lock capital into LDI frameworks.
- Defined Benefit:Promise fixed retirement incomes calculated from final salary or career-average formulas, requiring sponsors to backfill funding shortfalls. Corporate sponsors in manufacturing and legacy sectors concentrate here, grappling with gilt yield volatility that swings balance sheet valuations quarterly.
- Defined Contribution:Accumulate individual member pots where retirement outcomes depend on contribution rates and investment performance. Technology sector employers and gig-economy platforms favor these portable structures, driving master trust consolidation as members switch jobs frequently.
- Hybrid:Blend guaranteed benefit floors with defined contribution upside participation, appealing to employers seeking middle-ground risk sharing.
- Cash Balance:Credit notional accounts with employer-specified returns, offering predictable accruals without full defined benefit guarantees.
Defined Benefit anchors the volume base while Defined Contribution gains share at the steepest rate.
Investment Strategy:
Cost tiers stratify sharply across these mandates, with growth strategies commanding premium active management fees and conservative approaches squeezing provider margins toward passive replication.
- Growth:Maximize capital appreciation through elevated equity and alternatives exposure, targeting younger cohorts with multi-decade accumulation horizons. Master trust default funds deploy these frameworks for auto-enrolled members under age 40.
- Income:Prioritize yield generation through dividend equities, credit instruments, and real estate distributions. Retirees and near-retirees cluster here, demanding cash flow predictability that infrastructure allocations increasingly satisfy.
- Balanced:Split risk across growth and defensive assets, serving members seeking middle-road volatility profiles without sharp tactical shifts.
- Conservative:Limit downside through high fixed income weightings and liquidity buffers, protecting accumulated pots for members approaching retirement crystallization.
Balanced strategies dominate platform assets under management while Growth allocations expand most quickly among auto-enrolment defaults.
Asset Class:
Supply concentration in UK gilt markets and London-listed equities shapes how trustees construct efficient frontiers, with alternatives pipelines deepening through Mansion House reform incentives.
- Equities:Span UK-listed shares, developed market allocations, and emerging market exposures. Passive tracking dominates institutional flows as fee compression erodes active equity mandates, though unlisted equity channels are widening through productive finance reforms.
- Fixed Income:Encompass government bonds, investment grade credit, and liability-matching gilt portfolios. Defined benefit schemes anchor demand here, using LDI derivatives to hedge interest rate and inflation sensitivity.
- Real Estate:Capture direct property holdings and REIT exposures, generating inflation-linked income streams that match long-dated pension liabilities.
- Alternatives:Absorb infrastructure, private credit, hedge funds, and natural resources. The Pensions Regulator's guidance on illiquidity risk management shapes how trustees scale these allocations within prudent parameters.
Fixed Income underpins liability-driven structures while Alternatives climb the fastest as trustees chase yield in low-gilt environments.
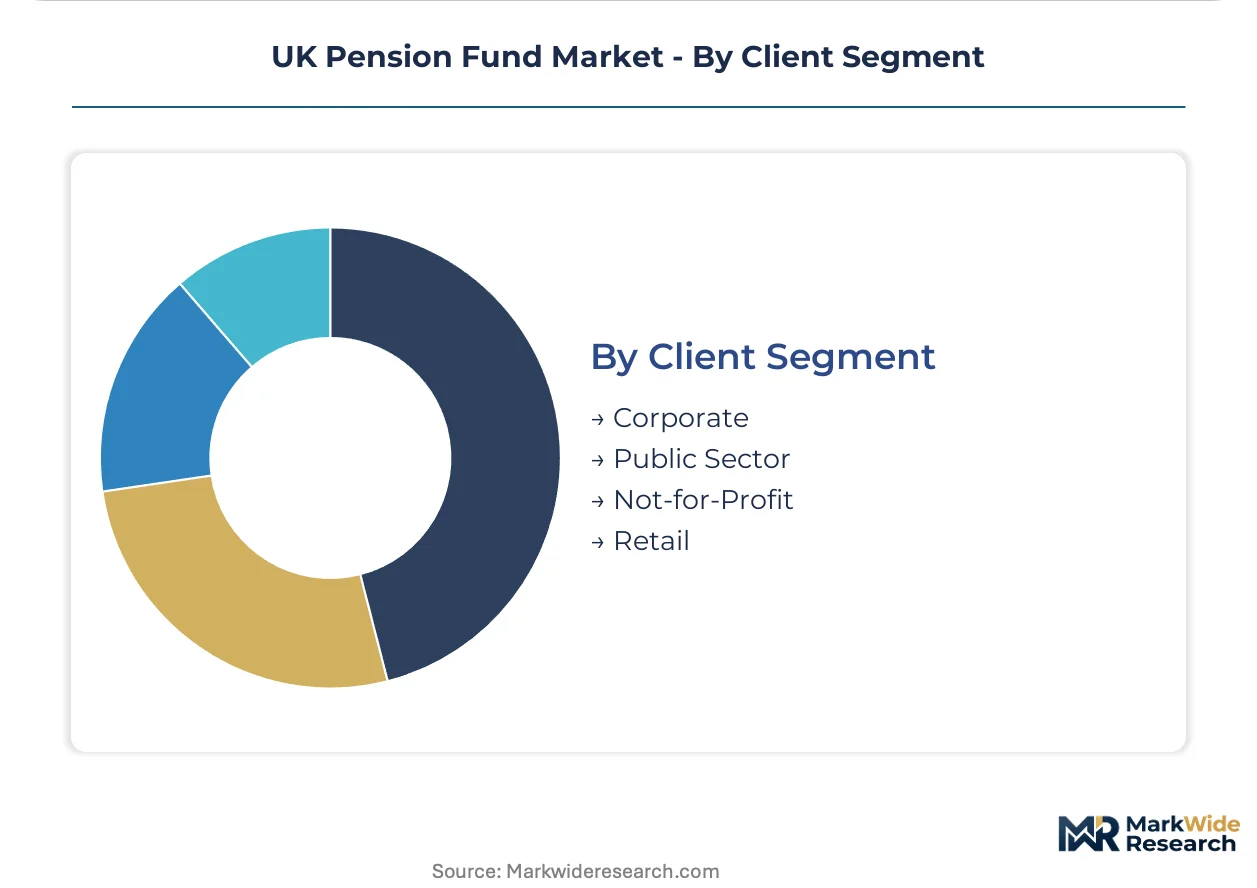
Client Segment:
Maturity gradients separate these customer types, with public sector schemes exhibiting stable membership pipelines and retail platforms facing acute customer acquisition cost pressures.
- Corporate:Span FTSE-listed multinationals, mid-cap employers, and small enterprises navigating auto-enrolment duties. Single-employer trust closures are accelerating as sponsors migrate to master trusts to offload governance burdens.
- Public Sector:Encompass civil service, NHS, teacher, and local government arrangements backed by statutory employer guarantees. These schemes exhibit limited portability and stable contribution flows, though unfunded pay-as-you-go elements create intergenerational fiscal pressures.
- Not-for-Profit:Cover charitable trusts, social housing providers, and membership organizations with constrained administrative resources favoring outsourced master trust solutions.
- Retail:Capture self-invested personal pensions and stakeholder products marketed directly to consumers. Platform competition here centers on app-based user experience and ESG screening tools that younger savers prioritize.
Corporate sponsors anchor the volume base while Retail platforms gain share at the steepest rate through digital distribution expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England concentrates the bulk of UK pension fund assets under management, while Scotland and Wales exhibit distinct regulatory adaptations and industrial clustering patterns that differentiate their operational approaches from London-centric master trust platforms.
London and Southeast England
The Department for Work and Pensions operates from Westminster, shaping auto-enrolment policy that channels millions of workers into default funds. The Pensions Regulator enforces the single code of practice from offices in Brighton and London. Canary Wharf hosts the headquarters of Nest Corporation and multiple master trust administrators, creating a dense cluster of pension technology and governance expertise.
Scotland
Edinburgh anchors Scottish pension administration with concentrated expertise in defined benefit wind-down and buyout execution. The Scottish Government's financial services strategy supports fintech innovation in pension dashboards and member engagement tools. Glasgow complements this cluster with back-office operations and customer service centers serving UK-wide master trust platforms.
Midlands
Birmingham and the wider West Midlands region host manufacturing sector legacy defined benefit schemes grappling with gilt yield volatility and sponsor covenant pressure. The Pensions Protection Fund maintains operational presence in the region, administering compensation for failed schemes. Solihull and Coventry house specialist actuarial consultancies serving mid-cap corporate sponsors.
North England
Manchester and Leeds have emerged as alternative financial centers attracting pension fund administrators seeking lower operational costs than London. The Northern Powerhouse initiative has drawn master trust back-office functions to the region. Sheffield and Newcastle retain substantial local government pension scheme assets with distinctive investment pooling arrangements.
Wales
Cardiff hosts the Welsh Government's financial services division, which coordinates with UK-wide regulators on pension policy implementation. The region exhibits higher concentrations of not-for-profit and social housing sector employers utilizing outsourced master trust solutions. Swansea and Newport support administrative functions for UK-wide pension platforms.
UK Pension Fund Market Competitive Landscape
Capability concentration sits with insurance-integrated platforms; scale advantage sits with government-backed and cost-optimized challengers. The market exhibits tiered structure with three discernible player archetypes: insurance-affiliated master trusts leveraging integrated balance sheets, independent cost-competitive platforms, and single-employer legacy schemes transitioning to buyout. Consolidation accelerates through scheme buyouts and master trust acquisitions. Fee compression forces operational scale investments and technology platform unification.
Within the government-mandated tier, Nest Corporation occupies a foundational position as the auto-enrolment default for millions of workers. Among insurance-integrated providers, Legal & General Mastertrust and Aviva Master Trust exemplify the convergence of pension administration with broader financial services capabilities. The People's Pension represents the independent cost-competitive archetype, anchoring market pressure on basis-point pricing across the master trust segment.
| Leading Market Players |
|---|
| Nest Corporation |
| Universities Superannuation Scheme |
| BT Pension Scheme |
| Electricity Supply Pension Scheme |
| Aviva Master Trust |
| Legal & General Mastertrust |
| The People's Pension |
| Scottish Widows Master Trust |
| Local Government Pension Fund |
| Others |
Pricing and Supply Chain Analysis
London and Southeast England host the densest concentration of master trust administration capacity, where operational scale at Nest Corporation and Legal & General Mastertrust translates into sustained pricing power over smaller regional providers.
Pricing Analysis
Long-term fiduciary management contracts dominate trustee-sponsor relationships, with fee schedules anchored to basis-point charges on assets under administration rather than performance benchmarks. Price differentiation rests on governance bundling depth and technology platform sophistication, where integrated insurance-pension platforms command premium tiers over standalone administrators. Cost compression intensifies as The People's Pension and Nest Corporation compete on single-digit basis-point pricing, squeezing mid-tier master trust margins. Small and medium employers exhibit acute price sensitivity, driving consolidation toward scale-efficient providers.
Supply Chain Analysis
Upstream talent pipelines from Edinburgh and Glasgow feed actuarial and investment advisory capacity into UK-wide pension operations. Custody and fund administration services draw from Ireland and Luxembourg, while technology platform development concentrates in London fintech clusters. Single-source vulnerability persists in liability-driven investment derivative execution, where concentrated gilt market-making capacity creates systemic dependency. Distribution runs through employer-sponsored enrollment channels, with auto-enrolment mandates channeling flows into government-backed and cost-optimized default funds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK pension fund market exhibits cyclical recovery characteristics as gilt yield stabilization and auto-enrolment threshold expansion restore sponsor confidence and member accumulation momentum.
For Market Incumbents: Entrench governance scale advantages through accelerated technology platform unification and trustee board consolidation services. Defend against fee compression by deepening insurance-pension integration and capturing buyout execution mandates from shrinking defined benefit schemes. Vertical integration into member engagement technology preserves margin through proprietary dashboard and retirement planning tool deployment. For New Entrants and Emerging Players: Establish a beachhead in collective defined contribution administration as the Pensions Schemes Act 2021 structures mature. Target not-for-profit and social housing sector employers in Wales and Northern England, where outsourced master trust penetration remains below corporate sector levels. Pursue partnership-first go-to-market models with existing actuarial consultancies to bypass direct trust acquisition costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with demonstrated auto-enrolment default fund scale and regulatory compliance automation capabilities. Long-term viability hinges on capturing consolidation-driven inflows from single-employer scheme closures. Monitor gilt yield volatility as the primary inflection indicator for defined benefit buyout transaction velocity and insurance consolidator acquisition appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Master Trust Platform Consolidation | Operational scale investments at Nest Corporation and Legal & General compress competitor margins through unified data architectures. |
| Collective Defined Contribution Launch | Risk-sharing structures enabled by the Pensions Schemes Act 2021 blend portability with stability for technology sector employers. |
| Infrastructure Asset Allocation Expansion | Mansion House reforms channel retirement capital toward unlisted equity and productive finance mandates. |
| Digital Member Engagement Investment | Mobile-first interfaces and retirement income calculators mirror retail banking experiences for auto-enrolled cohorts. |
| Defined Benefit Buyout Execution | Insurance consolidators acquire legacy scheme liabilities, transferring regulatory burden from corporate sponsors. |
Research Methodology
A spread of perspectives from master trust chief operating officers, pension scheme trustees, actuarial consultants, and Department for Work and Pensions policy officials converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against The Pensions Regulator enforcement data, Financial Conduct Authority conduct reports, and master trust annual returns. Bottom-up asset flow modeling and top-down regulatory impact assessment provided triangulation across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with enrollment growth projections tested against master trust capacity expansion and sponsor migration patterns from single-employer trusts. Segmentation dimensions modeled encompass fund type, investment strategy, asset class allocation, and client segment across the projection horizon. CAGRs derived from historical flow trajectories adjusted for auto-enrolment threshold policy and gilt yield trajectory assumptions.
Sensitivities concentrate around regulatory enforcement intensity, longevity assumption revisions, and gilt market volatility as forecast revision triggers. Cross-checking against The Pensions Regulator's annual defined benefit funding statement and Office for National Statistics mortality projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market