
 Europe Wealth Management Market | 2026-2036
Europe Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wealth Management Market Foresight
Swiss private banking capacity is repositioning around digital onboarding and ESG-integrated mandates. UBS Group AG leverages its dual headquarters structure to anchor cross-border flows between Zurich and London. BNP Paribas Wealth Management differentiates through open-architecture fund platforms across Belgium and France. HSBC Holdings competes via its Channel Islands and Luxembourg booking centers for UK expatriate capital.
Europe wealth management denotes the professional allocation, preservation, and transfer of investable assets across jurisdictions, governed by MiFID II suitability protocols and AIFMD transparency requirements. Its primary commercial purpose centers on optimizing after-tax, after-fee returns while ensuring regulatory compliance across multiple domiciles. Portfolio Management services dominate fee income pools, while Alternative asset classes represent the fastest-growing allocation channel. Active Management strategies retain margin superiority among Ultra High Net Worth Individuals, though Passive Management is displacing traditional mandates in the Affluent segment.
ESMA enforces product governance standards that shape fund distribution access across the EU27, while the FCA in London maintains prudential rules for UK-resident international clients. The EU Green Deal's taxonomy requirements are forcing disclosure upgrades across all marketed strategies. Stakeholders must monitor whether CSRD reporting obligations will extend wealth manager fiduciary duties to financed emissions.
Market Dynamics
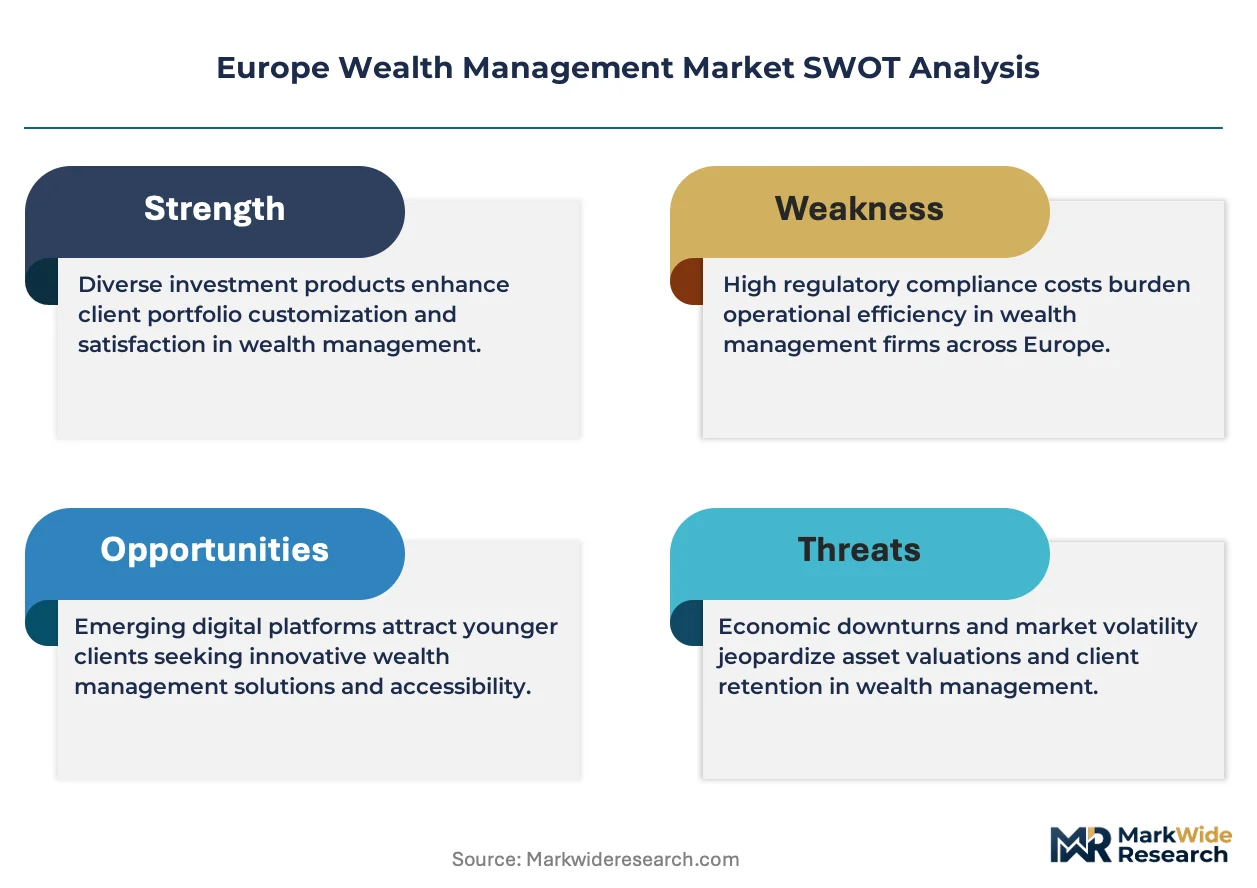
The EU Green Deal is forcing a wholesale reconfiguration of portfolio construction across European wealth managers, with ESG-integrated mandates now displacing traditional risk-return frameworks as the primary client acquisition tool.
Growth Catalysts
- CSRD Disclosure Mandates:The EU's Corporate Sustainability Reporting Directive is expanding wealth manager fiduciary duties to financed emissions, creating new advisory revenue streams around carbon accounting and transition planning.
- Geneva-Zurich-Liechtenstein Corridor:Cross-border capital flows through this Alpine cluster are deepening as Ultra High Net Worth Individuals consolidate multi-jurisdictional holdings under unified booking structures.
- Digital Onboarding Infrastructure:Biometric KYC and remote signature frameworks are compressing client acquisition timelines from weeks to days across Swiss and Luxembourg domiciles.
Market Restraints
- MiFID II Suitability Protocols:The EU's product governance standards impose documentation burdens that elevate compliance costs disproportionately for sub-$50 million advisory practices.
- Passive Management Displacement:ETF platforms and robo-advisory substitutes are eroding fee margins on traditional active mandates among the Affluent segment.
- Luxembourg Booking Concentration:Over-reliance on this single domicile for UCITS fund structures creates systemic vulnerability to regulatory arbitrage shifts or tax treaty renegotiations.
Strategic Opportunities
- Poland and Czech Republic:These Central European markets remain underpenetrated by cross-border private banking, with emerging entrepreneur wealth accumulating faster than local advisory capacity.
- EU Green Deal Taxonomy:The sustainable finance classification system offers first-mover advantages to wealth managers who build proprietary green bond and transition equity screening tools.
- Open-Architecture Convergence:The integration of blockchain settlement rails with traditional custody infrastructure is enabling real-time fractional ownership of alternative assets.
Industry Challenges
- ESG Data Analyst Scarcity:The specialized skill set required to validate sustainability claims and model climate scenario risks commands premium compensation that compresses margin at smaller practices.
- Legacy Core Banking Integration:Wealth managers face multi-year migration timelines to unify client data across siloed custody, portfolio accounting, and CRM platforms accumulated through decades of acquisition.
- AIFMD Transparency Timelines:The Alternative Investment Fund Managers Directive's reporting deadlines create operational bottlenecks during quarterly close periods, particularly for managers with illiquid private market allocations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wealth Management Market |
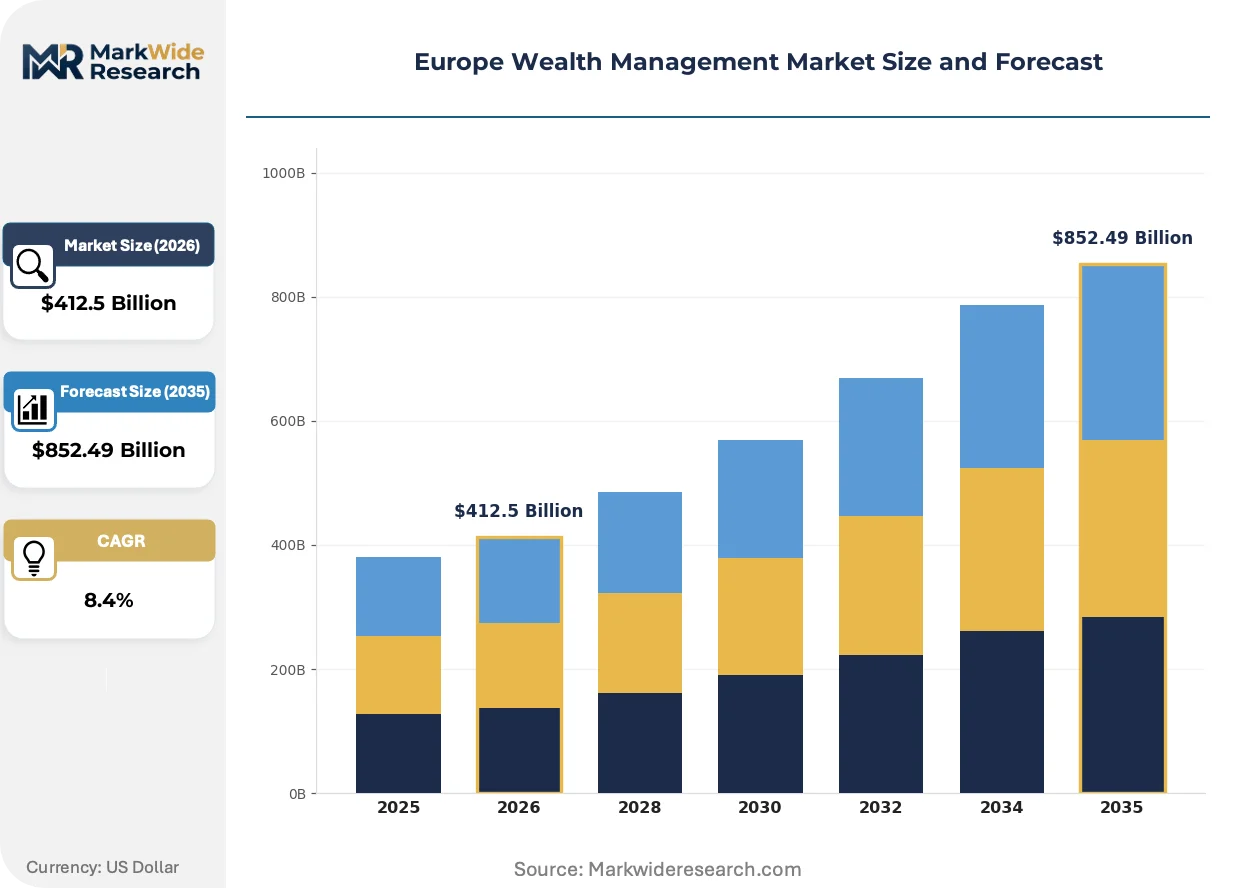
| Market Size in 2026 | $412.5 Billion |
| Market Size in 2035 | $852.49 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Investment Advisory, Portfolio Management, Tax Planning, Estate Planning Client Type: Affluent Individuals, High Net Worth Individuals, Ultra High Net Worth Individuals, Institutions Investment Strategy: Active Management, Passive Management, Growth Investing, Value Investing Asset Class: Equities, Fixed Income, Real Estate, Alternatives |
| Companies Covered | UBS Group AG, JPMorgan Chase & Co., BNP Paribas Wealth Management, HSBC Holdings, Allianz SE, AXA Group, Amundi SA, Barclays PLC, Intesa Sanpaolo Private Banking Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wealth Management Market Shifts & Advancements
Artificial intelligence is compressing the cost structure of personalized portfolio construction while regulatory technology is automating compliance workflows that previously required manual oversight across multiple jurisdictions.
Natural language processing engines are automating the extraction and synthesis of unstructured ESG data from corporate disclosures, sustainability reports, and news feeds. Swiss private banks are deploying these tools to pre-screen investment universes before analyst review, reducing research hours per mandate by half. The structural consequence is a compression of minimum viable account sizes, extending bespoke advisory services down into the mass-affluent tier previously served only by standardized products.
The EU Green Deal's taxonomy requirements are mandating granular disclosure of portfolio alignment with six environmental objectives, including climate adaptation and circular economy transition. Asset managers must now report the percentage of underlying revenues derived from taxonomy-eligible activities, forcing upgrades to data vendor contracts and internal classification frameworks. Strategies marketed as "sustainable" or "ESG" face the highest scrutiny, with national regulators in France and Germany already issuing deficiency letters for vague marketing claims.
Family offices and entrepreneurial wealth holders are unbundling execution, custody, and advisory functions that were historically packaged under single private banking relationships. This disintermediation favors specialized boutiques for alternative asset sourcing and independent platforms for custody, with relationship pricing power migrating toward the entity controlling capital deployment decisions. The Benelux corridor exhibits this pattern most acutely, where multi-generational family wealth has cultivated deep networks of single-family offices resistant to consolidated banking propositions.
Europe Wealth Management Market Segmentation
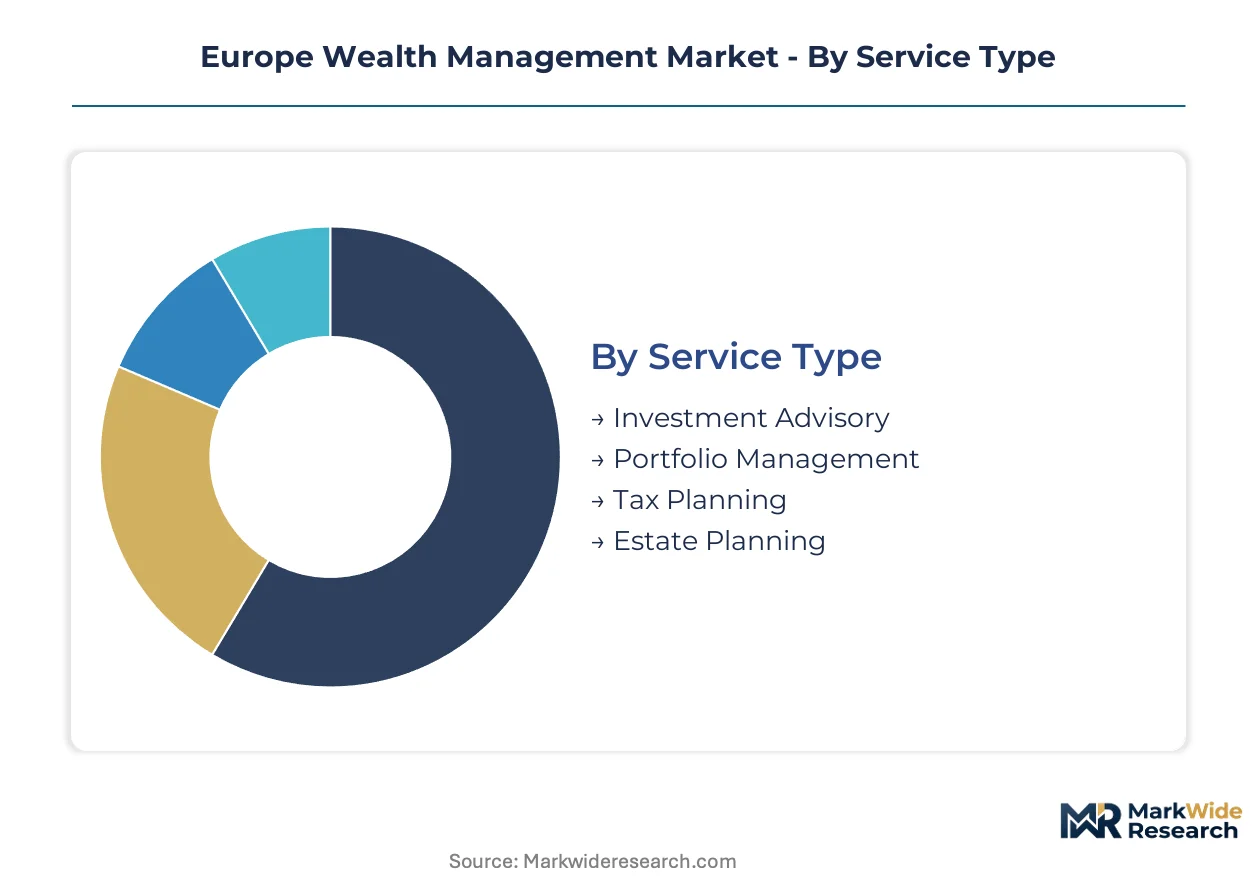
Segmentation in European wealth management reveals distinct service economics across client tiers and asset classes. MiFID II suitability protocols and the EU Green Deal taxonomy are forcing specialization that fragments traditional full-service models. Understanding these divides exposes where margin pools concentrate and where regulatory arbitrage creates structural opportunities.
Service Type:
Service differentiation tracks the depth of fiduciary obligation and the complexity of cross-border coordination required.
- Investment Advisory:Discrete recommendations on asset allocation and security selection without discretionary trading authority. Demand concentrates among German and French affluent households seeking MiFID II-compliant guidance on ESG-integrated fund selection.
- Portfolio Management:Discretionary mandates where the wealth manager executes trades within agreed investment policies. Swiss private banks in Geneva and Zurich capture the deepest share of ultra-high-net-worth mandates here, driven by multi-jurisdictional tax reporting requirements.
- Tax Planning:Structuring of holdings across domiciles to optimize after-fee, after-tax returns. Luxembourg booking centers anchor demand as families navigate cross-border inheritance regimes.
- Estate Planning:Intergenerational wealth transfer through trusts, foundations, and succession vehicles. Liechtenstein's foundation law attracts Central European entrepreneurial families consolidating multi-generational holdings.
Portfolio Management leads volumes today; Investment Advisory is gaining share fastest as digital platforms compress minimum account thresholds.
Client Type:
Client stratification follows liquid asset thresholds that determine service intensity and pricing power.
- Affluent Individuals:Households with investable assets below high-net-worth thresholds, typically served through standardized fund platforms and digital onboarding. Robo-advisory substitutes from Nordic fintechs are eroding traditional branch-based acquisition costs in this tier.
- High Net Worth Individuals:Clients requiring dedicated relationship managers and open-architecture product access. Belgian and Dutch private banks compete here through ESG-integrated discretionary mandates aligned with EU Green Deal taxonomy requirements.
- Ultra High Net Worth Individuals:Family offices and multi-generational wealth holders demanding bespoke alternative asset sourcing and cross-border structuring. The Geneva-Zurich-Liechtenstein corridor captures the densest concentration of these mandates as individuals consolidate fragmented holdings.
- Institutions:Pension funds, endowments, and corporate treasuries outsourcing investment governance. Luxembourg's UCITS and AIFM frameworks attract these entities seeking regulated fund structures with passporting rights across EU27.
High Net Worth Individuals anchor fee income today; Ultra High Net Worth Individuals show the steepest expansion trajectory as entrepreneur wealth concentrates in Alpine jurisdictions.
Investment Strategy:
Strategy selection reflects the tension between fee generation and performance accountability under tightening disclosure regimes.
- Active Management:Discretionary security selection aiming to outperform benchmarks through fundamental research or quantitative signals. Ultra-high-net-worth mandates in Switzerland retain active strategies despite fee pressure, driven by access to private market co-investments.
- Passive Management:Index-tracking vehicles and ETF-based implementation minimizing cost drag. French and German affluent segments are migrating here fastest as CSRD disclosure requirements raise due diligence burdens on active managers.
- Growth Investing:Concentrated exposure to earnings-expanding companies, often in technology and healthcare sectors. Nordic wealth managers specialize here, leveraging regional venture capital networks for deal flow.
- Value Investing:Disciplined acquisition of securities trading below intrinsic worth, often in cyclical or out-of-favor industries. Italian family offices maintain structural overweight here, reflecting long-term holding periods and dividend-focused income needs.
Active Management retains margin superiority today; Passive Management is climbing the fastest as platform economics reshape the affluent tier.
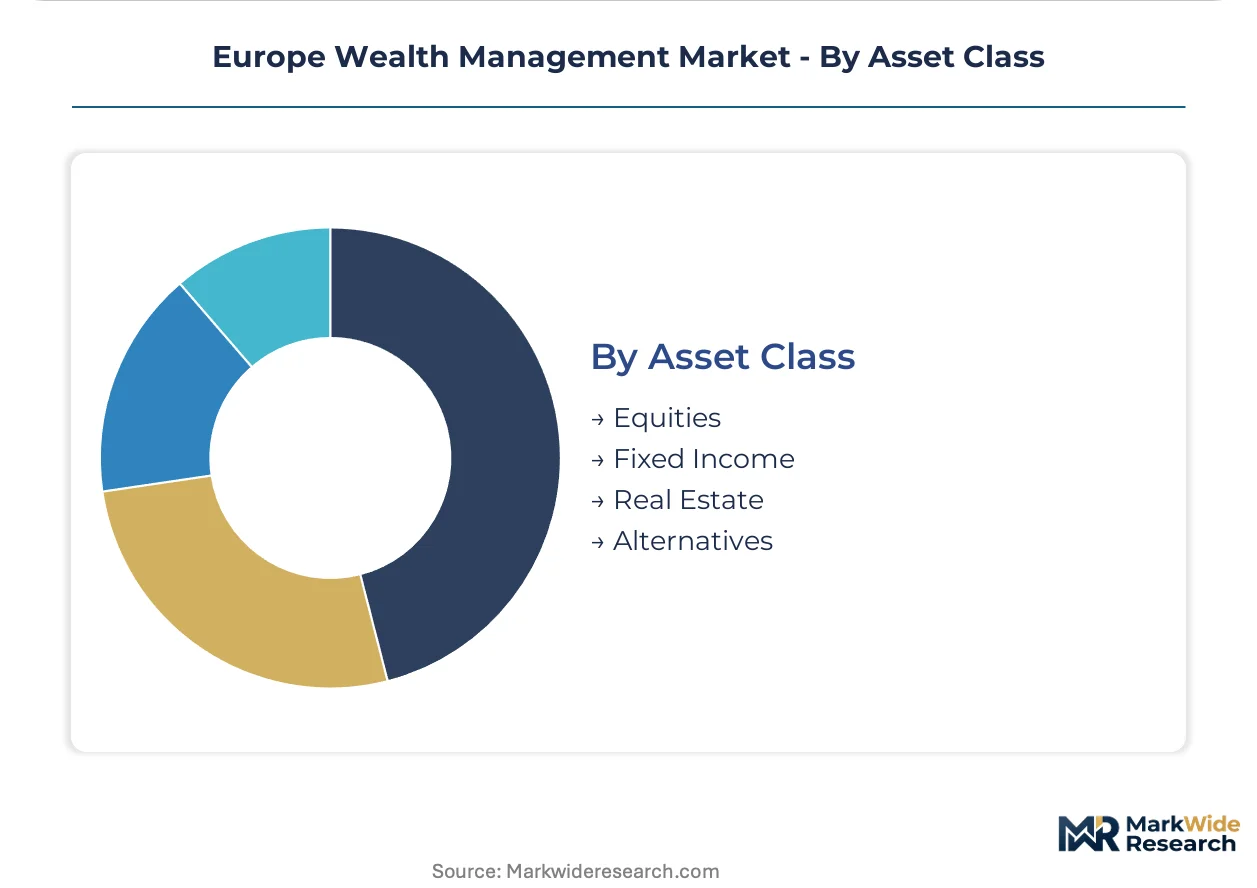
Asset Class:
Asset allocation patterns reveal how the EU Green Deal and AIFMD transparency requirements are redistributing capital across liquidity spectrums.
- Equities:Public company shares across developed and emerging markets, now subject to granular sustainability disclosure under CSRD. Benelux wealth managers are rebuilding research infrastructure to validate taxonomy alignment claims.
- Fixed Income:Sovereign, corporate, and structured debt instruments. Green bond issuance from German and French corporates is capturing allocations previously directed toward conventional credit.
- Real Estate:Direct property holdings and REIT exposures, favored for inflation hedging and depreciation benefits. Swiss cantonal banks dominate domestic commercial real estate advisory for local high-net-worth individuals.
- Alternatives:Private equity, infrastructure, hedge funds, and commodities accessed through specialized funds or co-investment structures. Luxembourg's AIFM framework and Liechtenstein's limited partnership structures are deepening this allocation channel for ultra-high-net-worth families seeking yield outside public markets.
Equities dominate booked assets today; Alternatives are expanding most quickly as families unbundle custody from capital deployment decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing wealth management capacity across Europe as cost-of-compliance gaps widen between jurisdictions. Firms migrate advisory infrastructure toward domiciles with streamlined fund authorization and lighter sustainability disclosure burdens.
Switzerland
Geneva and Zurich anchor the densest concentration of ultra-high-net-worth mandates in Europe. Swissmedic and FINMA maintain prudential frameworks that accommodate cross-border client acquisition without full EU membership constraints. The Geneva-Zurich-Liechtenstein corridor processes the majority of Alpine wealth consolidation as families unify fragmented holdings under unified booking structures.
Luxembourg
UCITS and AIFM fund frameworks attract institutional capital seeking passporting rights across EU27. The country's CSSF regulator enforces AIFMD transparency timelines that create operational bottlenecks for managers with illiquid allocations. Luxembourg City hosts the dominant share of European fund domiciliation as asset managers relocate product infrastructure from London post-Brexit.
Germany
Affluent households in Frankfurt and Munich drive demand for MiFID II-compliant ESG-integrated fund selection. BaFin enforces product governance standards that elevate documentation burdens for advisory practices serving sub-high-net-worth segments. The KBA and federal financial supervisory structure shapes custody and reporting requirements for cross-border mandates booked through Frankfurt.
France
Paris-based private banks compete through open-architecture platforms aligned with EU Green Deal taxonomy requirements. ANSM and AMF regulators have issued deficiency letters to asset managers marketing vague sustainability claims. The Île-de-France region concentrates the majority of French wealth management capacity as BNP Paribas and domestic institutions anchor discretionary mandate growth.
United Kingdom
London retains execution and advisory functions for international clients despite post-Brexit passporting limitations. The FCA maintains prudential rules for UK-resident international clients that diverge from EU27 MiFID II protocols. Channel Islands booking centers capture UK expatriate capital as HSBC and competing institutions restructure cross-border service delivery.
Europe Wealth Management Market Competitive Landscape
Swiss private banks anchor one tier; French and British universal banks hold adjacent positions through integrated wealth platforms. Market structure concentrates around three to five dominant institutions with scale advantages in cross-border compliance infrastructure, while mid-tier specialists compete through niche ESG or alternative asset capabilities. Strategic archetypes include Alpine-domiciled private banks, universal bank wealth divisions, and independent asset managers with open-architecture fund access. Competitive moves center on digital onboarding compression and ESG data infrastructure acquisition.
Among Swiss-domiciled institutions, UBS Group AG exemplifies the universal-private hybrid archetype through its dual headquarters structure anchoring flows between Zurich and London. BNP Paribas Wealth Management represents the integrated European bank model with fund platform specialization across Belgium and France. HSBC Holdings occupies a position serving UK expatriate segments through Channel Islands and Luxembourg booking center infrastructure.
| Leading Market Players |
|---|
| UBS Group AG |
| JPMorgan Chase & Co. |
| BNP Paribas Wealth Management |
| HSBC Holdings |
| Allianz SE |
| AXA Group |
| Amundi SA |
| Barclays PLC |
| Intesa Sanpaolo Private Banking Group |
| Others |
Supply & Pricing Matrix
ESG data analyst concentration in Zurich and Geneva widens pricing-tier spreads as labor-cost differentials between Alpine hubs and secondary European centers compress margins at smaller advisory practices while premium mandates absorb specialist compensation premiums.
Pricing Analysis
Advisor fee layers stratify across discretionary mandate markups, platform access charges, and direct-to-family-office retainers. Three-tier pricing structure across premium, standard, and economy levels separates bespoke UHNW portfolio construction from digital-affluent robo-advisory substitutes. Pricing pressure stems from ETF platform commoditization eroding active management fees. Mass-affluent households exhibit highest price sensitivity; multi-generational family offices show lowest.
Supply Chain Analysis
Portfolio accounting software rests on vendors concentrated in Switzerland, Luxembourg, and the United Kingdom. Core dependencies include custody infrastructure, ESG data feeds, and regulatory reporting engines. Single-source vulnerability concentrates around dominant fund-administration platforms serving UCITS and AIFM structures. Distribution runs through relationship-manager networks anchored in Geneva-Zurich-Liechtenstein corridor booking centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe wealth management functions as a stable compounder where recurring advisory fees and long-duration client relationships generate predictable revenue streams through regulatory and macroeconomic cycles.
For Market Incumbents: Acquire carbon-accounting capabilities to capture CSRD-mandated advisory revenue before specialist boutiques consolidate this skill set. Build proprietary ESG-screening infrastructure to defend against open-architecture fund platforms eroding discretionary mandate pricing power. Deepen Zurich and Geneva talent pools to offset analyst scarcity compressing margins at smaller practices.
For New Entrants and Emerging Players: Polish and Czech entrepreneur families remain underserved by cross-border private banking despite accelerating wealth accumulation. Digital-native onboarding infrastructure offers entry path into mass-affluent tier where robo-advisory substitutes have displaced traditional branch acquisition. Target ESG-integrated discretionary mandates in Central European markets where local advisory capacity lags wealth creation.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Swiss private banks with legacy core banking integration burdens and fragmented client data architectures. Long-term viability hinges on successful technology modernization and retention of relationship-manager talent through generational transition. Monitor CSRD implementation timelines as inflection indicator for advisory revenue expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ESG Data Infrastructure Acquisition | Proprietary carbon-accounting tools capture CSRD-mandated advisory fees before competitor consolidation. |
| Digital Onboarding Platform Deployment | Biometric KYC compression reduces client acquisition timelines from weeks to days across Swiss domiciles. |
| Alternative Asset Sourcing Capability | Private market co-investment access retains UHNW active management mandates despite ETF fee pressure. |
| Cross-Border Booking Center Expansion | Luxembourg and Channel Islands infrastructure captures UK expatriate capital post-Brexit. |
| Open-Architecture Fund Platform Integration | Third-party product access defends against client unbundling of custody and advisory functions. |
Research Methodology
Coverage spans Switzerland, Luxembourg, Germany, France, and the United Kingdom, with primary inputs from each jurisdiction combining interviews with private banking relationship managers, ESG data specialists, regulatory compliance officers, and family office executives alongside secondary validation from FINMA and CSSF regulatory filings, UCITS fund prospectuses, and AIFMD transparency reports. Bottom-up client-segment sizing triangulates against top-down market value estimates.
Granularity-level modeling addresses service type, client tier, investment strategy, and asset class dimensions across the projection horizon. CAGRs derive from segment-level growth rate blending anchored to AUM flow projections and fee compression assumptions. Forecast inputs incorporate MiFID II suitability protocol evolution and EU Green Deal taxonomy implementation timelines.
Inputs from regulatory disclosure databases and fund administrator records were available through the study window; gaps in private family office AUM reporting introduce uncertainty bands around ultra-high-net-worth segment sizing. Forecasts reflect documented assumptions regarding CSRD adoption velocity and digital platform substitution rates. A small set of triggers—MiFID III proposal timelines, Swiss-EU financial services agreement negotiations, and Luxembourg tax treaty renegotiations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Digital Wealth Management Market