
 Family Office Software for Financial Management Market | 2026-2036
Family Office Software for Financial Management Market Size, Share, and Industry Trends Forecast 2026-2036
Family Office Software for Financial Management Market Insights
Single-source vendor dependency is shifting toward multi-platform ecosystems across family office technology stacks. Addepar leverages open architecture to anchor institutional-caliber portfolio analytics for complex asset structures. FundCount competes through integrated partnership accounting and general ledger consolidation. Eton Solutions specializes in single-family office workflow automation, differentiating through entity management depth.
Family office software for financial management denotes integrated technology platforms that aggregate illiquid and liquid holdings, automate consolidated reporting, and enforce compliance workflows across multi-entity structures. These systems typically support real-time data feeds from custodians, alternative investment administrators, and private bank portals while calculating performance metrics across custom benchmark hierarchies. Cloud-based deployment leads solution delivery, though private cloud configurations gain traction among ultra-high-net-worth families prioritizing data sovereignty. Portfolio management functionality captures the largest margin pool given its centrality to investment decision-making, while risk analytics represents the fastest-expanding module as geopolitical volatility intensifies stress-testing requirements.
SEC oversight of registered investment advisers shapes product roadmaps through Form PF and ADV filing automation requirements, while GDPR and Swiss Federal Act on Data Protection constrain cross-border data architecture choices for European and Swiss deployments. The IRS partnership audit rules and OECD Common Reporting Standard further complicate tax optimization module design, forcing vendors to maintain jurisdictional compliance layers. Stakeholders must evaluate whether vendor API ecosystems can accommodate emerging tokenized asset classes and decentralized finance reporting standards without core platform replacement.
Market Dynamics
Cloud-native architectures are overtaking legacy on-premise deployments as multi-generational family offices demand real-time portfolio visibility across dispersed custodian networks.
Growth Catalysts
- SEC Form PF Automation:Registered investment advisers face escalating filing complexity for private fund reporting, forcing technology refreshes that embed regulatory logic directly into portfolio accounting workflows.
- Tokenized Asset Integration:Family offices holding cryptocurrency and digital securities require API-first platforms capable of ingesting blockchain-native position data alongside traditional custody feeds.
- Singapore Wealth Migration:Ultra-high-net-worth families relocating to the city-state's tax-efficient jurisdiction generate concentrated demand for multi-currency, multi-entity reporting infrastructure.
Market Restraints
- Custodian Data Fragmentation:Alternative investment administrators lack standardized data formats, forcing vendors to maintain expensive bilateral integration layers that compress implementation margins.
- Swiss Data Sovereignty Requirements:The Swiss Federal Act on Data Protection mandates local data residency, complicating cloud deployment economics for vendors serving single-family offices in Geneva and Zurich.
- Specialized Talent Scarcity:Implementation teams require simultaneous expertise in partnership tax accounting, software engineering, and family governance consulting, creating a bottleneck in deployment velocity.
Strategic Opportunities
- Artificial Intelligence Convergence:Natural language processing and predictive analytics are merging with traditional portfolio reporting to automate narrative generation for investment committee presentations.
- Next-Generation Succession Planning:Millennial family members demand mobile-native interfaces and ESG scoring modules, opening white space for user-experience-focused entrants.
- OECD Common Reporting Standard Expansion:Automatic exchange of financial account information is extending to additional jurisdictions, creating mandatory upgrade cycles for tax optimization modules.
Industry Challenges
- Intergenerational User Design Tension:Platform interfaces must simultaneously satisfy patriarchs accustomed to printed reports and digital-native successors expecting real-time dashboards, complicating product roadmaps.
- Entity Structure Complexity:Multi-jurisdictional trust and holding company hierarchies require dynamic consolidation engines that adapt to changing legal structures without reimplementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Family Office Software for Financial Management Market |
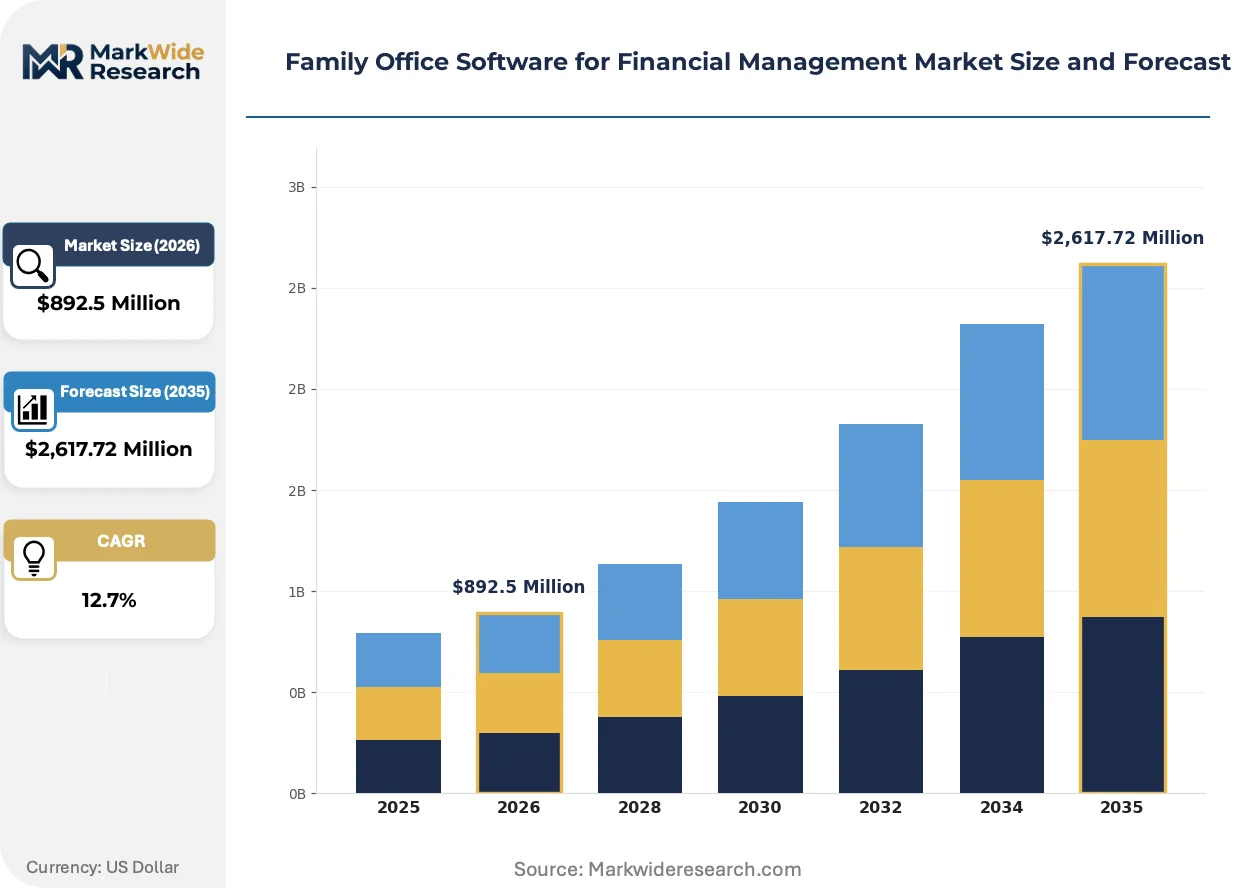
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $2,617.72 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Portfolio Management, Risk Analytics, Reporting Tools, Compliance Management, Wealth Planning, Tax Optimization Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud End User/Industry Vertical: High Net Worth Individuals, Family Trusts, Private Wealth Advisors, Asset Managers Investment Strategy: Equity, Fixed Income, Alternative Investments, Real Assets, Venture Capital, Hedge Funds |
| Companies Covered | FundCount, Eton Solutions, Masttro, Addepar, Asset Vantage, Asora, Black Diamond, Archway, Advent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Family Office Software for Financial Management Market Trends and Innovations
Artificial intelligence and open banking protocols are compressing the latency between transaction execution and consolidated reporting, reshaping how family offices monitor illiquid alternative investments.
API-first data aggregation is overtaking screen-scraping and manual file uploads as the dominant integration methodology for alternative investment administrators. Family offices holding private equity, venture capital, and real estate funds demand direct system-to-system connectivity that eliminates reconciliation delays. This shift is compressing the implementation timeline for new custodian relationships from quarters to weeks.
The EU Digital Operational Resilience Act is mandating stringent third-party risk management for financial entities, including family offices with registered investment adviser status. Vendors must now demonstrate business continuity planning and penetration testing protocols to maintain compliance. European deployments are responding by prioritizing private cloud configurations with documented failover capabilities.
Subscription-based pricing models are displacing perpetual license arrangements as family offices seek to align technology costs with asset volatility. Multi-family office aggregators and outsourced CIO platforms favor operational expenditure structures that scale with client acquisition. This pattern is most visible in the United States, where outsourced family office services are consolidating vendor relationships across multiple underlying families.
Family Office Software for Financial Management Market Segmentation
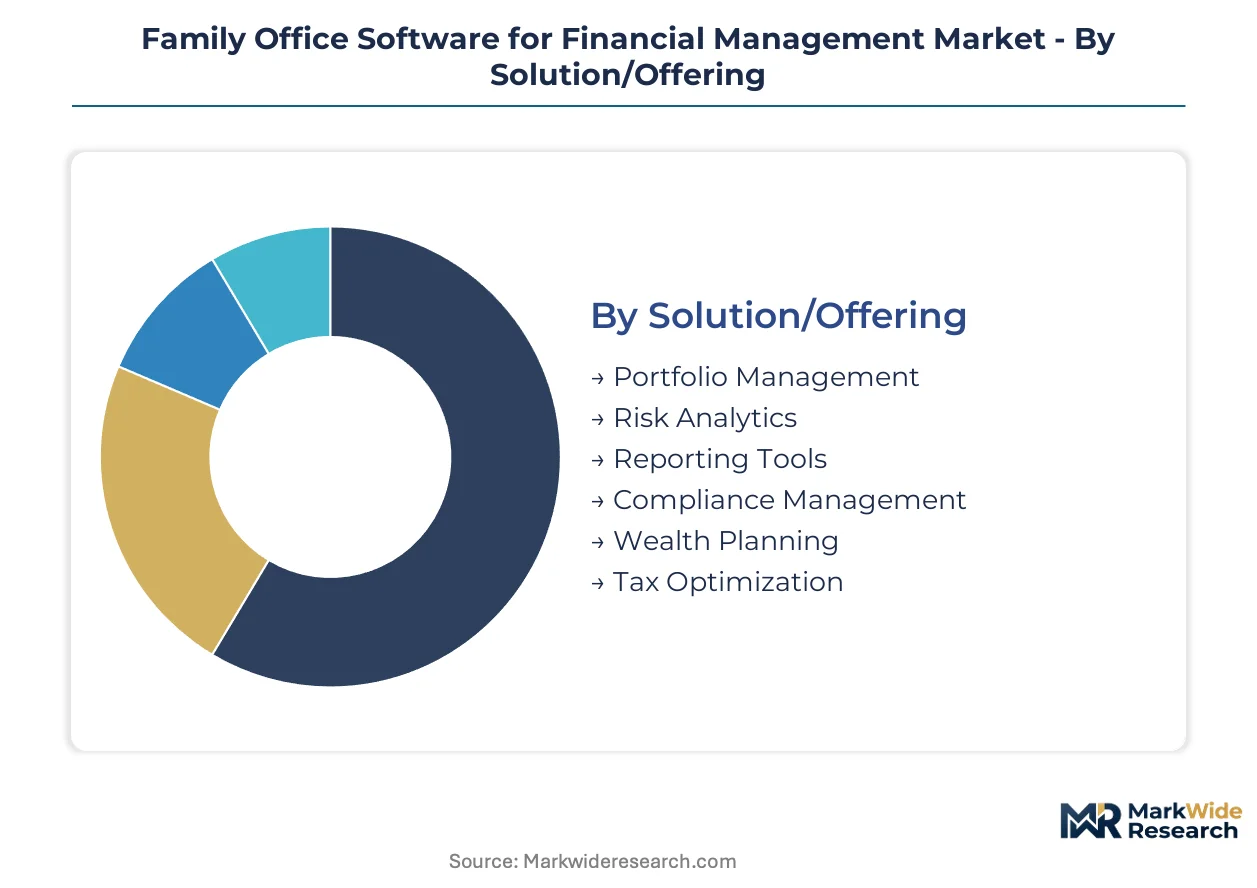
Segmentation in family office software reveals how capital deployment, data sovereignty requirements, and investment complexity drive purchasing decisions across disparate client profiles. Vendors must architect modular platforms that scale from single-family office simplicity to multi-family office operational intensity without core system replacement.
Solution/Offering:
Portfolio Management and Risk Analytics command the highest upfront development capital given their dependency on real-time data infrastructure and quantitative modeling engines.
- Portfolio Management:Centralizes position aggregation across custodians, calculates performance attribution against custom benchmarks, and supports illiquid asset valuation workflows. Demand concentrates among multi-generational family offices in the United States managing diversified alternative investment portfolios, driven by SEC Form PF filing automation requirements.
- Risk Analytics:Delivers stress-testing, scenario modeling, and exposure aggregation across currency, counterparty, and geopolitical dimensions. Swiss single-family offices in Geneva and Zurich prioritize these modules as volatility in European energy markets intensifies hedging complexity.
- Reporting Tools:Automates consolidated statement generation across entity hierarchies with customizable narrative templates.
- Compliance Management:Embeds regulatory filing logic for SEC, OECD CRS, and jurisdictional tax authorities.
- Wealth Planning:Supports succession modeling, trust administration, and intergenerational transfer optimization.
- Tax Optimization:Calculates multi-jurisdictional liability exposure and automates cross-border reporting workflows.
Portfolio Management absorbs the bulk of installed capacity; Risk Analytics is expanding most quickly.
Deployment:
Cloud configurations dominate procurement volume among outsourced CIO platforms seeking operational expenditure alignment with client acquisition cycles.
- Cloud-Based:Delivers multi-tenant scalability with automatic updates and elastic compute for batch reporting cycles. Singapore-based family offices migrating from Hong Kong favor public cloud for rapid deployment without local infrastructure investment.
- Private Cloud:Provides dedicated tenant isolation with vendor-managed infrastructure, satisfying Swiss Federal Act on Data Protection residency mandates. Geneva single-family offices with concentrated cryptocurrency holdings select private cloud for enhanced cryptographic key control.
- On-Premise:Retains full hardware ownership within family office premises.
- Hybrid:Segregates sensitive data on-premise while leveraging cloud for non-critical workloads.
- SaaS:Offers subscription pricing with minimal implementation friction for emerging family offices.
Cloud-Based deployments capture the greatest transaction volume; Private Cloud configurations gain share fastest among ultra-high-net-worth segments prioritizing data sovereignty.
End User/Industry Vertical:
Family Trusts generate the most complex implementation requirements given multi-jurisdictional entity layering and beneficiary reporting obligations.
- Family Trusts:Requires dynamic consolidation engines adapting to changing trust structures across Delaware, Cayman Islands, and Swiss domiciles. Demand concentrates in the United States where dynasty trust structures span multiple generations with divergent investment mandates.
- Asset Managers:Needs institutional-caliber analytics with client-facing reporting portals for underlying family office investors. Singapore's growing fund management sector drives adoption as managers establish family office service divisions.
- High Net Worth Individuals:Seeks streamlined platforms with mobile-native interfaces.
- Private Wealth Advisors:Demands multi-client aggregation with segregated data architecture.
Family Trusts absorb the bulk of implementation complexity; Asset Managers are climbing the fastest as outsourced CIO models proliferate.
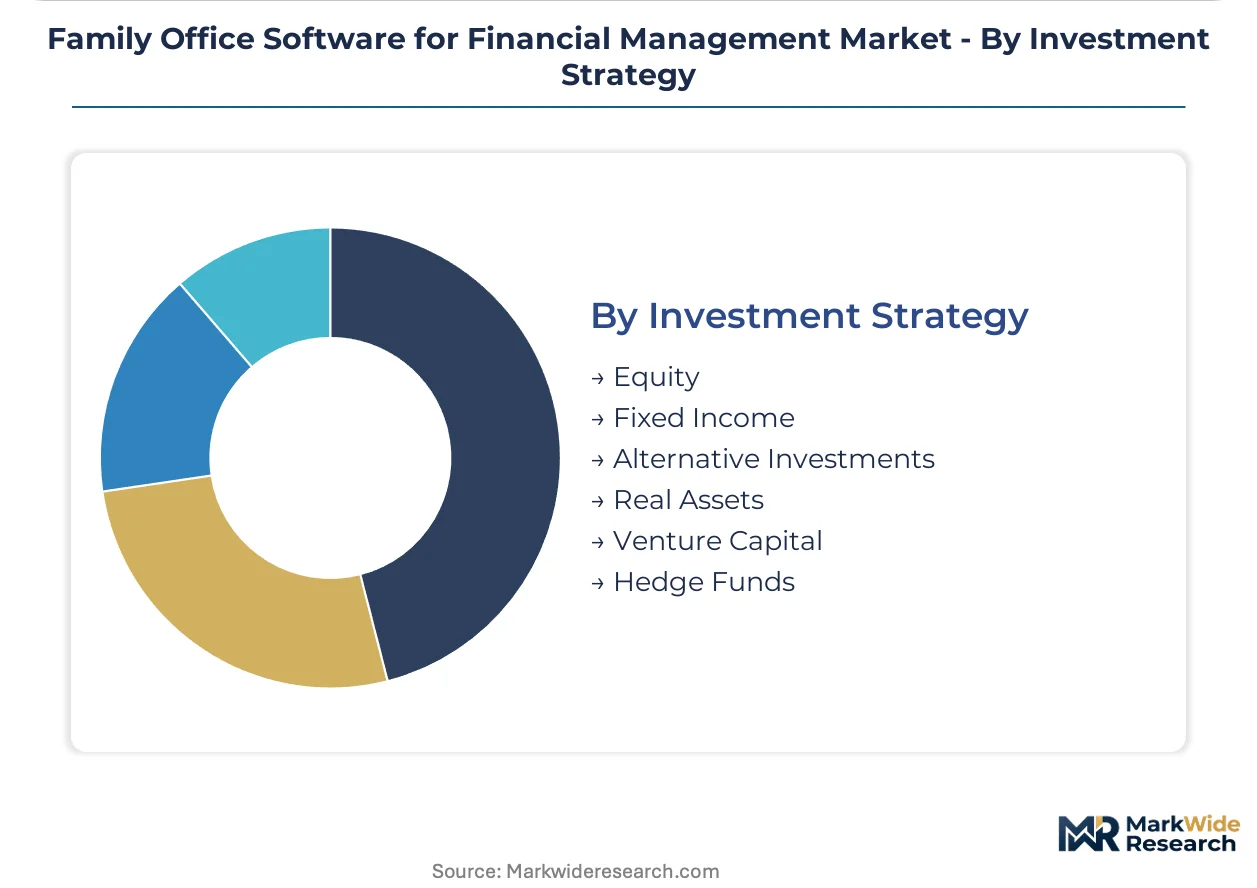
Investment Strategy:
Alternative Investments and Venture Capital impose the steepest integration costs due to non-standardized administrator data formats and illiquidity-adjusted valuation protocols.
- Alternative Investments:Encompasses private equity, infrastructure, and natural resources with bespoke waterfall calculations and capital call forecasting. Family offices in Switzerland holding direct European energy infrastructure stakes drive demand for administrator-agnostic data ingestion.
- Venture Capital:Tracks carried interest allocations, SAFE note conversions, and pro-rata participation rights across fund and direct portfolios. Silicon Valley multi-family offices managing founder liquidity events require real-time cap table synchronization.
- Equity:Supports long-only and long-short public market strategies with T+1 settlement integration.
- Fixed Income:Calculates duration, convexity, and credit spread exposure across government and corporate issuers.
- Real Assets:Manages direct property holdings, REITs, and commodity exposures.
- Hedge Funds:Aggregates prime brokerage positions with leverage and financing cost attribution.
Alternative Investments command the deepest platform customization; Venture Capital is gaining share fastest as technology wealth creation accelerates direct investment activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentration in Northern Virginia and financial data center clusters in Frankfurt anchor procurement patterns for family office software deployments worldwide.
United States
Multi-generational family offices in New York and Connecticut drive demand for SEC Form PF automation and alternative investment tracking. The SEC's registered investment adviser regulations mandate granular private fund reporting, pushing technology refreshes. Silicon Valley multi-family offices managing founder liquidity events require real-time venture capital cap table synchronization alongside traditional custody feeds.
Switzerland
Geneva and Zurich single-family offices prioritize data sovereignty and cryptographic key control for cryptocurrency holdings. The Swiss Federal Act on Data Protection mandates local data residency, complicating cloud economics for vendors. Private banking clusters in Geneva generate concentrated demand for multi-currency, multi-entity reporting infrastructure with European energy market hedging capabilities.
Singapore
Ultra-high-net-worth families migrating from Hong Kong fuel demand for rapid public cloud deployment without local infrastructure investment. The Monetary Authority of Singapore's wealth management regulatory framework supports family office structuring with tax-efficient jurisdiction benefits. Asset managers establishing family office service divisions in the city-state drive institutional-caliber analytics adoption.
United Kingdom
London-based family trusts with dynasty structures spanning Delaware and Cayman Islands domiciles require dynamic consolidation engines. The Financial Conduct Authority's oversight of investment advisers shapes compliance module requirements for cross-border reporting. Mayfair and City of London private wealth advisors demand multi-client aggregation with segregated data architecture.
Germany
Industrial family offices in Bavaria and Baden-Württemberg managing direct European infrastructure stakes seek administrator-agnostic data ingestion. The EU Digital Operational Resilience Act mandates stringent third-party risk management and documented failover capabilities. Frankfurt's financial services cluster responds by prioritizing private cloud configurations with penetration testing protocols.
Family Office Software for Financial Management Market Competitive Landscape
API-first platform expansion dominates the current landscape as vendors race to accommodate tokenized asset classes and decentralized finance reporting standards. The vendor base stratifies across three tiers: institutional-caliber portfolio analytics providers, integrated partnership accounting specialists, and single-family office workflow automation platforms. Strategic archetypes include open-architecture aggregators, entity management depth specialists, and custody-agnostic data integrators. Technology licensing and vertical integration into alternative investment administrator networks constitute the dominant competitive moves.
Within the open-architecture tier, Addepar anchors institutional-caliber portfolio analytics for complex asset structures. FundCount occupies a position exemplifying integrated partnership accounting and general ledger consolidation capabilities. Eton Solutions represents the single-family office workflow automation archetype, differentiating through entity management depth. These three vendors collectively illustrate how specialization across data aggregation, tax accounting, and governance workflow automation defines competitive positioning.
| Leading Market Players |
|---|
| FundCount |
| Eton Solutions |
| Masttro |
| Addepar |
| Asset Vantage |
| Asora |
| Black Diamond |
| Archway |
| Advent |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up software specialists anchor supply concentration across the family office technology stack, translating fragmented vendor consolidation into pricing discipline that resists commoditization pressure. Their captive control over implementation talent pipelines and proprietary data aggregation protocols sustains margin architecture even as cloud infrastructure costs compress.
Pricing Analysis
Warranty and service bundling separates enterprise-grade deployments from stripped-down SaaS tiers, with implementation support and regulatory filing automation embedded in premium contracts while self-service modules carry lighter service obligations. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity and entity count rather than user seats alone. Price differentiation hinges on API ecosystem breadth and jurisdictional compliance layer depth. Cost compression in the economy tier is intensifying because outsourced CIO platforms demand operational expenditure alignment without customization. Emerging family offices exhibit highest price sensitivity, while multi-generational single-family offices in Switzerland and Singapore prioritize data sovereignty over cost minimization.
Supply Chain Analysis
Regional distribution centers in Northern Virginia, Frankfurt, and Singapore anchor hub-and-spoke delivery patterns for cloud infrastructure serving family office deployments. Software engineering talent concentrates in the United States, Switzerland, and India, with implementation expertise tethered to partnership tax accounting proficiency. Raw material dependencies include cloud compute capacity from hyperscalers, cryptographic security modules, and alternative investment administrator data feeds. Single-source vulnerability runs through custodian-agnostic aggregation layers that lack standardized formats. Distribution runs through direct vendor relationships for large single-family offices and outsourced CIO platform aggregators for multi-family office structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Implementation talent scarcity props pricing power across deployment cycles, constraining vendor capacity expansion regardless of demand acceleration. This bottleneck sustains margin architecture even as cloud infrastructure commoditizes.
For Market Incumbents: Anticipate API-first entrants targeting tokenized asset integration by hardening blockchain-native data ingestion capabilities before standards crystallize. Defensive consolidation through captive supply of partnership tax accounting expertise in Geneva and Zurich protects against Swiss data sovereignty mandates tightening further. Channel control over alternative investment administrator relationships represents the priority lever for locking out challenger platforms. For New Entrants and Emerging Players: Begin with mobile-native interfaces and ESG scoring modules targeting millennial family members as the most penetrable successor-generation segment. Singapore's wealth migration corridor offers geographic white space given rapid deployment requirements without local infrastructure investment. A direct-to-family-office go-to-market angle bypassing incumbent aggregator relationships accelerates initial traction. For Investors and Strategic Acquirers: Distressed-cycle entries favor entity-management-depth specialists in Switzerland facing compliance cost escalation from evolving Federal Act on Data Protection interpretations. Long-term viability across the next decade rests on jurisdictional compliance layer maintenance rather than core portfolio analytics commoditization. Watch SEC Form PF filing complexity expansion as the inflection signal for mandatory upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Expansion | Accommodates tokenized assets and DeFi reporting standards without core replacement. |
| Private Cloud Configuration Buildout | Satisfies Swiss Federal Act on Data Protection residency mandates for Geneva single-family offices. |
| Partnership Tax Accounting Talent Acquisition | Captures scarce implementation expertise constraining deployment velocity industry-wide. |
| Regulatory Filing Automation Investment | Embeds SEC Form PF and OECD CRS logic directly into portfolio accounting workflows. |
| Alternative Investment Administrator Integration | Eliminates reconciliation delays compressing new custodian relationship timelines from quarters to weeks. |
Research Methodology
Independent corroboration across family office technology executives, registered investment adviser compliance officers, and alternative investment administrator operations leads underwrites the qualitative findings presented herein. Primary interviews with CTOs at multi-generational family offices, platform engineers at cloud-native vendors, and integration specialists at custodian data providers combined with secondary validation from SEC Form PF filings, Swiss Federal Act on Data Protection regulatory guidance, and Monetary Authority of Singapore wealth management frameworks. Bottom-up deployment volume estimates and top-down addressable market sizing triangulate across the analysis window.
Comparable-period anchoring to historical technology refresh cycles and regulatory mandate implementation timelines structured the projection horizon. Segmentation dimensions modeled encompass deployment model, family office type, investment strategy complexity, and regional regulatory cluster. CAGRs were derived from adoption curve analysis and vendor capacity constraints. Forecast inputs include cloud migration velocity among ultra-high-net-worth segments and tokenized asset integration pipeline development.
Underlying measurement precision varies by segment; cloud-based deployment forecasts carry tighter precision than private cloud configurations given standardization. Forecasts reflect assumptions about regulatory filing automation adoption rates and jurisdictional data sovereignty enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market