
 Wealth Management Market | 2026-2036
Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
Wealth Management Market Outlook
Digital infrastructure is recalibrating how wealth management firms deliver scaled personalization at lower marginal cost. Vanguard leverages its mutual ownership structure to sustain fee compression across retail advisory channels. BlackRock anchors institutional portfolio construction through its Aladdin risk analytics platform. JPMorgan Chase competes by integrating private banking with commercial and investment banking capabilities under one balance sheet.
Wealth management encompasses the professional discipline of advising individuals, families, and institutions on asset allocation, risk management, tax efficiency, and intergenerational transfer, typically requiring certified personnel, fiduciary standards, and continuous portfolio monitoring against stated objectives. The practice generates revenue through advisory fees, asset-based charges, or performance incentives tied to portfolio outcomes. Investment Advisory services occupy the largest revenue pool given recurring fee structures, while Robo-Advisors represent the fastest-scaling technology segment as automated onboarding and rebalancing reduce unit economics for mass-affluent clients. Sustainable Investing commands premium pricing and stickier client relationships as environmental and governance mandates deepen across family office mandates.
The SEC regulates investment advisers under the Investment Advisers Act, requiring fiduciary duty disclosure and Form ADV transparency, while the CFP Board enforces ethical standards for certified planners that shape hiring and training investments. FINRA's broker-dealer oversight creates a dual regulatory architecture that fragments compliance architecture across hybrid advisory models. Stakeholders must monitor how artificial intelligence tools for client profiling and portfolio construction trigger evolving supervisory expectations from Washington regulators.
Market Dynamics
The wealth management sector faces structural recalibration as generative artificial intelligence compresses client onboarding costs while simultaneously elevating supervisory scrutiny from multiple jurisdictions. Fiduciary duty standards are tightening across Singapore, the United States, and Switzerland, forcing operating model redesigns.
Growth Catalysts
- SEC Enhanced Disclosure Framework:The Investment Advisers Act amendments mandate granular fee transparency, accelerating advisory firm consolidation as smaller practices absorb compliance overhead.
- Family Office Outsourcing:Ultra-high-net-worth households are delegating chief investment officer functions to external platforms, creating recurring revenue pools for multi-family office structures.
- Singapore Private Banking Migration:Regional asset relocation from Hong Kong is deepening liquidity in Singapore's wealth hub, concentrating custody and advisory service demand.
Market Restraints
- Talent Compensation Inflation:Certified financial planner scarcity across Zurich, London, and New York is elevating fixed cost structures for advisory practices.
- Technology Infrastructure Capex:Cybersecurity upgrades required by FINRA and MAS guidelines demand substantial capital deployment before revenue realization.
- Fee Compression Mechanics:Passive investment vehicle proliferation is displacing active management pricing power across mass-affluent segments.
Strategic Opportunities
- Sustainable Mandate Premium:Environmental and governance integration into family office portfolios commands pricing premiums and extends client tenure.
- India Wealth Penetration:SEBI-regulated investment adviser registrations are expanding access to underpenetrated high-net-worth households in Mumbai and Delhi.
- Hybrid Robo-Convergence:Automated rebalancing technology combined with human adviser overlay is capturing mass-affluent segments previously served by pure digital platforms.
Industry Challenges
- AI Supervisory Uncertainty:Washington regulators have issued evolving guidance on algorithmic client profiling, creating compliance timeline ambiguity for firms deploying machine learning tools.
- Intergenerational Transfer Complexity:Estate planning for cross-border family structures requires coordination across Swiss, US, and Singapore trust law frameworks, extending service delivery cycles.
- Legacy System Integration:Core banking platform modernization for established private banks demands sustained capital allocation while maintaining operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wealth Management Market |
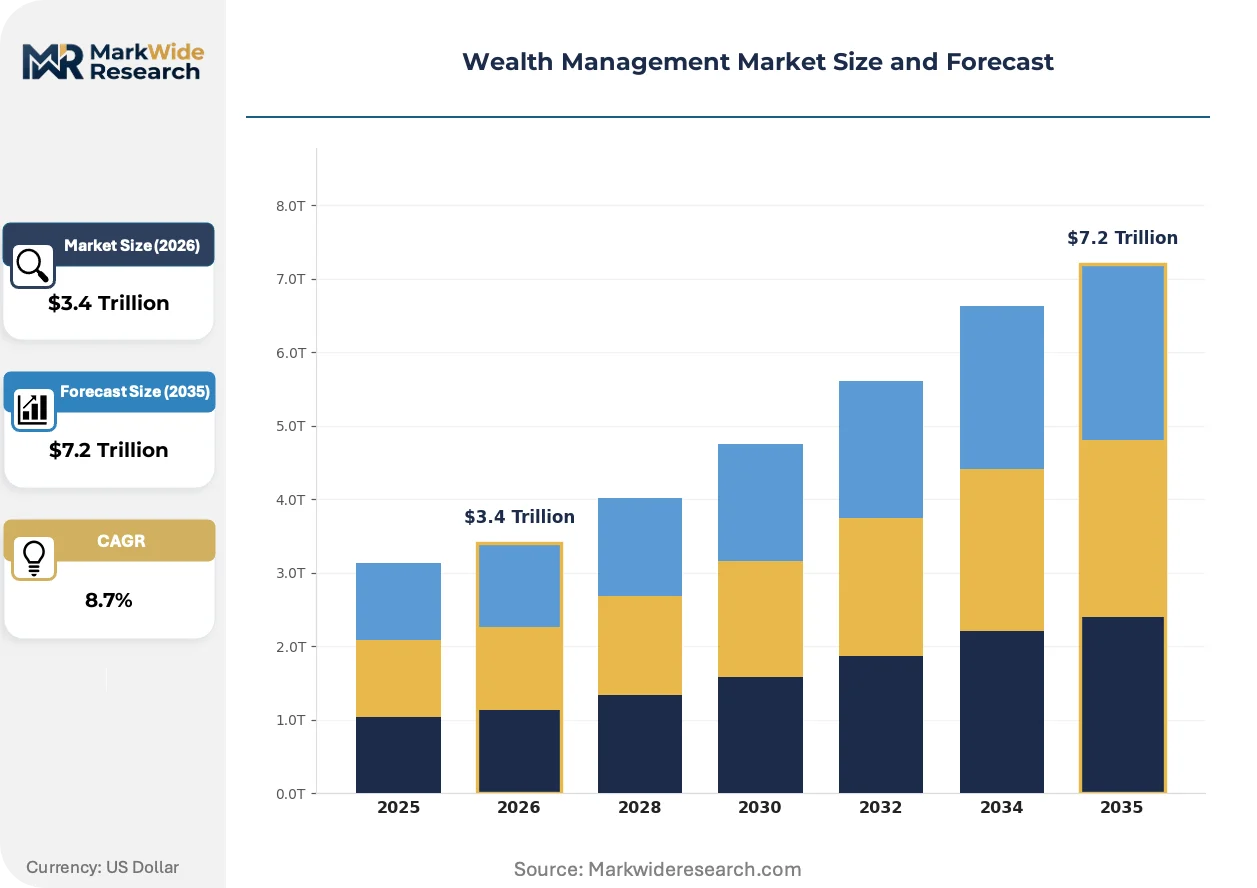
| Market Size in 2026 | $3.4 Trillion |
| Market Size in 2035 | $7.2 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Investment Advisory, Portfolio Management, Tax Planning, Estate Planning Client Type: High-Net-Worth Individuals, Families, Institutions, Corporations Investment Strategy: Active Management, Passive Management, Alternative Investments, Sustainable Investing Technology: Robo-Advisors, WealthTech Platforms, CRM Solutions, Data Analytics |
| Companies Covered | Vanguard, UBS, JPMorgan Chase, Edelman Financial Engines, BlackRock, Morgan Stanley, Charles Schwab, Facet, Fidelity Investments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wealth Management Market Strategic Shifts
Artificial intelligence deployment is restructuring how wealth platforms deliver personalization at scale, while regulatory technology investments reshape compliance architecture. Three developments are redefining competitive positioning.
Natural language processing tools are expanding into client communication workflows, automating routine portfolio commentary and rebalancing notifications. Mass-affluent segments are adopting these interfaces fastest, reducing human adviser touchpoints for standardized account actions. This capability compression is expanding into higher-net-worth segments as trust in algorithmic explanation generation deepens.
EU Sustainable Finance Disclosure Regulation requirements are mandating granular taxonomy alignment for investment products marketed across European Economic Area jurisdictions. Asset managers must reclassify fund offerings according to Article 6, 8, and 9 definitions, restructuring distribution materials and client reporting. Luxembourg and Dublin-domiciled funds are experiencing the most intensive re-documentation cycles as they serve cross-border European distribution.
Direct indexing platforms are displacing mutual fund wrappers among taxable high-net-worth investors seeking customization and tax-loss harvesting precision. Traditional separately managed account infrastructure is being unbundled into software-as-a-service offerings accessible through registered investment adviser channels. This pattern is most visible in the United States, where household concentration in appreciated equity positions creates demand for systematic transition strategies.
Wealth Management Market Segmentation
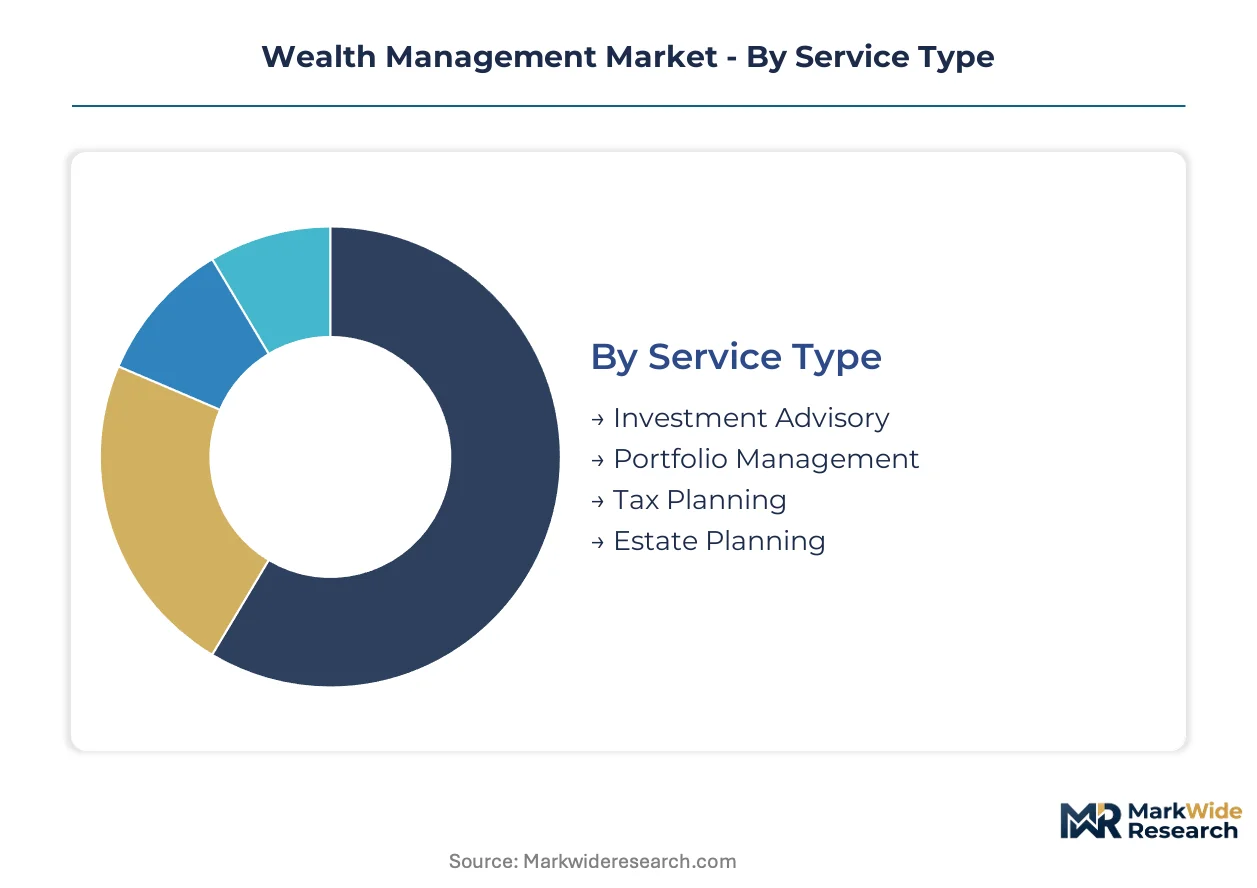
Wealth management segmentation reveals how advisory firms calibrate service intensity, technology deployment, and pricing architecture against distinct client liquidity profiles and complexity thresholds. Understanding these partitions illuminates where margin compression concentrates and where premium pricing endures.
Service Type:
Clients select service tiers based on portfolio complexity, regulatory exposure, and intergenerational transfer requirements rather than asset scale alone.
- Investment Advisory:Recurring fee structures dominate revenue pools as SEC disclosure mandates elevate fiduciary documentation standards. Demand concentrates among mass-affluent households in the United States seeking automated rebalancing with periodic human overlay. Compliance overhead is forcing consolidation among smaller registered investment adviser practices.
- Portfolio Management:Discretionary authority over asset allocation commands premium pricing for taxable accounts requiring systematic loss harvesting. Singapore's private banking hub attracts regional mandates as Hong Kong wealth migrates southward. Family offices outsource chief investment officer functions to external platforms here.
- Tax Planning:Cross-border coordination across Swiss, US, and Singapore trust law frameworks extends engagement duration for ultra-high-net-worth structures.
- Estate Planning:Intergenerational transfer complexity drives demand for multi-jurisdictional legal coordination and dynasty trust architecture.
Volume sits with Investment Advisory; growth tilts toward Portfolio Management.
Client Type:
Service economics diverge sharply across liquidity tiers, with operational infrastructure and personnel certification requirements scaling non-linearly with client complexity.
- High-Net-Worth Individuals:Direct indexing platforms displace mutual fund wrappers as taxable investors seek customization precision. United States households with concentrated equity positions drive demand for systematic transition strategies. Technology infrastructure investments here target tax-loss harvesting automation.
- Families:Multi-generational mandates command the longest advisory tenures and highest switching costs. Singapore and Switzerland compete for Asian family office relocation as Hong Kong regulatory uncertainty persists. Outsourced chief investment officer services deepen penetration here.
- Institutions:Fiduciary oversight requirements from ERISA and similar frameworks demand specialized compliance architecture.
- Corporations:Defined benefit pension derisking and non-qualified deferred compensation plans create episodic advisory demand.
Revenue concentrates with Families; expansion accelerates fastest among High-Net-Worth Individuals.
Investment Strategy:
Strategy selection reflects fee tolerance, liquidity needs, and regulatory-driven taxonomy compliance rather than pure return optimization.
- Active Management:Fee compression from passive vehicle proliferation constrains pricing power across mass-affluent segments. Certified financial planner scarcity in Zurich, London, and New York elevates fixed cost structures. Talent compensation inflation threatens margin sustainability here.
- Sustainable Investing:EU Sustainable Finance Disclosure Regulation mandates granular taxonomy alignment for products marketed across European Economic Area jurisdictions. Article 8 and Article 9 fund reclassification demands intensive re-documentation cycles in Luxembourg and Dublin. Environmental and governance integration commands pricing premiums.
- Passive Management:Vanguard's mutual ownership structure sustains fee compression across retail advisory channels.
- Alternative Investments:Private fund access requires qualified purchaser thresholds and specialized custody arrangements.
Assets aggregate in Passive Management; Sustainable Investing gains share fastest.
Technology:
Technology procurement decisions hinge on regulatory technology integration requirements, cybersecurity mandates, and marginal cost reduction targets.
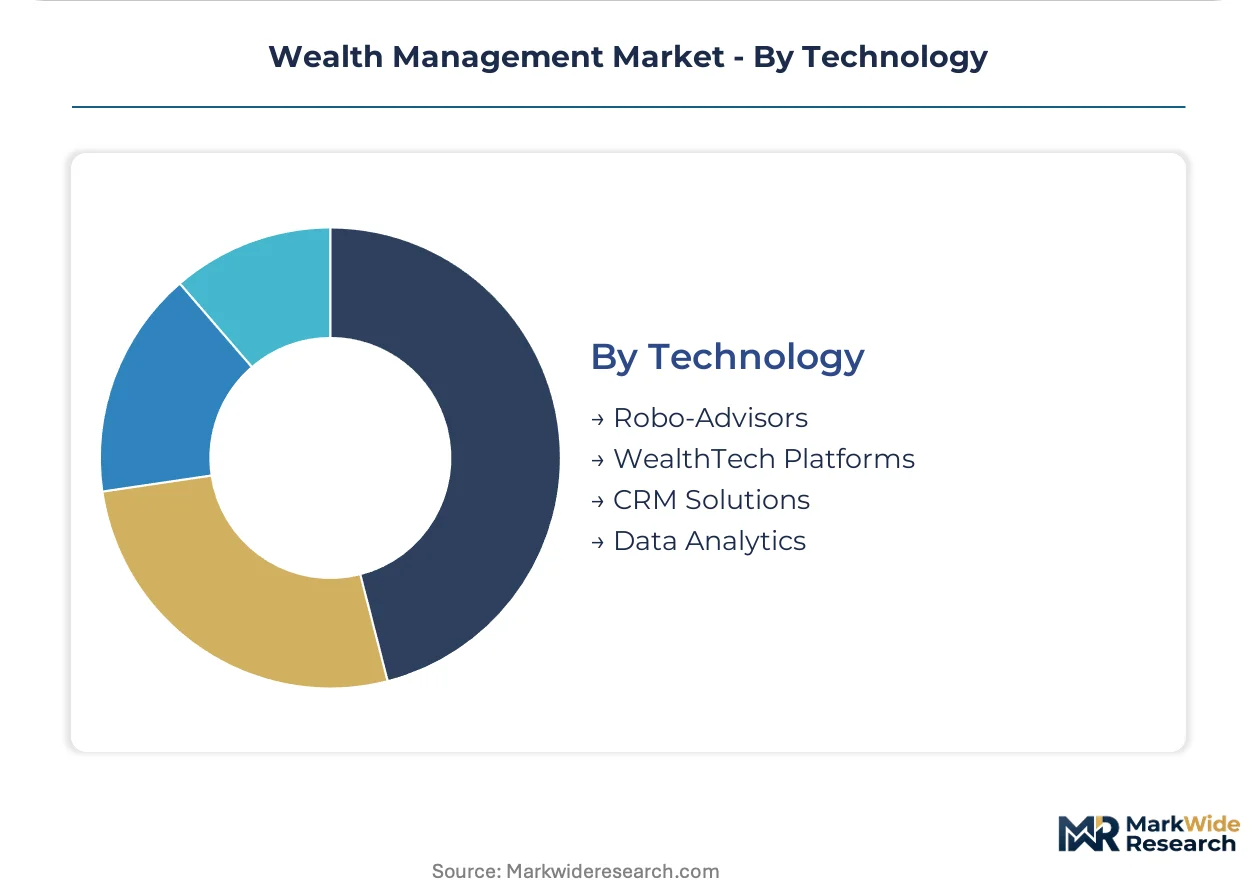
- Robo-Advisors:Automated onboarding and rebalancing reduce unit economics for mass-affluent clients previously served by pure digital platforms. Hybrid models combining algorithmic infrastructure with human adviser overlay capture market share from standalone automated services. FINRA and MAS cybersecurity guidelines demand substantial capital deployment.
- Data Analytics:Natural language processing tools automate routine portfolio commentary and rebalancing notifications. BlackRock's Aladdin platform anchors institutional risk analytics and portfolio construction workflows. Algorithmic client profiling triggers evolving supervisory expectations from Washington regulators.
- WealthTech Platforms:Core banking modernization for established private banks requires sustained capital allocation.
- CRM Solutions:Client lifecycle management integration with compliance documentation streamlines Form ADV transparency requirements.
Deployment concentrates in Data Analytics; adoption expands most quickly in Robo-Advisors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth households concentrate advisory demand in jurisdictions with stable trust law frameworks and favorable tax treaties. Singapore, Switzerland, the United States, and the United Kingdom capture the majority of cross-border wealth flows.
United States
Mass-affluent households drive automated advisory adoption while family offices outsource chief investment officer functions. SEC disclosure mandates under the Investment Advisers Act elevate compliance costs for registered investment advisers. New York and Boston anchor institutional portfolio construction activity.
Switzerland
Cross-border family structures demand coordination across Swiss, US, and Singapore trust law frameworks. FINMA guidelines shape private banking compliance architecture for wealth managers serving international clients. Zurich and Geneva concentrate multi-family office outsourcing mandates.
Singapore
Regional wealth migration from Hong Kong deepens liquidity in private banking custody and advisory services. MAS cybersecurity guidelines demand substantial capital deployment for technology infrastructure upgrades. The city-state's wealth hub attracts outsourced chief investment officer platforms.
United Kingdom
EU Sustainable Finance Disclosure Regulation mandates reclassify fund offerings for cross-border European distribution. FCA oversight shapes hybrid advisory model compliance across retail and institutional channels. London maintains concentration in discretionary portfolio management for taxable accounts.
India
SEBI-regulated investment adviser registrations expand access to underpenetrated high-net-worth households in Mumbai and Delhi. RBI prudential norms influence wealth platform capital requirements and custody arrangements. Maharashtra and Karnataka lead adoption of hybrid robo-advisory services.
Wealth Management Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with mutual ownership structures and integrated banking platforms defining competitive boundaries. The market exhibits tiered concentration: scale-driven asset managers compete on fee compression, while boutique multi-family offices command premium pricing for complex cross-border structures. Three archetypes dominate: mutual-owned retail platforms, integrated universal banks, and technology-anchored institutional asset managers. Competitive moves center on strategic partnerships for distribution reach and vertical integration into risk analytics infrastructure.
Among US-based asset managers, Vanguard exemplifies the mutual ownership model that sustains fee compression across retail advisory channels. BlackRock anchors institutional portfolio construction through its Aladdin risk analytics platform. JPMorgan Chase occupies a position integrating private banking with commercial and investment banking capabilities under one balance sheet.
| Leading Market Players |
|---|
| Vanguard |
| UBS |
| JPMorgan Chase |
| Edelman Financial Engines |
| BlackRock |
| Morgan Stanley |
| Charles Schwab |
| Facet |
| Fidelity Investments |
| Others |
Value Chain & Pricing Dynamics
Ultra-high-net-worth households in Singapore and Switzerland anchor pricing power for outsourced chief investment officer services, where discretionary portfolio management commands asset-based fees rather than flat retainers. This concentration of sophisticated buyers sustains premium pricing for multi-family office structures while compressing margins in mass-affluent robo-advisory channels.
Pricing Analysis
Volume aggregates in automated advisory tiers while margins concentrate in discretionary mandates. Three-tier pricing structure across premium, standard, and economy levels separates outsourced CIO services from hybrid robo-human offerings and pure digital platforms. Cost compression in mass-affluent segments stems from Vanguard's mutual ownership model sustaining fee erosion. Family offices exhibit least price sensitivity; mass-affluent digital adopters drive hardest bargain.
Supply Chain Analysis
Single-source vulnerability sits with BlackRock's Aladdin platform anchoring institutional risk analytics infrastructure across multiple competitors. Technology development concentrates in the United States, Switzerland, and Singapore where regulatory technology vendors cluster. Raw material dependencies include cloud computing capacity, cybersecurity certification frameworks, and specialized quant talent pools. Regulatory restriction risk intensifies as SEC and MAS guidelines evolve for AI-driven client profiling. Distribution runs through registered investment adviser networks and private banking partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wealth management sector is becoming a vertical-integration race as players pursue captive control over risk analytics infrastructure to differentiate advisory delivery. Ownership of algorithmic portfolio construction tools now determines margin sustainability.
For Market Incumbents: Acquire specialist risk analytics capabilities to defend against technology-anchored entrants. Consolidate smaller registered investment adviser practices absorbing SEC compliance overhead. Lock in certified financial planner talent pools in Zurich and New York before compensation inflation accelerates. For New Entrants and Emerging Players: Launch via hybrid robo-advisory models targeting India's underpenetrated high-net-worth households in Mumbai and Delhi. Exploit SEBI's expanding investment adviser registration framework. White-space opportunity sits with sustainable mandate integration for Asian family offices relocating from Hong Kong. For Investors and Strategic Acquirers: The window for entry favors technology-anchored asset managers with proprietary analytics platforms. Long-term viability hinges on recurring revenue structures rather than transactional brokerage models. Watch for AI supervisory guidance from Washington regulators as inflection signal for compliance technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | BlackRock's Aladdin risk analytics anchors institutional portfolio construction workflows. |
| Acquisition of Specialist Firm | Outsourced CIO platforms deepen penetration among ultra-high-net-worth family structures. |
| Regulatory Technology Investment | FINRA and MAS cybersecurity guidelines demand substantial capital deployment ahead. |
| Geographic Expansion | Singapore's private banking hub attracts regional wealth migration from Hong Kong. |
| Strategic Partnership | JPMorgan Chase integrates private banking with commercial and investment banking capabilities. |
Study Parameters
SEC filings, MAS regulatory circulars, and SEBI registration databases formed the secondary backbone for this analysis. Primary interviews with chief investment officers at multi-family offices, heads of private banking at Swiss institutions, regulatory technology vendors, and certified financial planners in New York and Zurich informed qualitative assessments. Bottom-up and top-down triangulation validated segment-level projections.
Bottom-up modeling aggregated service-type and client-type volumes while top-down cross-checks anchored against macro wealth concentration trends. Segmentation dimensions included service intensity tiers, technology deployment modes, and jurisdictional regulatory clusters. CAGRs were derived from fitted trend extrapolation moderated by structural breakpoint analysis across the projection horizon. Forecast inputs incorporated advisor headcount constraints and platform adoption curves.
Regulatory guidance evolution, talent scarcity inflections, and technology infrastructure capex cycles are the dominant revision risks to these projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
India Private Banking Market