
 High Net Worth (HNW) Offshore Investment Market | 2026-2036
High Net Worth (HNW) Offshore Investment Market Size, Share, and Industry Trends Forecast 2026-2036
High Net Worth (HNW) Offshore Investment Market Analysis
Wealth management from family offices is shifting toward multi-jurisdictional trust structures and alternative investment vehicles. UBS leverages its Swiss private banking heritage to dominate cross-border wealth advisory for ultra-HNW clients. JPMorgan Chase anchors its offshore platform through integrated custody and investment banking capabilities in key financial centers. Goldman Sachs differentiates via exclusive access to co-investment opportunities and bespoke structured products for offshore accounts.
High Net Worth (HNW) Offshore Investment encompasses cross-border deployment of liquid and illiquid assets through vehicles domiciled outside an investor's country of residence, typically structured to optimize tax efficiency, regulatory arbitrage, and currency diversification while maintaining compliance with home-country reporting obligations. The practice relies on specialized legal frameworks, segregated account structures, and multi-layered governance protocols to preserve capital across generations. Private equity and real estate investment vehicles command the deepest allocation pools among offshore structures, reflecting extended lock-up preferences and illiquidity premiums that family offices specifically seek. Hedge fund allocations through offshore feeders sustain momentum among aggressive risk-profile clients, though fee compression and transparency mandates are redistributing margin pools toward direct and co-investment structures.
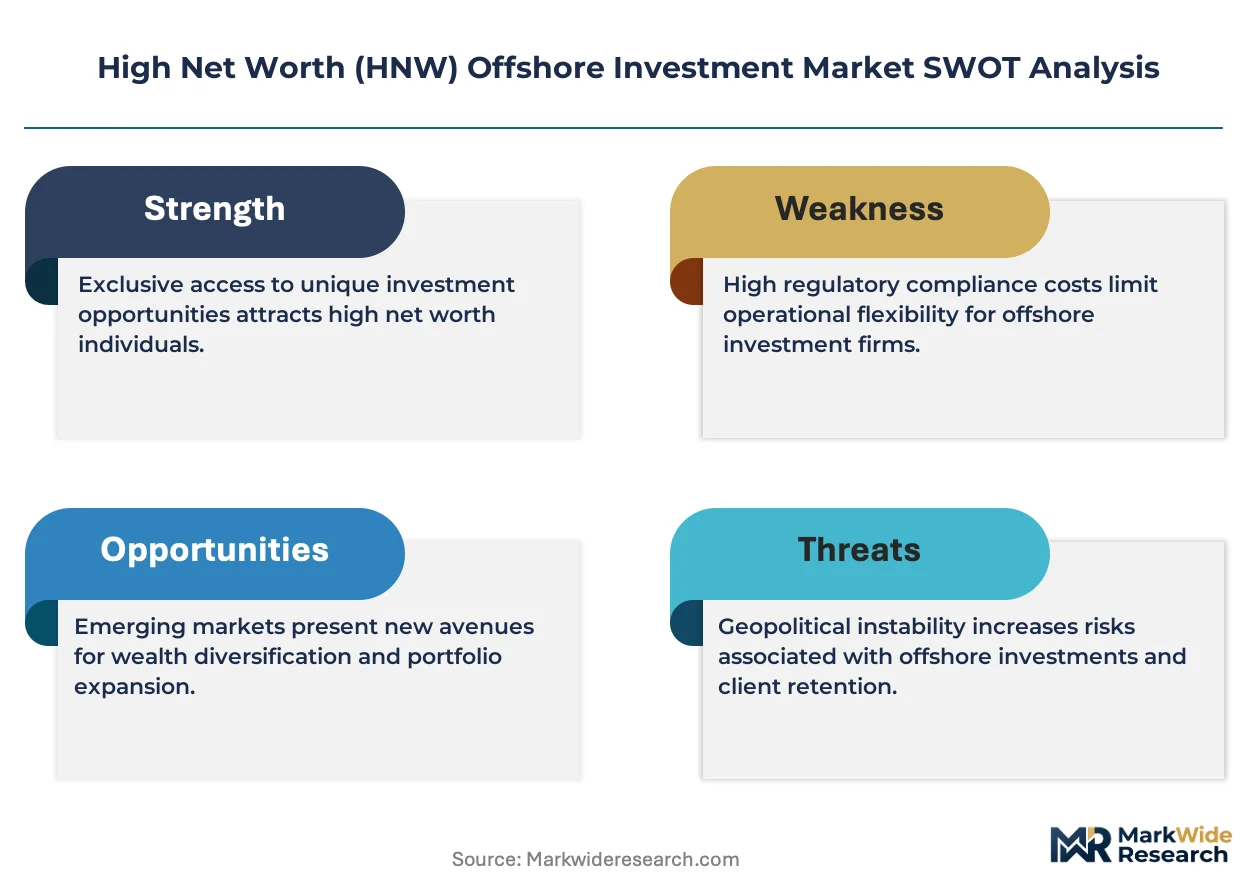
The OECD Common Reporting Standard and the US Foreign Account Tax Compliance Act create parallel compliance architectures that institutions must navigate simultaneously, elevating operational costs but also consolidating activity toward jurisdictions with robust treaty networks and regulatory clarity. The SEC and FCA impose overlapping conduct standards on marketing and advisory activities that cross into their respective territories, shaping product design and client onboarding protocols. Stakeholders must monitor evolving substance requirements in traditional offshore centers and assess whether emerging hubs can replicate the legal certainty and service depth that HNW clients demand for generational wealth structures.
Market Dynamics
The OECD Common Reporting Standard's phased expansion is forcing family offices to restructure legacy vehicles, compressing jurisdictional arbitrage and consolidating activity into treaty-network hubs with demonstrable substance requirements.
Growth Catalysts
- APAC Wealth Migration:Singapore's enhanced Variable Capital Company framework attracts mainland Chinese and Indian capital seeking firewall structures against domestic policy volatility.
- Alternative Asset Tokenization:Distributed ledger infrastructure enables fractionalized offshore exposure to private equity and real estate previously gated by minimum ticket sizes.
- OECD CRS Phase 3:Expanded due diligence protocols paradoxically benefit licensed trustees in Cayman Islands and British Virgin Islands by eliminating unregulated competition.
Market Restraints
- Substance Compliance Costs:Physical office and director presence mandates in traditional centers inflate operating overhead by 40-60% versus pre-2018 baselines.
- Beneficial Ownership Registers:Public disclosure regimes in EU member states and UK Overseas Territories strip privacy layers that historically anchored competitive positioning.
- US FATCA Withholding:Recalcitrant institution penalties and intergovernmental agreement complexity deter smaller trust companies from maintaining US-linked client relationships.
Strategic Opportunities
- UAE Hub Development:Dubai International Financial Centre's Common Law courts and zero personal tax regime attract European family offices exiting Swiss structures under OECD pressure.
- Climate Finance Structuring:Blended finance vehicles domiciled in Luxembourg and Ireland channel HNW capital into emerging market green bonds with tax-transparent treatment.
- Digital Nomad Wealth:Portugal's NHR regime and Greece's non-dom programs create captive demand for offshore investment wrappers among mobile entrepreneurs.
Industry Challenges
- Cross-Border Tax Expertise Scarcity:Qualified professionals capable of navigating simultaneous CRS, FATCA, and MLI treaty interpretations command premium compensation that erodes margin at mid-size institutions.
- Legacy System Interoperability:Core banking platforms built for secrecy-era account structures require costly middleware development to interface with automatic exchange reporting protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Net Worth (HNW) Offshore Investment Market |
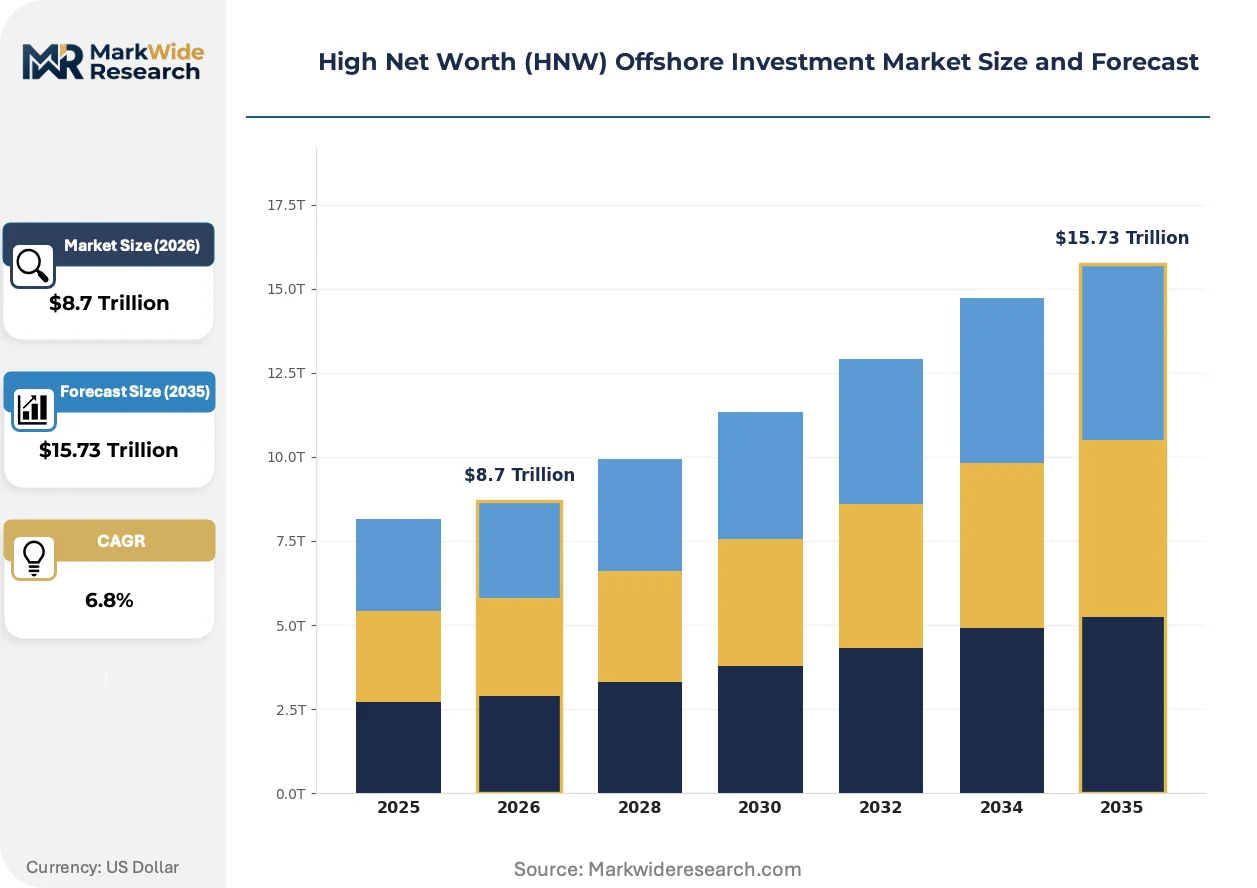
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $15.73 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Vehicle: Private Equity, Hedge Funds, Real Estate, Commodities Client Type: Individual Investors, Family Offices, Trusts, Institutions Risk Profile: Conservative, Balanced, Aggressive, Speculative Investment Stage: Seed, Growth, Late Stage, Mature |
| Companies Covered | Credit Suisse, Citigroup, JPMorgan Chase, Barclays, Morgan Stanley, Goldman Sachs, Deutsche Bank, HSBC, UBS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Net Worth (HNW) Offshore Investment Market Emerging Trajectories
Digital infrastructure and regulatory technology are compressing the cost curve for compliance-heavy offshore structuring, enabling smaller family offices to access institutional-grade jurisdictional engineering previously reserved for billionaire dynasties.
Blockchain-based fund administration is converging with traditional trust law to create immutable ownership records that satisfy CRS audit trails while reducing reconciliation overhead. Singapore-licensed trustees are piloting smart contract distribution waterfalls for private equity feeders. The structural consequence is compressing administrator margins and forcing incumbents to acquire or partner with fintech infrastructure providers.
The EU's sixth Anti-Money Laundering Directive extends beneficial ownership verification to crypto-asset service providers, capturing previously unregulated wallet custodians. Trust companies serving EU-domiciled clients must now integrate chain analytics into onboarding workflows. Luxembourg and Irish structures face the steepest compliance recalibration given their concentration of crypto-fund vehicles.
Direct indexing and separately managed accounts are displacing commingled offshore fund structures among ultra-HNW segments seeking granular tax-loss harvesting and ESG exclusion customization. Swiss private banks and Channel Island trustees are unbundling custody from investment management to capture this preference. The shift is most visible in US expatriate segments in London and Singapore seeking home-country tax attribute preservation.
High Net Worth (HNW) Offshore Investment Market Segmentation
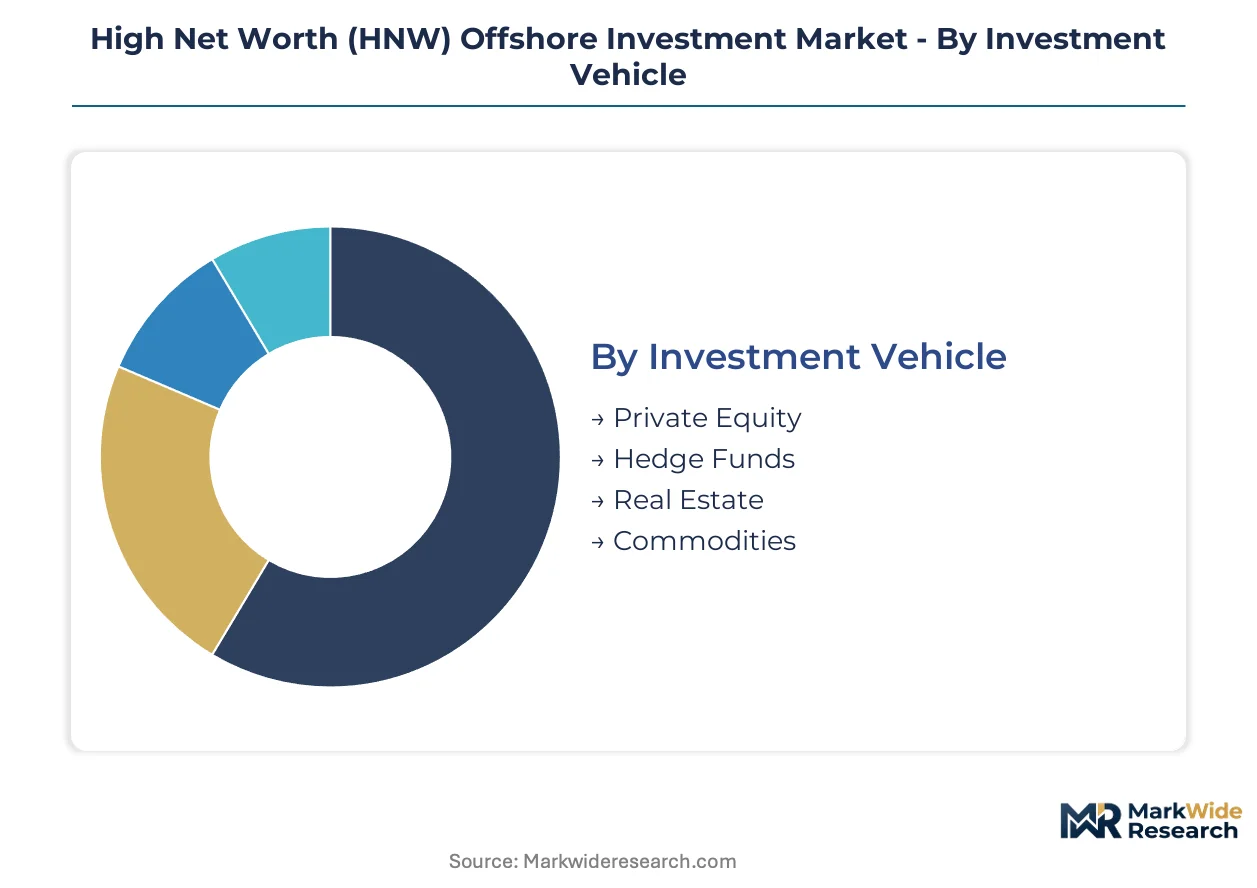
HNW offshore investment structures fragment across vehicle types, client governance models, risk tolerances, and capital deployment timelines. Each segmentation dimension carries distinct regulatory treatment, fee architecture, and jurisdictional optimization requirements that shape structuring decisions.
Investment Vehicle:
Vehicle selection determines custody location, tax treaty access, and reporting obligations across the holding period.
- Private Equity:Illiquid partnership interests domiciled in Cayman Islands and Luxembourg feeder structures concentrate capital from family offices seeking generational lock-up premiums. Singapore's Variable Capital Company framework now captures mainland Chinese allocation flows previously routed through BVI.
- Hedge Funds:Offshore master-feeder architectures maintain dominance among aggressive risk-profile clients despite fee compression toward 1.5% management and 15% performance structures. Cayman Islands maintains regulatory primacy for fund registration volume.
- Real Estate:Direct property holdings and REIT wrappers channel capital into Dubai, London, and Singapore commercial assets with Shariah-compliant structures gaining share in Gulf-domiciled vehicles.
- Commodities:Physical storage certificates and futures-backed ETCs provide inflation hedging through Swiss and Singapore custody arrangements with allocated bullion preference over unallocated claims.
Volume placements concentrate in Private Equity; the faster expansion belongs to Real Estate as Asian family offices diversify from public market exposure.
Client Type:
Governance complexity and reporting granularity scale directly with entity sophistication and beneficial ownership layering.
- Individual Investors:Direct offshore brokerage accounts face tightening CRS disclosure with Singapore and Switzerland capturing migration from traditional secrecy jurisdictions. Minimum ticket sizes now exceed $5 million at tier-one private banks.
- Family Offices:Multi-generational structures deploy capital through Delaware statutory trusts and Guernsey purpose trusts with embedded governance protocols for succession events. These entities command bespoke fee negotiations and direct co-investment access.
- Trusts:Discretionary and purpose trust vehicles restructure under OECD substance requirements with Bermuda and Cayman Islands trustees investing in physical presence and director residency compliance.
- Institutions:Pension and endowment allocations through offshore feeders face home-country prudent investor rule constraints that limit concentration in single-jurisdiction vehicles.
Advisory revenue concentrates with Family Offices; the steepest client acquisition growth trajectory belongs to Trusts as legacy structures require restructuring compliance.
Risk Profile:
Return targets and liquidity preferences determine leverage tolerance, derivative usage, and alternative asset concentration.
- Conservative:Capital preservation mandates prioritize sovereign bond ladders, investment-grade credit, and currency diversification through Swiss franc and Singapore dollar exposure.
- Balanced:Traditional 60/40 allocations migrate toward risk-parity implementations with volatility targeting across multi-asset class wrappers.
- Aggressive:Concentrated equity, event-driven credit, and activist positions deploy through leveraged feeder structures with margin facilities in prime brokerage arrangements.
- Speculative:Venture capital, crypto-asset, and frontier market exposures utilize high-water-mark fee structures with extended lock-up provisions.
Asset flows concentrate in Balanced mandates; the fastest share expansion belongs to Aggressive profiles as generational wealth transfers to risk-tolerant principals.
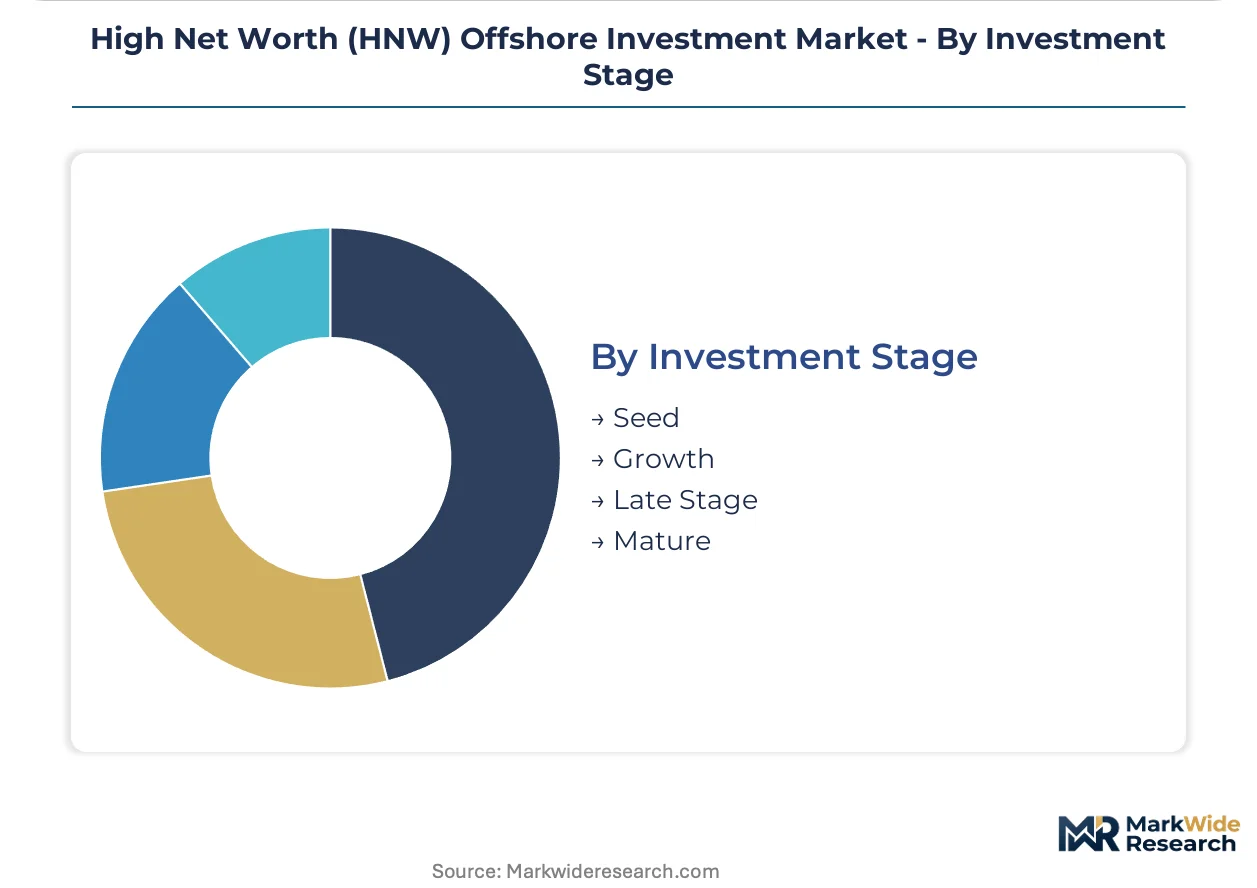
Investment Stage:
Capital deployment timing dictates due diligence intensity, governance rights, and exit pathway certainty.
- Seed:Early-stage venture and angel syndicates utilize SPV aggregation to meet offshore fund minimums with carried interest optimization through Luxembourg SOPARFI structures.
- Growth:Series B and C private equity commands the deepest allocation pools with co-investment rights and board observation seats standard in family office direct deals.
- Late Stage:Pre-IPO positions and secondary fund interests provide liquidity optionality with shorter duration profiles appealing to trustees with distribution obligations.
- Mature:Dividend-focused equity, mezzanine credit, and infrastructure yield vehicles anchor liability-matching portfolios for insurance-linked wrappers.
Capital deployment concentrates in Growth stage; the most rapid allocation expansion belongs to Late Stage as secondary markets mature for pre-IPO liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Variable Capital Company regime and Dubai International Financial Centre's zero personal tax framework are redistributing offshore wealth concentration from traditional European centers toward Asia-Pacific and Gulf hubs.
Singapore
Mainland Chinese and Indian family offices are migrating capital to Singapore's Variable Capital Company structures to establish firewall protection against domestic policy volatility. The Monetary Authority of Singapore enforces stringent substance requirements that parallel OECD CRS protocols. Marina Bay financial district houses the densest concentration of licensed trustees specializing in multi-generational wealth preservation.
Switzerland
UBS and Credit Suisse heritage private banks maintain dominance over ultra-HNW cross-border advisory despite eroding secrecy advantages. FINMA implements enhanced due diligence mandates that exceed baseline CRS requirements. Geneva and Zurich private banking clusters are restructuring toward transparent treaty-network hubs with demonstrable economic substance.
United Arab Emirates
European family offices exiting Swiss structures under OECD pressure are relocating to Dubai International Financial Centre's Common Law courts. The UAE Central Bank's regulatory framework permits zero personal taxation with robust anti-money laundering protocols. DIFC's physical office mandates attract trustees investing in director residency compliance.
Cayman Islands
Hedge fund master-feeder architectures sustain registration volume despite fee compression across the industry. The Cayman Islands Monetary Authority's expanded due diligence protocols eliminate unregulated competition under OECD CRS Phase 3. George Town's trustee sector is absorbing 40-60% operating overhead inflation from physical presence mandates.
United Kingdom
London-based private banks serve US expatriate segments seeking home-country tax attribute preservation through direct indexing structures. The FCA imposes overlapping conduct standards on marketing activities that cross into territorial jurisdiction. Mayfair and Canary Wharf clusters are unbundling custody from investment management to capture separately managed account preferences.
High Net Worth (HNW) Offshore Investment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated universal banks commanding ultra-HNW relationships while boutique trustees capture restructuring compliance demand. The vendor base concentrates around three tiers: Swiss-heritage private banking franchises, US investment banking platforms with custody integration, and mid-size Channel Island trustees specializing in family office governance. Strategic archetypes include treaty-network hub operators, alternative asset co-investment gatekeepers, and regulatory technology infrastructure providers. Consolidation activity centers on fintech acquisitions for blockchain-based fund administration and middleware development for CRS interoperability.
Among Swiss-heritage universal banks, UBS and Credit Suisse exemplify the cross-border advisory archetype anchored in multi-generational private banking relationships. JPMorgan Chase represents the integrated platform model combining custody infrastructure with investment banking capabilities across key financial centers. These institutions occupy positions within the premium-tier vector where minimum ticket sizes exceed five million dollars and bespoke fee negotiations are standard.
| Leading Market Players |
|---|
| Credit Suisse |
| Citigroup |
| JPMorgan Chase |
| Barclays |
| Morgan Stanley |
| Goldman Sachs |
| Deutsche Bank |
| HSBC |
| UBS |
| Others |
Supply Flow & Price Mechanics
OECD substance mandates gate qualified trustee supply and premium-tier pricing access for multi-jurisdictional structures. Family offices seeking compliant vehicles face extended onboarding timelines and elevated fee schedules at licensed providers.
Pricing Analysis
Short lead-time structures command premium pricing as trustees accelerate CRS-compliant vehicle formation for policy-sensitive capital. Bespoke fee negotiations dominate family office relationships while standardized trust products stratify across premium, standard, and economy tiers based on governance complexity and director residency requirements. Cost compression in mid-market trustee services intensifies as regulatory overhead inflates operating baselines. Digital-first entrants exhibit highest price sensitivity; ultra-HNW dynasties demonstrate lowest sensitivity given intergenerational wealth preservation priorities.
Supply Chain Analysis
Freight costs for physical document transfer and original signature logistics add marginal friction to trustee-client relationships despite digital onboarding advances. Licensed trustee capacity concentrates in Cayman Islands, Bermuda, and Singapore with Guernsey and Jersey serving European family office demand. Core service inputs draw from legal advisory networks, compliance technology platforms, and director talent pools. Single-source vulnerability runs through director residency requirements as substance mandates eliminate fly-in governance models. Distribution runs through private banking referral networks and direct family office relationships rather than open-architecture platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as OECD CRS Phase 3 compliance costs force sub-scale trustees into distressed exit or acquisition scenarios.
For Market Incumbents: Lock in multi-generational family office relationships through embedded succession governance protocols before restructuring mandates accelerate. Acquire regulatory technology capabilities to automate CRS reporting workflows and compress administrator margins. Vertical integration into blockchain-based fund administration counters fintech specialist encroachment on reconciliation services. For New Entrants and Emerging Players: Mobile entrepreneurs under Portugal's NHR regime and Greece's non-dom programs represent an underserved buyer archetype with captive demand for streamlined offshore wrappers. Target digital-native family offices seeking fractionalized private equity exposure through tokenized feeder structures. Pursue partnership routes with Singapore-licensed trustees rather than direct licensing given capital requirements. For Investors and Strategic Acquirers: Cayman Islands Monetary Authority enforcement actions against unregulated competition is the leading indicator that licensed trustee valuations will recover as margin pools consolidate. Five-to-ten year viability favors institutions with demonstrated substance compliance and physical presence investment. Monitor DIFC court ruling volumes as proxy for Dubai hub maturation and European family office migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Acquisition | Automated CRS reporting workflows compress administrator margins at Cayman Islands trustees. |
| Director Residency Compliance Investment | Physical presence mandates in Bermuda and Guernsey eliminate fly-in governance competition. |
| Blockchain Fund Administration Partnership | Smart contract distribution waterfalls reduce reconciliation overhead for Singapore VCC structures. |
| Variable Capital Company Licensing | MAS authorization captures mainland Chinese capital migration seeking firewall protection. |
| Climate Finance Vehicle Structuring | Luxembourg SICAV-SIF wrappers channel HNW capital into emerging market green bond pipelines. |
Methodological Framework
Document review covered SEC Form ADV filings, FATCA intergovernmental agreement texts, OECD CRS implementation handbooks, and trust company regulatory returns, complemented by interviews with licensed trustees, private banking relationship managers, family office chief investment officers, and regulatory technology platform developers. Secondary validation drew from central bank statistical releases, financial secrecy index databases, and cross-border investment flow estimates. Bottom-up vehicle formation counts and top-down wealth stock estimates were triangulated to establish market sizing.
Segmented outputs across the projection horizon reflect vehicle type, client governance model, risk tolerance band, and capital deployment stage dimensions. CAGRs were derived from trend extrapolation of family office allocation surveys and trustee registration volume trajectories. Forecast inputs incorporated OECD CRS phase-in schedules, substance requirement enforcement intensity, and APAC wealth migration velocity assumptions.
Revisions become necessary when regulatory enforcement intensity diverges from baseline assumptions or when technological infrastructure for tokenized fund administration achieves production-scale deployment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Smart Wealth Management Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Japan Private Banking Market