
 Core Banking Solutions Market | 2026-2036
Core Banking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Core Banking Solutions Market Intelligence
Neobanks and digital-first online banks are bifurcating demand away from traditional commercial bank procurement patterns, forcing incumbent vendors to split product roadmaps. FIS sustains dominance through captive data center infrastructure and mainframe-to-cloud bridge architectures. Temenos differentiates via API-native microservices that let smaller credit unions compete on digital experience parity. Mambu occupies the SaaS-native tier, extending composable banking engines to challenger banks across emerging markets.
Core banking solutions are integrated software platforms that manage a financial institution's central operations—deposit accounts, loan origination, payment routing, and general ledger reconciliation—typically processing transactions in real time through centralized databases with sub-second latency requirements. Their primary commercial purpose is to replace fragmented legacy host systems with unified record-keeping infrastructure that reduces operational risk and enables regulatory reporting automation. Cloud-based deployment now captures the fastest expansion as banks exit owned data centers, while on-premises installations retain residual demand among investment banks with bespoke risk-engine requirements. Payment processing solutions command the deepest margin pools because ISO 20022 migration and real-time gross settlement integration require continuous engineering investment.
The European Banking Authority's DORA framework and the EU AI Act impose operational resilience and algorithmic accountability standards that elevate compliance management modules to must-have status in RFP evaluations. India's RBI mandates periodic IT system audits for scheduled commercial banks, directly accelerating replacement cycles at institutions running 1990s-era Cobol architectures. Stakeholders must monitor how open banking API standards in Brazil and Nigeria reshape core vendor interoperability requirements before committing to single-platform contracts.
Market Dynamics
API-first architecture mandates from EU banking regulators and India's UPI-linked modernization programs are compressing replacement cycles at mid-tier commercial banks, forcing incumbent vendors to split product roadmaps between cloud-native microservices and mainframe bridge solutions.
Growth Catalysts
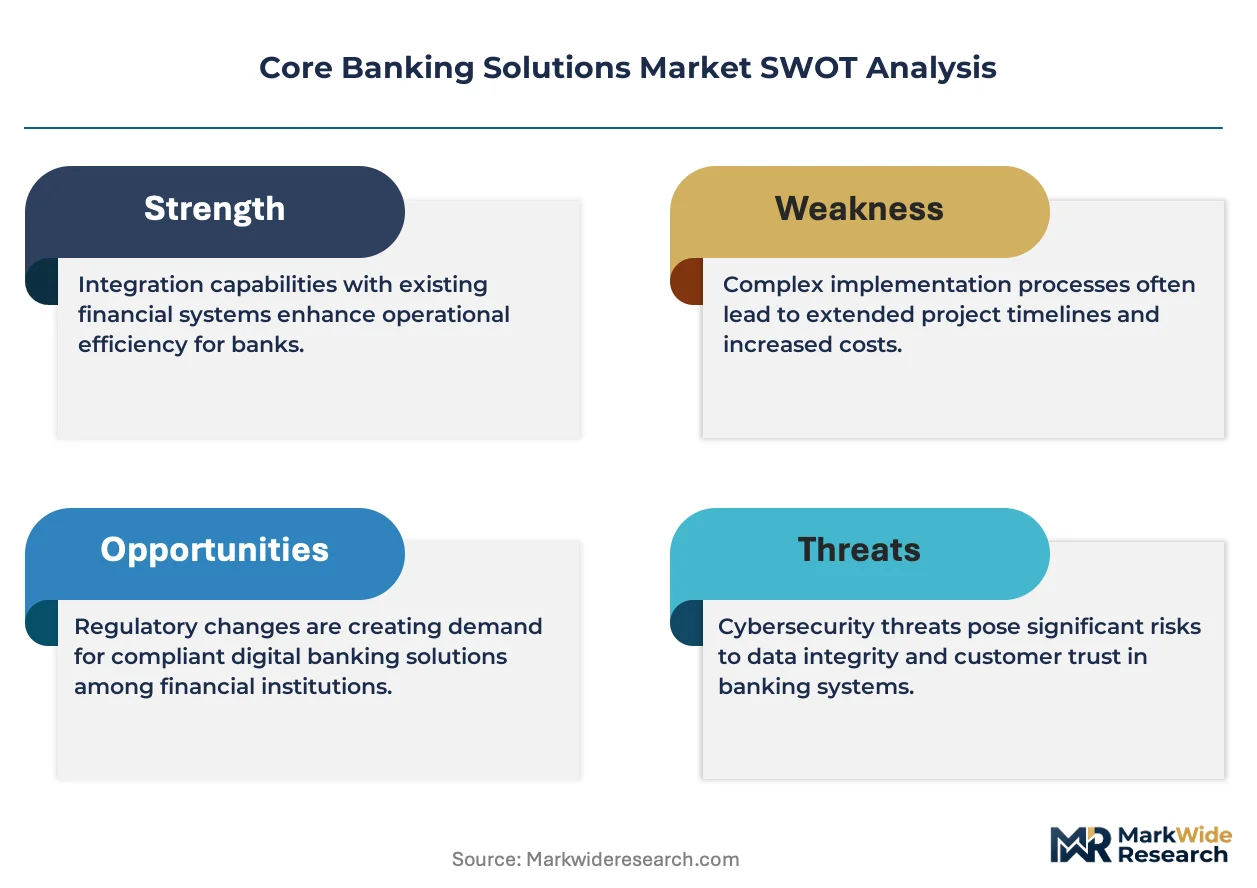
- EU DORA Framework:The European Banking Authority's operational resilience mandates elevate compliance management modules to must-have status in RFP evaluations, accelerating procurement of integrated risk-engine platforms.
- Cloud Migration Mandates:Regulators in Germany and France now require demonstrable exit strategies from captive data centers, pushing retail banking divisions toward SaaS-native core engines.
- Real-Time Payment Infrastructure:India's UPI-linked core modernization at public sector banks creates concentrated demand spikes for vendors offering sub-second latency transaction processing.
Market Restraints
- Cobol Skill Scarcity:Institutions running 1990s-era host systems face structural talent gaps as specialized maintenance expertise concentrates among aging contractor pools in North America and Western Europe.
- Mainframe Exit Costs:Data migration complexity from centralized databases to distributed cloud architectures imposes prohibitive switching costs at investment banks with bespoke risk-calculation requirements.
- Regulatory Fragmentation:Divergent open banking API standards between Brazil's central bank directives and Nigeria's interoperability frameworks complicate single-platform contract commitments.
Strategic Opportunities
- Credit Union Digital Parity:API-native microservices enable smaller cooperative banks to match neobank user experiences without captive infrastructure investment.
- Emerging Market Challenger Banks:Composable banking engines address unmet demand across Southeast Asian markets where regulatory sandboxes permit rapid license acquisition.
- ISO 20022 Convergence:Payment processing module upgrades tied to real-time gross settlement integration create recurring engineering revenue streams.
Industry Challenges
- Microservices Integration Complexity:Banks struggle to reconcile API-native components with residual mainframe general ledger systems during phased migration programs.
- Algorithmic Accountability Compliance:The EU AI Act's explainability requirements for automated credit decisions extend development timelines for machine learning-driven origination modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Core Banking Solutions Market |
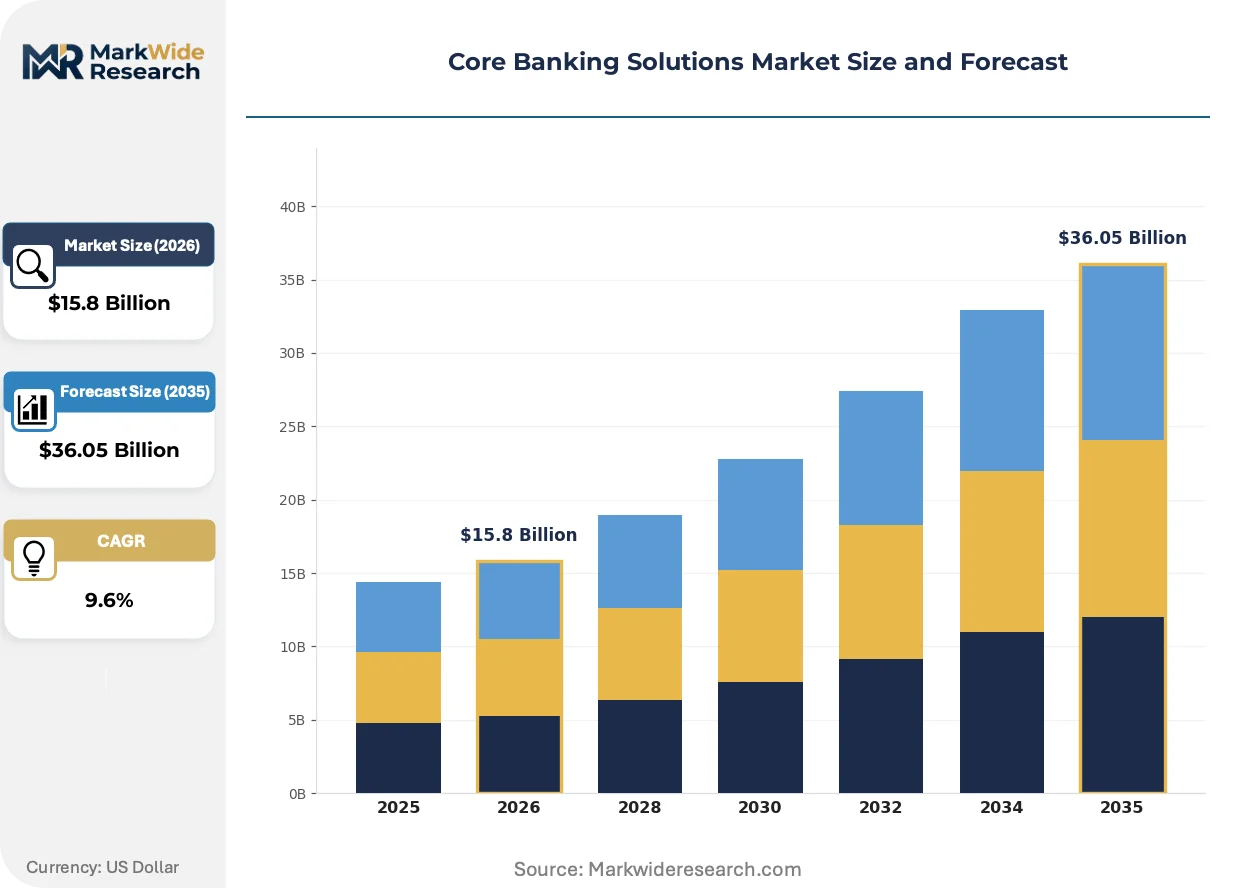
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $36.05 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: E-Banking, Mobile Banking, Digital Banking, Core Banking Deployment: On-Premises, Cloud-Based, Hybrid, Software as a Service End User: Commercial Banks, Credit Unions, Investment Banks, Online Banks Solution: Account Management, Payment Processing, Loan Management, Compliance Management |
| Companies Covered | FIS, Temenos, Finastra, Fiserv, Oracle FLEXCUBE, Finacle, TCS BaNCS, Mambu, Jack Henry & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Core Banking Solutions Market Strategic Shifts & Innovations
Core banking infrastructure is fragmenting into composable service layers as real-time payment rails and open banking APIs dissolve the monolithic architecture that dominated procurement for three decades.
Containerized core banking functions are miniaturizing into discrete microservices that handle specific operations—KYC verification, loan origination, or payment routing—as independently deployable units. Tier-2 banks in Spain and Italy are adopting these modules fastest, compressing vendor selection cycles from multi-year transformations to incremental capability purchases. This architectural shift is miniaturizing the traditional core banking contract into subscription-based component procurement.
The EU AI Act's risk-based classification system for automated decision-making now governs credit scoring and fraud detection modules deployed across the single market. Vendors must embed explainability interfaces and human oversight protocols directly into algorithmic workflows. Retail banking divisions face the steepest compliance burden, with French and Dutch regulators already requiring documented audit trails for model drift.
Neobanks and digital-first challengers are unbundling after-sales service expectations from core platform contracts, demanding standalone technical support tiers and transparent API documentation as standalone purchase criteria. This disintermediates traditional systems integrators who previously controlled implementation relationships. The pattern is most visible in the UK and Brazil, where regulatory sandboxes have accelerated challenger bank licensing.
Core Banking Solutions Market Segmentation
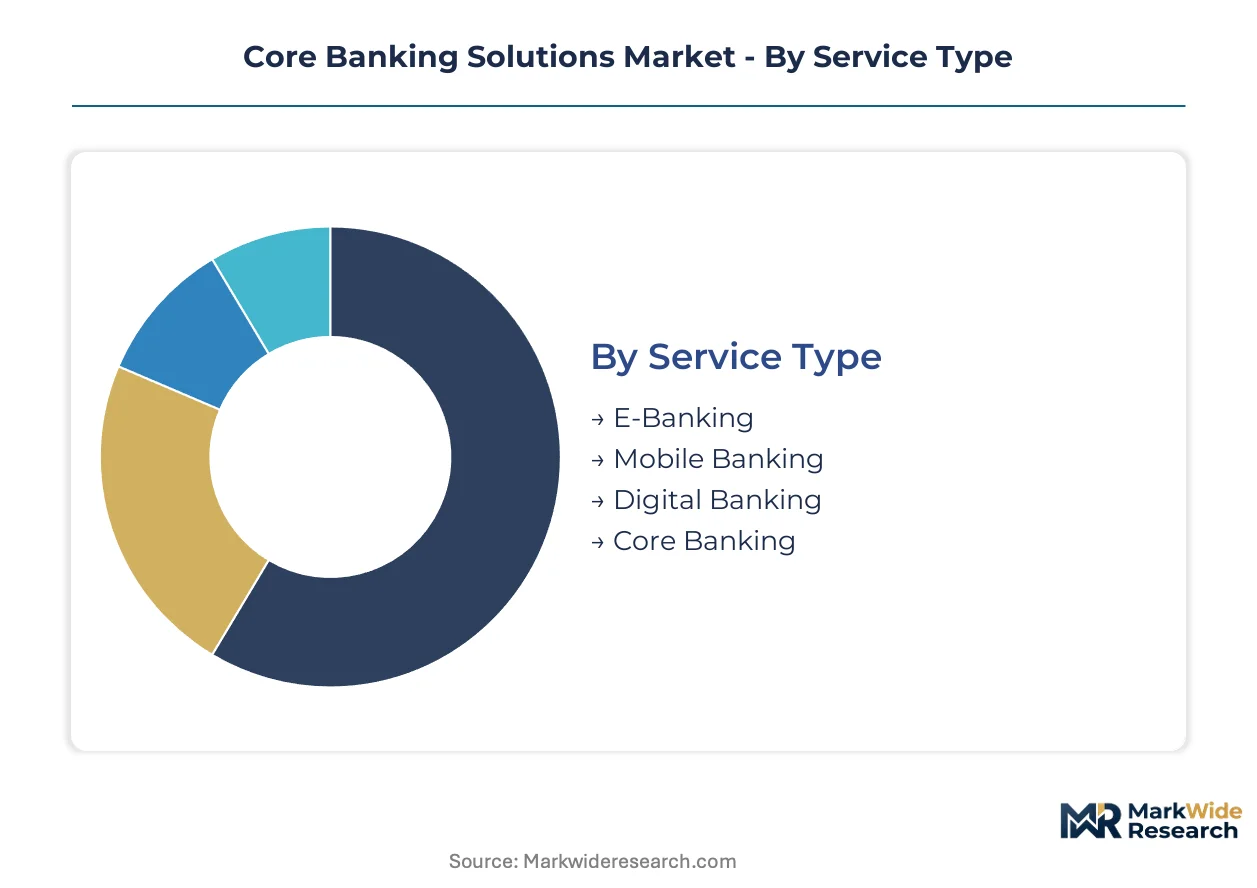
Segmentation in core banking solutions reveals how procurement patterns diverge between legacy institutions seeking migration pathways and digital-native challengers demanding composable architectures. Understanding these divides helps vendors align engineering roadmaps with divergent buyer risk profiles and deployment timelines.
Service Type:
Channel mix varies sharply across service categories, with mobile and digital banking solutions flowing primarily through SaaS vendor direct sales while core banking platforms still route through systems integrators and professional services firms.
- E-Banking:Web-based transaction portals with multi-factor authentication and session management capabilities. Demand concentrates at mid-tier commercial banks in Germany and France replacing legacy internet banking stacks ahead of DORA compliance deadlines.
- Mobile Banking:Native iOS and Android applications with biometric login and push notification architectures. India's public sector banks drive concentrated procurement as UPI integration mandates force frontend modernization at institutions running 1990s-era host systems.
- Digital Banking:Omnichannel platforms unifying web, mobile, and API touchpoints into single customer profiles. Challenger banks in Brazil's regulatory sandbox environment prioritize these solutions for rapid license acquisition.
- Core Banking:Centralized ledger and transaction processing engines handling real-time account updates. Credit unions in Spain and Italy adopt API-native microservices variants to match neobank experience parity without captive infrastructure.
By volume, Core Banking leads procurement value. By growth pace, Mobile Banking is expanding most quickly.
Deployment:
Cost tier stratification dominates deployment selection, with SaaS and cloud options capturing smaller institutions while hybrid and on-premises retain investment banks with bespoke risk-calculation requirements.
- On-Premises:Captive data center installations with dedicated hardware and licensed perpetual software. Investment banks in London and Frankfurt maintain these deployments for proprietary trading risk engines subject to algorithmic accountability audits under EU AI Act requirements.
- Cloud-Based:Public cloud infrastructure with containerized core functions and auto-scaling compute. Retail banking divisions at French and German institutions accelerate migration as national regulators mandate demonstrable exit strategies from owned facilities.
- Hybrid:Split architectures keeping general ledger on mainframe while migrating customer-facing modules to cloud. Mid-tier commercial banks favor this pattern to manage Cobol skill scarcity during phased transformation programs.
- Software as a Service:Fully managed multi-tenant platforms with subscription pricing and continuous feature updates. Challenger banks across Southeast Asian markets adopt these engines for rapid deployment within regulatory sandboxes.
By maturity, On-Premises dominates installed base. By customer acquisition velocity, Software as a Service is gaining share fastest.
End User:
Application urgency varies by institution type, with online banks demanding immediate API-native deployment while commercial banks navigate multi-year mainframe exit timelines.
- Commercial Banks:Full-service deposit and lending institutions with branch networks and corporate banking divisions. Mid-tier institutions in Italy and Spain compress replacement cycles as EU operational resilience mandates elevate compliance modules to must-have RFP status.
- Credit Unions:Member-owned cooperative banks with community-focused lending portfolios. Smaller institutions leverage API-native microservices to achieve digital experience parity with neobanks without infrastructure capital expenditure.
- Investment Banks:Securities trading and advisory firms with complex derivatives risk calculations. Proprietary risk-engine requirements preserve on-premises demand despite broader cloud migration trends.
- Online Banks:Digital-first challengers without physical branch infrastructure. Brazil and UK regulatory sandboxes accelerate licensing for these institutions, which unbundle after-sales service expectations from core platform contracts.
By revenue concentration, Commercial Banks anchor procurement. By contract velocity, Online Banks show steepest expansion trajectory.
Solution:
Margin pools concentrate in payment processing modules where ISO 20022 migration and real-time gross settlement integration require continuous engineering investment.
- Account Management:Real-time deposit tracking, interest calculation, and statement generation across currency types. Indian scheduled commercial banks modernize these systems as RBI-mandated IT audits expose vulnerabilities in 1990s-era Cobol architectures.
- Payment Processing:Transaction routing, clearing, and settlement with sub-second latency requirements. Real-time payment infrastructure investments in India and EU instant payment schemes create recurring upgrade revenue for vendors managing ISO 20022 convergence.
- Loan Management:Origination workflows, collateral tracking, and amortization scheduling with automated decisioning. EU AI Act explainability requirements extend development timelines for machine learning-driven credit scoring modules deployed across the single market.
- Compliance Management:Regulatory reporting automation, audit trail preservation, and risk monitoring dashboards. DORA framework implementation elevates these modules to mandatory status in European Banking Authority jurisdiction procurements.
By engineering intensity, Payment Processing commands deepest investment. By procurement urgency, Compliance Management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports core banking modernization services to Southeast Asian challenger banks, while EU regulatory mandates drive procurement corridors from Frankfurt and Paris into Central European markets. Demand concentrates where real-time payment infrastructure intersects with legacy system replacement urgency.
United States
Mid-tier commercial banks accelerate mainframe exit timelines as Cobol skill scarcity concentrates among aging contractor pools. The Federal Reserve's FedNow instant payment network mandates sub-second latency capabilities that force platform replacements. New York and Charlotte banking clusters drive concentrated vendor selection for hybrid cloud architectures bridging legacy general ledger systems.
Germany
BaFin mandates demonstrable exit strategies from captive data centers, compressing procurement cycles at retail banking divisions. The EU DORA framework elevates operational resilience modules to mandatory RFP status. Frankfurt's financial services corridor anchors demand for compliance-integrated core engines that automate regulatory reporting workflows.
India
RBI-mandated IT system audits expose vulnerabilities in 1990s-era host systems at public sector banks, triggering concentrated replacement demand. UPI-linked core modernization programs require vendors offering real-time transaction processing. Mumbai and Bangalore technology clusters house implementation partnerships serving scheduled commercial banks.
Brazil
Central bank regulatory sandboxes accelerate challenger bank licensing, unbundling after-sales service expectations from core platform contracts. Open banking API standards reshape vendor interoperability requirements. São Paulo's fintech corridor drives adoption of composable banking engines among digital-first institutions.
United Kingdom
Neobanks demand standalone technical support tiers and transparent API documentation as separate purchase criteria, disintermediating traditional systems integrators. The Financial Conduct Authority's operational resilience expectations compress vendor selection timelines. London's digital banking cluster leads procurement of subscription-based component architectures.
Core Banking Solutions Market Key Industry Players
Player mix skews toward incumbent mainframe-to-cloud bridge providers with captive data center infrastructure. Market structure concentrates around three tiers: legacy platform maintainers, API-native microservices specialists, and SaaS-native composable engine providers. Dominant competitive moves include portfolio diversification into compliance management modules and strategic partnerships with systems integrators to control implementation relationships.
Within the incumbent tier, FIS and Temenos anchor positions through differentiated infrastructure approaches, while Mambu occupies the SaaS-native segment. FIS exemplifies the captive data center archetype with bridge architecture capabilities. Temenos represents API-first microservices positioning that enables smaller institutions to achieve digital parity. Mambu sits within the composable banking engine category serving emerging market challengers.
| Leading Market Players |
|---|
| FIS |
| Temenos |
| Finastra |
| Fiserv |
| Oracle FLEXCUBE |
| Finacle |
| TCS BaNCS |
| Mambu |
| Jack Henry & Associates |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with SaaS-native vendors lock in both cloud infrastructure access and predictable subscription pricing for retail banking divisions exiting captive data centers. This contract structure shields buyers from spot-market volatility in compute resources while binding vendors to continuous feature delivery timelines.
Pricing Analysis
Current-generation API-native microservices command substantial premiums over prior-generation mainframe bridge solutions, while next-generation composable banking engines with embedded AI explainability interfaces sit at the apex of vendor pricing hierarchies. Three-tier pricing structure across premium API-native suites, standard hybrid cloud bundles, and economy-tier legacy maintenance contracts dominates procurement negotiations. Price differentiation hinges on ISO 20022 certification status and geographic data residency compliance, with EU DORA-aligned modules extracting measurable premiums. Pricing pressure stems from challenger banks unbundling after-sales service expectations, forcing margin compression in implementation support tiers. Credit unions exhibit highest price sensitivity due to capital constraints, while investment banks with bespoke risk-engine requirements demonstrate lowest sensitivity.
Supply Chain Analysis
Implementation lead times for core banking platforms have extended from twelve to eighteen months as cloud infrastructure provisioning queues lengthen at hyperscale providers serving financial services workloads. Engineering talent concentrates in India, Ireland, and Poland, with Mumbai and Bangalore clusters anchoring delivery capacity for public sector bank modernization programs. Software development draws from specialized Cobol contractor pools in North America and Western Europe, alongside cloud-native engineering pipelines in Southeast Asian technology hubs. Single-source vulnerability concentrates in mainframe-to-cloud migration tooling controlled by incumbent vendors with decades-long client relationships. Distribution runs through systems integrators and professional services firms that control implementation relationships and post-deployment support revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Core banking incumbents face sustained substitution threat from composable SaaS-native engines that disintermediate traditional platform vendors through API-first architectures and rapid deployment timelines.
For Market Incumbents: Consolidate around captive data center bridge architectures and deepen compliance management module integration to defend against Mambu-tier challengers. Prioritize ISO 20022 certification investments and vertical integration into implementation services to control customer relationships during multi-year transformation programs. Lock in mid-tier commercial banks with hybrid cloud roadmaps that extend mainframe dependency while cloud modules mature. For New Entrants and Emerging Players: Differentiate on embedded explainability interfaces that satisfy EU AI Act algorithmic accountability requirements for automated credit decisions. Target credit unions in Spain and Italy seeking digital experience parity without infrastructure capital expenditure, and challenger banks in Brazil's regulatory sandbox environment demanding rapid license acquisition. Lead with transparent API documentation and standalone technical support tiers that disintermediate traditional systems integrators. For Investors and Strategic Acquirers: Capital is best deployed toward SaaS-native composable engine providers with proven regulatory sandbox deployments and recurring revenue visibility across emerging markets. Long-term viability hinges on API-native microservices architectures that accommodate evolving open banking interoperability standards. Monitor RBI-mandated IT audit schedules at Indian public sector banks as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native microservices bridge residual mainframe general ledger systems during phased cloud migration programs at mid-tier commercial banks. |
| Regulatory Compliance Investment | Embedded DORA framework modules automate operational resilience reporting for European Banking Authority jurisdiction procurements. |
| Strategic Partnership | Systems integrator alliances control implementation relationships and post-deployment support revenue streams in competitive RFP evaluations. |
| Acquisition of Specialist Firm | Cobol contractor pool consolidation addresses structural talent scarcity for 1990s-era host system maintenance during transformation windows. |
| Geographic Expansion | UPI-linked core modernization programs at Indian public sector banks create concentrated demand spikes for real-time transaction processing capabilities. |
Research Approach
The analysis maps core banking platforms, payment processing modules, compliance management suites, and channel solutions, each validated through CTOs at commercial banks, IT procurement officers at credit unions, platform engineers at SaaS-native vendors, and integration specialists at systems integrators. Primary fieldwork combined structured interviews with secondary validation against SEC filings from publicly traded vendors, RBI circulars on IT system audits, European Banking Authority DORA implementation guidelines, and hyperscaler financial services cloud deployment disclosures. Bottom-up segmentation sizing triangulated against top-down market aggregates derived from vendor revenue disclosures and banking regulator procurement notices.
Consistency checks validated volume and value outputs against external benchmarks including banking technology expenditure surveys and cloud migration spending patterns across the analysis window. The forecast framework modeled deployment model transitions, institution size tiers, solution complexity gradients, and regional regulatory adoption patterns. CAGRs were derived from segmented growth trajectory analysis incorporating replacement cycle compression at Cobol-dependent institutions and real-time payment infrastructure investment intensity. Industry-specific inputs included UPI transaction volume growth curves and EU instant payment scheme integration timelines.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory pressure for cloud migration and stable Cobol skill scarcity; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking As a Service (BAAS) Market
Banking
Letter of Credit Confirmation Market
Banking
Retail Banking Market
Banking
Singapore Neobanking Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
Smart Banking Solutions Market
Banking
Automated Teller Machine (ATM) Market
Banking
North America Data Analytics in Banking Market
Banking
Middle East and Africa Neobanking Market
Banking
Europe Neobanking Market
Banking
Disaster Recovery in Banking Market
Banking
API Banking Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Italy Data Analytics in Banking Market
Banking
Global AI in Banking Market