
 Family Offices Market | 2026-2036
Family Offices Market Size, Share, and Industry Trends Forecast 2026-2036
Family Offices Market Insights
Next-generation heirs and first-generation technology founders is rotating capital deployment away from traditional wealth preservation toward direct private equity and impact investing strategies. Walton Enterprises anchors its position through concentrated public equity holdings and long-horizon portfolio construction. Bezos Expeditions competes through aggressive venture capital deployment in frontier technology sectors. Cascade Investment sustains dominance via disciplined equity concentration and minimal external manager reliance.
A family office constitutes a privately held wealth management advisory firm serving one or multiple ultra-high-net-worth families, typically requiring minimum investable assets of $100 million to justify operational overhead through dedicated investment teams, legal infrastructure, and consolidated reporting systems. The client type dimension shows single-family offices capturing the largest share of assets under management while multi-family offices expand fastest by pooling operational costs across client bases. Within investment strategy, private equity and venture capital allocations command the most staff resources and generate the highest fee intensity, whereas real assets and fixed income strategies function as mature, lower-margin stabilizers.
The SEC enforces investment adviser registration and Form PF disclosure requirements that shape operational scale thresholds and compliance staffing decisions for US-based family offices. The IRS coordinates estate tax regulations and generation-skipping transfer rules that directly influence succession planning service demand and trust structuring complexity. Stakeholders must monitor evolving cryptocurrency custody regulations and artificial intelligence governance frameworks as these domains attract increasing family office capital allocation scrutiny.
Market Dynamics
The SEC's expanded Form PF reporting requirements and accredited investor redefinitions are compressing operational scale thresholds, forcing family offices to consolidate compliance infrastructure or absorb elevated fixed costs per dollar of assets under management.
Growth Catalysts
- Regulatory Clarity on Digital Assets:The SEC's evolving guidance on cryptocurrency custody frameworks is enabling structured allocation strategies for family offices previously sidelined by fiduciary uncertainty.
- Healthcare Entrepreneurship Concentration:Biotech founder liquidity events in Boston and San Diego corridors are generating new single-family office formations with specialized venture deployment capabilities.
- Direct Indexing Technology:Customized separately managed accounts with tax-loss harvesting automation are reducing reliance on external mutual fund managers and compressing fee drag.
Market Restraints
- Compliance Cost Escalation:The Investment Advisers Act registration thresholds and Form ADV disclosure burdens impose disproportionate fixed costs on sub-$500 million offices.
- Talent Concentration Risk:Experienced family office executives cluster in New York, London, and Singapore, creating wage inflation and retention vulnerability for secondary market offices.
- Illiquidity Trap:Private equity and venture capital allocations exceeding 40% of portfolio construction create cash flow mismatches during generational wealth transfer events.
Strategic Opportunities
- Next-Generation Governance Platforms:Artificial intelligence-driven consolidated reporting systems are enabling multi-family offices to serve ultra-high-net-worth clients with previously uneconomical asset thresholds.
- Impact Measurement Standardization:The EU's Sustainable Finance Disclosure Regulation and proposed SEC climate disclosure rules are creating first-mover advantages for offices with integrated ESG data infrastructure.
- Miami Wealth Corridor Expansion:Florida's absence of state income tax and concentrated private aviation infrastructure is attracting technology founder relocations and associated office establishment.
Industry Challenges
- Cybersecurity Architecture Complexity:Multi-generational family offices with legacy IT infrastructure face elevated breach exposure as ransomware operators target concentrated wealth repositories.
- Succession Planning Execution:Intergenerational wealth transfer involving operating businesses, real estate holdings, and illiquid private fund interests requires specialized trust and estate legal coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Family Offices Market |
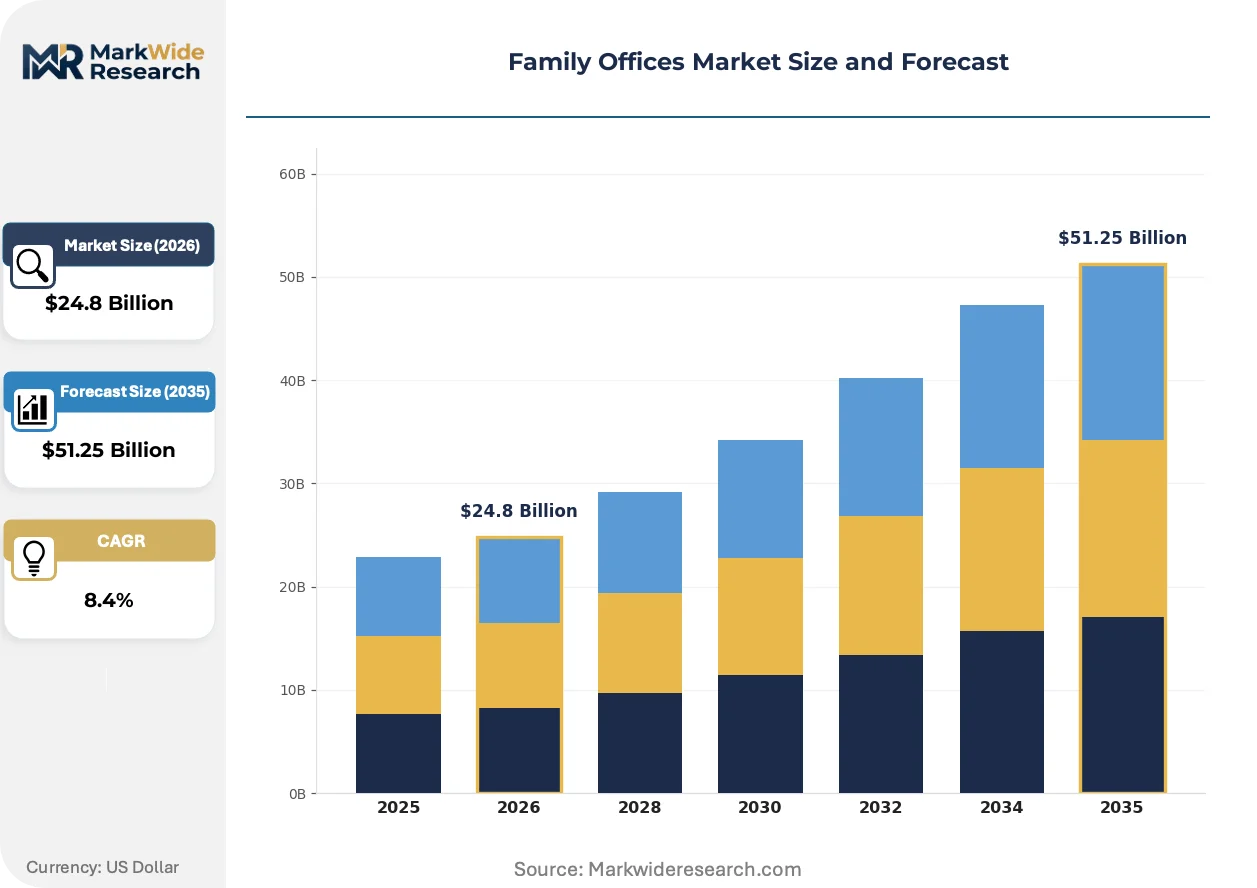
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Growth Equity, Venture Capital, Private Debt, Real Assets, Hedge Funds, Impact Investing Client Type: Single-Family Office, Multi-Family Office, Virtual Family Office, Outsourced Family Office Asset Class: Direct Equity, Fixed Income, Real Estate, Private Equity, Commodities, Cash Equivalents Service Offering: Wealth Preservation, Succession Planning, Tax Advisory, Philanthropy, Risk Management, Estate Planning |
| Companies Covered | Bayshore Global Management, Mousse Partners, Walton Enterprises, Waycrosse, Ballmer Group, Cascade Investment, Pontegadea Inversiones, The Woodbridge Company, Bezos Expeditions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Family Offices Market Trends and Innovations
Family office operations are undergoing structural recalibration as digital infrastructure, regulatory technology, and generational preference shifts compress traditional advisory models.
Blockchain-based asset tokenization is supplanting conventional limited partnership structures for private equity and real estate holdings. Technology founders in Silicon Valley and Austin corridors are demanding fractionalized ownership instruments with automated distribution waterfalls. This shift is compressing administrative overhead and enabling secondary market liquidity for previously locked capital.
The SEC's proposed amendments to the Investment Advisers Act custody rule are mandating enhanced qualified custodian verification for digital assets. Family offices with cryptocurrency allocations must restructure custody relationships or face registration-triggering events. Smaller single-family offices are responding by consolidating into multi-family office platforms with institutional-grade infrastructure.
Heir-led investment committees are rotating capital deployment away from outsourced manager models toward direct co-investment alongside venture capital sponsors. This behavioral shift disrupts traditional fund-of-funds fee structures and concentrates due diligence burden on internal staff. The pattern is most visible among first-generation technology wealth in Seattle and Denver metropolitan areas.
Family Offices Market Segmentation
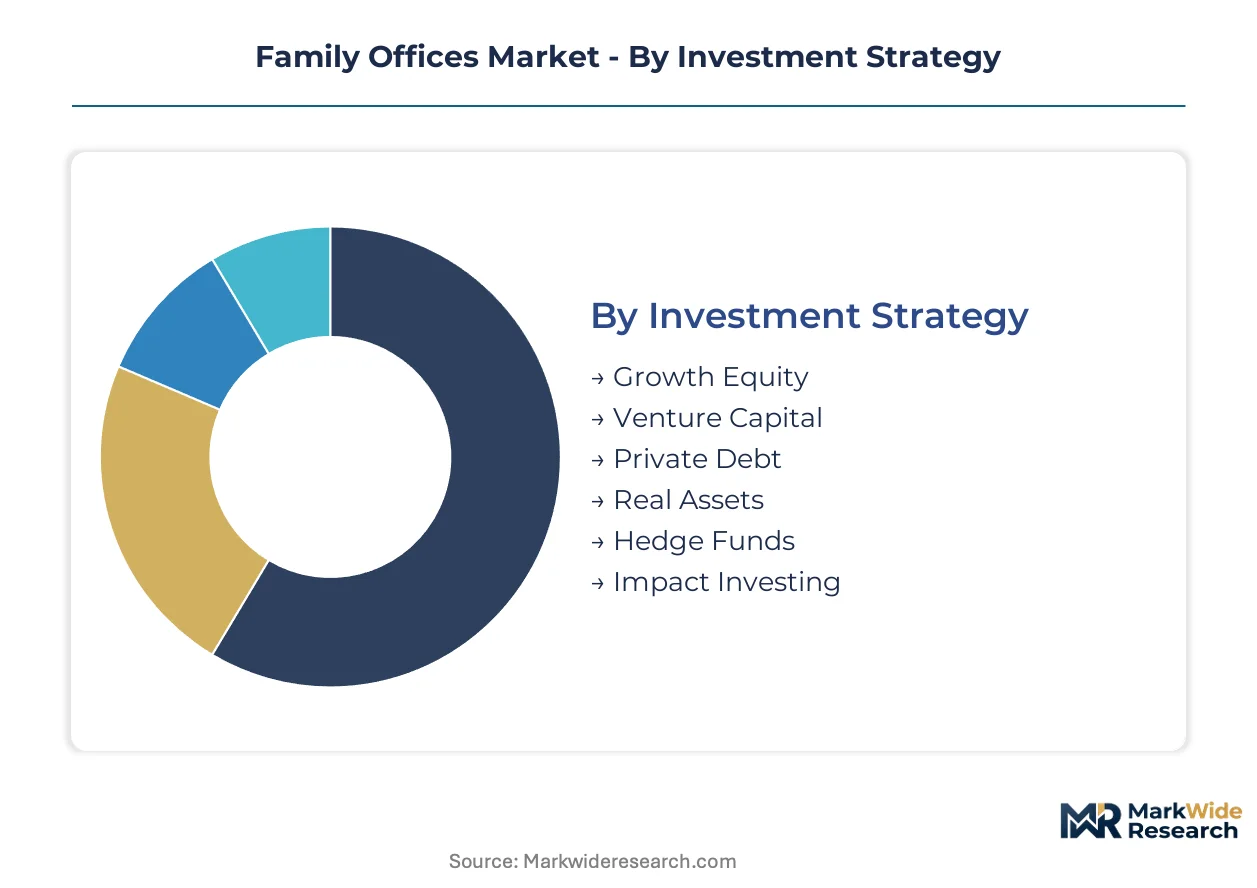
Segmentation in family offices reveals how capital deployment preferences, governance structures, and service requirements fragment across wealth origins and generational priorities. Understanding these divisions exposes where operational scale thresholds and fee intensity concentrate.
Investment Strategy:
Growth Equity and Venture Capital strategies concentrate in Silicon Valley and Austin corridors where technology founder liquidity events dominate. Private Debt and Real Assets strategies cluster around Miami and New York wealth corridors with established institutional infrastructure.
- Growth Equity:Targets mature private companies with proven revenue models, typically deploying $10-50 million per transaction. Demand concentrates among first-generation technology wealth in Seattle and Denver seeking control-oriented positions without full buyout complexity.
- Venture Capital:Early-stage equity deployment in frontier technology sectors with high loss ratios offset by asymmetric return profiles. Silicon Valley single-family offices allocate here most aggressively, driven by founder familiarity with startup operating models.
- Private Debt:Direct lending to middle-market companies seeking non-bank financing alternatives. Miami wealth corridors favor this strategy for yield generation without equity volatility.
- Real Assets:Infrastructure, timber, and agricultural land holdings providing inflation linkage and tangible collateral. Demand clusters among multi-generational wealth in the Northeast seeking intergenerational wealth preservation.
- Hedge Funds:Absolute return strategies employing long-short equity, event-driven, and macro approaches. Single-family offices above $1 billion in assets under management maintain allocations here for portfolio diversification.
- Impact Investing:Measurable social or environmental outcomes alongside financial returns. Next-generation heirs in Boston and San Francisco drive demand here, requiring specialized reporting infrastructure.
Venture Capital holds the largest share; momentum sits with Impact Investing.
Client Type:
Single-Family Offices dominate asset concentration while Multi-Family Offices expand by pooling operational costs across client bases. Virtual and Outsourced models reduce fixed overhead for sub-$200 million wealth bases.
- Single-Family Office:Dedicated staff and infrastructure serving one ultra-high-net-worth family, typically requiring $100 million minimum investable assets to justify overhead. Silicon Valley technology founders establish these at record pace following liquidity events.
- Multi-Family Office:Shared operational platform serving multiple families, spreading compliance and technology costs across pooled assets. Fastest expansion trajectory as sub-$500 million offices consolidate to absorb SEC regulatory burdens.
- Virtual Family Office:Network of independent specialists coordinated without permanent staff, reducing fixed costs. Favored by geographically dispersed families with simpler asset structures.
- Outsourced Family Office:External providers handling investment management, tax planning, and administrative functions. Miami wealth corridor sees particular adoption among relocated technology founders seeking immediate operational capability.
Single-Family Office commands the deepest asset pools; Multi-Family Office is climbing the fastest.
Asset Class:
Direct Equity and Private Equity allocations command the most staff resources and generate highest fee intensity. Fixed Income and Cash Equivalents function as mature, lower-margin stabilizers across wealth corridors.
- Direct Equity:Concentrated public or private company ownership without intermediary fund structures. Cascade Investment exemplifies this approach with disciplined equity concentration and minimal external manager reliance.
- Fixed Income:Government bonds, investment-grade credit, and structured products providing capital preservation and liquidity. Multi-generational offices in the Northeast maintain heavier allocations here for wealth transfer stability.
- Real Estate:Commercial, residential, and development properties including direct ownership and fund investments. Miami and New York corridors concentrate demand for trophy assets and tax-advantaged structures.
- Private Equity:Fund commitments and co-investments in buyout, growth, and venture strategies. Bezos Expeditions competes through aggressive deployment here in frontier technology sectors.
- Commodities:Physical holdings and derivative exposure to energy, metals, and agricultural products. Smaller allocation category serving inflation-hedge objectives for specific family risk profiles.
- Cash Equivalents:Treasury bills, money market instruments, and short-term deposits providing liquidity buffers. Essential component for offices managing private fund capital call obligations.
Direct Equity holds the largest share; Private Equity is gaining share fastest.
Service Offering:
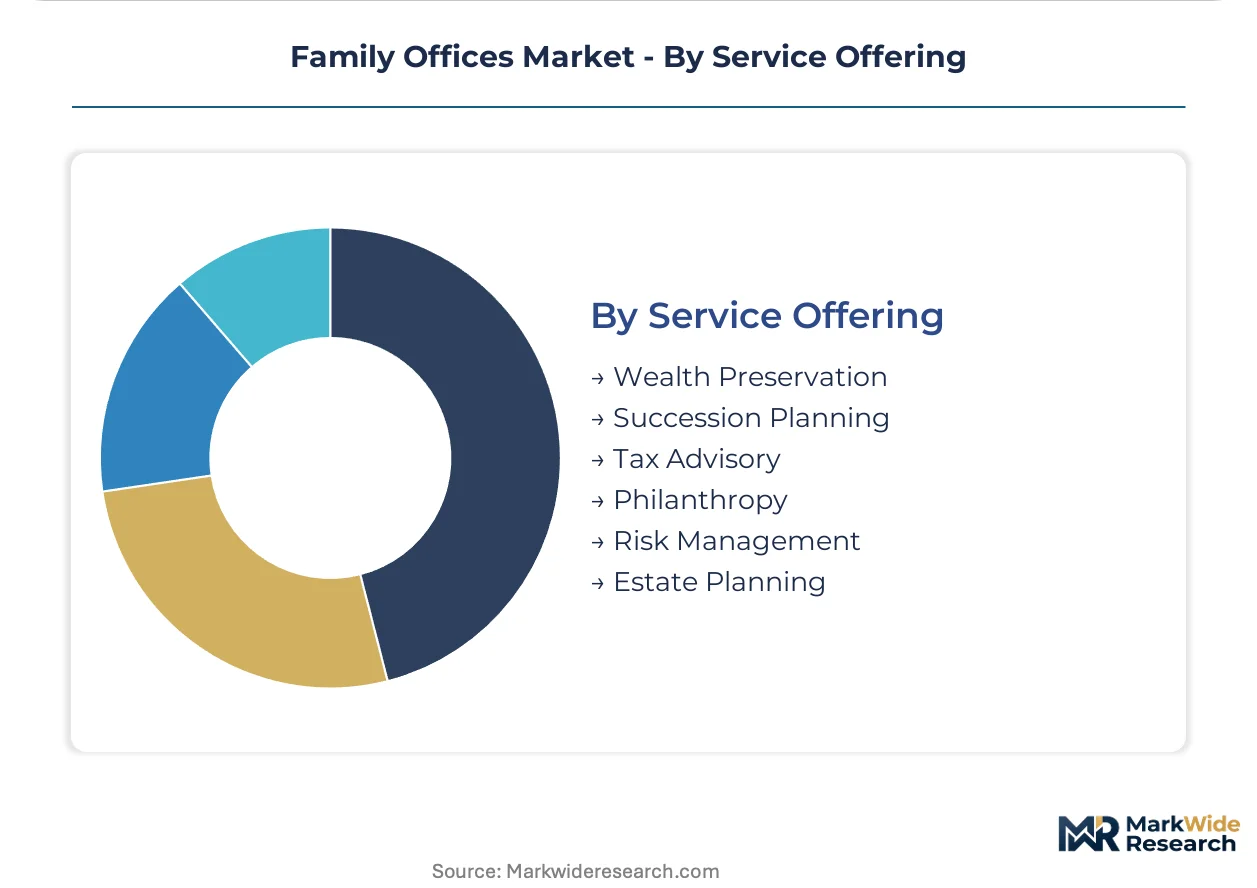
Wealth Preservation and Succession Planning anchor traditional family office mandates. Tax Advisory and Philanthropy services expand as regulatory complexity and next-generation preferences reshape demand.
- Wealth Preservation:Risk management and capital protection strategies prioritizing intergenerational asset maintenance. Walton Enterprises anchors its position through concentrated public equity holdings and long-horizon portfolio construction in this category.
- Succession Planning:Governance structures, next-generation education, and leadership transition protocols. IRS generation-skipping transfer rules directly influence complexity and service intensity here.
- Tax Advisory:Income, estate, and trust optimization across federal, state, and international jurisdictions. Florida's absence of state income tax drives relocation decisions and associated service demand.
- Philanthropy:Charitable foundation management, donor-advised funds, and impact measurement. Next-generation heirs rotate capital deployment here away from traditional wealth preservation toward measurable social outcomes.
- Risk Management:Insurance structuring, liability mitigation, and cybersecurity architecture. Ransomware operators targeting concentrated wealth repositories elevate this service priority.
- Estate Planning:Trust structuring, asset titling, and wealth transfer execution. Intergenerational transfers involving operating businesses and illiquid private fund interests require specialized legal coordination.
Wealth Preservation holds the largest share; Philanthropy is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable network and private aviation infrastructure at Miami-Opa Locka Executive Airport underwrite North America's dominance in family office concentration. These assets enable real-time portfolio management and rapid principal mobility across wealth corridors.
United States
Technology founder liquidity events in Silicon Valley and Seattle generate single-family office formations at record velocity. The SEC's Form PF disclosure requirements and expanded accredited investor definitions reshape operational compliance thresholds for sub-$500 million offices. Miami's absence of state income tax attracts relocating technology principals, concentrating new office establishment in Florida's wealth corridor.
Switzerland
Multi-generational European wealth maintains Zurich and Geneva as private banking integration hubs for cross-border succession planning. Swissmedic and the Swiss Federal Banking Commission enforce custody and disclosure standards that exceed EU baseline requirements. The Lake Geneva region concentrates family office service providers specializing in trust structuring for international asset holders.
Singapore
Southeast Asian family wealth migration drives demand for English-law trust structures and Asian private equity co-investment platforms. The Monetary Authority of Singapore's Variable Capital Company framework streamlines fund domiciliation for family investment vehicles. The Marina Bay financial district anchors regional headquarters for multi-family offices serving Indonesian and Malaysian family principals.
United Kingdom
London's legal infrastructure and time zone positioning sustain its role as European deal flow coordination center for direct private equity deployment. The Financial Conduct Authority's investment adviser registration regime imposes operational scale thresholds comparable to SEC requirements. Mayfair and Knightsbridge concentrate single-family offices serving Middle Eastern and Russian wealth with specialized cultural liaison staffing.
United Arab Emirates
Zero personal income taxation and concentrated luxury real estate development attract family office relocation from European high-tax jurisdictions. The Dubai International Financial Centre's regulatory framework permits 100% foreign ownership of investment advisory entities. Abu Dhabi's sovereign wealth proximity creates co-investment opportunities for family offices seeking infrastructure and energy transition exposure.
Family Offices Market Competitive Landscape
Listed investment vehicles compete with privately held family office structures across operational flexibility and disclosure burden. The market fragments across three tiers: billionaire-founded single-family offices with concentrated equity positions, multi-family office platforms pooling compliance infrastructure, and outsourced providers serving sub-$200 million wealth bases. Strategic differentiation centers on direct co-investment capability, next-generation governance technology, and specialized sector expertise in technology or healthcare deployment.
Within the technology-founder archetype, Bezos Expeditions and Cascade Investment exemplify concentrated equity strategies with minimal external manager reliance. Walton Enterprises anchors the multi-generational wealth preservation tier through long-horizon public equity construction. Bayshore Global Management represents the outsourced specialist model serving principals seeking immediate operational capability without dedicated staff infrastructure.
| Leading Market Players |
|---|
| Bayshore Global Management |
| Mousse Partners |
| Walton Enterprises |
| Waycrosse |
| Ballmer Group |
| Cascade Investment |
| Pontegadea Inversiones |
| The Woodbridge Company |
| Bezos Expeditions |
| Others |
Pricing and Supply Chain Analysis
Technology platform substitution for legacy relationship-based advisory models is redrawing talent geography and compressing fee economics across the family office sector. Cloud-based portfolio management systems from Silicon Valley vendors displace Manhattan-headquartered custodian relationships, simultaneously reducing operational overhead thresholds and enabling Miami-based offices to compete on price with established Northeast competitors.
Pricing Analysis
Volume-discount tiering structures stratify family office services across asset thresholds, with single-family offices above $500 million capturing preferential custody rates and reduced Form PF compliance costs per dollar managed. Three-tier pricing separates white-glove dedicated staff arrangements from pooled multi-family platforms and virtual outsourced models, with customization level and principal-to-staff ratio as primary differentiation drivers. Pricing pressure stems from direct indexing technology automating tax-loss harvesting previously requiring external manager fees. Sub-$200 million wealth bases exhibit highest price sensitivity, driving consolidation into multi-family platforms.
Supply Chain Analysis
Inventory and lead-time compression in talent acquisition now defines competitive positioning, with experienced family office executives requiring 6-12 month search cycles in New York and London. Geographic supply concentrates in the United States, Switzerland, and Singapore, each anchoring distinct regulatory expertise pools. Raw material dependencies include qualified custodian relationships, trust and estate legal specialization, and cybersecurity infrastructure. Single-source vulnerability in executive talent creates retention risk during generational transition events. Distribution runs through private banking networks, wealth management platforms, and direct founder-to-founder referral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The family office market is entering a cyclical recovery phase as technology founder liquidity events in Silicon Valley and Austin regenerate formation velocity after regulatory compliance cost compression.
For Market Incumbents: Consolidate compliance infrastructure across multiple family principals to absorb SEC Form PF fixed costs, or acquire specialized technology platforms offering AI-driven consolidated reporting. The threat of next-generation heirs rotating capital toward direct co-investment models erodes traditional fund-of-funds fee structures. Vertical integration into in-house venture deployment capabilities defends margin position against outsourced manager displacement. For New Entrants and Emerging Players: Differentiate on impact measurement infrastructure as EU Sustainable Finance Disclosure Regulation and proposed SEC climate rules create first-mover advantages. The most penetrable segment sits with next-generation heirs in Boston and San Francisco demanding specialized ESG data capabilities. A go-to-market angle targeting healthcare entrepreneurship corridors with dedicated biotech venture expertise captures founder liquidity event timing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-family office platforms that consolidated during regulatory cost escalation. Long-term viability over a 5-10 year window hinges on technology-enabled scale economics overcoming talent concentration inflation. The signal to watch is cryptocurrency custody regulation clarity triggering digital asset allocation mandates across previously sidelined principals.| Strategic Initiative | Industry Significance |
|---|---|
| Next-Generation Governance Platform Deployment | AI-driven consolidated reporting systems enable multi-family offices to serve previously uneconomical asset thresholds. |
| Direct Co-Investment Capability Buildout | In-house venture deployment teams capture fee savings and control advantages over outsourced fund commitments. |
| Impact Measurement Infrastructure Investment | Integrated ESG data systems secure first-mover positioning under evolving EU and SEC disclosure regimes. |
| Miami Wealth Corridor Establishment | Florida's absence of state income tax attracts technology founder relocations and associated office formations. |
| Cybersecurity Architecture Modernization | Institutional-grade security systems defend against ransomware operators targeting concentrated wealth repositories. |
Research Methodology
Operator-level perspectives from family office chief investment officers, trust and estate attorneys, custody relationship managers, and next-generation board members anchored the qualitative base. Primary interviews combined with secondary validation from SEC Form ADV filings, IRS estate tax statistics, and private aviation infrastructure utilization data. Bottom-up asset formation estimates triangulated against top-down wealth concentration metrics from Federal Reserve Survey of Consumer Finances.
Sensitivity analysis across regulatory compliance cost scenarios and technology adoption curves shaped the projection framework. Segmentation dimensions modeled include client type, investment strategy, asset class, and service offering across the analysis window. CAGRs derived from historical formation velocity in technology entrepreneurship corridors and projected liquidity event timing. Forecast inputs incorporated SEC rulemaking timelines and cryptocurrency custody framework evolution.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and technology platform substitution rates; material deviation in SEC accredited investor thresholds or custody rule amendments would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Smart Wealth Management Market