
 India Construction Market | 2026-2036
India Construction Market Size, Share, and Industry Trends Forecast 2026-2036
India Construction Market Outlook
The BIS certification mandate for construction materials is rebalancing the cost-of-entry calculus for new contractors across India. Larsen & Toubro Limited leverages its in-house testing infrastructure to preempt compliance costs. Tata Projects Limited anchors its bidding strategy on pre-certified supply chains. Shapoorji Pallonji and Company Limited differentiates through legacy relationships with BIS-accredited laboratories.
India Construction encompasses the physical assembly of buildings, transport networks, and utility systems using cementitious binders, structural steel with specified yield strengths, and engineered glass composites. The sector delivers habitable space, logistics capacity, and energy distribution infrastructure to a population exceeding one billion. Residential project types command the largest volume share as urban migration intensifies. Infrastructure project types represent the fastest expansion corridor, driven by dedicated freight corridors and metro rail commitments. Cement as a material category dominates absolute consumption, though sustainable design technology is capturing premium-margin contracts from government and institutional end users.
The Ministry of Housing and Urban Affairs, BIS, and the National Green Tribunal collectively enforce building codes, material standards, and environmental clearances that determine project viability timelines. The Real Estate Regulatory Authority framework in each state mandates disclosure protocols that reshape developer financing structures. Stakeholders must monitor how state-level RERA enforcement variance affects capital deployment across Maharashtra, Karnataka, and Tamil Nadu.
Market Dynamics
The BIS certification mandate for steel and cement is compressing contractor margins while redistributing competitive advantage toward testing-capable incumbents across Maharashtra, Gujarat, and Tamil Nadu.
Growth Catalysts
- Delhi-Mumbai Industrial Corridor nodes:Dedicated freight corridors and industrial townships are pulling cement and structural steel demand into contiguous urban infrastructure belts.
- Affordable Housing for All:Central government outlays for low-income residential units are expanding project pipelines in Pune, Ahmedabad, and Nagpur metropolitan rings.
- Metro rail commitments:State urban development authorities in Karnataka, Maharashtra, and Telangana are tendering underground and elevated corridor packages.
Market Restraints
- Petroleum-based input cost volatility:Bitumen and polymer-modified binder prices track crude fluctuations, destabilizing road contractor margins.
- Domestic steel supply concentration:Integrated primary producers control rebar and structural section availability, limiting secondary fabricator bargaining power.
- BIS certification timeline friction:Laboratory testing queues for cement grade validation extend project mobilization schedules by 8-14 weeks.
Strategic Opportunities
- Green building certification tailwind:GRIHA and IGBC rating mandates for government buildings are opening premium-margin contracts for low-carbon concrete specialists.
- Prefabrication technology convergence:Modular panel systems are converging with building information modeling to compress high-rise residential cycle times.
- Tier-2 city corridor expansion:Indore, Surat, and Coimbatore municipal corporations are floating integrated water supply and sanitation packages.
Industry Challenges
- Skilled formwork and finishing labor scarcity:Migration disruptions have thinned specialized trades in Kerala and Punjab, forcing wage escalation.
- Legacy project management system integration:RERA-mandated disclosure portals require data reconfiguration from fragmented developer ERP environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Construction Market |
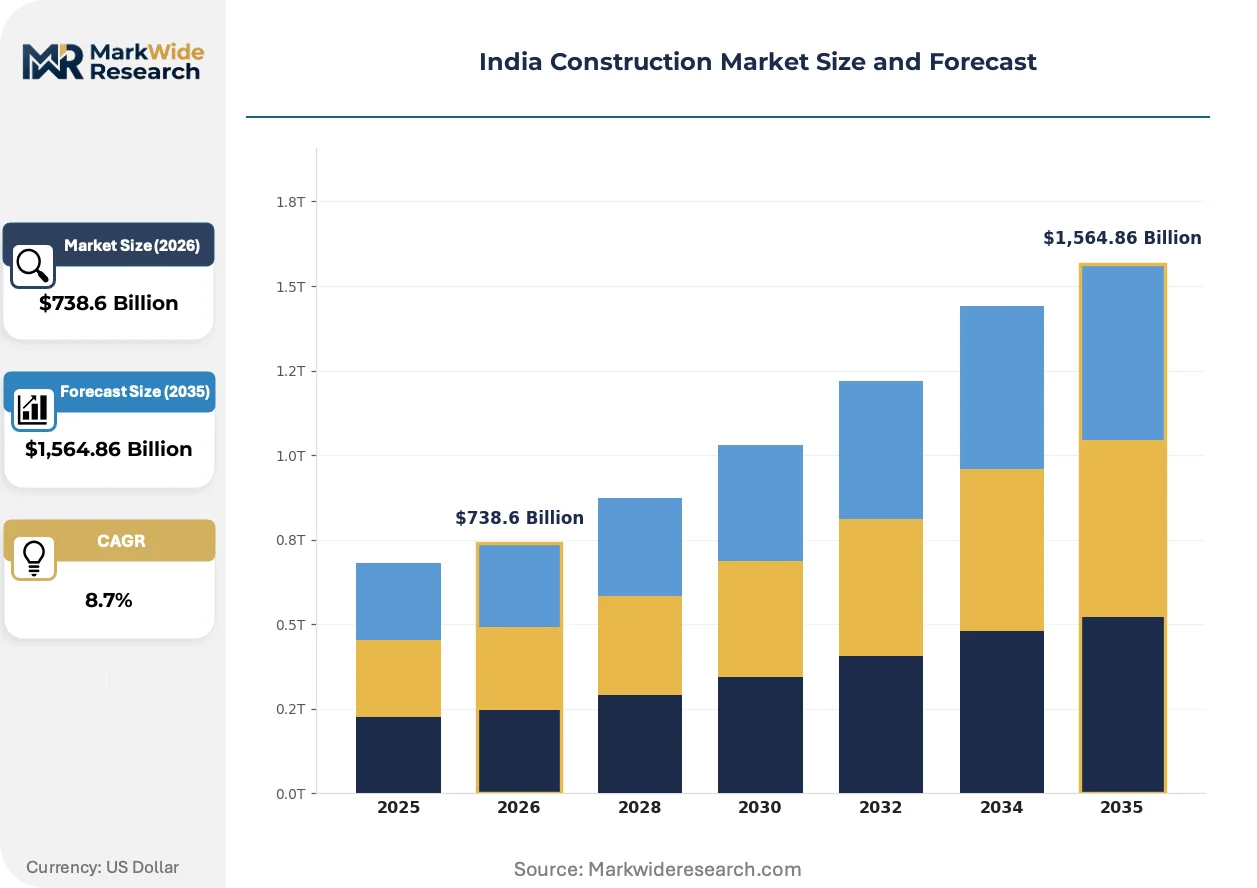
| Market Size in 2026 | $738.6 Billion |
| Market Size in 2035 | $1,564.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material: Cement, Steel, Wood, Glass End User: Developers, Contractors, Homeowners, Government Technology: 3D Printing, Prefabrication, Building Information Modeling, Sustainable Design |
| Companies Covered | Hindustan Construction Company Limited, Shapoorji Pallonji and Company Limited, Larsen & Toubro Limited, Gammon India Limited, GMR Group, Tata Projects Limited, Reliance Infrastructure Limited, NKC Projects Private Limited, Nagarjuna Construction Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Construction Market Strategic Shifts
Material science advances and digital coordination tools are compressing construction cycle timelines while elevating quality assurance thresholds across Indian state urban development authorities.
Geopolymer concrete formulations are converging with supplementary cementitious material blending to reduce clinker content while maintaining compressive strength ratings. National highway and metro rail authorities are specifying these mixes for marine and sulfate-exposure environments. The technology is converging with automated batching controls to enable real-time quality verification.
BIS certification mandates for structural steel and Portland cement are tightening material traceability requirements nationwide. Contractors must now document mill test certificates and third-party laboratory validation for each consignment. Large infrastructure packages in the Delhi-Mumbai Industrial Corridor are requiring pre-approved manufacturer lists, compressing supplier eligibility pools.
State RERA portals are mandating quarterly project progress disclosure with photographic and financial milestone verification. Institutional financiers and retail homebuyers are using this data to accelerate pre-sale decisions in Mumbai and Bangalore. Tier-1 developers are deploying drone-based site monitoring to generate compliant documentation with reduced field supervisor overhead.
India Construction Market Segmentation
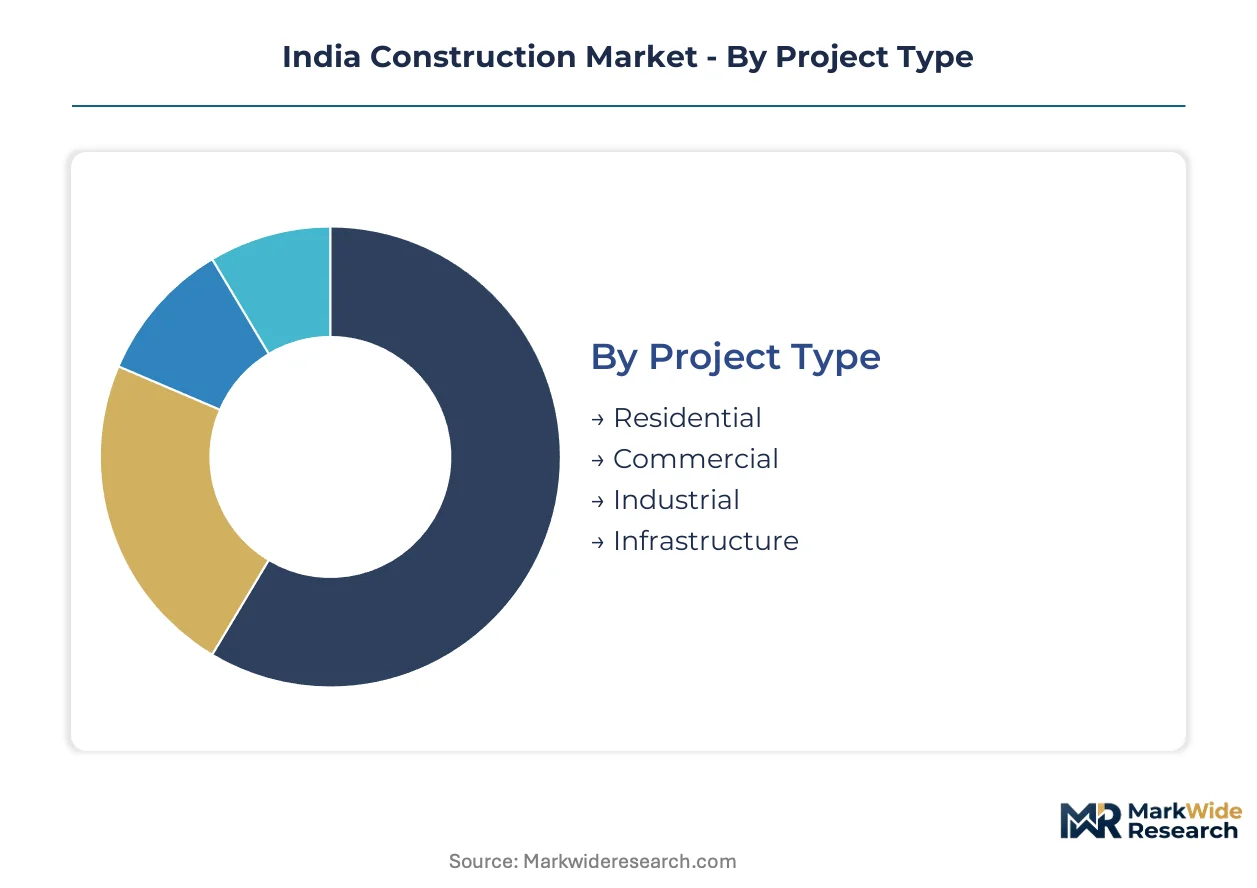
Segmentation in the India Construction Market reveals how project scale, material selection, and procurement authority determine margin structures and competitive positioning. Each dimension carries distinct regulatory exposure and capital intensity profiles.
Project Type:
Volume dominance rests with mass housing, while premium margins concentrate in specialized infrastructure packages.
- Residential:Affordable housing programs in Maharashtra and Gujarat drive cement and rebar consumption at scale. Municipal corporations in Pune, Ahmedabad, and Nagpur metropolitan rings are releasing contiguous land parcels for low-income unit construction.
- Infrastructure:Dedicated freight corridors and metro rail commitments pull structural steel and engineered concrete demand into urban belts. Delhi-Mumbai Industrial Corridor nodes command pre-approved manufacturer lists and BIS-certified supply chains.
- Commercial:Office and retail developments in Bangalore and Hyderabad track IT/ITES employment density.
- Industrial:Warehouse and manufacturing shell construction concentrates in Gujarat and Tamil Nadu port-linked zones.
Mature deployment sits with Residential. Newer deployment is concentrated in Infrastructure.
Material:
Cost tier stratification separates commodity bulk from specification-grade imports.
- Cement:Portland and blended varieties dominate absolute consumption across all project categories. BIS certification queues for grade validation extend mobilization schedules by 8-14 weeks, compressing contractor liquidity.
- Steel:Rebar and structural sections face supply concentration among integrated primary producers. Secondary fabricators in secondary cities encounter limited bargaining power against mill-direct pricing.
- Wood:Engineered timber and treated softwood gain specification in Kerala and Karnataka hospitality projects.
- Glass:Coated and laminated composites command premium margins in commercial facade contracts.
Commodity-grade supply concentrates in Cement. Performance-specified procurement is climbing fastest in Glass.
End User:
Procurement authority determines disclosure obligation depth and financing structure complexity.
- Government:Central and state urban development authorities mandate GRIHA and IGBC ratings for public buildings. Low-carbon concrete specialists capture premium-margin contracts through pre-qualification requirements.
- Developers:Tier-1 firms deploy drone-based site monitoring to satisfy RERA quarterly disclosure mandates. Mumbai and Bangalore institutional financiers accelerate pre-sale decisions using portal-verified progress data.
- Contractors:Margin pressure from BIS certification timelines forces testing-capable incumbents to absorb compliance costs.
- Homeowners:Individual residential construction in tier-2 cities depends on informal labor markets and uncertified material channels.
Institutional procurement maturity sits with Government. Individual-scale activity is expanding most quickly among Homeowners in Surat, Indore, and Coimbatore corridors.
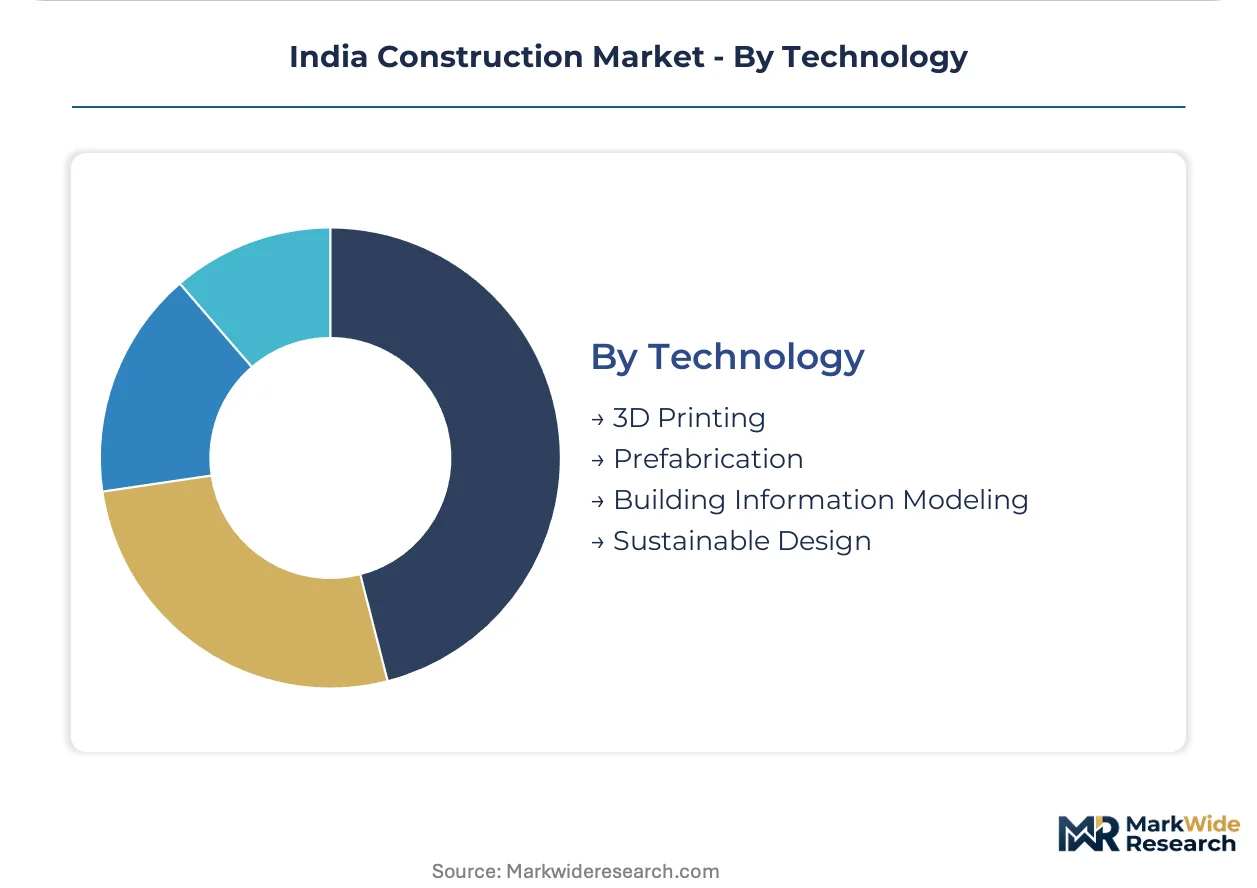
Technology:
Adoption depth correlates with project scale and state-level urban development authority technical capacity.
- Building Information Modeling:Digital coordination tools compress high-rise residential cycle times when converged with modular panel systems. State tendering authorities in Karnataka and Telangana now mandate BIM deliverables for metro rail packages.
- Sustainable Design:Geopolymer concrete formulations with supplementary cementitious material blending reduce clinker content. National highway authorities specify these mixes for marine and sulfate-exposure environments.
- Prefabrication:Modular panel systems penetrate affordable housing programs where repetition enables factory economics.
- 3D Printing:Contour crafting and binder jetting remain demonstration-scale, constrained by material certification gaps and skilled technician scarcity.
Established implementation sits with Building Information Modeling. Steepest expansion trajectory belongs to Sustainable Design as green building mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delhi-Mumbai Industrial Corridor special investment nodes concentrate cement and structural steel procurement into contiguous urban infrastructure belts across western and central India.
Maharashtra
Pune and Nagpur metropolitan rings release contiguous land parcels for affordable housing programs under central government outlays. Mumbai's municipal corporation enforces RERA-mandated quarterly disclosure portals with photographic milestone verification. The Mumbai-Pune expressway corridor anchors dedicated freight corridor packages pulling pre-certified manufacturer demand.
Gujarat
Ahmedabad's urban development authority tenders integrated water supply and sanitation packages for metropolitan expansion. BIS certification queues for cement grade validation compress contractor mobilization schedules by 8-14 weeks. Surat municipal corporation floats sanitation infrastructure contracts attracting tier-2 city corridor investment.
Karnataka
Bangalore's IT/ITES employment density tracks commercial office and retail development pipelines. State urban development authorities mandate BIM deliverables for metro rail underground and elevated corridor packages. Institutional financiers accelerate pre-sale decisions using RERA portal-verified progress data.
Tamil Nadu
Chennai port-linked zones concentrate warehouse and manufacturing shell construction for industrial project types. BIS certification mandates for structural steel tighten material traceability requirements for consignment documentation. Coimbatore municipal corporations float integrated water supply packages expanding tier-2 city infrastructure.
Telangana
Hyderabad state urban development authorities tender metro rail corridor packages with pre-approved manufacturer list requirements. Geopolymer concrete specifications for marine exposure environments converge with automated batching controls for real-time quality verification. Drone-based site monitoring generates RERA-compliant documentation with reduced field supervisor overhead.
India Construction Market Competitive Environment
Mumbai-based conglomerates anchor one tier; Delhi-NCR and Chennai specialists hold regional infrastructure niches. The contractor base stratifies across testing-capable incumbents absorbing BIS compliance costs and smaller fabricators facing laboratory queue friction. Three archetypes dominate: diversified engineering conglomerates with in-house certification infrastructure, project specialists leveraging pre-certified supply chains, and regional contractors differentiating through legacy BIS-accredited laboratory relationships. Competitive moves concentrate on strategic partnerships for supply chain pre-qualification and geographic expansion into tier-2 municipal corridors.
Among diversified engineering conglomerates, Larsen & Toubro Limited and Tata Projects Limited exemplify contrasting compliance strategies. Larsen & Toubro Limited occupies a position representing in-house testing infrastructure deployment to preempt certification timeline costs. Tata Projects Limited anchors the pre-certified supply chain archetype, bidding strategy converging on manufacturer relationships that bypass laboratory queue friction. Shapoorji Pallonji and Company Limited sits within the legacy relationship tier, differentiation flowing from established BIS-accredited laboratory networks rather than captive testing capacity.
| Leading Market Players |
|---|
| Hindustan Construction Company Limited |
| Shapoorji Pallonji and Company Limited |
| Larsen & Toubro Limited |
| Gammon India Limited |
| GMR Group |
| Tata Projects Limited |
| Reliance Infrastructure Limited |
| NKC Projects Private Limited |
| Nagarjuna Construction Company Limited |
| Others |
Value Chain & Pricing Dynamics
Captive in-house testing infrastructure at diversified engineering conglomerates anchors both supply security and pricing power across Maharashtra and Gujarat project corridors. Contractors absorbing BIS certification costs through captive laboratories command premium positioning while competitors queue at accredited facilities.
Pricing Analysis
Short-lead-time premiums dominate contractor bidding strategies as BIS laboratory queues extend mobilization schedules. Project-based pricing stratifies across certified and uncertified material tiers, with government packages mandating pre-approved manufacturer lists that compress supplier eligibility. Cost compression in commodity cement and rebar runs through petroleum-based input volatility and domestic steel supply concentration. Tier-2 city municipal corporations exhibit highest price sensitivity, while Delhi-Mumbai Industrial Corridor nodes accept specification-grade premiums for traceability documentation.
Supply Chain Analysis
Domestic-content mandates under BIS certification protocols are reshaping sourcing toward integrated primary steel producers and accredited cement manufacturers. Supply draws from concentrated domestic production clusters in Gujarat, Maharashtra, and Tamil Nadu, with engineered glass composites and polymer-modified binders sourcing from specialized regional fabricators. Raw material dependencies rest on clinker imports, metallurgical coke, and bitumen derivatives. Single-source vulnerability concentrates around integrated steel mills controlling rebar availability. Distribution feeds through project-site direct delivery with mill test certificate documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Construction Market sits in a technology-transition phase as Building Information Modeling displaces legacy CAD coordination across Karnataka and Telangana metro rail tenders.
For Market Incumbents: Extend in-house testing infrastructure into tier-2 municipal corridors to preempt BIS certification timeline friction. Absorb compliance costs through captive laboratory capacity while competitors face 8-14 week mobilization delays. Anchor bidding strategies on pre-certified manufacturer relationships that bypass supply concentration at integrated steel mills.
For New Entrants and Emerging Players: Capture white-space in Surat, Indore, and Coimbatore integrated water supply packages where legacy contractor relationships remain underdeveloped. Penetrate geopolymer concrete specialization for marine exposure environments as national highway authorities harden sustainable design mandates. Lead go-to-market through automated batching control partnerships with municipal corporations.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by diversified engineering conglomerates seeking testing-capable regional platforms. Long-term viability favors contractors with backward integration into BIS-accredited laboratory networks. Watch drone-based site monitoring adoption rates as inflection indicator for RERA compliance automation.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Infrastructure Investment | Captive laboratory capacity preempts 8-14 week mobilization delays at accredited facilities. |
| Pre-certified Supply Chain Partnerships | Manufacturer relationships bypass steel mill concentration and cement grade validation queues. |
| Geopolymer Concrete Specialization | Low-carbon mix expertise captures GRIHA-mandated government building premiums. |
| BIM-Deliverable Capability Buildout | Digital coordination tools satisfy Karnataka and Telangana metro rail tender requirements. |
| Tier-2 City Corridor Expansion | Surat and Coimbatore municipal packages offer first-mover positioning before incumbent saturation. |
Study Parameters
Ministry of Housing and Urban Affairs circulars, BIS certification databases, and state RERA portal disclosures formed the secondary backbone for this analysis. Primary interviews with project directors at diversified engineering conglomerates, procurement leads at state urban development authorities, and laboratory managers at BIS-accredited facilities validated segment assumptions. Customs records for cement and steel imports, National Highway Authority tender documents, and municipal corporation budget allocations provided demand-side triangulation against bottom-up project pipeline enumeration.
Bottom-up enumeration of announced project values across residential, infrastructure, commercial, and industrial categories converged with top-down macroeconomic elasticity modeling. Segmentation dimensions spanned project type, material category, end-user procurement authority, and technology adoption depth. CAGRs were derived from trend-line fitting against historical completion data and announced pipeline values. Forecast inputs incorporated BIS certification timeline friction, petroleum-based input cost volatility, and green building mandate acceleration.
The model holds under continued BIS enforcement intensity and affordable housing program continuity; deviation in regulatory relaxation or central government outlay reduction would shift trajectory. Forecasts reflect documented assumptions regarding material traceability requirement permanence and state-level RERA portal operationalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
India Prefabricated Buildings Market
Building Construction
Thailand Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
France Prefab Homes Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
Malaysia Construction Market
Building Construction
GCC Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Modular and Portable Building Market
Building Construction
China Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Indonesia Construction Market