
 Europe Prefab Wood Buildings Market | 2026-2036
Europe Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Prefab Wood Buildings Market Insights
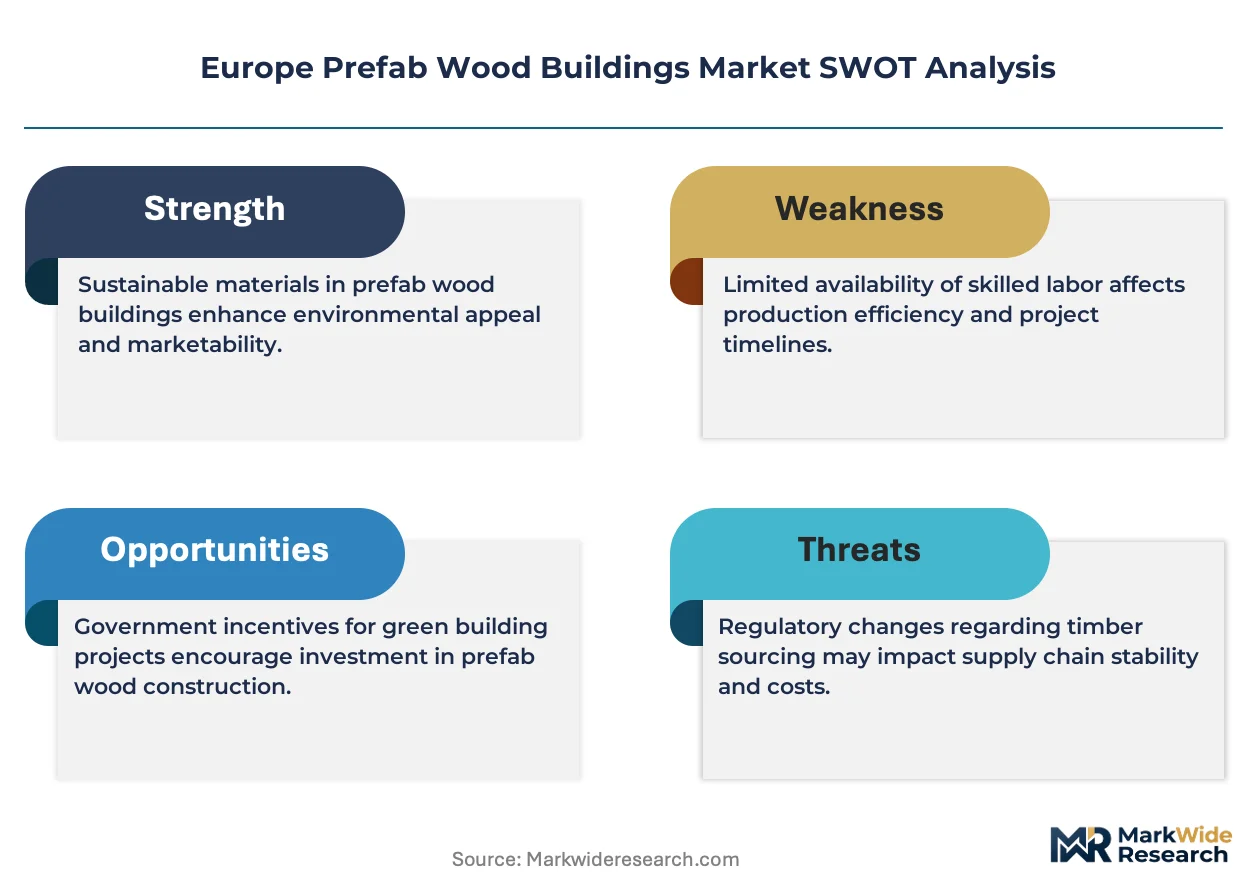
EU Green Deal construction benchmarks are decoupling cost structures from traditional concrete and steel baselines. Lindbäcks Bygg AB anchors its output in Sweden's Norrland timber corridor, leveraging fully automated factory lines to compress delivery cycles. Moelven Byggmodul AB dominates Nordic public-sector procurement through captive sawmill capacity, while ELK Fertighaus GmbH specializes in precision-engineered wall systems for Central European climate zones.
Europe prefab wood buildings are structural assemblies manufactured off-site using engineered wood products such as cross-laminated timber and glulam, with moisture content typically controlled below 20 percent during fabrication to ensure dimensional stability. These systems serve residential and commercial end users seeking reduced on-site labor exposure and predictable construction schedules. Modular Homes command the deepest contractor relationships through repeatable floor plans and standardized foundation interfaces, while Panelized Systems capture margin pools from custom architectural specifications requiring field flexibility. Tiny Houses remain a niche with concentrated demand from rural hospitality operators and accessory dwelling unit ordinances in France and Portugal.
REACH chemical compliance, CE marking for structural timber products, and national building codes under the EU Construction Products Regulation shape material certification pathways and cross-border market access. ECHA scrutiny of wood preservatives and flame retardants is forcing reformulation of factory-applied treatments, adding qualification layers for suppliers outside the European Economic Area. Buyers and manufacturers must track evolving national derogations on tall wood structures as each member state transposes the revised Eurocode 5 standards at different speeds.
Market Dynamics
EU Green Deal embodied carbon mandates are compressing the competitive window for concrete and steel alternatives, forcing residential developers to requalify supply chains around mass timber engineering and factory-controlled moisture specifications.
Growth Catalysts
- EU Green Deal construction benchmarks:Binding limits on embodied carbon in building materials are disqualifying traditional concrete and steel from public procurement in Germany and Sweden.
- Cross-laminated timber engineering:Advances in panel lamination and CNC cutting are collapsing factory-to-occupancy timelines for mid-rise residential towers.
- Industrialized forest belt concentration:Sweden's Norrland region offers captive softwood supply chains with integrated drying, treating, and finishing capabilities.
Market Restraints
- Adhesive cost volatility:Polyurethane and melamine resin prices fluctuate with petrochemical feedstock markets, compressing margins on engineered wood products.
- CE marking complexity:Divergent national transposition timelines for revised Eurocode 5 standards create cross-border certification friction between member states.
- Concrete foundation legacy:Existing contractor networks and building codes in Southern Europe perpetuate slab-on-grade construction despite timber superstructure compatibility.
Strategic Opportunities
- Portuguese ADU ordinances:Municipal zoning reforms in Lisbon and Porto are legalizing accessory dwelling units, opening a channel for compact prefab wood systems.
- Digital fabrication convergence:Integration of BIM-to-CNC workflows with automated panel assembly is enabling mass customization at batch production economics.
- Nordic public-sector procurement:Swedish and Norwegian state housing agencies are mandating timber content thresholds in social housing tenders.
Industry Challenges
- Moisture management expertise:Site crews lack training in vapor barrier sequencing and seasonal acclimation protocols for engineered wood panels.
- Factory capex intensity:Automated pressing lines and climate-controlled curing chambers require eight-figure capital commitments with five-year payback horizons.
- ECHA chemical reformulation:Wood preservative and flame retardant qualification timelines are extending factory certification cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Prefab Wood Buildings Market |
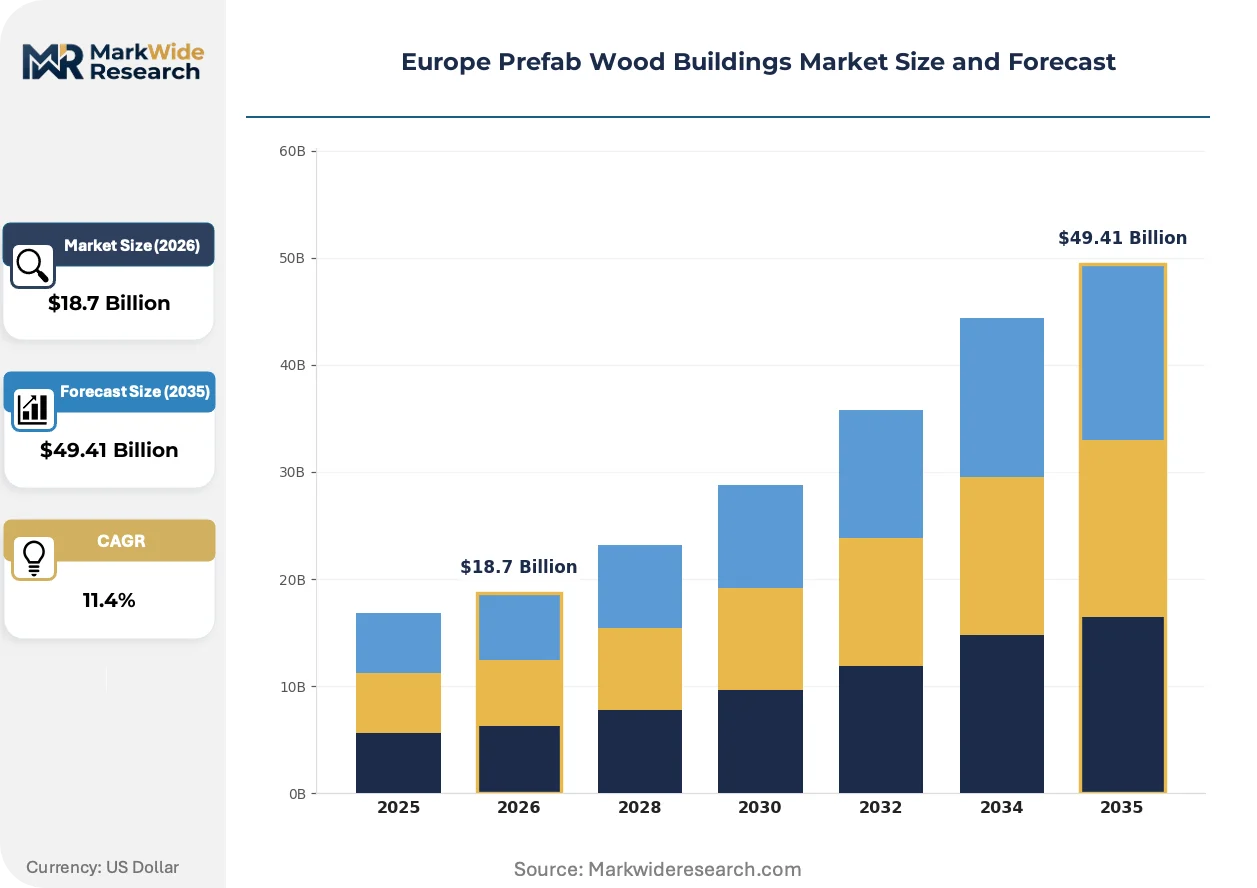
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Tiny Houses, Prefab Cottages, Multi-Family Units End User: Residential Customers, Contractors, Developers, Government Projects Construction Method: Sustainable Building, Energy-Efficient Solutions, Traditional Framing, Panelized Systems Building Size: Small Scale, Medium Scale, Large Scale, Custom Builds |
| Companies Covered | OBOS Bostadsutveckling AB, Alvsbyhus AB, Lindbäcks Bygg AB, Huscompagniet A/S, DFH Group, Moelven Byggmodul AB, ELK Fertighaus GmbH Zweigniederlassung Dtl, Peab AB, Derome Husproduktion AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Prefab Wood Buildings Market Trends and Innovations
Digital thread technologies are dissolving the boundary between architectural design and factory floor control, enabling real-time production adjustments that match panel outputs to site-specific foundation tolerances.
Cross-laminated timber is overtaking glulam beams as the primary structural system for five-to-twelve-story residential construction. German and Austrian developers are specifying CLT cores for elevator shafts and stairwells in multi-family projects. This material shift is compressing structural engineering review cycles and reducing crane-time on tight urban sites.
REACH chemical scrutiny is forcing reformulation of factory-applied wood treatments across the European Economic Area. ECHA's expanded candidate list for substances of very high concern is disqualifying legacy boron and chrome-based preservatives. Suppliers in Finland and Austria are accelerating bio-based alternatives through accelerated weathering protocols to maintain CE marking validity.
General contractors are bundling design, fabrication, and assembly into single-source agreements that displace traditional subcontractor tiers. French and Belgian residential developers are awarding turnkey timber frame contracts to factory operators with captive erection crews. This channel consolidation is most visible in the Rhine-Ruhr corridor, where labor cost arbitrage favors integrated delivery over fragmented procurement.
Europe Prefab Wood Buildings Market Segmentation
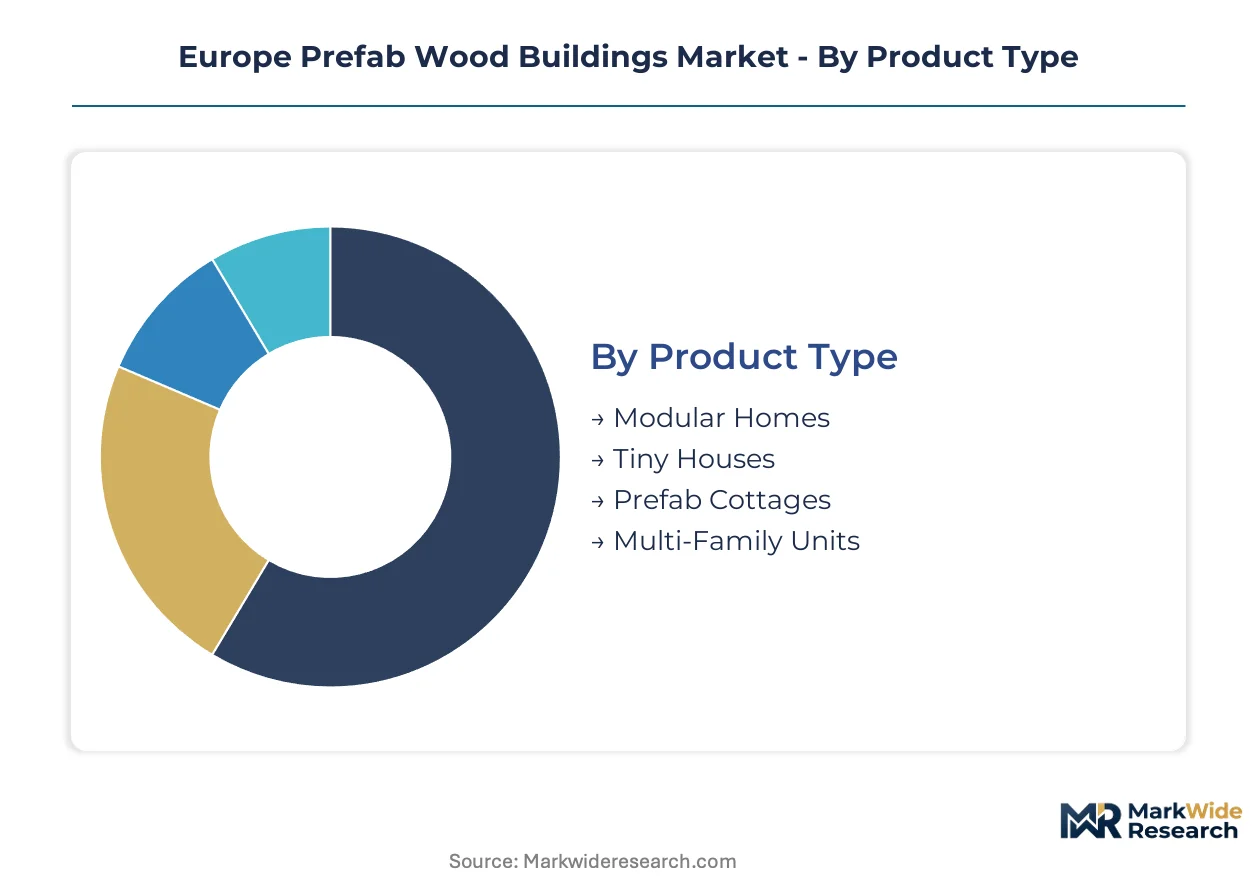
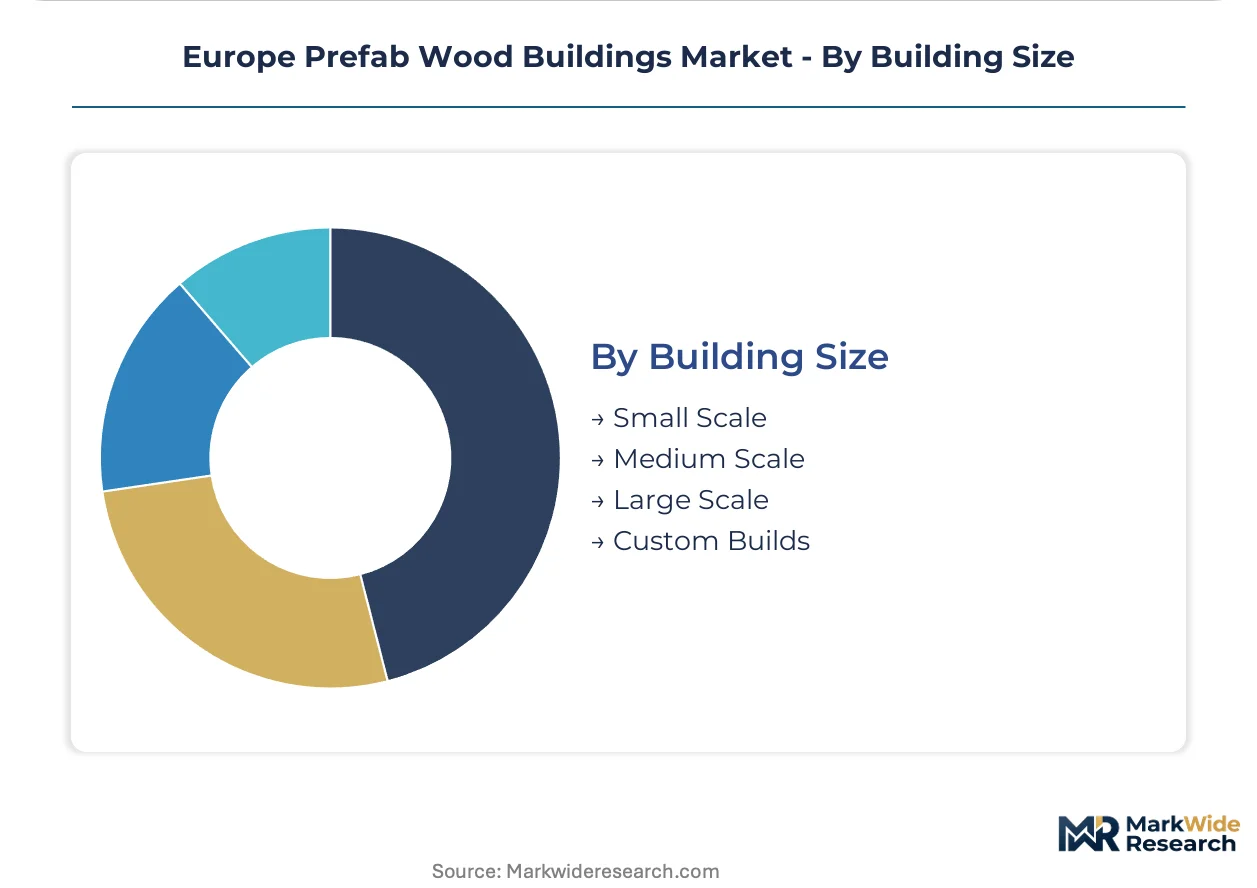
Prefab wood buildings fragment across four distinct category axes, each carrying different capital requirements and margin profiles. Product type and construction method segments diverge most sharply on factory automation intensity, while end-user and building size categories shape project financing structures and delivery timelines.
Product Type:
Capital intensity peaks with multi-family units requiring automated panel pressing lines and climate-controlled curing chambers, while tiny houses demand minimal fixed asset deployment.
- Modular Homes:Fully volumetric units factory-finished with MEP systems pre-installed, commanding the deepest contractor relationships through repeatable floor plans and standardized foundation interfaces. Demand concentrates in Germany's Rhine-Ruhr corridor where labor cost arbitrage favors integrated delivery over fragmented procurement.
- Multi-Family Units:Mid-rise volumetric assemblies engineered for five-to-twelve-story residential towers, leveraging cross-laminated timber cores for elevator shafts and stairwells. Swedish and Norwegian state housing agencies are mandating timber content thresholds in social housing tenders, compressing structural engineering review cycles.
- Tiny Houses:Compact sub-400-square-foot units serving rural hospitality operators and accessory dwelling unit ordinances in Lisbon and Porto.
- Prefab Cottages:Single-family vacation structures with seasonal occupancy profiles, concentrated in France's Alpine and coastal zones.
Modular homes absorb the bulk of installed capacity; multi-family units are expanding most quickly.
End User:
Customer type determines contract structure, with government procurement mandating CE-marked structural timber and REACH-compliant treatments while residential buyers prioritize speed-to-occupancy.
- Residential Customers:Individual homeowners purchasing single-unit dwellings through developer showrooms or direct factory contracts, concentrated in Scandinavia's industrialized forest belt where captive softwood supply chains integrate drying, treating, and finishing capabilities.
- Government Projects:Nordic public-sector procurement through Swedish and Norwegian state housing agencies, binding limits on embodied carbon in building materials disqualifying traditional concrete and steel from tender eligibility.
- Developers:Multi-unit residential project sponsors bundling design, fabrication, and assembly into single-source agreements that displace traditional subcontractor tiers.
- Contractors:General construction firms awarding turnkey timber frame contracts to factory operators with captive erection crews, most visible in Belgium and the Netherlands.
Government projects lock in the longest contract horizons; developers are gaining share fastest as channel consolidation accelerates.
Construction Method:
Method selection drives adhesive exposure and factory certification cycles, with sustainable building approaches requiring ECHA-compliant bio-based preservatives extending qualification timelines.
- Panelized Systems:Flat-packed wall, floor, and roof assemblies shipped for field erection, capturing margin pools from custom architectural specifications requiring site flexibility. German and Austrian developers specify these for Central European climate zones with demanding thermal performance requirements.
- Sustainable Building:Mass timber engineering with factory-controlled moisture specifications below 20 percent, cross-laminated timber lamination advances collapsing factory-to-occupancy timelines while REACH chemical scrutiny forces reformulation of factory-applied treatments.
- Energy-Efficient Solutions:High-performance envelope assemblies targeting near-zero operational carbon, concentrated in Passive House-certified developments across Germany and Austria.
- Traditional Framing:Platform frame construction with dimensional lumber, persisting in Southern Europe where existing contractor networks and building codes perpetuate slab-on-grade foundations despite timber superstructure compatibility.
Panelized systems dominate current factory throughput; sustainable building approaches are climbing the fastest as EU Green Deal mandates tighten.
Building Size:
Scale determines transportation economics and crane-time requirements, with large-scale projects demanding just-in-time delivery coordination that favors factories with captive logistics fleets.
- Large Scale:Multi-story commercial and residential complexes requiring BIM-to-CNC workflow integration for real-time production adjustments matching panel outputs to site-specific foundation tolerances. Demand concentrates in urban infill sites across Stockholm, Berlin, and Vienna where crane-time minimization commands premium pricing.
- Custom Builds:Architect-specified one-off structures with non-standard dimensions and material finishes, digital fabrication convergence enabling mass customization at batch production economics.
- Medium Scale:Small commercial and multi-unit residential projects, standard module widths optimizing highway transport clearances across EU member states.
- Small Scale:Single-family and accessory dwelling units, municipal zoning reforms in Portugal and France legalizing compact prefab wood systems for backyard installation.
Large-scale projects command the highest unit margins; custom builds are gaining share fastest as digital thread technologies dissolve design-to-factory boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for prefab wood buildings clusters along three distinct corridors: Scandinavia's industrialized forest belt, Germany's Rhine-Ruhr corridor, and Portugal's emerging ADU markets. Each geography exhibits unique regulatory drivers and supply chain configurations.
Germany
Residential developers in the Rhine-Ruhr corridor are requalifying supply chains around mass timber engineering as EU Green Deal embodied carbon limits tighten. The national implementation of revised Eurocode 5 standards through the German Institute for Standardization (DIN) is accelerating tall wood structure approvals. ELK Fertighaus GmbH anchors precision-engineered wall system production in Central European climate zones.
Sweden
State housing agencies are mandating timber content thresholds in social housing tenders, disqualifying traditional concrete and steel from public procurement. The Swedish National Board of Housing, Building and Planning (Boverket) is transposing Eurocode 5 standards ahead of neighboring member states. Lindbäcks Bygg AB operates fully automated factory lines in the Norrland timber corridor, compressing delivery cycles through captive softwood supply chains.
Norway
Public-sector procurement through the Norwegian State Housing Bank is binding timber content requirements into social housing tenders. The Norwegian Building Authority (DiBK) is enforcing CE marking compliance for structural timber products under the EU Construction Products Regulation. Moelven Byggmodul AB dominates Nordic public-sector contracts through integrated sawmill capacity.
Portugal
Municipal zoning reforms in Lisbon and Porto are legalizing accessory dwelling units, opening channels for compact prefab wood systems. The Portuguese Environment Agency (APA) is aligning national building codes with EU Green Deal benchmarks on embodied carbon. Tiny house demand concentrates among rural hospitality operators in the Algarve and Alentejo regions.
France
General contractors are bundling design, fabrication, and assembly into single-source timber frame agreements. The French Agency for Food, Environmental and Occupational Health & Safety (ANSES) is scrutinizing wood preservatives under REACH compliance frameworks. Prefab cottage production clusters in Alpine and coastal zones serving seasonal occupancy profiles.
Europe Prefab Wood Buildings Market Competitive Landscape
Scandinavian producers anchor one tier; German-Austrian specialists hold precision-engineering positions. The vendor base splits between integrated factory operators with captive erection crews and component suppliers serving fragmented general contractor networks. Three archetypes dominate: automated volume producers, public-sector procurement specialists, and climate-zone engineering boutiques. Competitive intensity is manifesting through turnkey contract bundling and BIM-to-CNC workflow integration.
Among Nordic fabricators, Lindbäcks Bygg AB and Moelven Byggmodul AB exemplify the integrated production model, while ELK Fertighaus GmbH occupies a position within the Central European precision-engineering tier. These entities represent contrasting strategic postures: captive vertical control versus specialized component supply. The competitive terrain is reshaping around digital fabrication convergence and single-source delivery commitments.
| Leading Market Players |
|---|
| OBOS Bostadsutveckling AB |
| Alvsbyhus AB |
| Lindbäcks Bygg AB |
| Huscompagniet A/S |
| DFH Group |
| Moelven Byggmodul AB |
| ELK Fertighaus GmbH Zweigniederlassung Dtl |
| Peab AB |
| Derome Husproduktion AB |
| Others |
Pricing and Supply Chain Analysis
Captive sawmill integration across Sweden's Norrland timber corridor anchors both supply security and pricing power for engineered wood producers, compressing margin leakage from third-party softwood procurement while insulating against petrochemical resin volatility.
Pricing Analysis
Volume producers compete on throughput economics while precision-engineering boutiques command project-based premiums. Pricing stratifies across CE-marked structural tiers, Passive House-certified envelopes, and standard platform-frame offerings. Cost compression in multi-family CLT segments is intensifying because polyurethane adhesive prices fluctuate with petrochemical feedstocks. Government procurement agencies exhibit lowest price sensitivity due to mandated timber content thresholds; rural hospitality operators in Portugal's Algarve region show highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Nordic softwood suppliers controlling 70 percent of European glulam feedstock. Manufacturing concentrates in Sweden, Germany, and Austria, drawing from spruce and pine stands in the Baltic Sea basin. The chain rests on polyurethane resins, CNC machining capacity, and climate-controlled curing infrastructure. Tariff exposure looms for treated timber imports from outside the European Economic Area. Distribution runs through factory-direct turnkey contracts with captive erection crews, displacing traditional builder-merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal embodied carbon mandates have erected a compliance moat around CE-marked structural timber producers, disqualifying non-compliant imports from public procurement channels and compressing the competitive set to qualified incumbents.
For Market Incumbents: Cement market position through backward integration into captive sawmill capacity in Sweden's industrialized forest belt and accelerated BIM-to-CNC workflow deployment. The threat of adhesive cost volatility from petrochemical markets demands resin hedging strategies. Certification investment in revised Eurocode 5 standards offers channel control leverage as national transposition timelines diverge. For New Entrants and Emerging Players: Portuguese accessory dwelling unit developers represent the most penetrable buyer archetype, with Lisbon and Porto municipal reforms legalizing compact prefab systems for backyard installation. White-space targets include rural hospitality operators in the Algarve and custom architectural specifications requiring panelized system flexibility. A go-to-market angle through digital fabrication convergence enables mass customization without automated pressing line capex. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated factory operators with captive erection crews and public-sector procurement credentials. Long-term viability favors entities with demonstrated REACH compliance and Eurocode 5 certification timelines already completed. The signal to watch is ECHA reformulation rulings on bio-based wood preservatives, which will extend factory qualification cycles and compress the acquirable target pool.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Sawmills | Secures softwood supply chains in Sweden's Norrland corridor against third-party price volatility. |
| BIM-to-CNC Workflow Deployment | Enables real-time production adjustments matching panel outputs to site-specific foundation tolerances. |
| REACH-Compliant Preservative Reformulation | Maintains CE marking validity as ECHA scrutiny disqualifies legacy boron-based treatments. |
| Turnkey Contract Bundling | Displaces fragmented subcontractor tiers in Germany's Rhine-Ruhr corridor through single-source delivery. |
| Portuguese ADU Market Entry | Captures municipal zoning reforms in Lisbon and Porto legalizing compact prefab wood systems. |
Research Methodology
Trade association filings, Eurostat construction statistics, and ECHA regulatory databases formed the secondary backbone, cross-referenced against primary interviews with factory operations directors, public-sector procurement officers at Swedish and Norwegian state housing agencies, CLT engineering specialists, and REACH compliance consultants. Bottom-up and top-down triangulation validated volume estimates across product type and construction method segments.
Bottom-up modeling aggregated unit economics across modular homes, multi-family CLT assemblies, and panelized systems, while top-down analysis calibrated against national building permit data and timber consumption reports. Segmentation dimensions included building size tiers, end-user categories, and climate-zone engineering requirements. CAGRs were derived from regression analysis of historical adoption curves against EU Green Deal implementation timelines and Eurocode 5 transposition schedules.
Revisions become necessary when ECHA reformulation rulings accelerate, Eurocode 5 national transposition timelines diverge sharply, or petrochemical feedstock markets destabilize adhesive cost structures. Forecasts reflect documented assumptions about regulatory enforcement intensity and contractor training availability for moisture management protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Middle East Data Center Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Mezzanine Floor Market
Building Construction
Dominican Republic Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Cold Storage Construction Market
Building Construction
Thailand Construction Market
Building Construction
Oman Construction Market
Building Construction
India Commercial Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Tanzania Construction Market
Building Construction
Modular and Prefabricated Construction Market