
 Guatemala Construction Market | 2026-2036
Guatemala Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Guatemala Construction Market Insights
The Guatemala construction sector is recalibrating around a widening split between premium developments with full engineering services and commodity contracting focused on basic residential shells. Grupo Cementos Progreso anchors domestic cement supply through integrated quarry-to-distribution operations. Constructora Meco differentiates via specialized infrastructure delivery for transport and energy clients. Holcim Guatemala leverages multinational technical standards in ready-mix and sustainable concrete formulations.
Construction in Guatemala encompasses the assembly of built structures using concrete, steel, wood, and glass materials, with concrete dominating structural frames due to local seismic performance requirements and volcanic aggregate availability. The primary purpose spans residential shelter, commercial facilities, industrial plants, and public infrastructure across private and government end users. Residential construction leads volume but infrastructure commands longer contract durations and more complex engineering service involvement. Commercial building attracts higher material specification intensity, particularly glass and structural steel imports. Contracting services capture the largest revenue pool while construction management remains underdeveloped outside Guatemala City metropolitan projects.
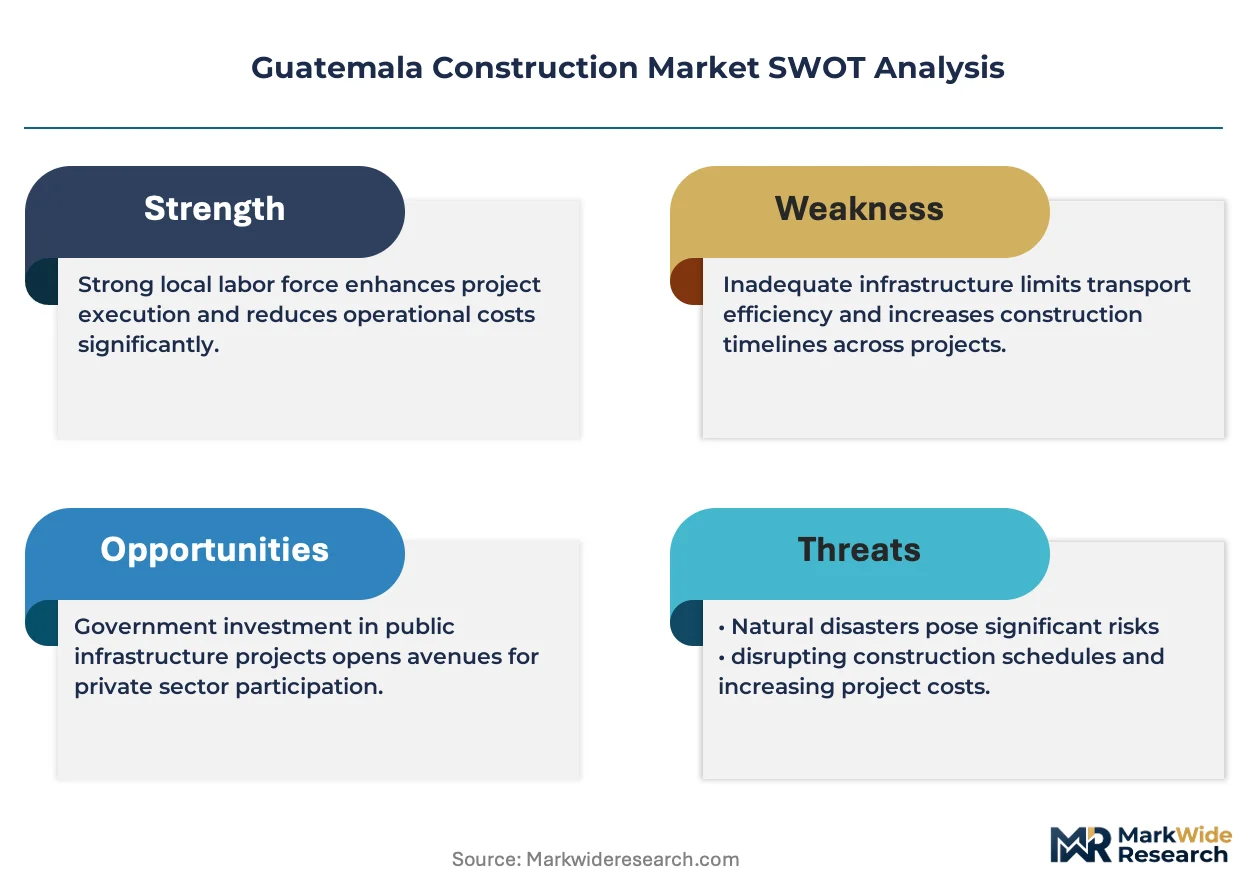
Guatemala's national seismic construction code and municipal building permits administered by local planning departments shape structural design requirements and project approval timelines. The Superintendencia de Administracion Tributaria influences sector liquidity through tax treatment of construction inputs and developer withholding obligations. Stakeholders must monitor whether updated seismic standards trigger retrofit demand in existing commercial stock or redirect new investment toward peripheral municipalities with faster permitting regimes.
Market Dynamics
Guatemala's construction sector pivots around seismic code enforcement tightening in Guatemala City, which is compressing project timelines and forcing developers toward pre-engineered structural systems that bypass traditional masonry-intensive methods.
Growth Catalysts
- Residential density mandates:Municipal zoning reforms in Guatemala City and Quetzaltenango are accelerating vertical housing permits, pulling mid-rise concrete frame demand from low-rise masonry alternatives.
- CA-1 highway corridor investment:Transport infrastructure spending between the capital and Pacific port terminals is extending contractor order books for bridge and pavement segments.
- Geopolymer concrete adoption:Volcanic pozzolan availability in the Guatemala highlands is enabling binder formulations that reduce Portland cement intensity while meeting seismic performance thresholds.
Market Restraints
- Rebar import dependency:Structural steel reinforcement arrives primarily through Puerto Quetzal and Santo Tomás de Castilla, exposing project schedules to maritime logistics volatility and customs clearance friction.
- Permit timeline variability:Municipal planning departments outside the capital operate with inconsistent technical review capacity, stretching pre-construction phases unpredictably.
- Skilled welder scarcity:Certified steel connection specialists concentrate in Guatemala City, limiting structural steel frame adoption in secondary municipalities.
Strategic Opportunities
- Petén infrastructure gap:Northern Guatemala's road and utility deficit presents first-mover positioning for contractors capable of mobilizing equipment across limited access corridors.
- Green building certification adoption:EDGE and LEED recognition is emerging as a differentiator in Guatemala City commercial leasing, creating premium positioning for certified project delivery.
- Modular housing fabrication:Factory-built panel systems are penetrating social housing programs, compressing on-site labor requirements and quality variance.
Industry Challenges
- Seismic engineer certification bottlenecks:The Colegio de Ingenieros de Guatemala maintains limited specialist accreditation capacity, constraining project sign-off velocity for complex structures.
- Equipment financing access:Heavy machinery acquisition depends on dollar-denominated lending, exposing contractors to exchange rate risk and collateral requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guatemala Construction Market |
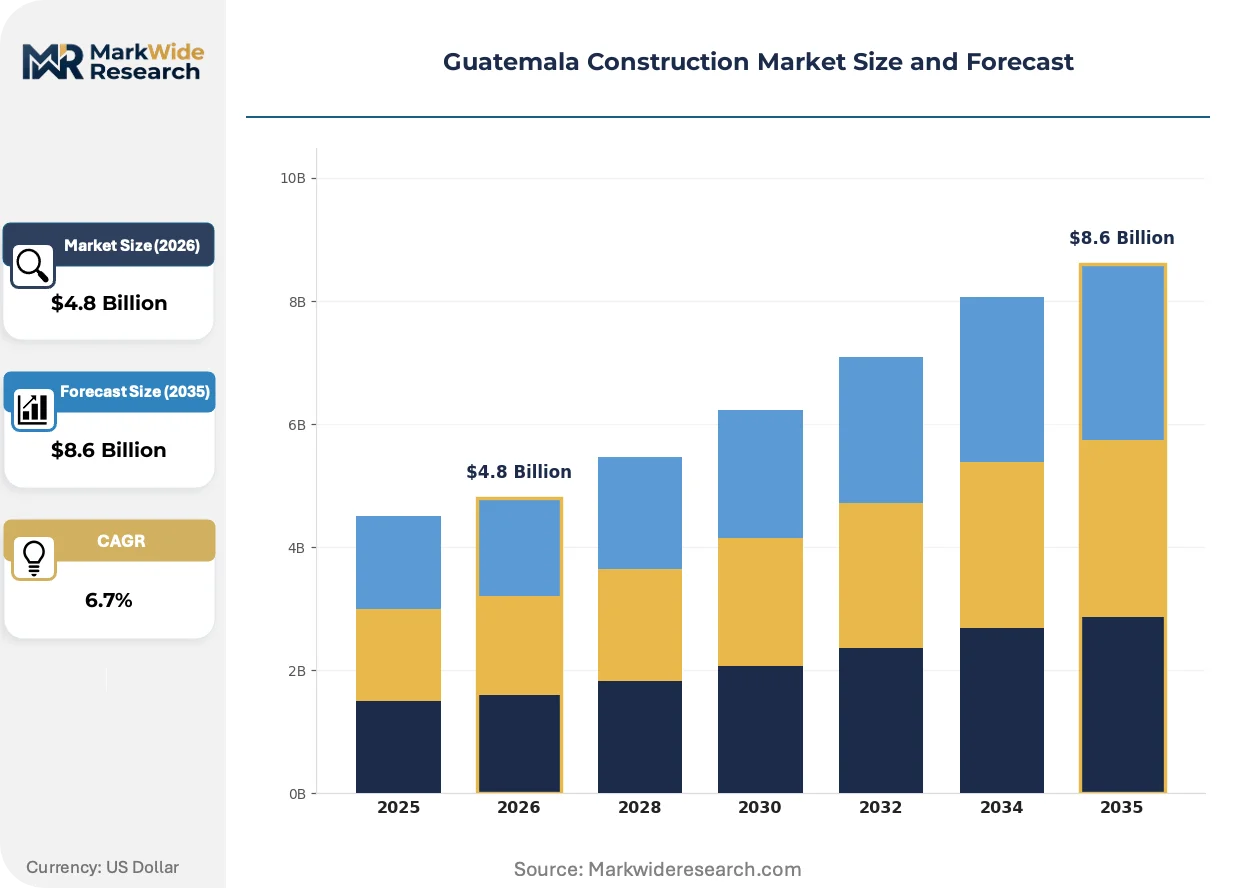
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Residential, Commercial, Infrastructure, Industrial Material: Concrete, Steel, Wood, Glass Service Type: Design, Engineering, Construction Management, Contracting End User: Private Sector, Government, Non-Profit, Developers |
| Companies Covered | Corporacion San Francisco S.A., Constructora AICSA S.A., Metro Proyectos S.A., CVG ITSA S.A., Futuros Constructivos Sobre la Roca S.A., Grupo Cementos Progreso, Constructora Meco, Holcim Guatemala, Fucorsa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guatemala Construction Market Trends and Innovations
Prefabrication and digital coordination tools are compressing traditional construction timelines in Guatemala's urban corridor, while regulatory pressure on structural performance is filtering material specifications and procurement patterns.
BIM coordination software is penetrating Guatemala City commercial projects above ten stories, enabling clash detection before steel and MEP installation. Large developers and engineering consultancies are mandating model-based handoffs from specialty contractors. This digital layer is modularizing subcontractor scopes, allowing parallel fabrication and reducing on-site trade stacking.
Guatemala's updated national seismic construction code is mandating enhanced ductility detailing for concrete moment frames and restricting masonry bearing walls in high seismic zones. The Superintendencia de Administracion Tributaria has aligned depreciation schedules for seismic retrofit investments, indirectly steering commercial owner decisions. Mixed-use developments in Zones 10 and 14 of Guatemala City are absorbing the compliance cost premium fastest.
Developer procurement is consolidating around design-build delivery for mid-rise residential, compressing the traditional architect-bid-build sequence. Integrated contracts are displacing fragmented tendering in projects above five hundred units. This shift is most pronounced in the Guatemala City–Antigua corridor, where foreign capital participation favors single-point accountability and fixed-price certainty.
Guatemala Construction Market Segmentation
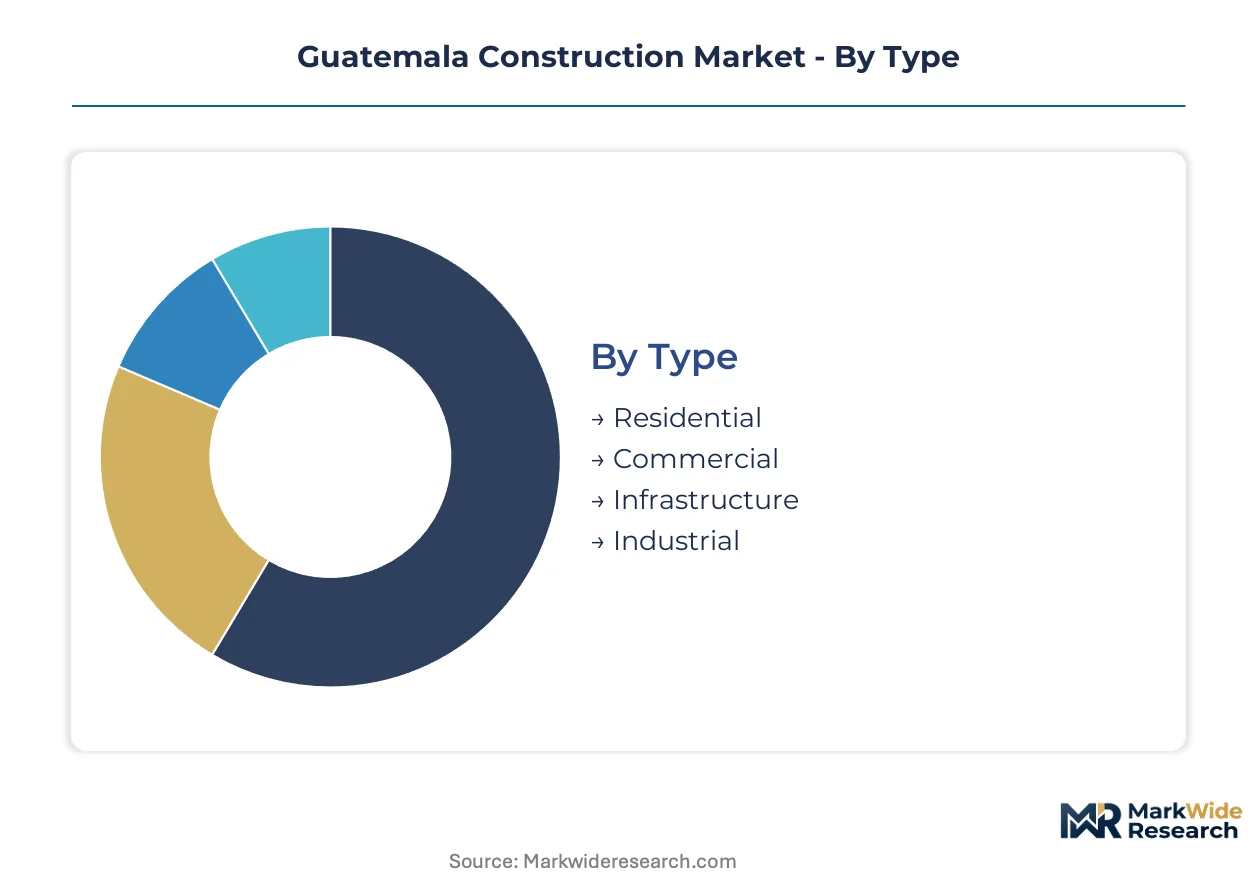
Guatemala's construction market fragments across project typology, material specification, service delivery model, and capital source. Each axis shapes procurement patterns, margin profiles, and regulatory exposure differently across the Guatemala City–Quetzaltenango corridor and secondary municipalities.
Type:
Technical complexity and contract duration diverge sharply across project categories, with seismic code compliance costs varying by structural system and occupancy risk.
- Residential:Mid-rise concrete frame construction dominates Guatemala City and Quetzaltenango as municipal density mandates displace low-rise masonry. Vertical housing permits are accelerating, pulling demand toward pre-engineered structural systems that compress traditional build timelines.
- Infrastructure:CA-1 highway corridor investment between the capital and Pacific port terminals is extending contractor order books for bridge and pavement segments. Transport and energy clients favor specialized infrastructure delivery with longer contract durations and complex engineering service involvement.
- Commercial:Mixed-use developments in Zones 10 and 14 of Guatemala City absorb seismic compliance cost premiums fastest, with higher material specification intensity for glass and structural steel imports.
- Industrial:Manufacturing facility construction concentrates near Puerto Quetzal and Santo Tomás de Castilla, leveraging maritime logistics access for imported equipment and rebar.
Residential leads on scale; infrastructure leads on momentum.
Material:
Local geology and import dependency create divergent supply economics across structural and finish materials.
- Concrete:Volcanic pozzolan availability in the Guatemala highlands enables geopolymer binder formulations that reduce Portland cement intensity while meeting seismic performance thresholds. Grupo Cementos Progreso anchors domestic supply through integrated quarry-to-distribution operations.
- Steel:Structural reinforcement arrives primarily through Pacific and Caribbean ports, exposing project schedules to maritime logistics volatility and customs clearance friction. Certified welder scarcity in secondary municipalities limits structural steel frame adoption outside Guatemala City.
- Wood:Timber construction concentrates in low-rise residential and hospitality applications in Antigua and peripheral municipalities with traditional building cultures.
- Glass:Curtain wall and glazing specifications are climbing in Guatemala City commercial leasing as EDGE and LEED recognition emerges as a differentiator.
Concrete commands volume; steel faces supply friction.
Service Type:
Procurement consolidation is reshaping how owners access technical expertise and construction execution.
- Contracting:Captures the largest revenue pool through traditional build-only delivery, though margins compress in commodity residential shells.
- Design:Architectural services face pressure as design-build delivery consolidates architect-bid-build sequences in mid-rise residential above five hundred units.
- Construction Management:Remains underdeveloped outside Guatemala City metropolitan projects, with limited penetration in secondary municipalities.
- Engineering:Seismic engineer certification bottlenecks at the Colegio de Ingenieros de Guatemala constrain project sign-off velocity for complex structures.
Contracting dominates revenue; engineering faces accreditation constraints.
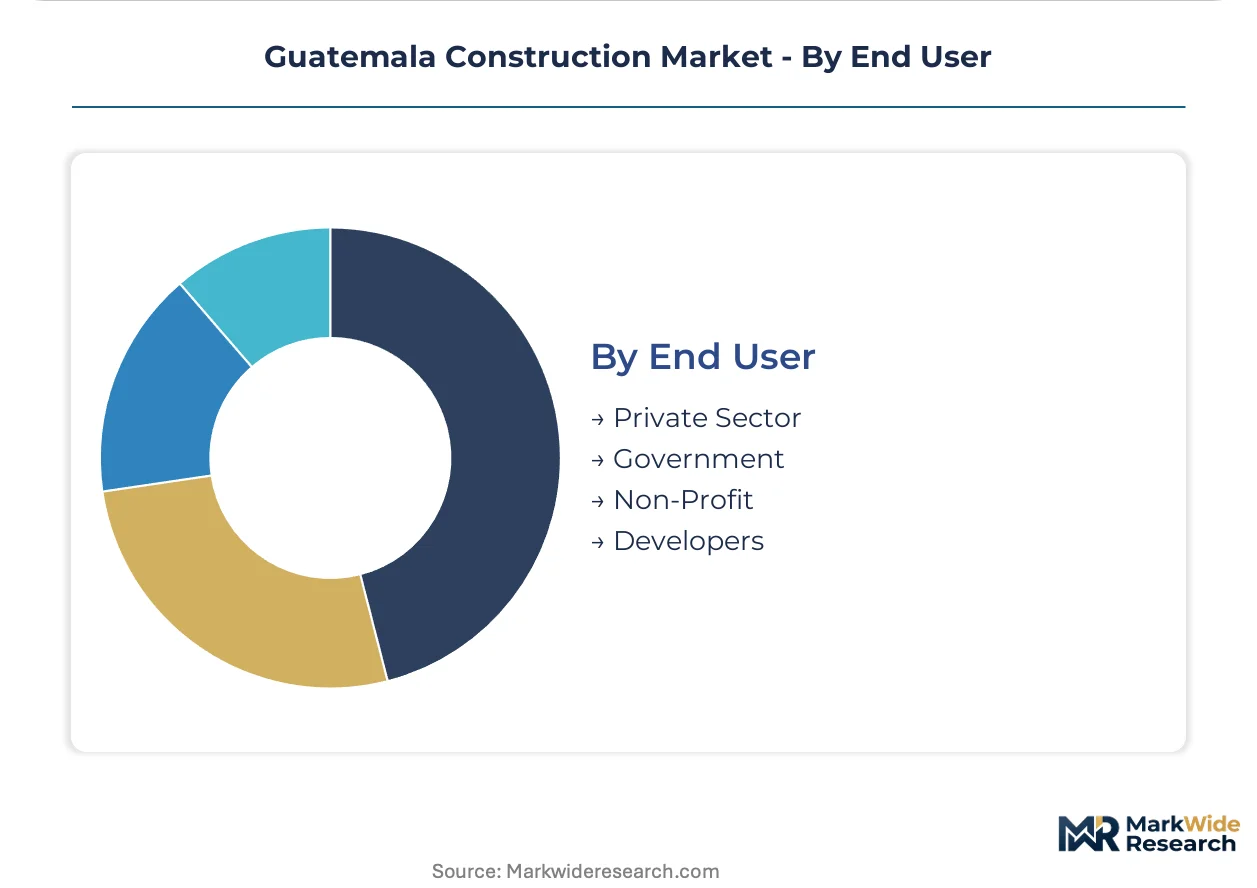
End User:
Capital source determines risk tolerance, procurement sophistication, and regulatory navigation capacity.
- Developers:Drive adoption of vertical housing and mixed-use formats in Guatemala City, consolidating procurement around design-build delivery for mid-rise residential.
- Private Sector:Commercial owners in Zones 10 and 14 are absorbing seismic retrofit investment incentives aligned by the Superintendencia de Administracion Tributaria depreciation schedules.
- Government:Transport infrastructure spending extends contractor order books, though payment timelines and tender transparency vary by agency.
- Non-Profit:Social housing programs are penetrating modular panel systems that compress on-site labor requirements and quality variance.
Developers lead on project velocity; government anchors infrastructure volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welders and seismic engineers concentrate in Guatemala City, anchoring technical capacity for complex structural projects while secondary municipalities face persistent skill scarcity.
Guatemala City Metropolitan Area
Mixed-use developments in Zones 10 and 14 absorb seismic compliance premiums fastest. The Superintendencia de Administracion Tributaria aligns depreciation schedules for retrofit investments. BIM coordination penetrates commercial projects above ten stories, compressing traditional build timelines through model-based handoffs.
Quetzaltenango Corridor
Municipal density mandates accelerate vertical housing permits, pulling mid-rise concrete frame demand from low-rise masonry. The national seismic construction code restricts masonry bearing walls in high seismic zones. Pre-engineered structural systems penetrate social housing programs, reducing on-site labor variance.
CA-1 Highway Pacific Axis
Transport infrastructure spending between the capital and Puerto Quetzal extends contractor order books for bridge segments. Government tender transparency varies by agency, affecting payment timeline predictability. Manufacturing facility construction concentrates near Santo Tomás de Castilla, leveraging maritime logistics for imported rebar.
Petén Northern Region
Road and utility deficits present first-mover positioning for contractors mobilizing across limited access corridors. Municipal planning departments operate with inconsistent technical review capacity. Modular panel fabrication remains underdeveloped, constraining rapid deployment options.
Antigua Peripheral Ring
Timber construction concentrates in low-rise hospitality applications amid traditional building cultures. Volcanic pozzolan availability enables geopolymer binder formulations reducing Portland cement intensity. EDGE and LEED recognition emerges as a leasing differentiator in premium commercial stock.
Guatemala Construction Market Competitive Landscape
Top-tier vendors anchor integrated cement-to-concrete operations, while mid-tier contractors compete on specialized infrastructure delivery and regional project mobilization. The vendor base stratifies across multinational technical standards adopters, domestic quarry-integrated producers, and corridor-focused transport specialists. Three archetypes dominate: volcanic aggregate-integrated cement producers, seismic-code-specialized engineering contractors, and Pacific port-proximate industrial builders. Capacity consolidation and design-build procurement consolidation represent the dominant competitive vectors reshaping contract award patterns.
Within the integrated materials tier, Grupo Cementos Progreso and Holcim Guatemala occupy positions exemplifying quarry-to-distribution control and multinational technical standard deployment respectively. Constructora Meco represents the specialized infrastructure archetype, anchoring transport and energy client relationships. These three entities collectively illustrate how domestic volcanic pozzolan access, Pacific maritime logistics positioning, and seismic engineering accreditation concentration determine competitive positioning across the Guatemala City–Quetzaltenango corridor.
| Leading Market Players |
|---|
| Corporacion San Francisco S.A. |
| Constructora AICSA S.A. |
| Metro Proyectos S.A. |
| CVG ITSA S.A. |
| Futuros Constructivos Sobre la Roca S.A. |
| Grupo Cementos Progreso |
| Constructora Meco |
| Holcim Guatemala |
| Fucorsa |
| Others |
Pricing and Supply Chain Analysis
Seismic code compliance mandates in Guatemala City are compressing project timelines and forcing developers toward pre-engineered structural systems, which concentrates procurement power among contractors capable of delivering integrated design-build packages and compresses margins for commodity shell builders.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the Guatemala construction sector. Design-build delivery commands premium positioning through single-point accountability, while traditional architect-bid-build sequences face margin erosion in commodity residential segments. Price differentiation hinges on seismic engineering certification tier and volcanic pozzolan integration in concrete formulations. Pricing pressure stems from rebar import dependency through Puerto Quetzal, which exposes project budgets to maritime logistics volatility. Government infrastructure clients exhibit highest price sensitivity due to tender transparency variability, while foreign capital-backed mixed-use developers in Zones 10 and 14 absorb compliance premiums with least negotiation leverage.
Supply Chain Analysis
Structural steel reinforcement supply rests on maritime arrivals through Guatemala's Pacific and Caribbean ports, with rebar sourcing concentrated in Mexico, China, and regional Central American mills. Volcanic pozzolan draws from highland quarry operations anchored by Grupo Cementos Progreso, while Portland cement imports supplement domestic clinker capacity during peak construction windows. Supply chain risk centers on customs clearance friction at Santo Tomás de Castilla, where equipment financing dollar-denomination creates exchange rate exposure for contractors. Distribution runs through vertically integrated quarry-to-distribution networks for cement, and project-direct maritime delivery for steel-intensive commercial frames.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Guatemala construction market functions as a stable compounder anchored by municipal density mandates that accelerate vertical housing permits across the Guatemala City–Quetzaltenango corridor.
For Market Incumbents: Anticipate procurement consolidation toward design-build delivery by deepening captive supply of geopolymer concrete through backward integration into volcanic pozzolan quarries. Certify seismic engineering capacity at the Colegio de Ingenieros de Guatemala ahead of accreditation bottlenecks that constrain competitor project sign-off velocity. Defend against modular housing fabricators penetrating social housing programs by compressing traditional concrete frame timelines through BIM coordination adoption. For New Entrants and Emerging Players: The premium-to-economy tier gap in commercial mixed-use development creates positioning room for mid-market contractors delivering seismic-compliant structures without multinational overhead. Target the Petén Northern Region's road and utility deficit as the most penetrable geography, where municipal planning departments lack technical review capacity and first-mover equipment mobilization secures multi-year order books. Penetrate through equipment financing partnerships that absorb dollar-denominated collateral requirements for local contractors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized infrastructure contractors holding CA-1 highway corridor relationships and transport agency accreditation. Long-term viability frames around seismic code enforcement tightening that structurally advantages engineering-capable vendors over commodity shell builders. Monitor green building certification adoption velocity in Guatemala City commercial leasing as the inflection signal for premium positioning capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pozzolan Quarries | Grupo Cementos Progreso's quarry-to-distribution model demonstrates captive supply advantages during peak demand windows. |
| Seismic Engineering Certification Investment | Colegio de Ingenieros de Guatemala accreditation bottlenecks create scarcity value for pre-certified project sign-off capacity. |
| Design-Build Delivery Capability | Foreign capital participation in the Guatemala City–Antigua corridor favors single-point accountability and fixed-price certainty. |
| Modular Panel Fabrication Scale-Up | Social housing programs in Quetzaltenango absorb factory-built systems that compress on-site labor requirements. |
| Pacific Port Logistics Positioning | Santo Tomás de Castilla proximity reduces rebar import lead times for industrial construction near manufacturing zones. |
Research Methodology
Bottom-up residential and infrastructure demand modeling reconciled against top-down cement and steel supply tracking forms the analytical core of this study. Primary interviews with project developers, municipal planning officials, seismic engineering consultants, and equipment financing officers combined with secondary validation from Superintendencia de Administracion Tributaria depreciation schedules, Colegio de Ingenieros de Guatemala accreditation records, and port authority import manifests. Trade data from Guatemala's customs administration and construction permit databases from Guatemala City and Quetzaltenango municipalities anchored supply-side calibration.
Input-output matrix framing connects structural material flows to end-use project typologies across the analysis window. Segmentation dimensions span residential verticality tiers, infrastructure contract duration brackets, commercial seismic performance grades, and service delivery model integration levels. CAGRs derive from project pipeline visibility weighted by permit approval velocity and equipment mobilization constraints. Forecast inputs incorporate volcanic pozzolan availability cycles and maritime logistics clearance patterns at Pacific port terminals.
Caveats apply where municipal planning department capacity expansion or seismic code enforcement variability could materially shift the outlook. Forecasts reflect assumptions around rebar import continuity and equipment financing access that may revise with exchange rate movements or collateral requirement changes. A small set of named triggers—green building certification adoption velocity, modular housing program scale-up, and Petén infrastructure tender transparency—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Bangladesh Construction Market
Building Construction
Early Production Facility Market
Building Construction
US Modular Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
Sweden New Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Pre-Engineered Building Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
El Salvador Construction Market
Building Construction
Turkey Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
United States Commercial Construction Market