
 North America Prefabricated Buildings Market | 2026-2036
North America Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Prefabricated Buildings Market Analytics
California's CALGreen building standards is expanding compliance requirements for low-carbon construction methods across commercial and institutional projects. Clayton Homes leverages its manufactured housing scale to dominate cost-sensitive residential segments across the southeastern United States. Nucor Building Systems anchors its position through captive steel supply and engineered metal building systems for industrial clients. ICON Technology differentiates through additive manufacturing capabilities that reduce material waste in wall-panel fabrication.
Prefabricated buildings are structures manufactured in factory-controlled environments using standardized or custom components, then transported and assembled at final sites; wall panels typically achieve R-values between R-21 and R-40 depending on insulation specification and climate zone targeting. These systems reduce on-site labor exposure, compress construction schedules, and enable quality control protocols impossible under traditional stick-built conditions. Panelized construction leads volume in single-family residential applications due to familiar framing methods and flexible finish options, while modular units capture margin pools in multi-story commercial and institutional projects where factory completion of MEP rough-ins generates the greatest schedule savings. Steel framing dominates industrial and warehouse applications across the Great Plains and Midwest manufacturing belts, though mass timber and cross-laminated timber hybrids are gaining specification share in Pacific Northwest institutional buildings.
OSHA maintains jurisdiction over factory assembly line safety and fall protection during module installation, while the ICC governs structural acceptance through the International Building Code and modular construction appendices adopted variably across U.S. states and Canadian provinces. EPA regulations on formaldehyde emissions from composite wood products directly constrain material selection for interior finishes, particularly affecting low-cost residential production. Buyers and contractors must monitor evolving provincial adoption of the National Building Code of Canada and state-level amendments to the IBC, as divergence in seismic, wind, and energy requirements shapes where factory capacity can serve without costly redesign.
Market Dynamics
Labor scarcity across the Texas urban corridor and Ontario Golden Horseshoe is compressing project timelines and forcing developers toward factory-controlled assembly methods that minimize on-site craft dependency.
Growth Catalysts
- CALGreen building standards:California's expanding low-carbon mandates for commercial and institutional projects are accelerating specification of prefabricated wall assemblies with verified embodied carbon footprints.
- Healthcare rapid-deployment:Hospital systems across the United States are adopting modular clinic units and emergency wings to address surge capacity requirements without traditional construction delays.
- Cross-laminated timber hybrids:Pacific Northwest institutional projects are specifying mass timber-panelized systems that reduce structural weight while meeting seismic performance targets.
Market Restraints
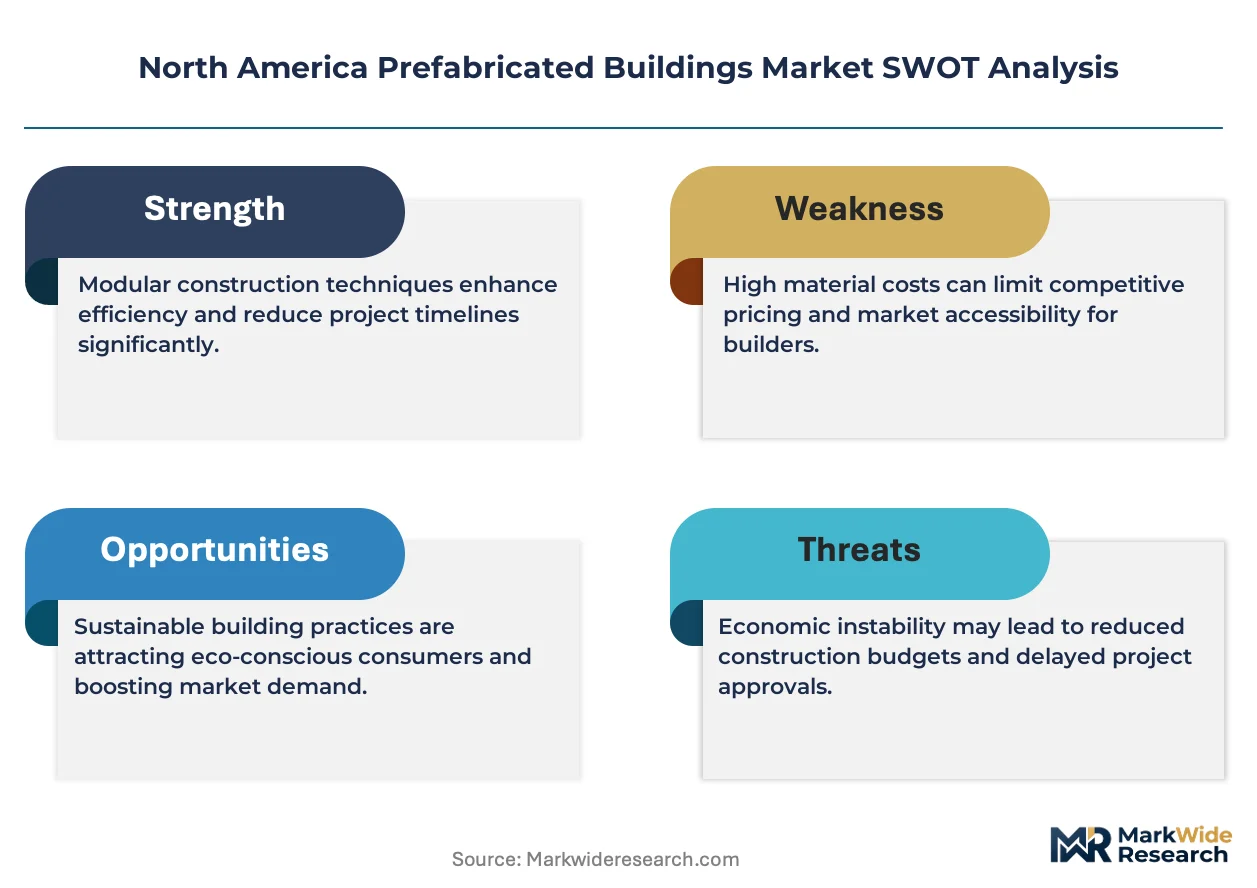
- Steel input volatility:Captive supply advantages at integrated producers like Nucor Building Systems highlight structural cost pressure on non-integrated fabricators exposed to spot steel pricing.
- Transportation radius limits:Module width constraints on interstate highway systems restrict factory-to-site distances, concentrating viable production capacity within 500 miles of major demand clusters.
- IBC adoption variance:State-level amendments to the International Building Code create design recertification costs that fragment addressable markets for standardized product lines.
Strategic Opportunities
- Texas urban corridor density:Compressed timelines in Houston-Dallas-Austin metro expansion create pull for multi-story modular commercial cores with factory-completed MEP rough-ins.
- Digital fabrication convergence:Additive manufacturing for wall-panel production is converging with robotic assembly to enable mass-customization at residential cost points.
- Green construction procurement mandates:New York state-level requirements for public project low-carbon methods are creating specification preference for certified prefabricated envelope systems.
Industry Challenges
- Seismic engineering specialization:California and British Columbia high-seismic zones require module-to-module connection detailing that exceeds standard factory engineering capabilities, creating talent bottlenecks.
- Factory certification timelines:EPA formaldehyde emission testing for composite wood interior finishes adds 8-14 weeks to production startup for residential-focused manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Prefabricated Buildings Market |
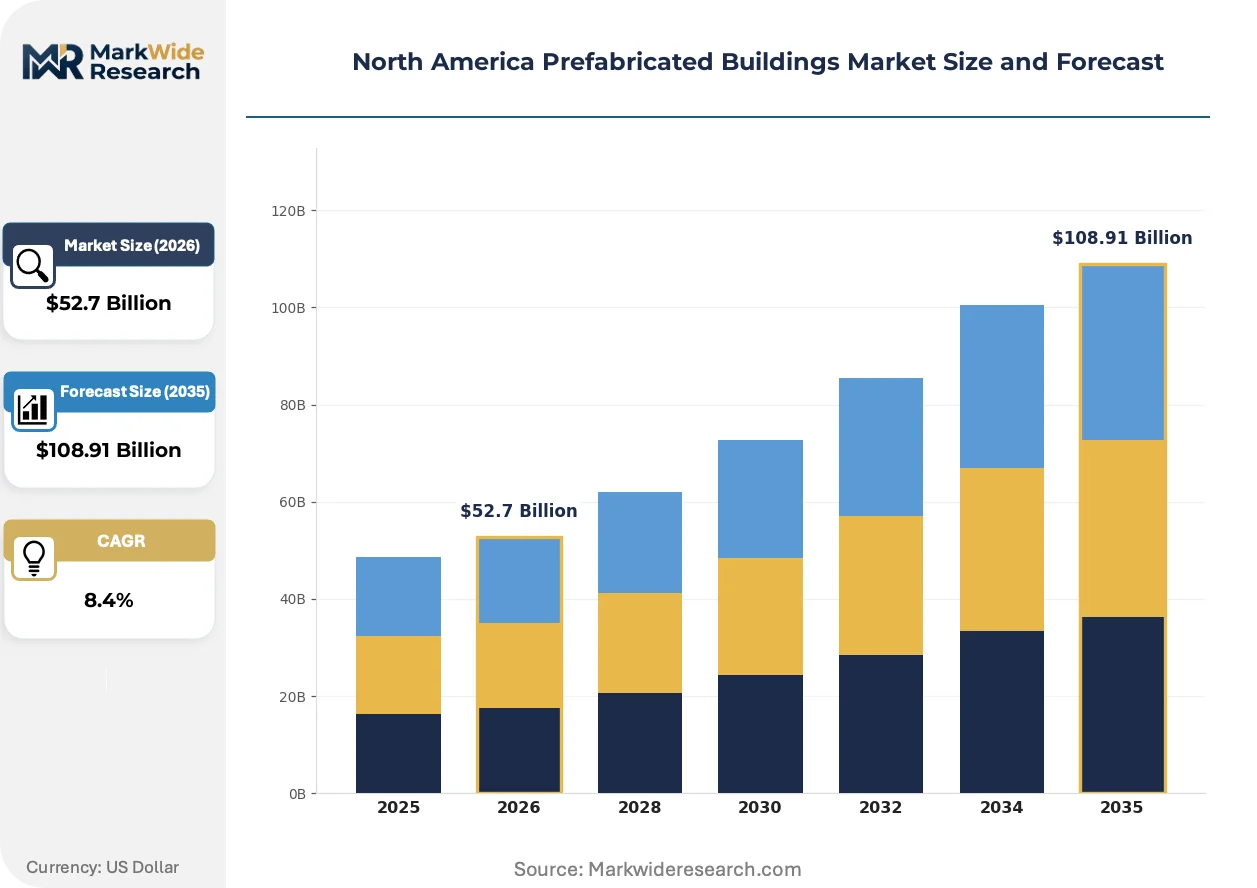
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Panelized, Hybrid, Temporary Application: Residential, Commercial, Industrial, Institutional Material: Wood, Steel, Concrete, Composite Construction Method: Off-site, On-site, Custom-built, Ready-to-use |
| Companies Covered | BluHomes, ICON Technology, Clayton Homes, Nucor Building Systems, Butler Manufacturing, Cavco Industries, Plant Prefab, Varco Pruden Buildings, Skyline Champion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Prefabricated Buildings Market Evolving Landscape
Digital fabrication and regulatory carbon accounting are rewriting competitive advantage in prefabricated construction, compressing the gap between custom architectural intent and factory production economics.
Additive manufacturing for wall-panel fabrication is converging with conventional panelized construction workflows. ICON Technology's deployment of large-scale 3D printing for concrete wall elements enables geometric complexity impossible in traditional formwork. Healthcare developers in Texas are piloting these systems for clinic exteriors, compressing envelope completion schedules by 30-40% while reducing material waste streams.
California's CALGreen Tier 1 and Tier 2 compliance pathways are mandating embodied carbon disclosure for commercial projects over 100,000 square feet. Institutional buyers in Los Angeles and San Francisco metro areas are now requiring Environmental Product Declarations for structural assemblies, filtering specification toward prefabricated suppliers with verified supply chain data. Panelized producers with third-party certified manufacturing are capturing disproportionate share in public-sector RFPs.
Hospital systems are consolidating procurement authority for rapid-deployment facilities into centralized capital planning departments. Traditional general contractor bidding is giving way to design-build-furnish contracts with prefabricated envelope and MEP modules. This consolidation is most visible in Ontario, where provincial health infrastructure planning has pre-qualified three modular suppliers for 10-year master agreements, compressing vendor pools and raising barriers for new entrants.
North America Prefabricated Buildings Market Segmentation
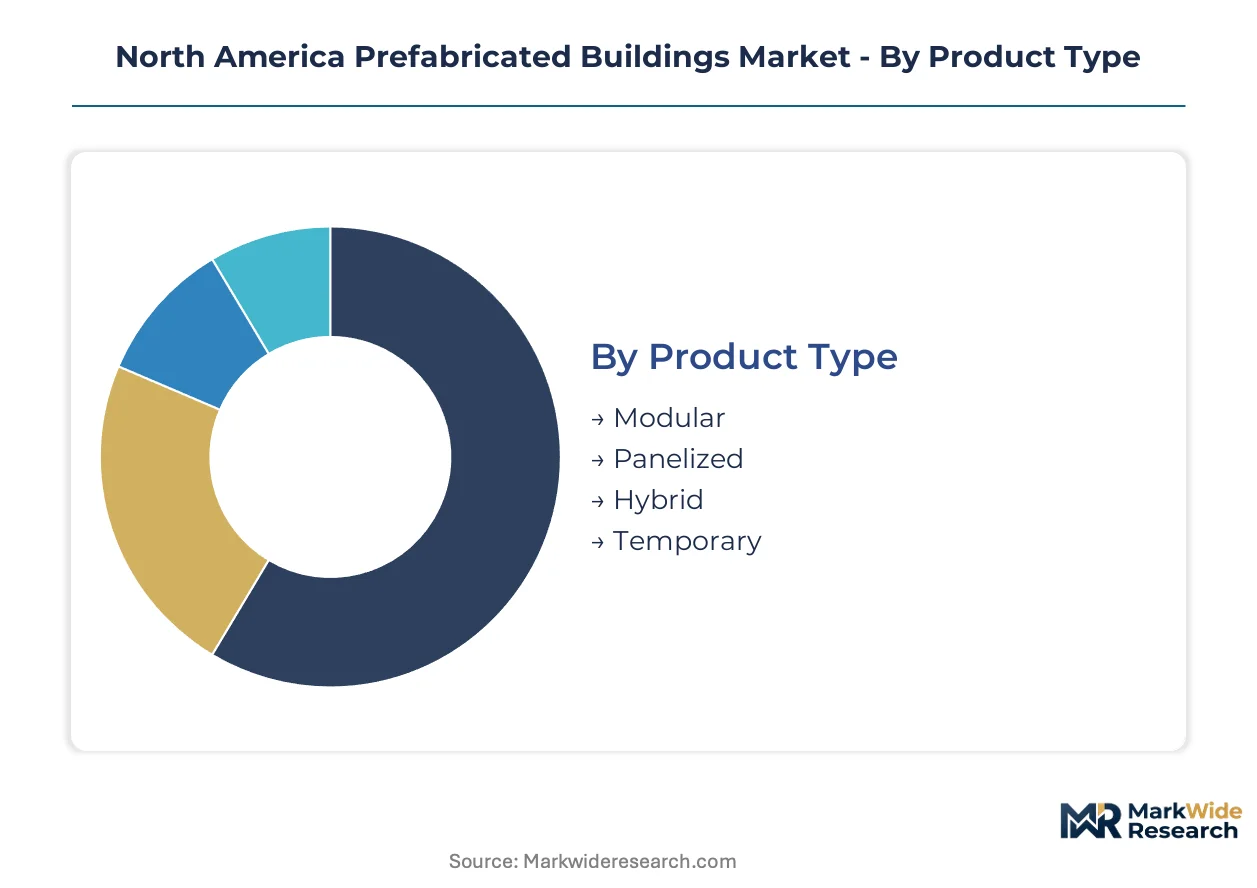
Prefabricated building segments diverge sharply by capital intensity and schedule sensitivity. Product architecture determines whether factory investment or site labor dominates project economics, while material selection locks in regulatory compliance pathways across California seismic zones and Texas wind corridors.
Product Type:
Modular commands premium pricing through factory-completed MEP systems, while panelized delivers volume through familiar framing methods and flexible finish options.
- Modular:Three-dimensional volumetric units arrive with structural, mechanical, electrical, and plumbing systems substantially complete. Hospital systems across Texas and Ontario specify these for rapid-deployment clinics where schedule compression justifies 15-25% cost premiums over conventional construction.
- Panelized:Flat wall and roof panels ship open for interior trades, preserving familiar stick-built sequencing for residential contractors. Single-family builders in the southeastern United States favor this format for its balance of factory quality control and on-site customization flexibility.
- Hybrid:Combines volumetric modules for repetitive spaces with panelized infill for irregular architectural elements.
- Temporary:Relocatable structures designed for sub-10-year service life with minimal foundation requirements.
Today's leader: Panelized. Tomorrow's challenger: Modular.
Application:
Institutional projects concentrate margin pools where factory-controlled infection prevention and seismic certification justify engineering premiums, while residential spreads across cost-sensitive production builders.
- Residential:Single-family production builders and multifamily developers drive volume through standardized floor plans and repetitive unit types. Clayton Homes deploys manufactured housing scale across cost-sensitive segments in the southeastern United States.
- Commercial:Office and retail developers specify prefabricated envelope systems to compress weather-tight schedules in dense urban corridors where on-site laydown space is constrained.
- Industrial:Warehouse and manufacturing facilities favor steel-framed engineered metal buildings across the Great Plains and Midwest manufacturing belts where clear-span requirements dominate.
- Institutional:Healthcare and education projects capture disproportionate engineering attention due to California CALGreen carbon disclosure mandates and Ontario master procurement agreements that filter specification toward certified suppliers.
Residential generates the volume base. Institutional commands the margin premium.
Material:
Steel anchors industrial applications through captive supply advantages, while mass timber gains specification share in Pacific Northwest institutional projects where seismic weight reduction and carbon accounting intersect.
- Wood:Light-frame lumber dominates single-family panelized construction with R-21 to R-40 insulation values depending on climate zone targeting. Cross-laminated timber hybrids are climbing fastest in British Columbia and Washington state institutional buildings.
- Steel:Cold-formed and hot-rolled structural sections anchor industrial warehouses and mid-rise commercial cores. Nucor Building Systems leverages captive steel supply to defend position against spot-price volatility affecting non-integrated fabricators.
- Concrete:Precast wall panels and 3D-printed elements from ICON Technology enable geometric complexity and compress envelope schedules by 30-40% in Texas healthcare pilot projects.
- Composite:Fiber-reinforced polymer and insulated metal panel systems deliver high thermal performance for controlled-environment facilities.
Steel holds industrial dominance. Wood is gaining fastest in carbon-accounted institutional procurement.
Construction Method:
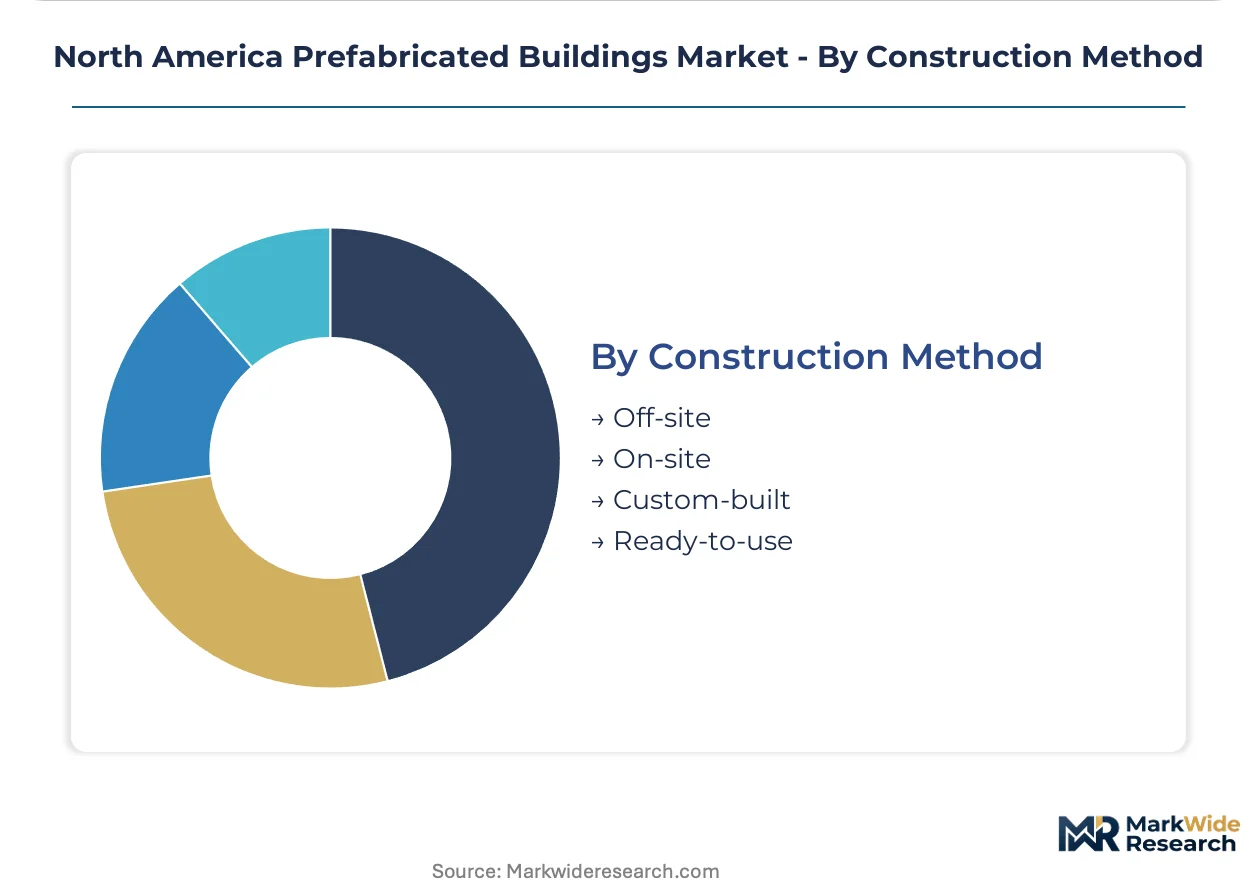
Off-site completion percentage determines labor cost exposure and schedule reliability, with pure off-site methods minimizing on-site craft dependency in labor-scarce Texas and Ontario corridors.
- Off-site:Maximum factory completion minimizes weather exposure and on-site labor requirements. Modular hospital wings and clinic units ship with MEP rough-ins complete, generating the steepest schedule savings in multi-story commercial and institutional projects.
- On-site:Traditional prefabrication with substantial site assembly retains contractor familiarity but sacrifices factory quality control advantages.
- Custom-built:Architect-specific designs requiring dedicated engineering and non-repetitive production sequences.
- Ready-to-use:Standardized product lines with minimal configuration options, optimized for velocity in residential and temporary applications.
Off-site commands the premium tier. Ready-to-use scales the volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory-built housing originated in the United States during the early twentieth century, with Michigan and Indiana emerging as early production centers. The industry later expanded into Canada during the postwar period, establishing cross-border supply chains that persist today.
United States
Hospital systems in Texas and California drive modular adoption for rapid-deployment clinics and emergency wings. OSHA and EPA regulations govern factory safety and formaldehyde emissions from composite wood products. The Texas urban corridor concentrates demand where Houston-Dallas-Austin metro expansion faces acute construction labor shortages.
Canada
Ontario's Golden Horseshoe generates institutional procurement through provincial health infrastructure master agreements. Health Canada and the National Building Code of Canada shape certification requirements for cross-border module shipments. British Columbia's high-seismic zones push specification toward mass timber-panelized systems in Vancouver and Victoria.
California
CALGreen Tier 1 and Tier 2 mandates force embodied carbon disclosure for commercial projects exceeding 100,000 square feet. The California Energy Commission enforces energy efficiency standards that favor high-R-value prefabricated wall assemblies. Los Angeles and San Francisco metro areas filter public-sector RFPs toward suppliers with third-party certified manufacturing.
Texas
Compressed timelines in Houston-Dallas-Austin corridor expansion create pull for multi-story modular commercial cores. State-level amendments to the International Building Code create design recertification costs that fragment addressable markets. Dallas-Fort Worth concentrates industrial warehouse demand where steel-framed engineered metal buildings dominate.
Ontario
Provincial health infrastructure planning has pre-qualified modular suppliers for decade-long master agreements. The Ontario Building Code adoption of modular construction appendices shapes factory-to-site logistics. The Golden Horseshoe from Toronto to Hamilton concentrates demand where labor scarcity intersects with institutional project pipelines.
North America Prefabricated Buildings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the certification and schedule-reliability dimension. The vendor base separates into three tiers: integrated steel producers with captive supply, manufactured housing specialists with national distribution footprints, and digital fabrication entrants with additive manufacturing capabilities. Consolidation pressures concentrate among residential-scale producers while institutional modular segments sustain fragmented competition. Dominant competitive moves include backward integration into material supply and geographic expansion through regional factory placement.
Among United States-based fabricators, Clayton Homes and Nucor Building Systems exemplify scale-driven archetypes, while ICON Technology occupies a position within the digital fabrication tier. Clayton Homes represents manufactured housing volume leadership across cost-sensitive residential segments. Nucor Building Systems anchors the industrial and commercial metal building segment through upstream control over steel supply. ICON Technology exemplifies additive manufacturing convergence in wall-panel production.
| Leading Market Players |
|---|
| BluHomes |
| ICON Technology |
| Clayton Homes |
| Nucor Building Systems |
| Butler Manufacturing |
| Cavco Industries |
| Plant Prefab |
| Varco Pruden Buildings |
| Skyline Champion Corporation |
| Others |
Value Network & Pricing Analysis
Additive manufacturing convergence in wall-panel fabrication is compressing production economics while redistributing supply concentration toward technology-integrated producers. Factory-controlled assembly methods reduce on-site labor exposure and reshape cost structures across Texas and Ontario demand corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified modular suppliers from panelized volume producers and manufactured housing specialists. Price differentiation hinges on CALGreen certification tier and factory completion percentage, with premium tiers commanding 15-25% markups for seismic-compliant institutional modules. Cost compression in standard panelized segments is intensifying because steel input volatility at non-integrated fabricators erodes margin buffers. Residential production builders exhibit highest price sensitivity, while hospital systems in Texas and Ontario demonstrate lowest sensitivity due to schedule-critical procurement mandates.
Supply Chain Analysis
Domestic-content mandates in California and New York public procurement are reshaping sourcing patterns toward North American steel and mass timber suppliers. Geographic supply concentration centers on United States, Canada, and Mexico, with cross-border module shipments governed by divergent IBC and National Building Code of Canada adoption. Raw material dependencies rest on structural steel, cross-laminated timber, and formaldehyde-compliant composite wood finishes. Single-source vulnerability concentrates in captive steel supply at integrated producers. Distribution runs through regional factory networks constrained by 500-mile interstate transport radius limits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Prefabricated Buildings Market operates as a stable compounder, with institutional procurement mandates and labor scarcity creating durable demand visibility across the analysis window.
For Market Incumbents: Lock in multi-year master agreements with hospital systems and provincial health infrastructure planners to defend against digital fabrication entrants. Deepen backward integration into steel supply or mass timber sourcing to neutralize input cost volatility. Prioritize CALGreen Tier 2 certification investment to capture premium-mid-economy pricing differentiation in California public-sector RFPs. For New Entrants and Emerging Players: Enter via additive manufacturing capabilities for wall-panel production, targeting Texas healthcare rapid-deployment clinics where ICON Technology has validated pilot demand. Exploit white-space in British Columbia mass timber-panelized systems for high-seismic institutional applications. Pursue design-build-furnish contracting models to bypass traditional general contractor gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among regional panelized producers lacking institutional certification credentials but possessing factory assets in Golden Horseshoe or Texas urban corridor proximity. Long-term viability favors suppliers with demonstrated seismic engineering capabilities and verified embodied carbon supply chain data. Monitor Ontario provincial health infrastructure pre-qualification announcements as inflection signal for vendor pool consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Nucor Building Systems leverages captive raw material access to defend margin position against spot-price volatility. |
| CALGreen Tier 2 Certification Investment | Third-party verified manufacturing unlocks premium pricing in California commercial projects exceeding 100,000 square feet. |
| Provincial Master Agreement Procurement | Ontario health infrastructure pre-qualification compresses vendor pools and secures decade-long revenue visibility. |
| Additive Manufacturing Deployment | ICON Technology's large-scale 3D printing reduces wall-panel material waste and compresses envelope schedules by 30-40%. |
| Cross-Laminated Timber Hybrid Development | Pacific Northwest institutional projects specify mass timber systems for seismic weight reduction and carbon accounting compliance. |
Research Methodology
Coverage spans United States and Canada, with primary inputs from each jurisdiction's construction regulatory environment. Primary interviews combined insights from modular factory operations directors, hospital capital planning executives, general contractor procurement leads, and structural engineering consultants specializing in seismic zone module connections. Secondary validation drew from ICC International Building Code adoption tracking, EPA formaldehyde emission compliance databases, California Energy Commission efficiency standard filings, and Ontario Building Code modular construction appendix amendments. Bottom-up project pipeline analysis triangulated against top-down regional construction spending forecasts.
Granularity-level modeling addressed product type at the modular-panelized-hybrid-temporary dimension, application across residential-commercial-industrial-institutional segments, material selection among wood-steel-concrete-composite categories, and construction method differentiation by off-site completion percentage. CAGRs were derived from regression analysis of historical shipment data and forward projection of demand drivers across the modeling period. Industry-specific forecast inputs included labor scarcity indices for Texas and Ontario construction markets and provincial health infrastructure capital budget allocations.
Inputs from ICC code adoption databases and EPA certification timelines were available through the study window; gaps in real-time steel spot pricing volatility introduce uncertainty bands around fabricator margin projections. Forecasts reflect assumptions regarding sustained CALGreen tier expansion and stable interstate transport regulatory frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
India Prefabricated Buildings Market
Building Construction
Bangladesh Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
India Construction Market
Building Construction
Africa Construction Market
Building Construction
UK Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Poland Construction Market
Building Construction
China Building Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
North America Construction Market
Building Construction
China Prefabricated Buildings Market