
 Blown Oils Market | 2026-2036
Blown Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Blown Oils Market Outlook
India is fragmenting its historical dominance in castor-derived blown oils as new processing clusters emerge across Gujarat and Rajasthan. Jayant Agro-Organics leverages backward integration into seed crushing to secure feedstock margins. Cargill, Incorporated competes through global oleochemical distribution networks spanning multiple continents. BASF SE anchors its position in specialty blown oil formulations for high-performance coatings.
Blown oils are vegetable, mineral, or synthetic base oils subjected to controlled air oxidation at elevated temperatures, yielding elevated viscosity and enhanced drying characteristics for industrial binders. Vegetable blown oils lead volume consumption due to castor and soybean feedstock availability, though specialty blown oils capture disproportionate margin pools in pharmaceutical-grade applications. The coatings application segment sustains steady demand from architectural and protective formulations, while lubricants represent the fastest-growing application as biodegradable base stocks displace mineral alternatives in environmentally sensitive operations.
REACH in Europe restricts petrochemical-derived additives, redirecting formulators toward bio-based blown oil intermediates. India's BIS standards govern lubricant performance classifications, creating compliance thresholds for domestic and export-bound production. The US EPA regulates volatile organic compound emissions from coatings containing certain blown oil dryers, shaping product development priorities. Stakeholders must monitor feedstock volatility in castor seed markets and assess dual-registration strategies across REACH and BIS jurisdictions to secure uninterrupted market access.
Market Dynamics
REACH compliance in Europe and BIS lubricant standards in India are forcing formulators to abandon petrochemical intermediates for castor-based blown oils, compressing substitution timelines across coatings and lubricant supply chains.
Growth Catalysts
- REACH restriction on petrochemical additives:ECHA mandates are redirecting European coatings formulators toward bio-based blown oil dryers and binders, accelerating feedstock switching in architectural and protective formulations.
- Castor seed processing clusters:Gujarat and Rajasthan processing infrastructure expansion is securing regional supply chains for export-grade vegetable blown oils with traceable sustainability credentials.
- Biodegradable lubricant demand:Mining, marine, and agricultural equipment operators are specifying vegetable blown oil base stocks for environmentally sensitive operations to meet discharge compliance.
Market Restraints
- Castor seed price volatility:Monsoon-dependent Indian harvests and speculative commodity trading create input cost instability that compresses margin predictability for processors and formulators alike.
- Supply concentration in Gujarat:Over 70 percent of global castor seed crushing capacity sits within a 200-kilometer radius, exposing buyers to localized weather, logistics, or labor disruption risks.
- Technical drying speed limitations:Vegetable blown oils cannot match cobalt-catalyzed petrochemical driers in high-throughput industrial coating lines, restricting penetration in automotive OEM clearcoat applications.
Strategic Opportunities
- Underpenetrated US coatings market:EPA VOC regulations have historically favored waterborne systems over oil-based alternatives, creating white space for low-VOC blown oil formulations in specialty wood and metal coatings.
- Pharmaceutical-grade blown oils:Excipient and topical formulation applications command premium pricing with limited qualified suppliers, offering margin expansion for processors achieving USP-NF or Ph.Eur certification.
- EU Green Deal bio-based content mandates:Public procurement rules requiring minimum renewable material shares in construction and infrastructure projects are creating guaranteed demand pools for certified bio-based blown oil suppliers.
Industry Challenges
- Dual-registration compliance timelines:Simultaneous REACH registration and BIS lubricant grade certification requires 18-24 month documentation cycles that delay market entry for new product variants.
- Specialized oxidation process engineering:Controlled air-blown viscosity modification demands precise temperature and residence time control that few processors outside established clusters have mastered at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blown Oils Market |
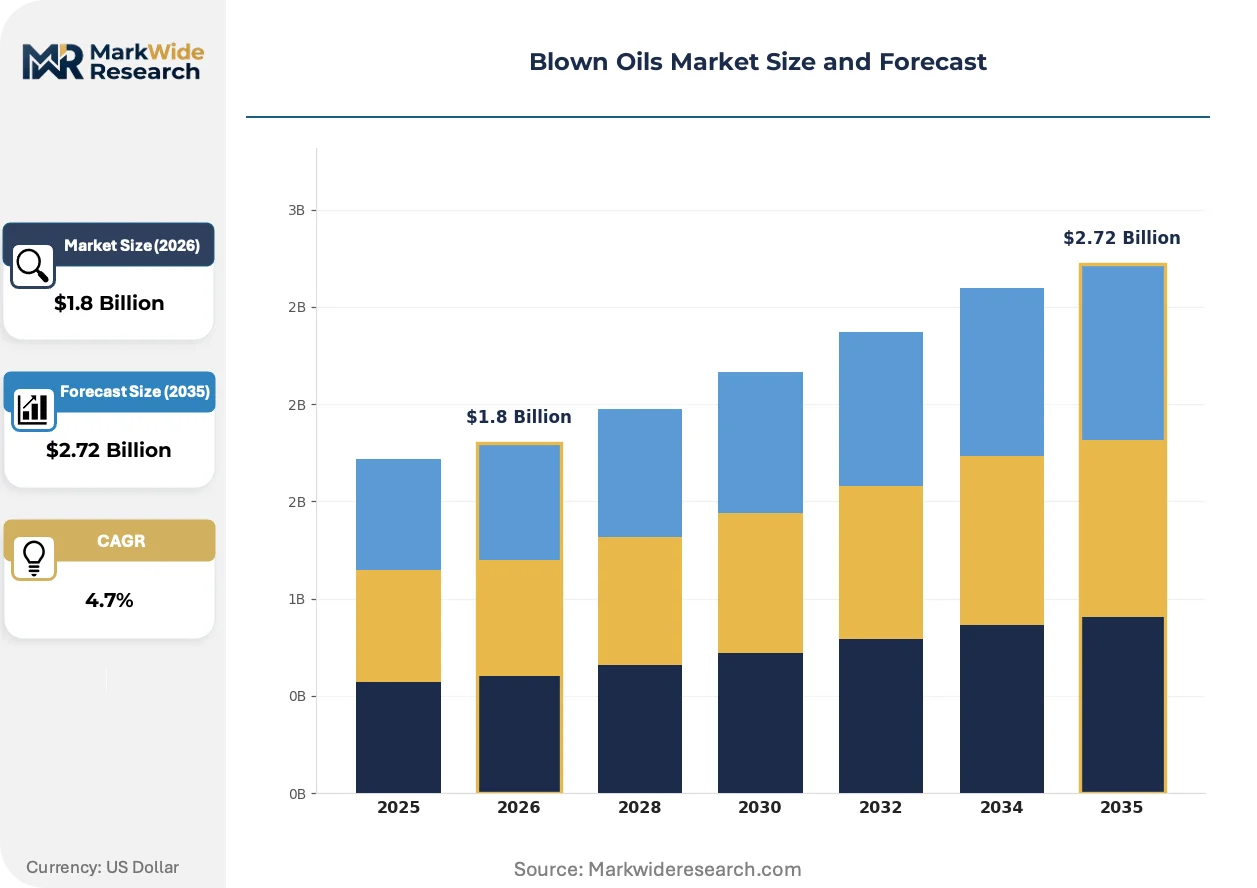
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Blown Oils, Mineral Blown Oils, Synthetic Blown Oils, Specialty Blown Oils Application: Coatings, Adhesives, Plastics, Lubricants End User: Manufacturing, Automotive, Construction, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Jayant Agro-Organics, Kerawalla Group, Adani Wilmar, Cargill, Incorporated, BASF SE, Vertellus, Croda Lubricants, Arvalli Castor Derivatives, Oleon NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blown Oils Market Strategic Shifts
Process control technologies and sustainability verification systems are compressing quality variance and documentation burdens across blown oil supply chains, enabling tighter specification adherence for pharmaceutical and food-contact applications.
Inline viscometry and automated oxidation reactor control is digitizing quality assurance in blown oil manufacturing. Specialty chemical processors in Germany and India are deploying sensor arrays that adjust air injection rates in real time, reducing batch-to-batch viscosity deviation. This capability is digitizing the path to pharmaceutical-grade certification that previously required manual sampling and laboratory verification cycles.
EU CSRD sustainability disclosure rules are mandating Scope 3 emissions tracking across chemical supply chains. Blown oil processors must now document castor seed farm-level carbon intensity and land-use change impacts to maintain formulator relationships. Coatings manufacturers with EU-domiciled parent companies are most affected, pressuring Indian suppliers to implement blockchain-traceable certification systems or risk contract non-renewal.
Long-term offtake agreements are displacing spot market purchasing for vegetable blown oils. Lubricant formulators in Europe and North America are locking in multi-year supply contracts with Gujarat-based processors to secure price stability and compliance documentation. Marine and offshore equipment manufacturers in Norway and the Netherlands are driving this behavioral shift, prioritizing supply security over short-term cost optimization in their procurement specifications.
Blown Oils Market Segmentation
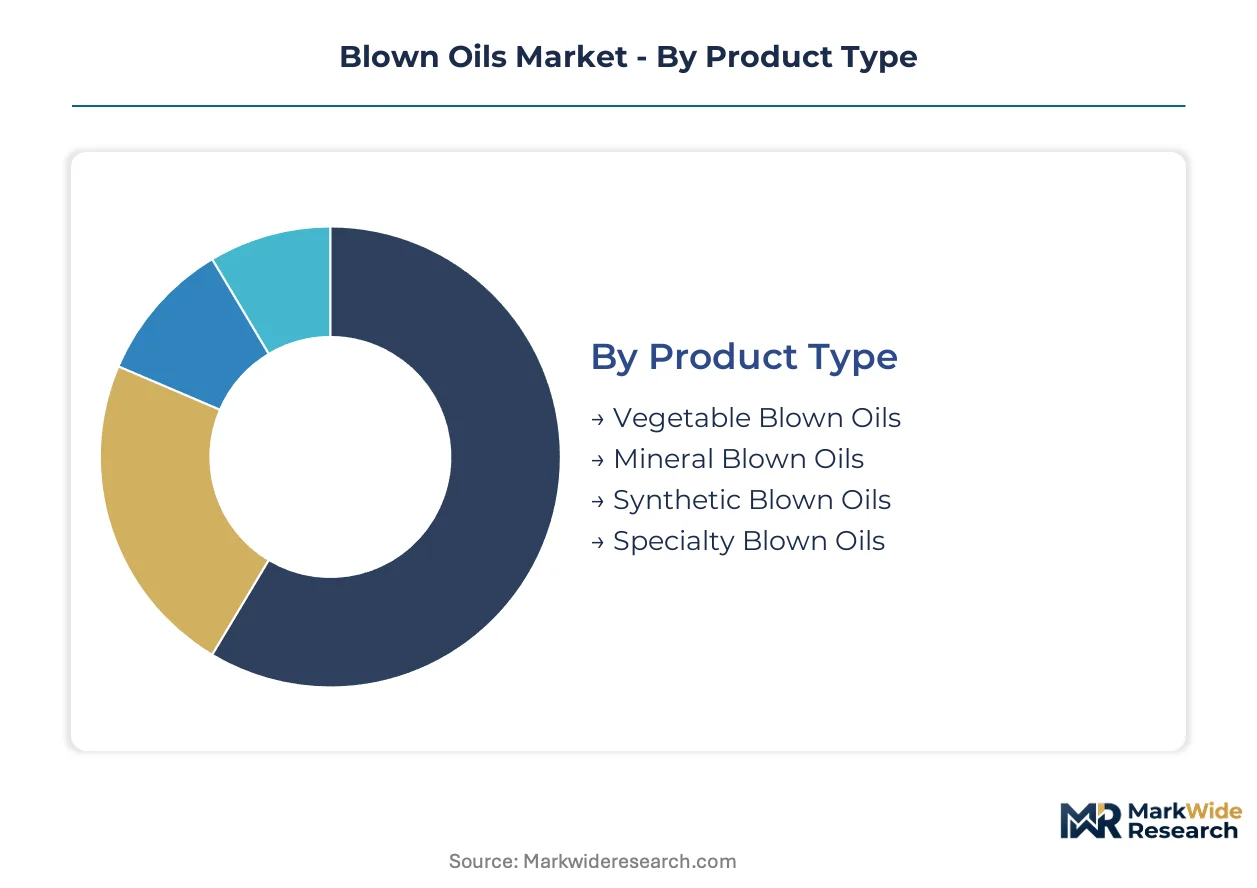
Blown oils serve divergent performance requirements across industrial binders, biodegradable lubricants, and pharmaceutical excipients. Segmentation reveals how feedstock chemistry and end-use compliance specifications create distinct margin architectures and procurement behaviors.
Product Type:
Cost tier differentiation separates commodity vegetable grades from premium synthetic and specialty formulations with certification overhead.
- Vegetable Blown Oils:Castor and soybean feedstocks undergo controlled air oxidation to elevate viscosity and impart drying characteristics. Demand concentrates in India where Gujarat and Rajasthan processing clusters supply export-grade material with traceable sustainability credentials for REACH-compliant European formulators.
- Specialty Blown Oils:Refined oxidation protocols achieve pharmaceutical-grade purity for excipient and topical formulation applications. European coatings manufacturers with CSRD-mandated Scope 3 disclosure requirements are locking in long-term offtake agreements with certified processors to secure compliance documentation.
- Mineral Blown Oils:Petrochemical base stocks modified through air-blowing for industrial binder applications.
- Synthetic Blown Oils:Engineered base fluids with controlled molecular architecture for high-performance lubricant formulations.
Vegetable blown oils command the established base. The steepest expansion runs through specialty grades.
Application:
Application selection determines regulatory exposure, from EPA VOC limits in coatings to BIS lubricant performance classifications.
- Lubricants:Biodegradable vegetable base stocks displace mineral alternatives in mining, marine, and agricultural equipment operating in environmentally sensitive zones. Norwegian and Dutch marine manufacturers are driving procurement shifts toward multi-year supply contracts with Gujarat processors.
- Coatings:Architectural and protective formulations rely on blown oil dryers and binders with constrained petrochemical additive content under ECHA mandates. Indian manufacturers face technical drying speed gaps against cobalt-catalyzed alternatives in automotive OEM clearcoat lines.
- Adhesives:Industrial binding applications requiring elevated viscosity and tack properties.
- Plastics:Processing aids and internal lubricants for polymer compounding operations.
Coatings command the established base. The steepest expansion runs through lubricants.
End User:
End user procurement patterns range from spot market purchasing in construction to specification-driven long-term contracting in automotive.
- Manufacturing:Industrial equipment operators specify biodegradable lubricant formulations to meet discharge compliance in sensitive watersheds. Mining sector procurement in Australia and Canada is formalizing vegetable blown oil base stock requirements in equipment tender specifications.
- Automotive:OEM and aftermarket lubricant formulators demand batch-to-batch viscosity consistency enabled by inline viscometry and automated oxidation reactor control. German specialty chemical processors are deploying sensor arrays that adjust air injection rates in real time.
- Construction:Public infrastructure projects in the EU are incorporating bio-based content mandates under Green Deal procurement rules.
- Agriculture:Farm equipment and processing machinery requiring environmentally compatible lubricant formulations.
Manufacturing commands the established base. The steepest expansion runs through automotive.
Distribution Channel:
Channel selection reflects documentation intensity, with REACH and BIS compliance requirements favoring direct processor relationships over intermediaries.
- Direct Sales:Lubricant formulators and coatings manufacturers establish direct procurement relationships with Gujarat-based processors to secure price stability and traceability documentation. Marine equipment manufacturers in Norway and the Netherlands prioritize supply security over short-term cost optimization.
- Distributors:Regional chemical distributors stock standard-grade vegetable and mineral blown oils for mid-scale manufacturing customers with less stringent certification requirements.
- Online Retail:Digital platforms serve small-batch purchasers and research institutions requiring rapid sample procurement.
- Wholesalers:Volume aggregators supply commodity grades to construction and agricultural end users with price-sensitive procurement profiles.
Direct sales command the established base. The steepest expansion runs through distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Castor seed crushing capacity concentrates in Gujarat's 200-kilometer industrial corridor, yet formulator demand is dispersing across three continents as REACH and EPA regulations redirect procurement flows.
India
Gujarat and Rajasthan processing clusters supply export-grade vegetable blown oils with blockchain-traceable sustainability credentials. BIS lubricant performance classifications govern domestic production and create compliance thresholds for export-bound material. Jamnagar and Kandla port infrastructure anchors regional supply chains serving European coatings formulators.
Germany
Specialty chemical processors deploy inline viscometry and automated oxidation reactor control for pharmaceutical-grade certification. ECHA REACH mandates redirect coatings formulators toward bio-based blown oil dryers and binders. Leverkusen and Ludwigshafen industrial complexes concentrate high-purity formulation capabilities for automotive OEM applications.
United States
Marine and agricultural equipment operators specify biodegradable lubricant base stocks for environmentally sensitive watershed compliance. EPA VOC regulations from coatings applications create white space for low-VOC blown oil formulations in specialty wood and metal coatings. Houston and New Jersey chemical corridors host blending operations for domestic lubricant formulators.
Netherlands
Marine equipment manufacturers in Rotterdam and Amsterdam drive procurement shifts toward multi-year supply contracts with Gujarat processors. EU Green Deal bio-based content mandates in public infrastructure procurement create guaranteed demand pools for certified suppliers. Rotterdam port logistics facilitate bulk import and redistribution across northwestern European coatings hubs.
Norway
Offshore equipment manufacturers prioritize supply security over short-term cost optimization in procurement specifications. Norwegian maritime regulators enforce strict discharge compliance for lubricants used in sensitive fjord and Arctic operations. Stavanger and Bergen industrial zones concentrate equipment specification influence that cascades through European marine supply chains.
Blown Oils Market Competitive Environment
Vertically integrated agro-processors and global oleochemical distributors split the market along feedstock control versus formulation specialization lines. The structure tilts toward consolidation at the upstream seed-crushing tier while fragmenting across specialty oxidation and pharmaceutical-grade certification capabilities. Three archetypes dominate: captive seed-to-oil processors, toll oxidation specialists, and multinational formulation distributors. Capacity expansion in Gujarat processing clusters and strategic partnerships for REACH compliance documentation represent the dominant competitive moves.
Among Indian agro-processing specialists, Jayant Agro-Organics exemplifies the captive feedstock archetype through backward integration into Gujarat seed crushing. Cargill, Incorporated occupies a position within global oleochemical distribution networks spanning multiple continents. BASF SE anchors the specialty formulation tier, representing high-performance coatings applications requiring precision oxidation protocols.
| Leading Market Players |
|---|
| Jayant Agro-Organics |
| Kerawalla Group |
| Adani Wilmar |
| Cargill, Incorporated |
| BASF SE |
| Vertellus |
| Croda Lubricants |
| Arvalli Castor Derivatives |
| Oleon NV |
| Others |
Value Chain & Pricing Dynamics
Gujarat's 200-kilometer castor seed processing corridor concentrates over 70 percent of global crushing capacity, granting regional processors substantial leverage in contract negotiations with European coatings formulators facing REACH compliance deadlines. This geographic chokepoint amplifies pricing power for certified vegetable blown oil suppliers while exposing downstream buyers to monsoon-dependent harvest volatility.
Pricing Analysis
REACH restriction on petrochemical additives dictates the pricing tier structure across the blown oils market, separating pharmaceutical-grade certified suppliers from commodity vegetable processors. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale, with specialty blown oils commanding substantial premiums for USP-NF documentation. Cost compression in standard vegetable grades is intensifying because speculative castor seed trading amplifies input instability. Construction sector wholesalers exhibit highest price sensitivity, while marine equipment manufacturers in Norway and the Netherlands prioritize supply security over unit economics.
Supply Chain Analysis
Castor seed harvests from Gujarat and Rajasthan feed the upstream tier, with soybean alternatives sourced from Argentina and Brazil for price-sensitive formulations. Controlled air oxidation equipment draws from German engineering suppliers, while cobalt catalyst alternatives hinge on domestic Indian chemical production. Single-source vulnerability concentrates in Jamnagar and Kandla port logistics, where localized weather disruption can sever European supply lines. Distribution runs through direct processor relationships for REACH-compliant grades, with regional distributors handling standard lubricant and coatings volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blown oils market functions as a regulatory entrenchment story, where dual-registration compliance timelines create switching costs that protect incumbent positions against new oxidation capacity entrants.
For Market Incumbents: Harden feedstock security through backward integration into Rajasthan seed crushing clusters, securing margin capture against monsoon volatility. Expand pharmaceutical-grade certification capabilities to defend against specialty chemical entrants from Leverkusen and Ludwigshafen. Prioritize blockchain-traceable sustainability documentation to meet EU CSRD Scope 3 disclosure mandates from coatings manufacturer parent companies. For New Entrants and Emerging Players: Pursue toll oxidation partnerships with underutilized Gujarat processors to bypass 18-24 month REACH registration cycles. Target the underpenetrated US specialty wood and metal coatings segment, where EPA VOC regulations have created white space for low-VOC blown oil formulations. Lead with pharmaceutical-grade purity positioning to access excipient and topical formulation premium pools with limited qualified competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty oxidation specialists with demonstrated pharmaceutical certification capabilities over commodity vegetable processors. Long-term viability rests on processors achieving USP-NF or Ph.Eur accreditation before EU Green Deal bio-based procurement mandates accelerate. Watch for marine equipment manufacturer procurement specification shifts toward multi-year offtake agreements as inflection indicator for supply security premium crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Crushing | Captive castor feedstock from Gujarat and Rajasthan insulates margin against commodity volatility. |
| Pharmaceutical-Grade Certification Investment | USP-NF and Ph.Eur accreditation unlocks excipient and topical formulation premium pricing pools. |
| Blockchain-Traceable Sustainability Systems | Farm-level carbon intensity documentation satisfies EU CSRD Scope 3 disclosure requirements from coatings manufacturers. |
| Long-Term Supply Agreement Structuring | Multi-year offtake contracts with Norwegian and Dutch marine equipment manufacturers secure volume visibility. |
| Inline Viscometry Process Deployment | Real-time oxidation reactor control reduces batch-to-batch viscosity deviation for automotive OEM specifications. |
Study Parameters
Initial hypotheses were tested against primary input from lubricant formulators, coatings procurement leads, seed crushing plant managers, and marine equipment specification engineers and refined through secondary validation against customs trade data, BIS lubricant standard filings, ECHA REACH registration databases, and SEC disclosures from listed oleochemical processors. Bottom-up volume modeling from individual processor capacity and top-down demand estimation from end-use industry consumption patterns were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the modeling period, with segmentation dimensions including product grade tier, application end-use, and regional regulatory cluster. CAGRs were derived from iterative convergence of feedstock availability projections and formulator substitution timelines. Key industry-specific inputs incorporated castor seed harvest yield variability and REACH restriction implementation phasing.
Sensitivities concentrate around monsoon failure frequency in Gujarat, speculative commodity trading amplification, and dual-registration timeline extensions. Cross-checking against ECHA registration database growth trajectories and BIS lubricant grade certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Deoiler Chemicals Market