
 High Pressure Roll Compactor Market | 2026-2036
High Pressure Roll Compactor Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Roll Compactor Market Insights
The EU Green Deal is rebalancing capital allocation toward energy-efficient pharmaceutical manufacturing equipment across European compounding facilities. Fitzpatrick leverages its North American installed base to sustain aftermarket service revenues, while Hosokawa anchors premium positioning through precision-engineered roll surfaces for micronized APIs. GERTEIS differentiates via specialized roll geometries designed for heat-sensitive actives, occupying a defensible niche in high-value oral dosage production.
A high pressure roll compactor is a mechanical densification unit that applies compressive forces between two counter-rotating rolls to convert fine powders into ribbons or briquettes, typically operating at roll pressures exceeding 50 MPa with gap widths adjustable to 1-3 mm. The resulting compacted material undergoes milling and sizing to produce free-flowing granules for tablet compression or capsule filling. Continuous roll compactors now lead capital expenditure flows among large-scale contract manufacturers seeking uninterrupted processing, while dry granulation technology commands the widest installed base due to its elimination of liquid binders and subsequent drying stages. Pneumatic roll systems represent the fastest-growing product configuration in emerging Asian manufacturing hubs where lower initial capital outlays align with facility expansion budgets.
EMA's Good Manufacturing Practice Annex 15 and FDA's Process Validation Guidance jointly shape equipment qualification protocols and documentation requirements for roll compaction installations in regulated pharmaceutical markets. REACH chemical safety standards in Europe and OSHA's combustible dust regulations in the United States further constrain material handling system designs and inerting requirements. Stakeholders must monitor evolving USP general chapters on particle engineering and emerging pharmacopoeial guidance on continuous manufacturing verification to anticipate next-generation equipment specification shifts.
Market Dynamics
Continuous roll compaction systems are displacing batch granulation across contract pharmaceutical manufacturing, driven by EMA process validation requirements and CDSCO quality mandates that favor real-time release testing over offline quality control.
Growth Catalysts
- EMA Annex 15 compliance pressure:European pharmaceutical manufacturers must demonstrate process understanding and control, accelerating investment in instrumented roll compactors with PAT integration.
- India CDSCO quality convergence:Domestic API producers upgrading facilities for export markets are adopting dry granulation to eliminate liquid binder variability and reduce cross-contamination risks.
- Heat-sensitive API processing:Biologics and complex small molecules requiring thermal protection drive demand for specialized roll geometries with active cooling channels.
Market Restraints
- Precision roll surface manufacturing concentration:Premium tungsten carbide roll finishing capacity concentrates in German and Swiss machine shops, creating 16-24 week lead times for critical spares.
- REACH chemical safety documentation burden:European equipment suppliers face escalating compliance costs for material certifications on contact surfaces, compressing margins on mid-range systems.
- Wet granulation substitution in high-dose formulations:Certain immediate-release tablet applications where liquid binders enable superior dissolution profiles retain incumbent process preference.
Strategic Opportunities
- Brazil ANVISA prequalification pathway:Generic pharmaceutical exporters targeting Latin American markets require roll compaction capacity meeting bioequivalence demonstration standards.
- Continuous direct compression hybrid systems:Convergence of roller compaction with continuous blending and tableting creates integrated process trains for high-volume solid dosage.
- US FDA quality metrics initiative:Voluntary program incentivizing real-time process monitoring rewards manufacturers with reduced inspection frequency and expedited review pathways.
Industry Challenges
- Continuous manufacturing process engineer scarcity:Pharmaceutical facilities struggle to recruit personnel with combined expertise in roll compaction physics, PAT implementation, and regulatory submission writing.
- Legacy batch equipment integration complexity:Brownfield sites face mechanical and control system incompatibilities when retrofitting continuous roll compactors into existing material handling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Roll Compactor Market |
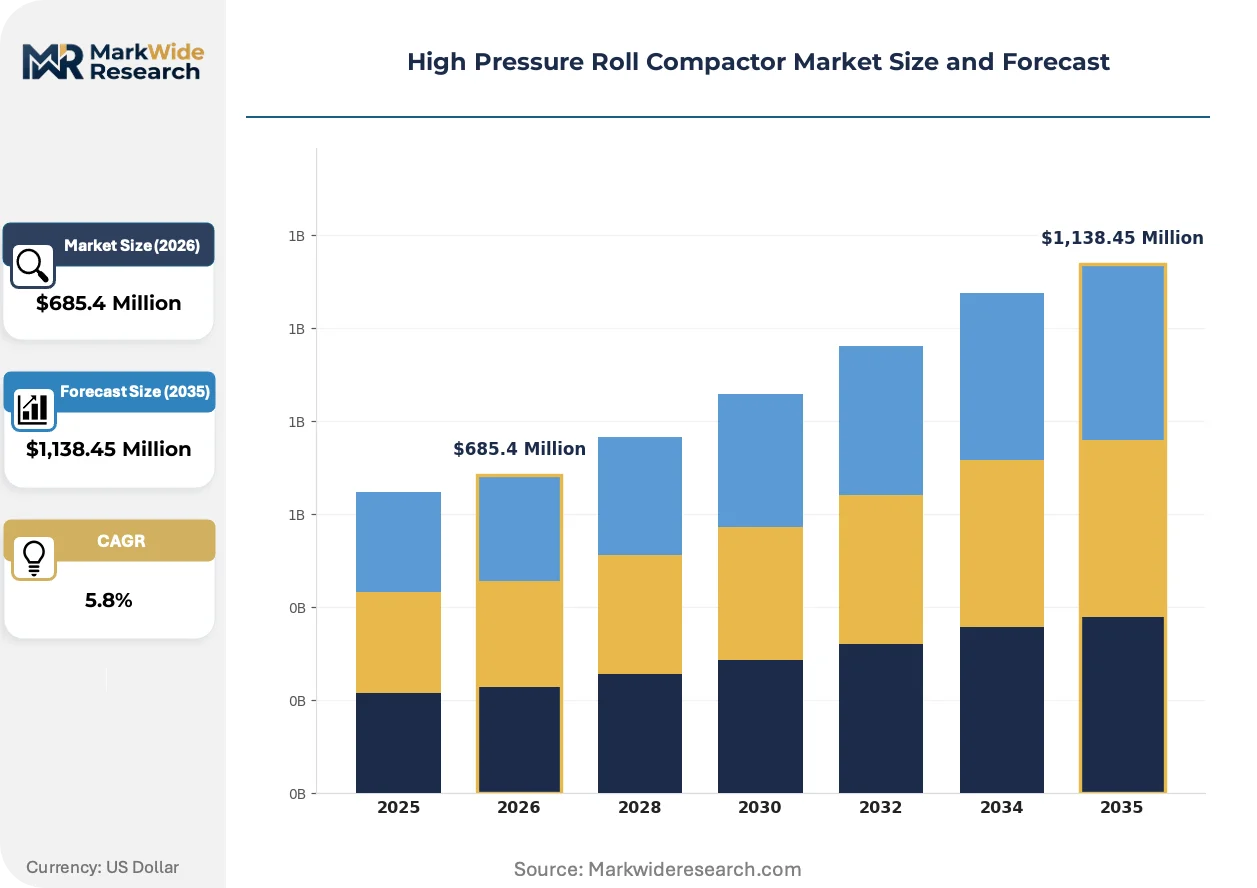
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Roll Compactors, Continuous Roll Compactors, Pneumatic Roll Compactors, Hydraulic Roll Compactors Technology: Dry Granulation, Wet Granulation, Twin Roll Compaction, Slip Roll Compaction Application: Pharmaceuticals, Nutraceuticals, Animal Nutrition, Chemical Processing, Agrochemicals End User: Contract Manufacturers, Bulk Drug Producers, Specialty Chemical Plants, Feed Manufacturers, Research Institutions |
| Companies Covered | Fitzpatrick, Hosokawa, GERTEIS, Alexanderwerk, L.B. Bohle, Freund Corporation, Yenchen Machinery, Beijing LongliTech, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Roll Compactor Market Trends and Innovations
Roll compaction technology is absorbing digitalization pressures from upstream pharmaceutical quality systems, with equipment suppliers embedding sensors and analytics to satisfy process analytical technology mandates.
Real-time gap control using hydraulic roll positioning with laser displacement feedback is absorbing variability from powder feed fluctuations. Large-scale contract manufacturers in Germany and India are retrofitting existing lines with these systems to reduce ribbon density coefficient of variation below 5%. The technology is absorbing quality risk previously managed through extensive offline testing, compressing batch release timelines.
REACH chemical safety standards are forcing redesign of material contact surfaces and seal materials across European-sourced equipment. Suppliers must now document full substance composition down to 0.1% weight thresholds for SVHC screening. Pharmaceutical manufacturers in France and Italy are responding by specifying fluoropolymer-free alternatives and demanding extended supplier declaration chains.
Aftermarket service unbundling is fragmenting traditional equipment supply relationships. End-users in oral solid dosage manufacturing are separating hardware procurement from qualification support and ongoing metrology services. This pattern is most visible among mid-sized generic producers in Spain and Portugal seeking to optimize total cost of ownership through competitive tendering of maintenance contracts.
High Pressure Roll Compactor Market Segmentation
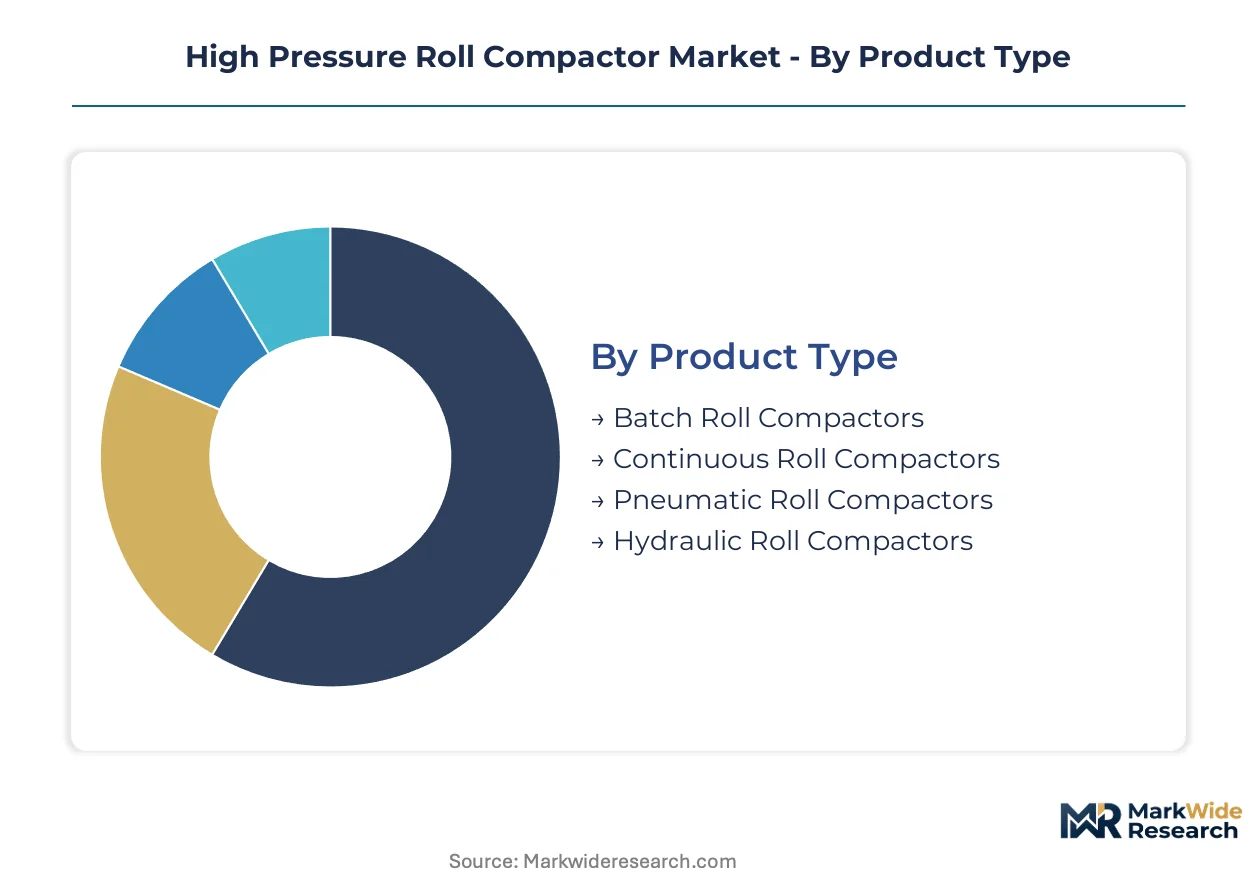
Segmentation in high pressure roll compactors reveals how equipment specifications align with distinct processing demands across pharmaceutical and chemical verticals. Technology choices determine capital intensity, operating efficiency, and regulatory compliance pathways.
Product Type:
Equipment architecture distinguishes between intermittent and uninterrupted material flow, with power transmission systems defining maintenance profiles and energy consumption patterns.
- Batch Roll Compactors:These units process discrete powder charges through timed compression cycles, suited for multi-product facilities requiring frequent changeovers. German and Indian pharmaceutical manufacturers retain substantial installed bases for EMA and CDSCO qualification flexibility.
- Continuous Roll Compactors:Uninterrupted powder feed through counter-rotating rolls enables real-time release testing and reduced in-process inventory. Contract manufacturers in Western Europe favor these systems for PAT integration and energy efficiency gains under EU Green Deal incentives.
- Pneumatic Roll Compactors:Compressed air actuation delivers lower initial capital outlays suited to emerging Asian manufacturing expansions.
- Hydraulic Roll Compactors:Precision force control serves micronized API applications demanding tight ribbon density tolerances.
Continuous Roll Compactors lead on scale; Pneumatic Roll Compactors lead on momentum.
Technology:
Granulation methodology determines solvent use, thermal exposure, and downstream processing complexity for active ingredient handling.
- Dry Granulation:Direct powder compression between rolls eliminates liquid binders and subsequent drying stages, reducing cross-contamination risks. Indian API exporters adopt this technology to meet CDSCO quality convergence for regulated markets.
- Wet Granulation:Liquid binder incorporation enables superior dissolution profiles for immediate-release high-dose tablets, retaining preference in specific therapeutic categories despite longer processing times.
- Twin Roll Compaction:Synchronized roll pairs achieve uniform density distribution across ribbon width for heat-sensitive biologics.
- Slip Roll Compaction:Differential roll speeds enhance shear mixing for cohesive powder blends in specialty chemical applications.
Dry Granulation commands the widest installed base; Twin Roll Compaction shows the steepest expansion trajectory in biologics processing.
Application:
End-use sectors impose distinct particle size, density, and purity specifications that shape roll surface engineering and containment requirements.
- Pharmaceuticals:Oral solid dosage manufacturing demands validated equipment with full batch traceability and PAT-compatible instrumentation. Western European facilities drive replacement cycles for EU Green Deal energy efficiency compliance.
- Nutraceuticals:Dietary supplement producers prioritize rapid changeover capabilities for diverse botanical and mineral formulations.
- Animal Nutrition:Feed manufacturers process high-volume mineral premixes with less stringent containment requirements.
- Chemical Processing:Specialty chemical plants handle abrasive inorganic compounds requiring hardened roll surfaces.
- Agrochemicals:Pesticide granulation operates under REACH chemical safety constraints for operator exposure control.
Pharmaceuticals dominates revenue concentration; Nutraceuticals gains share fastest as wellness product manufacturing scales.
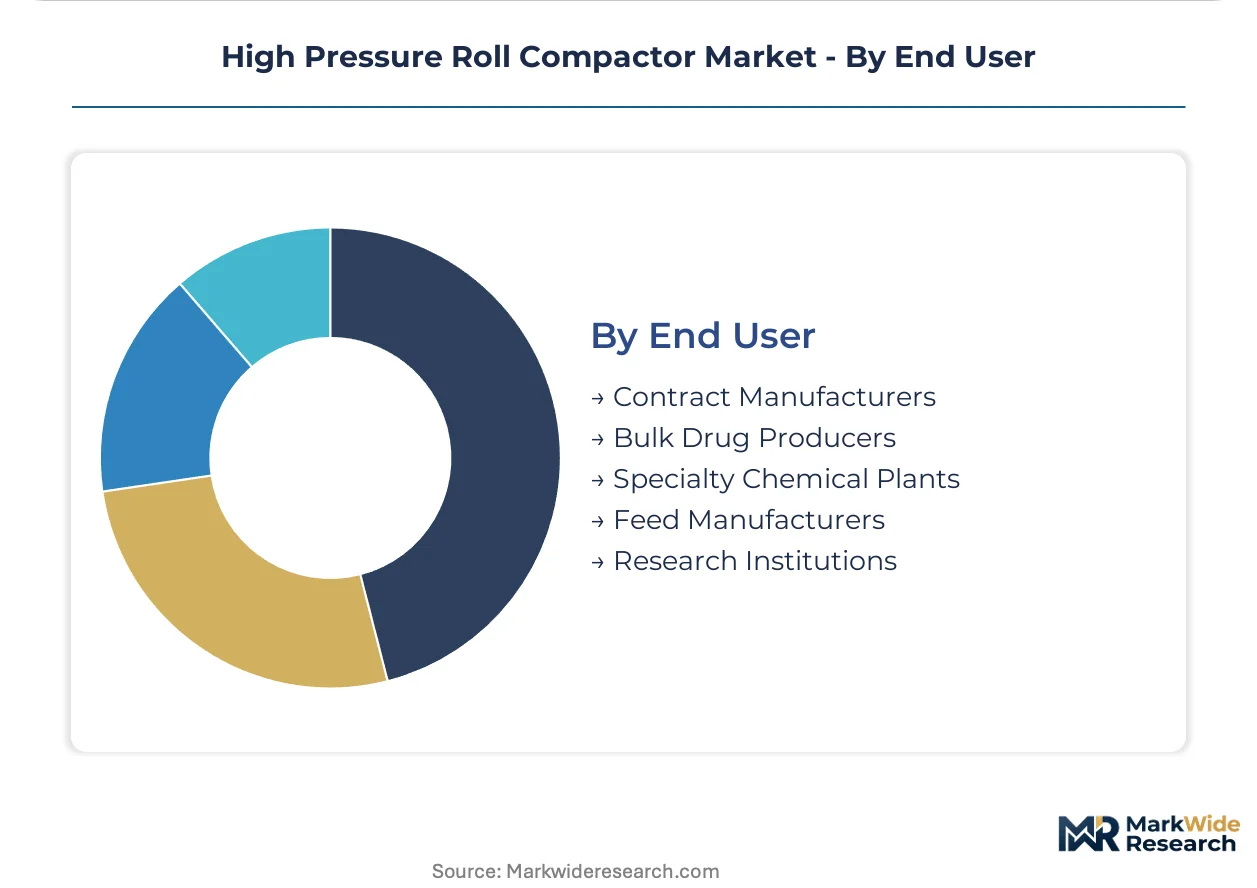
End User:
Procurement patterns diverge between outsourced service providers and captive manufacturing operations based on utilization rates and technical staffing depth.
- Contract Manufacturers:Multi-client facilities demand flexible equipment configurations with rapid validation protocols. CDSCO-mandated quality upgrades in India drive capacity expansion among these operators.
- Bulk Drug Producers:Captive API manufacturing integrates roll compaction into continuous process trains for cost optimization at scale.
- Specialty Chemical Plants:Low-volume high-margin operations specify precision-engineered rolls for micronized product consistency.
- Feed Manufacturers:Commodity producers prioritize throughput and durability over instrumentation sophistication.
- Research Institutions:Pilot-scale equipment supports formulation development with modular scale-up pathways.
Contract Manufacturers absorb the highest equipment volumes; Bulk Drug Producers show the strongest technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision roll compaction engineering during the post-war pharmaceutical equipment boom. Swiss finishing shops later perfected tungsten carbide roll surfaces for micronized API applications. Today equipment demand clusters in manufacturing hubs responding to EMA, FDA, and CDSCO quality mandates.
Germany
Baden-Württemberg and Bavaria host the densest concentration of precision roll surface finishing capacity. EMA Annex 15 compliance requirements drive replacement cycles for instrumented systems with PAT integration. Stuttgart-area machine shops supply critical tungsten carbide components with 16-24 week lead times.
India
Maharashtra and Gujarat absorb the fastest capacity expansion as CDSCO quality convergence pressures domestic API exporters. Dry granulation technology eliminates liquid binder variability for facilities targeting regulated export markets. Hyderabad and Ahmedabad clusters retrofit batch lines with continuous systems to reduce cross-contamination risks.
United States
New Jersey and Massachusetts pharmaceutical corridors sustain replacement demand for validated equipment with full batch traceability. FDA Process Validation Guidance shapes equipment qualification protocols and documentation requirements. Boston-area contract manufacturers favor integrated process trains for real-time release testing.
Switzerland
Basel and Zurich regions anchor premium positioning for heat-sensitive API processing equipment. Swissmedic oversight reinforces stringent equipment qualification standards for biologics manufacturing. Precision engineering clusters supply specialized roll geometries with active cooling channels.
China
Jiangsu and Zhejiang provinces scale pneumatic roll system production for emerging Asian manufacturing expansions. Lower initial capital outlays align with facility expansion budgets across domestic generic producers. Shanghai-area equipment fabricators serve Southeast Asian export markets.
High Pressure Roll Compactor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across roll surface engineering precision and aftermarket service depth. The vendor base stratifies between European precision specialists, Asian scale producers, and diversified process equipment conglomerates. Three archetypes dominate: tungsten carbide finishing specialists, pneumatic system fabricators, and integrated pharmaceutical equipment suppliers. Competitive moves concentrate on strategic partnerships for PAT integration and geographic expansion into CDSCO-regulated markets.
Among European precision specialists, Fitzpatrick leverages its North American installed base while GERTEIS occupies the heat-sensitive API niche through specialized roll geometries. Hosokawa anchors premium positioning through precision-engineered roll surfaces. These three exemplify how equipment differentiation concentrates in finishing precision and application-specific engineering rather than scale economies alone.
| Leading Market Players |
|---|
| Fitzpatrick |
| Hosokawa |
| GERTEIS |
| Alexanderwerk |
| L.B. Bohle |
| Freund Corporation |
| Yenchen Machinery |
| Beijing LongliTech |
| GEA Group |
| Others |
Pricing and Supply Chain Analysis
Roll surface engineering precision separates premium tungsten carbide systems from pneumatic alternatives, with this bifurcation creating divergent pricing power and supplier qualification pathways across German precision shops and Asian fabricators. EMA Annex 15 validation requirements and CDSCO quality convergence jointly reshape procurement economics, as certified equipment commands service premiums while commodity configurations compete on capital outlay.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects roll surface finishing precision and PAT instrumentation depth. Premium tiers leverage Swiss and German tungsten carbide expertise with active cooling channels; standard configurations target mid-sized generic producers in Spain and Portugal; economy pneumatic systems serve emerging Asian expansions. Cost compression in mid-range segments intensifies as REACH documentation burdens escalate. Contract manufacturers exhibit highest price sensitivity due to competitive tendering of maintenance contracts, while biologics processors accept premium positioning for heat-sensitive API handling.
Supply Chain Analysis
EMA and FDA equipment qualification requirements gate supplier participation, restricting premium roll finishing capacity to German and Swiss machine shops with documented substance composition chains. Critical inputs encompass tungsten carbide blanks, precision grinding equipment, and fluoropolymer-free seal materials. Single-source vulnerability concentrates in Stuttgart-area tungsten carbide component suppliers. Distribution runs through direct OEM relationships for validated pharmaceutical systems and regional distributors for pneumatic configurations in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service unbundling and continuous processing retrofits, as energy efficiency mandates and PAT integration requirements drive upgrade cycles across Western European and Indian manufacturing clusters.
For Market Incumbents: Anchor premium positioning through captive tungsten carbide finishing capacity in Baden-Württemberg, defending against Asian pneumatic system encroachment via qualification support bundling. Backward integration into precision roll surface manufacturing mitigates 16-24 week spare part lead times that threaten service level agreements with CDSCO-regulated facilities. For New Entrants and Emerging Players: Capture white-space in continuous direct compression hybrid systems, targeting mid-sized generic producers in Brazil seeking ANVISA prequalification pathways. Pneumatic roll configurations for Southeast Asian contract manufacturers offer lowest barrier to entry, with go-to-market positioning emphasizing lower initial capital outlays and rapid installation timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where aftermarket service fragmentation creates roll-up opportunities among European qualification specialists and metrology providers. Long-term viability favors equipment suppliers with integrated PAT capabilities and established EMA validation documentation libraries. Watch for CDSCO enforcement intensity shifts as inflection indicators for Indian capacity expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PAT Integration Partnership | Embedding real-time gap control with laser displacement feedback satisfies EMA process validation requirements. |
| Backward Integration into Roll Finishing | Captive tungsten carbide capacity in Stuttgart-area machine shops secures critical spare part supply chains. |
| Continuous Processing Retrofit Program | Batch-to-continuous conversions capture EU Green Deal energy efficiency incentives across German facilities. |
| CDSCO Qualification Service Expansion | Documentation support for Indian API exporters accelerates regulated market access timelines. |
| Fluoropolymer-Free Material Transition | REACH-compliant seal redesigns preserve European market access amid escalating SVHC screening thresholds. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical plant engineers, contract manufacturing procurement leads, regulatory affairs specialists at EMA-notified bodies, and aftermarket service heads at European equipment OEMs with secondary validation from FDA Process Validation Guidance documents, EMA Annex 15 compliance bulletins, CDSCO facility inspection reports, and REACH SVHC candidate list updates. Bottom-up equipment shipment tracking and top-down pharmaceutical capital expenditure analysis provided triangulation across market sizing dimensions.
Comparable-period anchoring tied projection models to historical replacement cycles and regulatory implementation timelines across the analysis window. Segmentation dimensions encompassed product architecture, granulation technology, application vertical, and end-user procurement pattern. CAGRs derived from equipment unit economics, operating cost trajectories, and regulatory compliance cost escalations. Forecast inputs included EMA inspection frequency data and CDSCO quality convergence enforcement patterns.
Underlying measurement precision varies by segment; continuous roll compactor forecasts carry tighter precision than pneumatic system projections due to more concentrated supplier bases. Forecasts reflect assumptions regarding regulatory enforcement continuity and raw material availability. A model refresh is warranted upon material change in EMA Annex 15 revision schedules or tungsten carbide supply chain disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market